
 Commercial Satellite Launch Service Market | 2026-2036
Commercial Satellite Launch Service Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Satellite Launch Service Market Intelligence
Heavy-lift payload certification is reorganizing competitive tiers in commercial launch services. SpaceX sustains cost leadership through rapid booster reuse and high flight frequency. United Launch Alliance anchors national security missions with proven reliability and vertical integration into solid rocket motor production. Arianespace competes via Ariane 6 modernization and European institutional backing for autonomous access to space.
Commercial satellite launch service denotes the contracted transportation of payloads from Earth surface to designated orbital trajectories, requiring precise delta-v budgets, payload fairing volumetric constraints, and stage separation sequences tailored to mission profiles. Reusable launch vehicles now capture the fastest-expanding contract volume as operators amortize hardware across multiple missions. Small-lift vehicles serve dedicated rideshare demand from space startups and technology demonstration payloads. Fixed-price contracts dominate commercial procurement while cost-plus structures persist for government agency missions with evolving technical requirements.
FAA licensing governs US commercial launch operations including safety approvals and environmental reviews under National Environmental Policy Act protocols. ESA member state frameworks plus EU Space Programme governance shape European procurement and technology development priorities. China's MIIT and national space administration coordinate civil-military launch scheduling and export control compliance. Stakeholders must track evolving orbital debris mitigation rules from FCC and ITU spectrum coordination mandates as constellation density escalates.
Market Dynamics
Reusable first-stage recovery is compressing launch economics and forcing legacy expendable architectures into rapid obsolescence. This single capability shift now determines contract viability across all payload classes.
Growth Catalysts
- LEO broadband mandates:ITU spectrum coordination deadlines and national digital inclusion policies in India and Brazil are accelerating constellation deployment schedules. Operators must secure orbital slots before expiration.
- FAA streamlined licensing:The Part 450 regulatory framework collapsed approval timelines from years to months for US commercial operators. Launch cadence constraints now sit with range capacity, not paperwork.
- Propellant depots:Cryogenic storage and transfer technologies enable distributed refueling architectures. This extends vehicle reach to cislunar trajectories without heavy-lift mass penalties.
Market Restraints
- Engine production bottlenecks:Turbopump and combustion chamber fabrication concentrates among three specialized US and European suppliers. Lead times now stretch 18-24 months.
- Range capacity saturation:Eastern and Western US launch ranges face scheduling conflicts between national security, civil, and commercial missions. Pad availability caps annual flight volume.
- Payload insurance escalation:Underwriters apply constellation-specific risk multipliers after multiple on-orbit failures. Premium loads now consume 8-15% of mission budgets for unproven operators.
Strategic Opportunities
- Polar corridor expansion:Alaska's Pacific Spaceport Complex and Norway's Andøya Spaceport offer uncongested high-inclination access. These sites capture dedicated rideshare demand from Earth observation constellations.
- In-orbit servicing:Satellite life extension through robotic refueling and component replacement creates recurring launch demand. This application shifts revenue from single-transport to logistics contracts.
- Green propellant mandates:ESA's Clean Space initiative and emerging EPA restrictions on hydrazine handling are accelerating MON-25 and ionic liquid adoption. Early certifiers capture institutional procurement preference.
Industry Challenges
- Propulsion engineering scarcity:Liquid rocket engine design expertise concentrates among aging specialists. Universities produce software and aerospace generalists, not combustion physicists.
- Stage integration complexity:Reusable boosters demand rapid turnaround inspection protocols. Thermal protection system refurbishment and engine requalification consume disproportionate labor hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Satellite Launch Service Market |
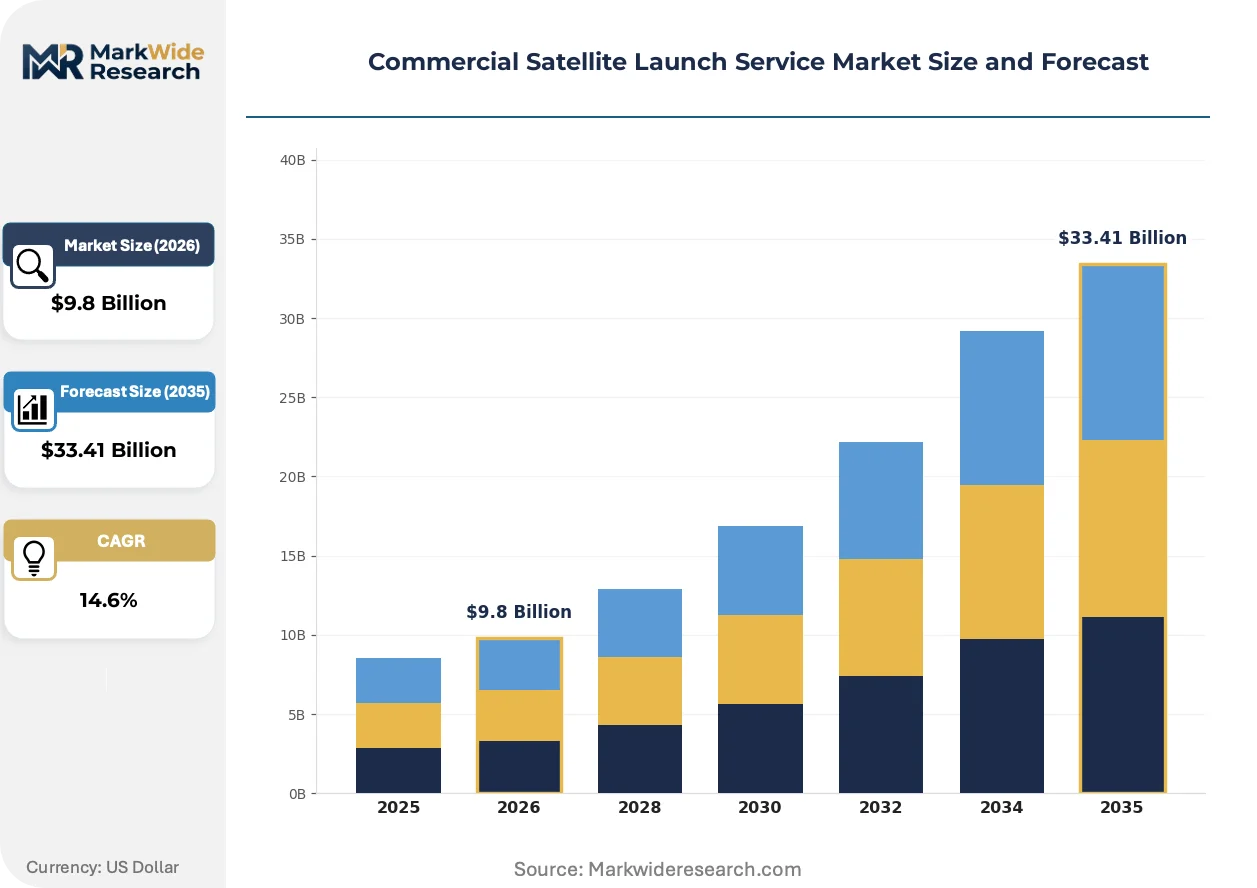
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Launch Vehicle Type: Expendable, Reusable, Small-Lift, Medium-Lift, Heavy-Lift Payload Type: Communication Satellites, Earth Observation Satellites, Navigation Satellites, Scientific Satellites, Technology Demonstration Satellites Customer Type: Satellite Manufacturers, Government Agencies, Telecommunication Providers, Research Organizations, Space Startups Contract Type: Fixed-Price, Cost-Plus, Time & Materials, Incentive-Based, Slot Leasing |
| Companies Covered | United Launch Alliance, Northrop Grumman, SpaceX, Relativity Space, China Aerospace Science and Technology Corporation, Blue Origin, Rocket Lab, Firefly Aerospace, Arianespace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Satellite Launch Service Market Strategic Shifts & Innovations
Propulsion architecture and manufacturing methodology are undergoing simultaneous transformation. These shifts reconfigure cost structures and competitive entry barriers across all vehicle classes.
Methane-oxygen staged combustion is supplanting kerosene-oxygen gas generator cycles in medium and heavy lift vehicles. Full-flow and oxygen-rich staged combustion designs achieve higher specific impulse with cleaner combustion residues. This enables rapid reuse without extensive engine teardown between flights, compressing turnaround intervals from months to days.
The FCC's updated orbital debris mitigation rules now mandate collision probability assessments and post-mission disposal reliability demonstrations for all licensed US launches. Operators must prove 90% successful disposal probability or obtain active debris removal bonds. Small satellite constellations face the steepest compliance burden due to sheer object count.
Fixed-price milestone contracts are displacing cost-plus arrangements for even complex government missions. NASA's Commercial Resupply and Crew programs established this precedent. Defense agencies now emulate the model, transferring design risk to contractors while retaining mission assurance oversight through independent verification requirements.
Commercial Satellite Launch Service Market Segmentation
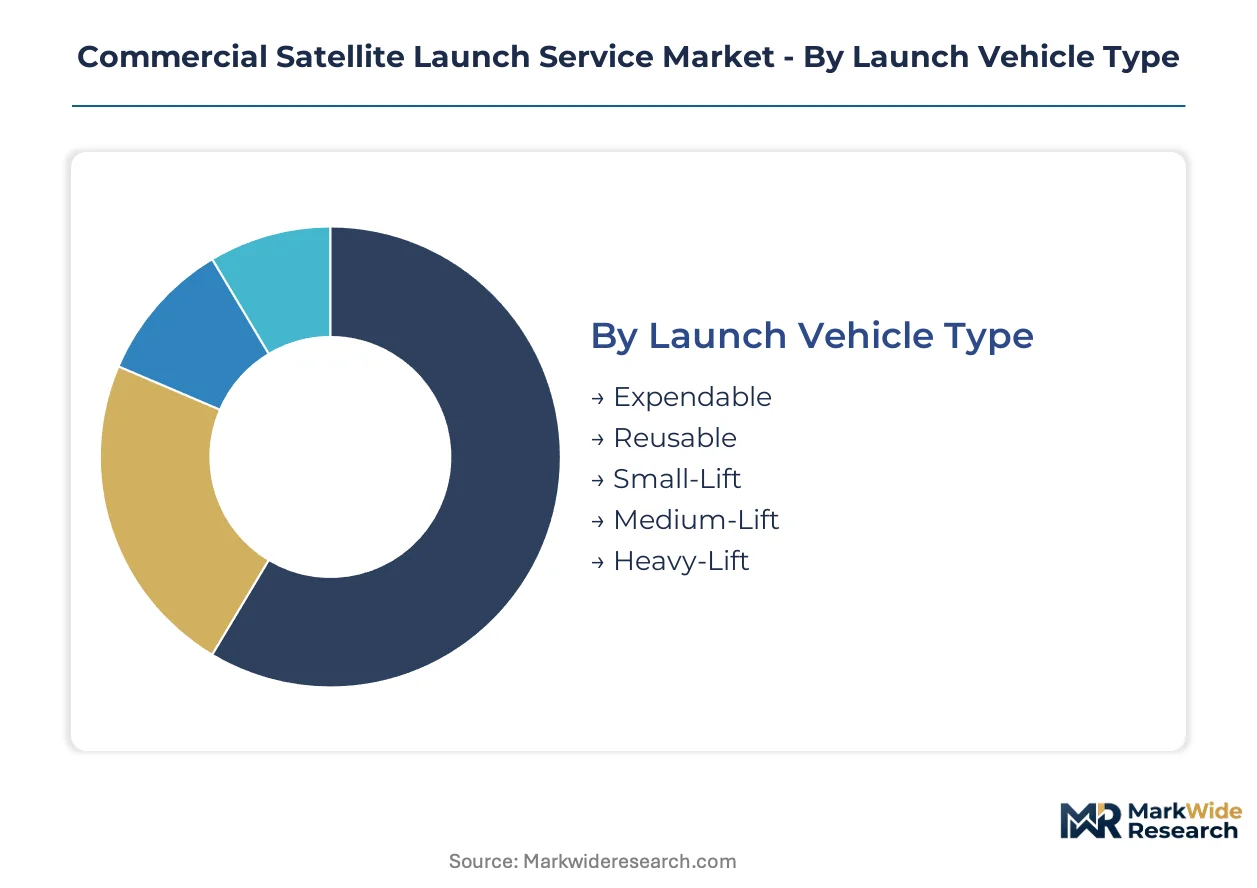
Commercial launch service segmentation reveals how payload mass, orbital destination, and risk allocation shape procurement behavior. Vehicle class determines pricing architecture while contract structure governs liability distribution between launch providers and satellite operators.
Launch Vehicle Type:
Expendable architectures flow through defense and institutional channels requiring mission-assurance redundancy, while reusable systems dominate commercial procurement through amortized hardware economics.
- Expendable:Single-use boosters with heritage flight-proven reliability. Demand concentrates in United States national security missions where mission assurance overrides cost optimization, constrained by solid rocket motor supply bottlenecks.
- Reusable:First-stage recovery enables rapid turnaround and compressed per-kilogram pricing. Commercial constellation operators in the United States and Europe prioritize this segment for high-cadence deployment schedules, though thermal protection refurbishment adds operational complexity.
- Small-Lift:Dedicated rideshare for sub-500kg payloads. Space startups in California and Bavaria drive volume through technology demonstration missions.
- Medium-Lift:Workhorse class for mid-sized communications and observation satellites. European institutional backing sustains Arianespace competitiveness.
- Heavy-Lift:Maximum payload capacity for geostationary transfer and interplanetary trajectories. China's Long March family and United States super-heavy vehicles anchor this tier.
By volume, Small-Lift leads through rideshare aggregation. By growth pace, Reusable vehicles are expanding most quickly.
Payload Type:
Payload mass and orbital requirements segment demand across dedicated versus shared launch services, with broadband constellations reshaping volume concentration.
- Communication Satellites:Geostationary broadband relays and LEO constellation nodes. ITU spectrum deadlines in India and Brazil compress deployment timelines, pulling launch cadence upward.
- Earth Observation Satellites:Optical and synthetic aperture radar platforms. Polar corridor demand from Norway's Andøya and Alaska's Pacific Spaceport Complex drives dedicated small-lift procurement.
- Navigation Satellites:Precision timing and positioning infrastructure. Government agencies in China and the United States control procurement through captive launch allocation.
- Scientific Satellites:Space telescopes and heliophysics missions. NASA and ESA institutional budgets sustain intermittent but high-value demand.
- Technology Demonstration Satellites:Prototype buses and component validation. University-led missions in Germany and Japan favor rideshare economics.
Communication Satellites generate the highest contract value. Technology Demonstration Satellites show the steepest expansion trajectory among emerging operators.
Customer Type:
Procurement sophistication varies sharply across customer categories, with institutional buyers demanding mission assurance and commercial operators optimizing for cost and schedule.
- Satellite Manufacturers:Prime contractors integrating launch into end-to-end delivery. Boeing and Airbus Defence and Space bundle transportation with spacecraft production, compressing vendor management overhead.
- Government Agencies:Civil and defense missions with evolving technical requirements. NASA and the United States Space Force sustain cost-plus contracting for complex payloads, though fixed-price migration accelerates.
- Telecommunication Providers:Constellation operators prioritizing launch cadence over unit cost. OneWeb and Amazon's Project Kuiper negotiate block buys across multiple providers to mitigate schedule risk.
- Research Organizations:University and laboratory missions with constrained budgets. European Space Agency member state programs aggregate demand through shared procurement.
- Space Startups:Venture-backed operators with high risk tolerance. Relativity Space and Isar Aerospace in the United States and Germany pursue dedicated small-lift access.
Government Agencies anchor revenue stability. Space Startups are climbing the fastest despite capital constraints.
Contract Type:
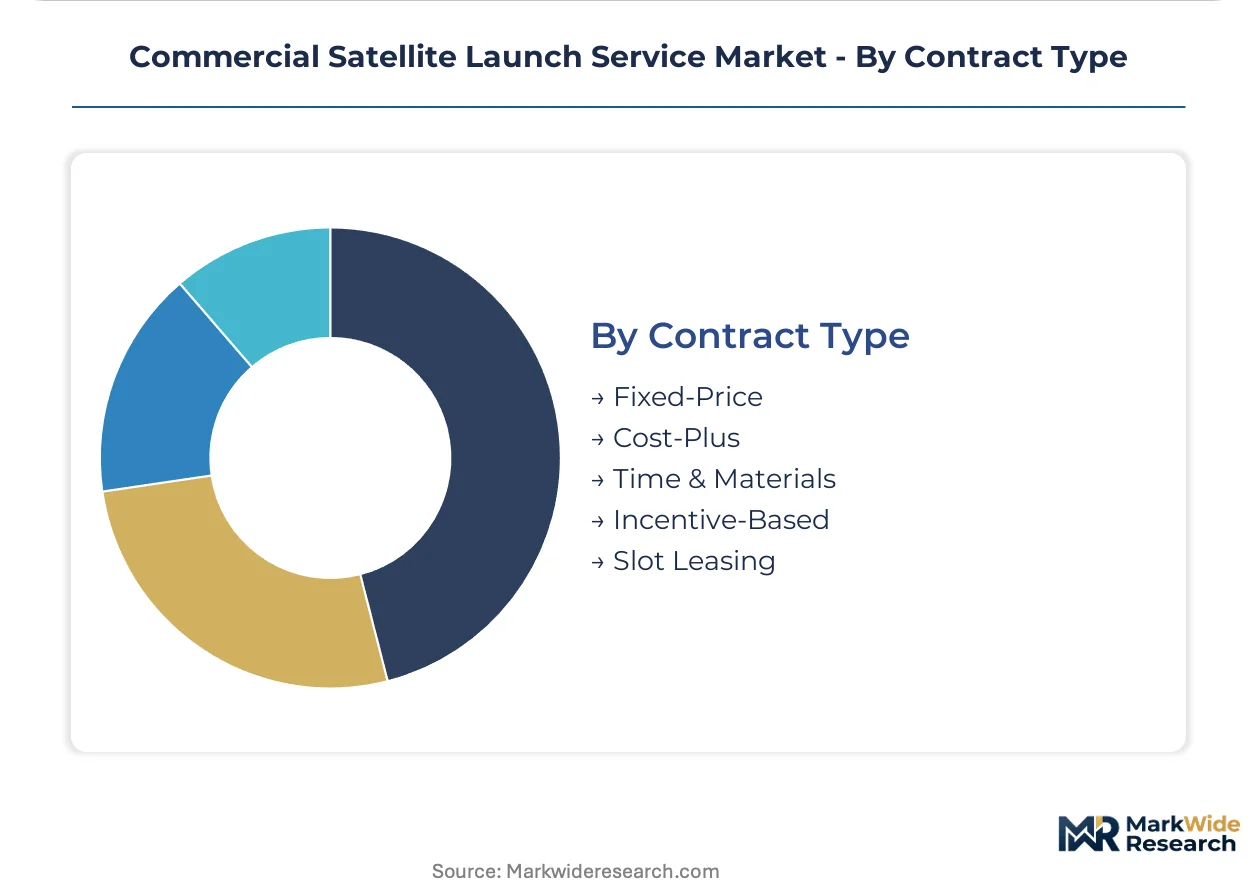
Risk allocation mechanisms segment procurement along design responsibility, cost uncertainty, and performance incentives.
- Fixed-Price:Predetermined mission cost with contractor absorbing design and execution risk. NASA Commercial Resupply established this precedent; United States defense agencies now emulate for operational missions.
- Cost-Plus:Reimbursement of allowable costs plus fixed fee. Persists for United States national security payloads with classified requirements and evolving specifications.
- Time & Materials:Labor and material cost recovery with minimal markup. Rare in launch services; occasional for integration support.
- Incentive-Based:Fee adjustments tied to schedule and technical performance. ESA employs for Ariane 6 development milestones.
- Slot Leasing:Pre-purchased launch capacity with transferability rights. Emerging model for constellation operators securing future access.
Fixed-Price dominates commercial procurement. Slot Leasing is gaining share fastest among constellation planners managing deployment risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch service trade flows heavily favor export-oriented providers with domestic range infrastructure. Nations with established spaceports and proven vehicle certification capture cross-border contract volume, while import-dependent markets rely on foreign lift capacity for constellation deployment.
United States
FAA Part 450 streamlined licensing collapsed approval timelines from years to months, accelerating commercial cadence. Cape Canaveral and Vandenberg Space Force Base anchor Eastern and Western range capacity, though pad scheduling conflicts now constrain annual flight volume. SpaceX and United Launch Alliance dominate domestic procurement, with emerging operators clustering in California and Texas.
China
MIIT coordinates civil-military launch scheduling alongside national space administration export controls. Xichang, Jiuquan, and Taiyuan satellite launch centers distribute capacity across inland provinces. Long March vehicle families serve institutional missions, while commercial spin-offs pursue dedicated small-lift access for domestic constellation operators.
France
ESA institutional backing and Ariane 6 modernization sustain autonomous European access to space. Kourou's equatorial Guiana Spaceport offers unmatched geostationary transfer orbit energy advantages. Arianespace anchors heavy-lift competitiveness, with supply chain concentration in Hauts-de-France and Provence-Alpes-Côte d'Azur.
Germany
Isar Aerospace and emerging Bavarian startups pursue dedicated small-lift capabilities for European rideshare demand. ESA Clean Space initiative propellant mandates accelerate green propulsion certification. Munich and Augsburg clusters concentrate propulsion engineering talent and component fabrication.
Japan
METI space industry promotion frameworks support domestic launch vehicle development and satellite export competitiveness. Tanegashima and Uchinoura space centers handle institutional and commercial missions. Kyushu region manufacturing bases supply precision components for liquid rocket engines.
Commercial Satellite Launch Service Market Key Industry Players
Concentration sits with vertically integrated heavy-lift providers and rapid-reuse specialists. The vendor base splits between established defense contractors with solid rocket motor capabilities and venture-backed newcomers pursuing methane-oxygen architectures. Three archetypes dominate: rapid-reuse scale operators, institutional mission assurance anchors, and dedicated small-lift disruptors. Competitive moves center on block-buy contract capture and propulsion technology licensing rather than horizontal consolidation.
Within the rapid-reuse tier, SpaceX exemplifies amortized hardware economics through booster recovery cadence. United Launch Alliance occupies the mission assurance position for national security payloads with proven expendable reliability. Arianespace anchors European institutional access, while Rocket Lab and Relativity Space represent the emerging dedicated-small-lift archetype targeting rideshare density.
| Leading Market Players |
|---|
| United Launch Alliance |
| Northrop Grumman |
| SpaceX |
| Relativity Space |
| China Aerospace Science and Technology Corporation |
| Blue Origin |
| Rocket Lab |
| Firefly Aerospace |
| Arianespace |
| Others |
Cost & Logistics Intelligence
Methane-oxygen staged combustion engine adoption is displacing kerosene-oxygen gas generator cycles across medium and heavy lift vehicles, simultaneously shifting propulsion engineering talent toward Texas and Bavaria while compressing per-kilogram launch economics through cleaner combustion residues and reduced refurbishment intervals.
Pricing Analysis
Industrial OEM buyers anchor fixed-price milestone contracting across commercial constellation deployments. Three-tier pricing structure across premium mission assurance, standard commercial rideshare, and economy demonstration tiers separates United Launch Alliance's national security premiums from SpaceX's amortized reuse rates and Rocket Lab's dedicated small-lift access. Cost compression in the economy tier is intensifying because venture-backed startups are accepting higher risk tolerance for technology validation missions. Telecommunication providers show the lowest price sensitivity due to ITU spectrum deadline penalties, while university research organizations face the tightest budget constraints.
Supply Chain Analysis
Port congestion at Long Beach and container availability constraints on transpacific trade lanes are feeding into solid rocket motor supply bottlenecks that stretch lead times for defense contractors. Turbopump and combustion chamber fabrication draws from specialized suppliers concentrated in the United States, France, and Germany. Supply chain risk centers on single-source vulnerability for high-performance alloys and cryogenic valve assemblies. Distribution runs through prime contractor integration facilities at Cape Canaveral, Vandenberg, and Kourou before final range delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid rocket engine design expertise is concentrating among aging specialists while universities produce software generalists, creating a combustion physics talent gap that threatens turnaround velocity for reusable architectures.
For Market Incumbents: Compound booster reuse cadence through rapid thermal protection system refurbishment protocols and in-house production of critical turbopump components. Lock in national security mission assurance contracts before FAA Part 450 streamlining enables emerging competitor licensing. Vertical integration into solid rocket motor supply would defend against Northrop Grumman production bottlenecks. For New Entrants and Emerging Players: FAA streamlined certification fast-tracks offer the most penetrable regulatory pathway for California and Texas operators seeking commercial launch licenses. Polar corridor expansion at Alaska's Pacific Spaceport Complex captures uncongested high-inclination demand from Earth observation constellations. Green propellant mandates from ESA's Clean Space initiative create procurement preference for early MON-25 certifiers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors rapid-reuse scale operators over heritage expendable architectures. Acquisition targets should demonstrate proven booster recovery with sub-30-day turnaround capability. Watch for FAA range capacity allocation decisions as the inflection signal determining annual flight volume ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Booster Certification | FAA Part 450 licensing validates rapid turnaround protocols for commercial cadence expansion. |
| Green Propellant Adoption | ESA Clean Space initiative accelerates MON-25 certification for European institutional preference. |
| Polar Spaceport Development | Alaska and Norway sites capture dedicated rideshare demand from Earth observation operators. |
| Engine Production Scale-Up | Backward integration into turbopump fabrication mitigates 18-24 month supplier lead times. |
| In-Orbit Servicing Partnership | Robotic refueling contracts shift revenue from single-transport to recurring logistics models. |
Research Approach
Operator-level perspectives from launch vehicle program managers, range safety officers, constellation procurement leads, and propulsion engineering directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA licensing databases, ESA procurement records, ITU spectrum coordination filings, and launch manifest aggregators. Bottom-up segment sizing triangulated against top-down market boundary estimates from national space agency budget disclosures.
Sensitivity analysis tested forecast robustness across launch cadence scenarios, propulsion technology adoption curves, and regulatory timeline variations over the projection horizon. Segmentation dimensions modeled include vehicle class, payload type, customer category, contract structure, and orbital destination. CAGRs were derived from historical launch volume trajectories and announced constellation deployment schedules. Industry-specific inputs incorporated ITU spectrum deadline enforcement patterns and range capacity expansion timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained reusable technology adoption and stable FAA licensing throughput; material deviation would warrant model refresh. Forecasts incorporate assumptions around propellant depot technology maturation and orbital debris mitigation compliance costs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Nano and Microsatellite Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Germany Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Remote Sensing Satellite Market
Satellite
Satellite Operation Service Market
Satellite
Russia Satellite Communications Market
Satellite
Satellite Manufacturing Market
Satellite
Satellite Sensor Market
Satellite
Global Dish Antennas Market
Satellite
North America Satellite Manufacturing Market
Satellite
UK Satellite Connectivity Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Military Satellite Market