
 China Satellite-Based Earth Observation Market | 2026-2036
China Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
China Satellite-Based Earth Observation Market Insights
The China satellite-based earth observation sector is restructuring around a sharp split between premium government-contracted reconnaissance missions and commodity analytics services sold to agribusiness and insurers. China Aerospace Science and Technology Corporation leverages its state-backed launch infrastructure to dominate high-altitude optical constellations. Chang Guang Satellite Technology Co., Ltd anchors the commercial tier with rapid-revisit Jilin-1 imaging for precision agriculture clients.
Satellite-based earth observation encompasses orbital platforms carrying electro-optical, synthetic aperture radar, or hyperspectral payloads that capture multispectral imagery with ground sample distances ranging from sub-meter to thirty-meter resolution, then downlink corrected data for terrain mapping, resource surveillance, and atmospheric profiling. Optical satellites retain the largest revenue share due to mature manufacturing pipelines and established calibration networks, while radar satellites represent the fastest-expanding segment because all-weather penetration unlocks maritime monitoring and disaster response contracts that optical systems cannot fulfill. Machine learning integration across geospatial technologies is redrawing margin pools toward automated feature-extraction software rather than raw imagery licensing.
MIIT orbital slot coordination rules, NMPA remote sensing data security classifications, and GB standard compliance requirements for geospatial accuracy together shape market access by restricting foreign satellite data resale and mandating domestic ground station processing. SAMR antitrust scrutiny of state enterprise pricing is gradually exposing certain analytics tiers to private competition. Stakeholders must track how dual carbon monitoring mandates from MEE redirect procurement budgets toward methane detection and carbon stock verification services.
Market Dynamics
Machine learning integration across geospatial technologies is redrawing margin pools toward automated feature-extraction software rather than raw imagery licensing, compressing traditional data resale margins while elevating software-centric revenue streams.
Growth Catalysts
- Dual Carbon Monitoring Mandates:MEE directives redirect procurement budgets toward methane detection and carbon stock verification services, creating sustained demand for hyperspectral payloads capable of atmospheric profiling.
- Heilongjiang Precision Agriculture:Crop monitoring data procurement from commercial satellite operators accelerates as large-scale farming cooperatives adopt variable-rate input management based on sub-meter resolution imagery.
- MIIT Spectrum Reforms:Orbital slot coordination rule revisions accelerate commercial constellation deployment timelines, reducing regulatory friction for private satellite operators seeking rapid-revisit capabilities.
Market Restraints
- Launch Infrastructure Concentration:State-backed launch providers dominate access to sun-synchronous orbits, constraining independent constellation deployment schedules and inflating slot reservation costs for commercial ventures.
- Ground Station Processing Mandates:NMPA remote sensing data security classifications require domestic downlink and preprocessing, fragmenting operational architectures and duplicating capital expenditure requirements.
- Optical Weather Dependency:Electro-optical payload performance degrades under persistent cloud cover in southern coastal provinces, limiting contract fulfillment reliability for maritime monitoring applications.
Strategic Opportunities
- Yangtze River Delta Corridor:Unmet demand for urban heat island monitoring and infrastructure deformation tracking across Shanghai, Jiangsu, and Zhejiang creates white space for synthetic aperture radar services.
- Insurer Risk Modeling:Agricultural reinsurance providers in northeastern provinces seek parametric trigger data, opening subscription revenue models based on automated yield loss detection algorithms.
- GB Standard Harmonization:Emerging geospatial accuracy certification frameworks for autonomous vehicle mapping create compliance-driven procurement channels for high-precision elevation data products.
Industry Challenges
- Geospatial AI Talent Scarcity:Shortage of machine learning engineers with domain expertise in radiometric correction and orthorectification workflows constrains feature-extraction product development cycles.
- Multi-Constellation Integration Complexity:Agribusiness clients struggle to fuse Jilin-1 optical data with radar sources into unified analytics pipelines, delaying operational deployment of fused monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Satellite-Based Earth Observation Market |
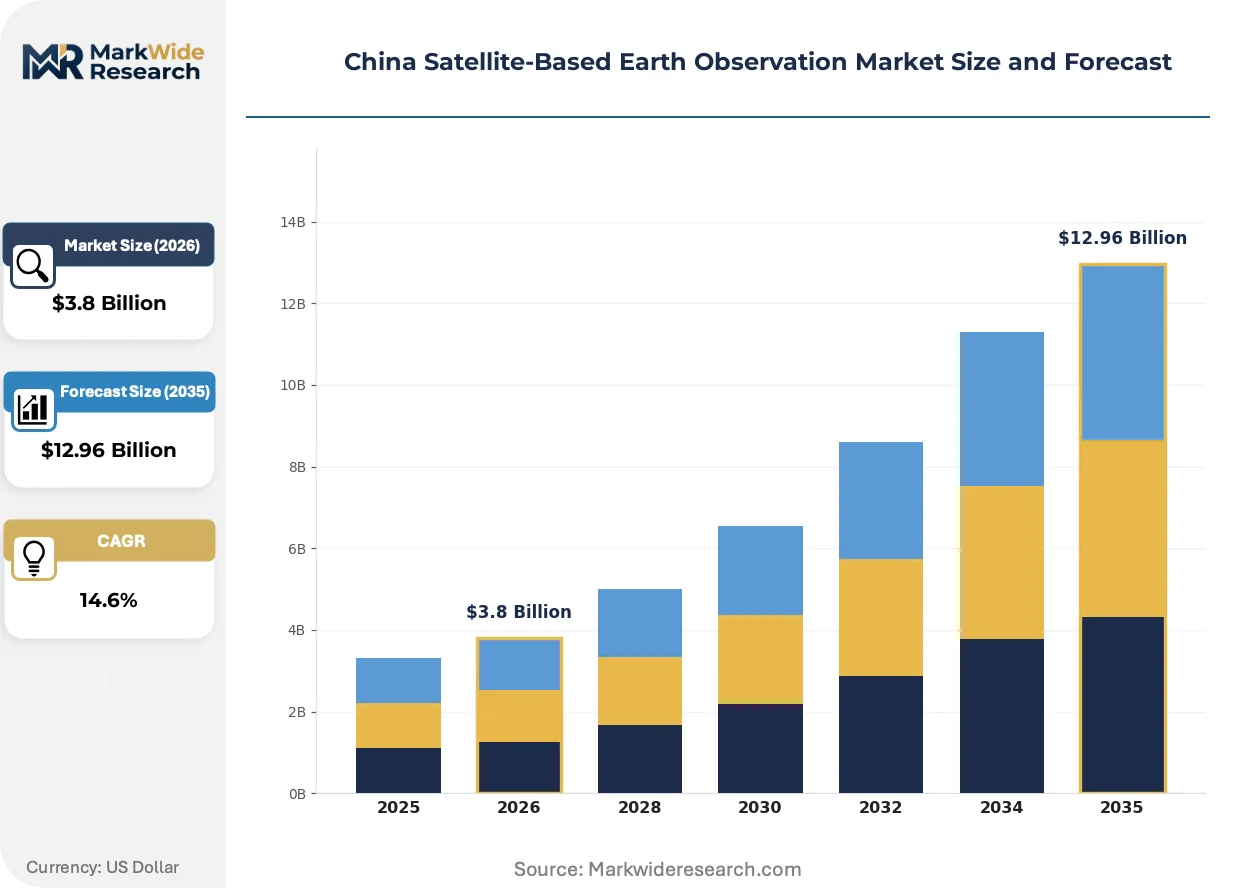
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Sounding Satellites Application: Agriculture Monitoring, Urban Planning, Disaster Management, Climate Research End User: Government Agencies, Research Institutions, Private Enterprises, Environmental Organizations Technology: Remote Sensing, Machine Learning, Data Analytics, Geospatial Technologies |
| Companies Covered | China Aerospace Science and Technology Corporation, China Academy of Space Technology, Chang Guang Satellite Technology Co., Ltd, Beijing Space Eye Innovation Technology Co., Ltd., China Siwei Surveying and Mapping Technology Co., Ltd., China Aerospace Science and Industry Corporation, Twenty First Century Aerospace Technology (Asia) Pte. Ltd., China Resources Satellite Application Center, 21AT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Satellite-Based Earth Observation Market Trends and Innovations
Onboard processing architectures and edge-computing payloads are transforming satellite value chains by shifting analytics execution from ground stations to orbital platforms, compressing data latency and enabling real-time decision support.
Synthetic aperture radar miniaturization is electrifying maritime surveillance and disaster response contracting. Port authorities in Fujian and Guangdong provinces are procuring all-weather vessel tracking services at accelerating pace. This capability expansion is compressing optical-only operators into narrower agricultural niches where cloud penetration matters less.
MEE dual carbon verification protocols now mandate satellite-derived methane plume detection for heavy industrial facilities. Steel and coal chemical producers in Shanxi and Inner Mongolia must submit quarterly emissions attestations based on third-party remote sensing analysis. This regulatory pressure is redirecting procurement budgets from traditional stack monitoring equipment toward subscription-based atmospheric analytics services.
Agribusiness buyers in Heilongjiang and Jilin provinces are consolidating vendor relationships around integrated crop monitoring platforms that bundle imagery, soil moisture modeling, and yield forecasting into single contracts. Equipment dealers and agricultural cooperatives are displacing direct satellite data subscriptions, capturing margin through value-added agronomic interpretation and prescription map generation services.
China Satellite-Based Earth Observation Market Segmentation
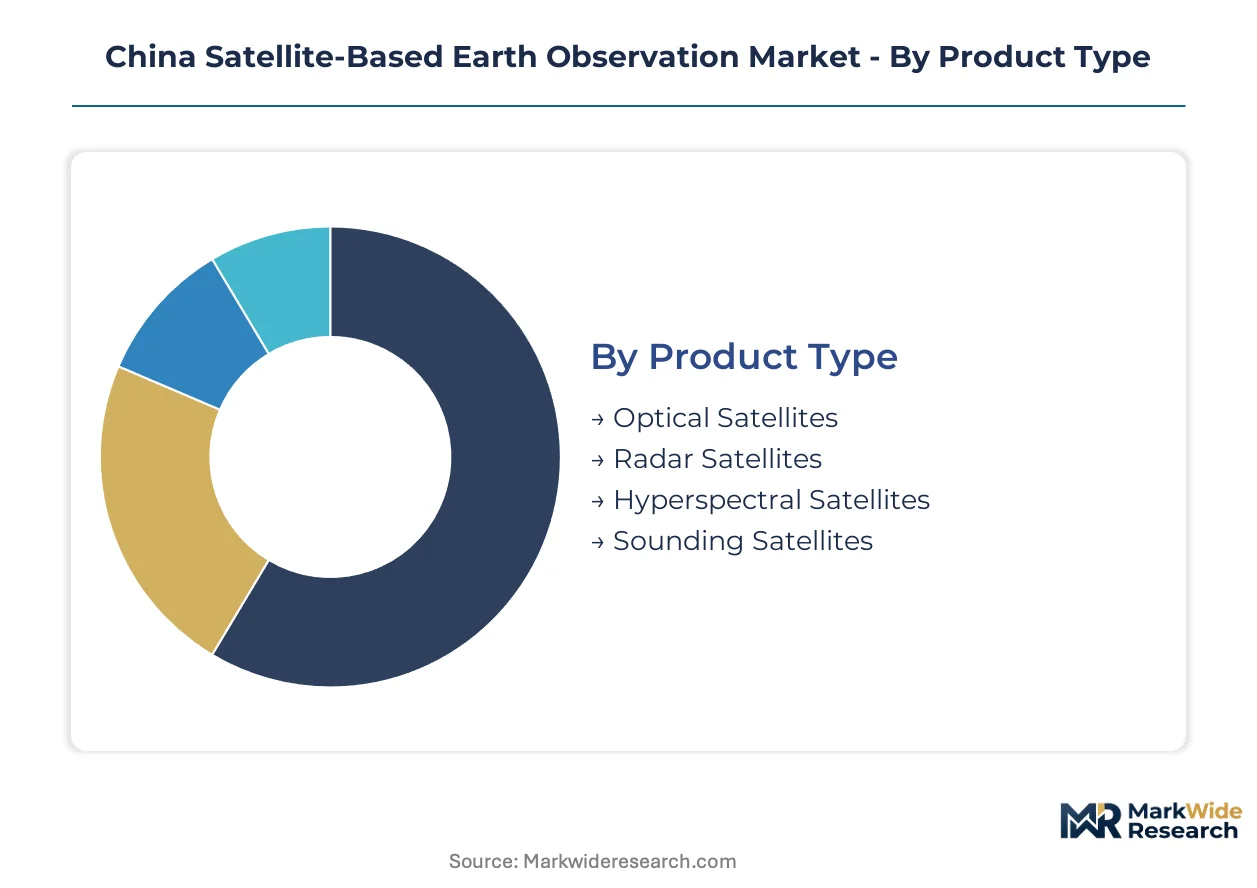
China's satellite-based earth observation market fragments across payload technologies, end-use applications, and customer procurement patterns. Each segmentation layer reveals distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Volume concentration favors optical platforms with mature manufacturing pipelines, while premium pricing accrues to radar and hyperspectral systems with specialized atmospheric capabilities.
- Optical Satellites:Electro-optical payloads capture multispectral imagery with sub-meter to thirty-meter ground sample distances. Heilongjiang precision agriculture cooperatives drive procurement of high-resolution crop monitoring data for variable-rate input management.
- Radar Satellites:Synthetic aperture radar systems penetrate cloud cover and darkness for all-weather surveillance. Maritime monitoring contracts from Fujian and Guangdong port authorities accelerate deployment of miniaturized SAR constellations.
- Hyperspectral Satellites:Atmospheric profiling payloads detect methane plumes for MEE dual carbon verification protocols.
- Sounding Satellites:Vertical atmospheric column measurement systems support meteorological agencies and climate research networks.
Mature deployment sits with optical satellites. Newer deployment is concentrated in radar satellites.
Application:
Customer procurement patterns split between compliance-driven government contracts and operational efficiency purchases by commercial operators.
- Agriculture Monitoring:Crop health assessment and yield forecasting services bundle imagery with soil moisture modeling. Large-scale farming cooperatives in Jilin and Heilongjiang consolidate vendor relationships around integrated monitoring platforms.
- Urban Planning:Infrastructure deformation tracking and heat island analysis create demand across the Yangtze River Delta corridor spanning Shanghai, Jiangsu, and Zhejiang.
- Disaster Management:Rapid-response imagery supports flood assessment and earthquake damage evaluation for emergency management departments.
- Climate Research:Long-term atmospheric datasets serve national meteorological centers and carbon cycle research programs.
Government budget allocation dominates climate research. Commercial subscription models are expanding fastest in agriculture monitoring.
End User:
Procurement authority concentrates in state-affiliated entities, though private enterprise access is widening under MIIT spectrum reforms.
- Government Agencies:National defense, environmental protection, and emergency management departments contract for reconnaissance and regulatory enforcement data.
- Research Institutions:Academies of science and technical universities acquire calibrated datasets for geophysical and climate studies.
- Private Enterprises:Agricultural equipment dealers and insurance providers build value-added services atop raw imagery subscriptions.
- Environmental Organizations:Conservation groups monitor ecosystem health and land use change for protected area management.
Budget scale peaks with government agencies. Procurement flexibility is greatest among private enterprises.
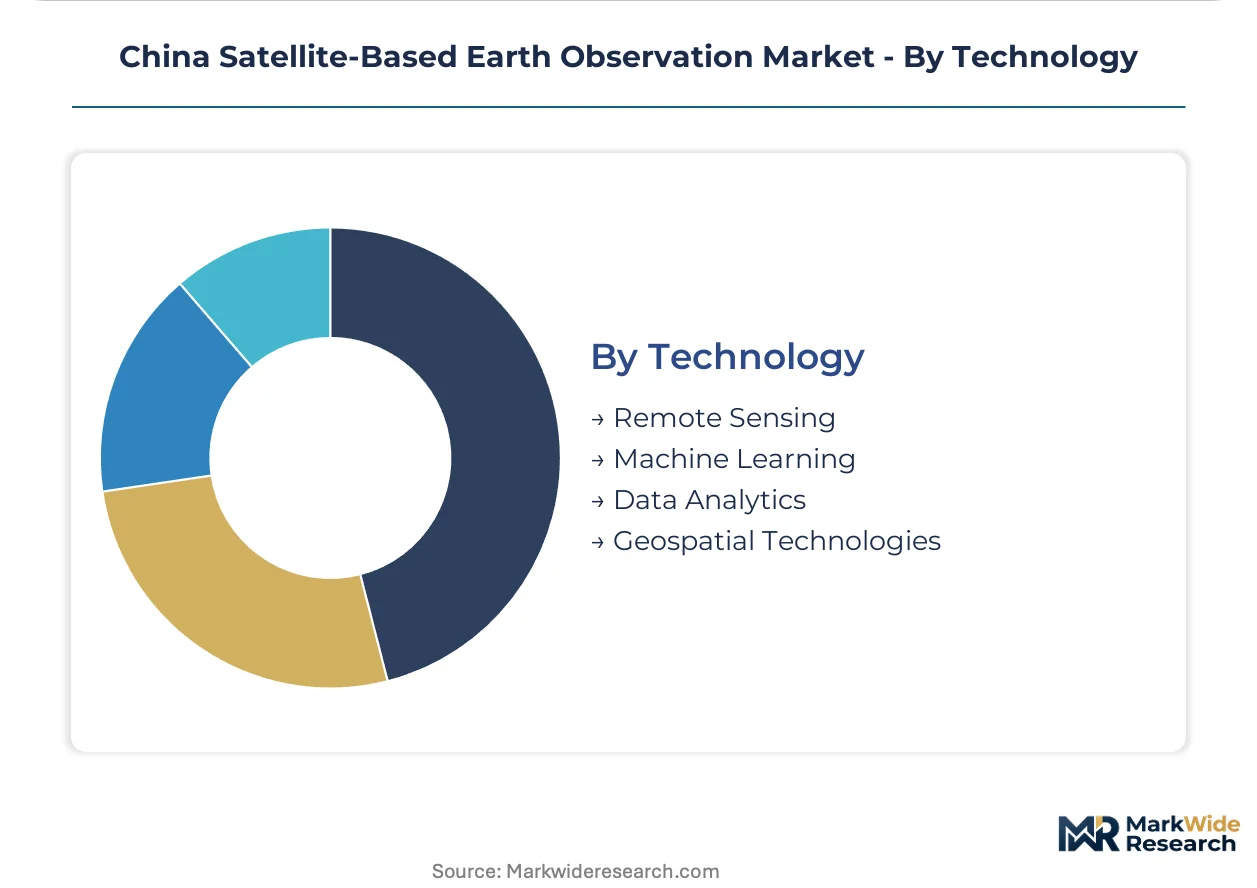
Technology:
Margin pools are migrating from raw data licensing toward automated analytics execution.
- Remote Sensing:Orbital platform operations and ground segment infrastructure for data acquisition and downlink.
- Machine Learning:Automated feature-extraction algorithms compress analyst labor costs and accelerate decision-support delivery.
- Data Analytics:Statistical modeling and trend identification for yield forecasting and risk assessment applications.
- Geospatial Technologies:Orthorectification, radiometric correction, and coordinate system integration for GB standard compliance.
Established revenue streams flow through remote sensing. Value capture is shifting most quickly toward machine learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta corridor spanning Shanghai, Jiangsu, and Zhejiang anchors procurement intensity for urban heat island monitoring and infrastructure deformation tracking services. Provincial environmental bureaus and municipal planning commissions across this megaregion are consolidating satellite data contracts under unified procurement frameworks.
Heilongjiang Province
Large-scale farming cooperatives in Heilongjiang are expanding procurement of sub-meter resolution crop monitoring data for variable-rate input management. The Ministry of Agriculture and Rural Affairs subsidizes precision agriculture technology adoption through dedicated equipment upgrade programs. Harbin-based agricultural equipment dealers are capturing margin by bundling satellite imagery with soil moisture modeling and prescription map generation services.
Jilin Province
Jilin's corn and soybean belt generates sustained demand for yield forecasting analytics from commercial satellite operators. Provincial agricultural insurance programs now require third-party remote sensing verification for parametric claim triggers. Changchun and surrounding counties host consolidating vendor relationships around integrated crop monitoring platforms that bundle multiple data streams.
Shanxi Province
Steel and coal chemical producers in Shanxi face MEE-mandated quarterly methane emissions attestations based on satellite-derived atmospheric analysis. The dual carbon verification protocol redirects procurement budgets from stack monitoring equipment toward hyperspectral subscription services. Taiyuan industrial clusters are contracting with analytics providers for plume detection and carbon stock verification.
Inner Mongolia Autonomous Region
Energy-intensive facilities across Inner Mongolia must submit satellite-verified emissions documentation under tightening MEE enforcement protocols. The region's coal-to-chemical complexes and power generation assets drive demand for atmospheric profiling payloads capable of detecting fugitive methane releases. Hohhot and Ordos industrial zones are emerging as concentrated procurement nodes for carbon monitoring services.
Guangdong Province
Port authorities in Guangdong are accelerating procurement of all-weather vessel tracking services from synthetic aperture radar operators. Maritime surveillance contracts from Fujian and Guangdong ports are electrifying miniaturized SAR constellation deployment timelines. Shenzhen and Guangzhou maritime administration bureaus are consolidating multi-year service agreements for coastal zone monitoring and illegal fishing detection.
China Satellite-Based Earth Observation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the government-contracted reconnaissance and commercial analytics service divide. State-backed launch infrastructure operators dominate high-altitude optical constellation deployment, while private satellite ventures compete on rapid-revisit capabilities for agricultural and insurance clients. Three archetypes define the competitive set: state aerospace conglomerates with captive launch access, commercial imagery providers with rapid-revisit constellations, and analytics software vendors with automated feature-extraction capabilities. Competitive moves concentrate on MIIT spectrum acquisition timing and NMPA data licensing compliance positioning.
Within the state aerospace tier, China Aerospace Science and Technology Corporation and China Academy of Space Technology exemplify vertically integrated players with orbital slot coordination advantages. Chang Guang Satellite Technology Co., Ltd anchors the commercial imagery segment with its Jilin-1 constellation architecture. These three entities represent distinct strategic positions across the premium-to-commodity margin spectrum, with procurement authority flowing differentially to each based on mission classification and data security requirements.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| China Academy of Space Technology |
| Chang Guang Satellite Technology Co., Ltd |
| Beijing Space Eye Innovation Technology Co., Ltd. |
| China Siwei Surveying and Mapping Technology Co., Ltd. |
| China Aerospace Science and Industry Corporation |
| Twenty First Century Aerospace Technology (Asia) Pte. Ltd. |
| China Resources Satellite Application Center |
| 21AT |
| Others |
Pricing and Supply Chain Analysis
Rare earth element price indices from the Chinese Society of Rare Earths cascade through satellite manufacturing supply chains, compressing margins for optical payload producers while amplifying pricing power for vertically integrated state conglomerates with captive material access.
Pricing Analysis
Yield-verified pricing anchors agricultural analytics contracts, where insurers and cooperatives pay premiums tied to forecast accuracy rather than raw imagery volume. Three-tier pricing structure across premium, standard, and economy levels separates government reconnaissance missions from commercial crop monitoring and commodity weather data feeds. Cost compression in standard-tier optical imagery is intensifying because Jilin-1 rapid-revisit constellations flood the market with sub-meter resolution supply. Agricultural equipment dealers show highest price sensitivity, while MEE-mandated emissions verification buyers accept substantial premiums for hyperspectral methane detection.
Supply Chain Analysis
Direct-to-agribusiness channels handle precision farming demand, while government procurement runs through state-affiliated distributors with NMPA security clearance. Manufacturing concentrates in China for optical payloads, draws from Germany for precision optics, and rests on Japan for synthetic aperture radar components. Supply chains hinge on gallium arsenide substrates, precision optical glass, and radiation-hardened electronics. Single-source vulnerability sits with domestic launch providers controlling sun-synchronous orbit access. Distribution runs through Harbin equipment dealers for agricultural buyers and provincial environmental bureaus for compliance-driven procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
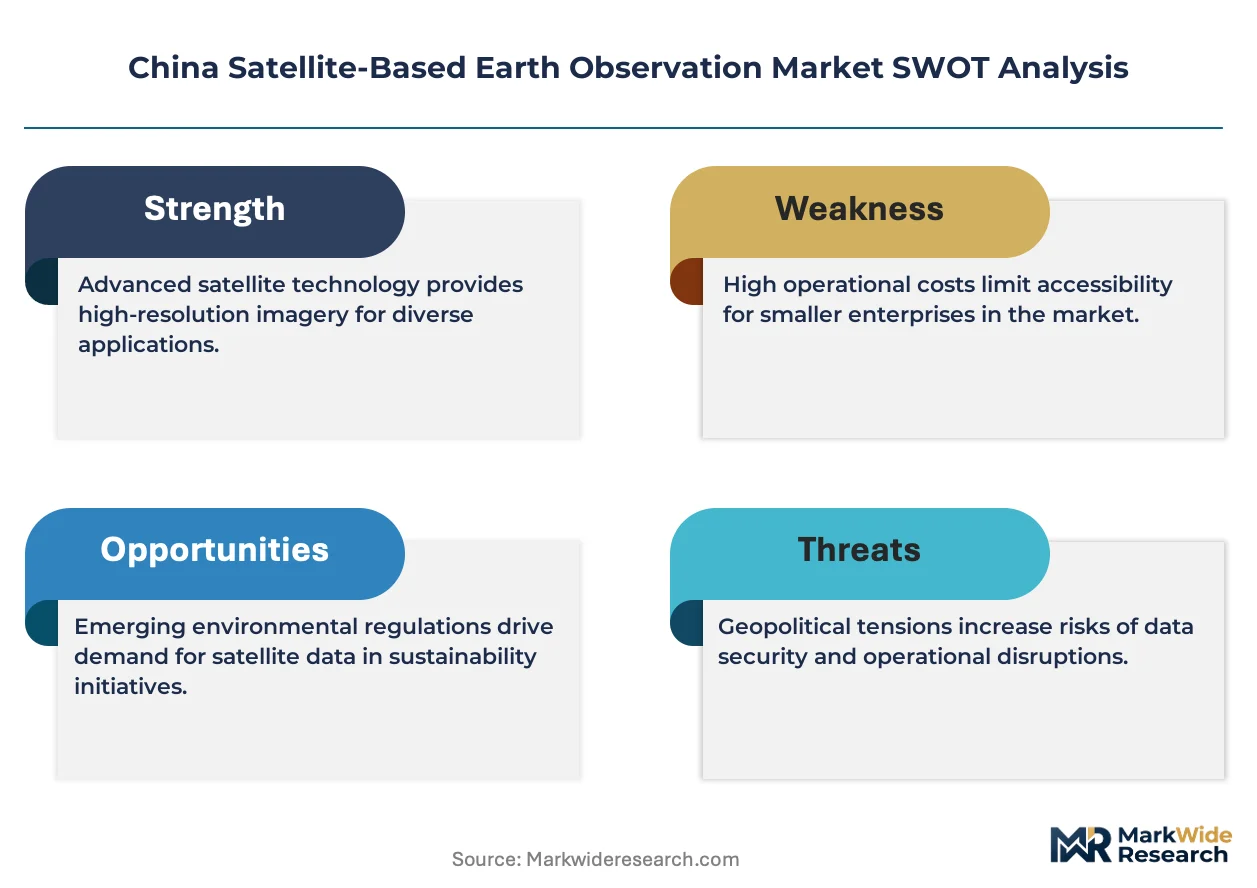
This market reads as a cost-of-compliance story where NMPA remote sensing data security classifications erect capital barriers that only state-backed or well-capitalized private operators can surmount.
For Market Incumbents: Deepen integration with agricultural equipment dealers in Heilongjiang and Jilin to lock distribution channels against emerging SAR constellation entrants. Expand in-house hyperspectral payload manufacturing to capture MEE-driven methane detection premiums before radar operators diversify into atmospheric profiling. MIIT spectrum allocation timing remains the critical defensive lever. For New Entrants and Emerging Players: SAMR antitrust scrutiny of state enterprise pricing in China opens a window for private analytics vendors to undercut government-contracted reconnaissance margins in commodity agricultural monitoring. Target insurer risk modeling in northeastern provinces with parametric trigger subscription models. White space concentrates in Yangtze River Delta urban heat island monitoring where SAR penetration lags optical saturation. For Investors and Strategic Acquirers: Distressed-cycle entries favor machine learning feature-extraction software vendors with NMPA compliance infrastructure already deployed. Long-term viability hinges on regulatory capture rather than technology differentiation alone. Watch MIIT orbital slot auction timing as the inflection signal for constellation deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Payload Development | MEE dual carbon mandates redirect steel and coal chemical procurement toward atmospheric analytics services. |
| Agricultural Equipment Dealer Partnership | Harbin and Changchun distributors capture margin through bundled imagery and prescription map generation. |
| SAR Constellation Miniaturization | Fujian and Guangdong port authorities accelerate all-weather vessel tracking procurement timelines. |
| Machine Learning Feature-Extraction Platform | Automated yield loss detection algorithms unlock parametric insurance subscription revenue models. |
| NMPA Security Clearance Acquisition | Domestic ground station processing mandates fragment architectures and duplicate capital requirements for uncertified rivals. |
Research Methodology
Multi-period observation of MIIT spectrum allocation timelines, NMPA licensing decisions, and MEE enforcement protocol shifts anchored the trend analysis, supplemented by interviews with satellite constellation operators, agricultural equipment procurement managers, provincial environmental bureau officials, and reinsurance risk modeling directors. Secondary validation drew from MIIT orbital slot registries, NMPA remote sensing data security classification bulletins, MEE emissions verification protocols, and SAMR antitrust disclosure filings. Bottom-up segment sizing triangulated against top-down procurement budget aggregation from provincial government expenditure reports.
Segment-weighting across payload technology, end-use application, and customer procurement pattern dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating dual carbon mandate enforcement intensity, precision agriculture technology subsidy uptake rates, and SAR miniaturization cost decline trajectories. Hyperspectral payload deployment timelines and machine learning integration penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for onboard edge-computing architectures would alter the outlook for ground station processing revenue pools. Forecasts embed assumptions regarding MIIT regulatory pacing, MEE enforcement consistency, and agricultural cooperative consolidation trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Commercial Satellite Imaging Market
Satellite
Satellite Transponder Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Satellite Communications Service Market
Satellite
Japan Satellite Imagery Services Market
Satellite
North America Satellite IoT Market
Satellite
Advanced Satellite Market
Satellite
Global Remote Sensing Services Market
Satellite
India Satellite Connectivity Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
High-Throughput Satellite Market
Satellite
China Satellite Communication Market
Satellite
Cubesat Market
Satellite
France Satellite Imagery Services Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market