
 Aviation Fluid Market | 2026-2036
Aviation Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Fluid Market Analytics
Defense contractors are unwinding the historical dominance of commercial airlines as the primary volume buyers of aviation fluids. Exxon Mobil Corporation anchors military supply chains through its synthetic turbine oil portfolio, while Shell plc competes aggressively on aviation fuel logistics across NATO airbases. BP plc differentiates via specialized hydraulic fluid formulations engineered for next-generation fighter platforms.
Aviation fluids encompass lubricants, fuels, and functional chemicals formulated to operate across temperature extremes from minus 65 to over 400 degrees Fahrenheit, with viscosity indices engineered for altitude-induced shear stress. These products prevent thermal degradation, corrosion, and seal failure in turbine engines, hydraulic actuators, and avionic cooling systems. Engine oils command the deepest margin pools due to MIL-PRF-23699 certification barriers and reformulation costs tied to synthetic ester base stocks. Hydraulic fluids are gaining fastest within the product type dimension as fly-by-wire architectures multiply actuator counts per airframe. Among end users, maintenance providers represent the most fragmented yet highest-frequency purchasing segment, driven by scheduled overhaul intervals and line-replaceable unit exchanges.
FAA mandates under 14 CFR Part 43 govern fluid specifications for US-registered aircraft, while SAE International publishes AS5780 and AMS standards that OEMs embed in procurement contracts. The EPA simultaneously scrutinizes phosphate ester toxicity in hydraulic formulations, pressuring suppliers toward bio-derived alternatives. Stakeholders must monitor how ASTM D4054 qualification pathways for sustainable aviation fuel intermediates reshape blending requirements and infrastructure compatibility across existing distribution networks.
Market Dynamics
Military aviation procurement is accelerating fluid consumption across NATO-aligned fleets, while SAE AS5780 revisions tighten thermal stability benchmarks and reshape supplier qualification pathways.
Growth Catalysts
- SAE AS5780 Revision Cycle:Tightened thermal stability benchmarks for engine oils are forcing reformulation investments that lock in multi-year supply contracts with qualified vendors.
- Fly-by-Wire Architecture Proliferation:Modern fighter and commercial platforms multiply hydraulic actuator counts per airframe, expanding addressable fluid volume per unit produced.
- Defense Procurement Surge:NATO member states are expanding fleet readiness programs that specify synthetic turbine oils under MIL-PRF-23699 certification tiers.
Market Restraints
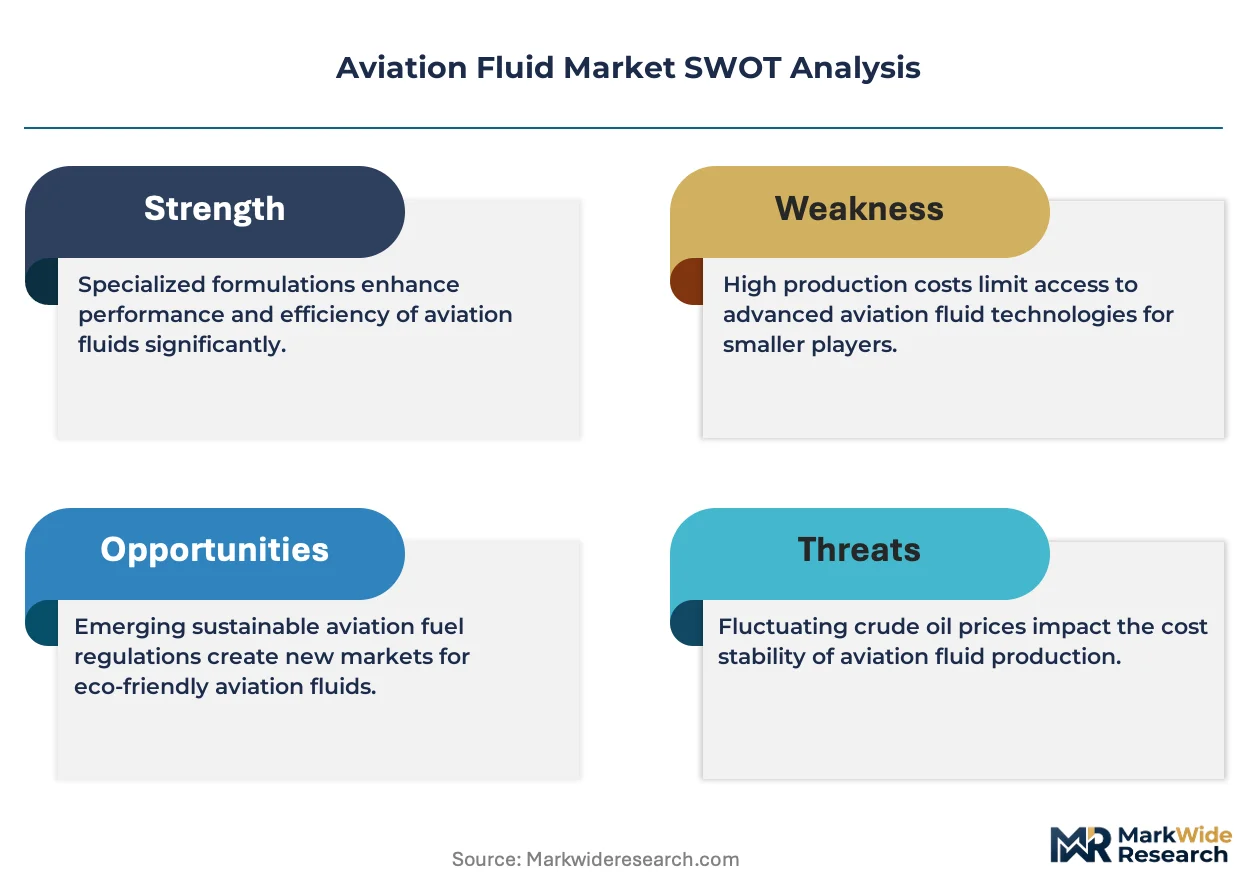
- Synthetic Ester Base Stock Concentration:Supply of high-purity neopentyl polyol esters concentrates among specialty chemical producers in Germany and the United States, creating input vulnerability.
- EPA Phosphate Ester Scrutiny:Toxicity assessments under TSCA Section 6 are pressuring hydraulic fluid suppliers toward bio-derived alternatives with unproven scale economics.
- MIL-PRF-23699 Certification Barriers:Qualification timelines extending 18-24 months for new synthetic turbine oil entrants protect incumbents but constrain supply elasticity.
Strategic Opportunities
- ASTM D4054 SAF Pathways:Sustainable aviation fuel qualification standards are reshaping blending requirements and creating infrastructure retrofit demand across existing distribution networks.
- Maintenance Provider Fragmentation:Third-party MRO facilities represent high-frequency purchasing segments underserved by direct OEM supply chains.
- Bio-Derived Hydraulic Formulations:EPA pressure on phosphate esters creates first-mover advantage for suppliers with validated vegetable oil-based alternatives meeting fire-resistance specifications.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in synthetic ester chemistry and high-temperature additive packages concentrates among retiring specialists at defense contractors and major oil companies.
- Dual Certification Complexity:Suppliers must maintain parallel MIL-PRF-23699 and SAE AS5780 qualifications while tracking divergent revision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Fluid Market |
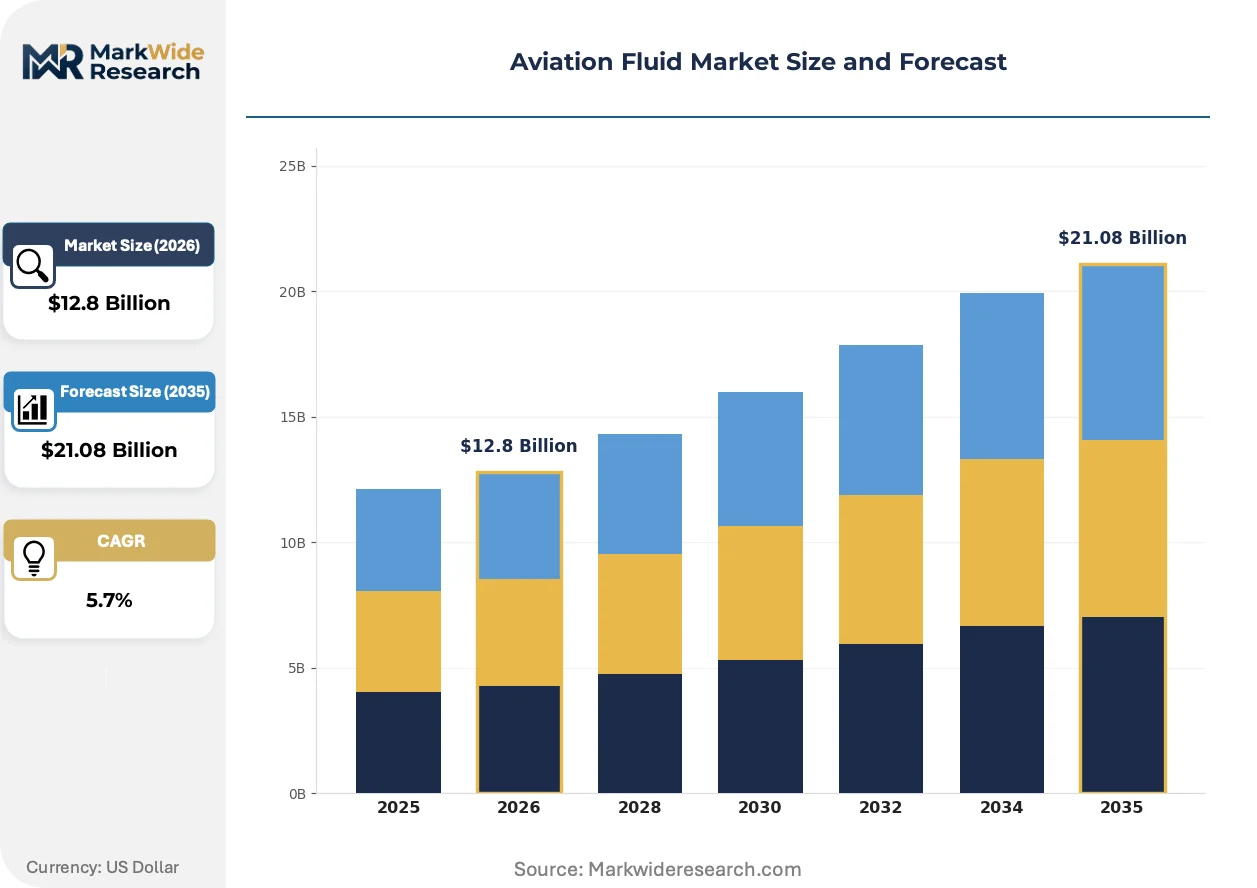
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avionic Fluids, Engine Oils, Hydraulic Fluids, Cleaners Application: Commercial Aviation, Military Aviation, General Aviation, Helicopters End User: Aerospace OEMs, Maintenance Providers, Airlines, Defense Contractors Service Type: Refueling Services, Maintenance Services, Storage Solutions, Distribution |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, BP plc, Shell plc, TotalEnergies, Valero Energy Corporation, Phillips 66, Neste, World Fuel Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Fluid Market Evolving Landscape
Formulation science is pivoting toward thermal endurance and environmental compliance as the dominant axes of product differentiation, compressing legacy mineral oil positions.
Polyol ester base stocks with viscosity indices exceeding 140 are supplanting diester formulations in next-generation engine oils. Military procurement offices specify these chemistries for extended drain intervals in high-thrust turbofan applications. The shift compresses margin structures for suppliers lacking backward integration into ester feedstock production.
REACH Annex XIV authorization requirements for certain phosphate ester flame retardants are accelerating substitution timelines for hydraulic fluids. European MRO facilities now face mandatory inventory turnover obligations that disrupt established supply relationships. Suppliers with pre-qualified bio-alternative formulations capture retrofit contracts at NATO airbases in Germany and Italy.
Scheduled overhaul intervals are compressing as predictive maintenance analytics penetrate commercial and military fleets. Airlines and defense operators now demand just-in-time fluid replenishment tied to sensor-triggered consumption signals. This pattern concentrates purchasing authority with integrated logistics providers at major hubs in the United States and United Kingdom.
Aviation Fluid Market Segmentation
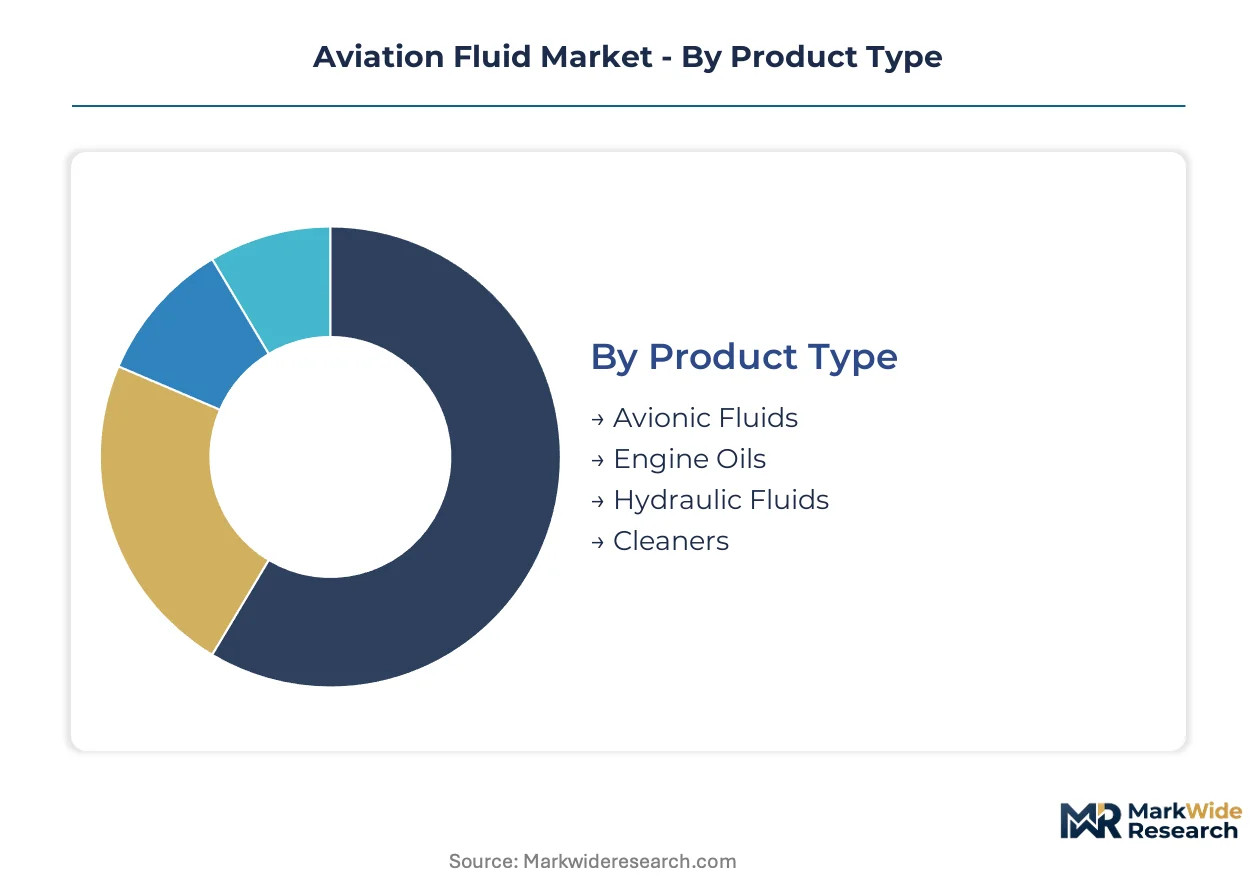
Aviation fluid procurement patterns diverge sharply across military and commercial channels, with specification regimes and certification timelines fragmenting supplier relationships. Segment boundaries are hardening as SAE AS5780 and MIL-PRF-23699 create non-overlapping qualification pools that lock in multi-year contract structures.
Product Type:
Engine oils face the most acute substitution pressure from synthetic ester reformulations, while hydraulic fluids confront bio-derived alternatives under regulatory toxicity scrutiny.
- Engine Oils:Synthetic turbine formulations based on neopentyl polyol esters dominate high-thrust applications, with viscosity indices engineered to exceed 140 for altitude shear resistance. Demand concentrates in United States defense procurement offices specifying MIL-PRF-23699 FST certification tiers for fighter platform readiness programs.
- Hydraulic Fluids:Fire-resistant phosphate ester formulations currently anchor fly-by-wire actuator systems across Boeing and Airbus architectures. EPA TSCA Section 6 assessments are pressuring NATO-aligned operators toward vegetable oil-based alternatives, creating qualification bottlenecks at German and Italian airbases.
- Avionic Fluids:Dielectric coolants and heat transfer media formulated for radar and electronic warfare systems operate across minus 65 to 400 degrees Fahrenheit thermal envelopes.
- Cleaners:Solvent-based and aqueous degreasing agents maintain turbine compressor blade efficiency, with specification divergence between commercial carrier SOPs and military technical orders.
Engine oils retain volume leadership; hydraulic fluids hold the steepest expansion curve.
Application:
Military aviation procurement runs on multi-year synthetic turbine oil contracts with 18-24 month qualification barriers, while commercial aviation operates on spot-market fuel logistics with thinner margin capture.
- Military Aviation:NATO fleet expansion programs specify synthetic ester engine oils under rigid MIL-PRF-23699 certification tiers, with United States defense contractors anchoring procurement volume through integrated logistics contracts.
- Commercial Aviation:Scheduled overhaul intervals for widebody and narrowbody fleets drive predictable consumption patterns, with SAE AS5780 thermal stability benchmarks governing supplier selection at major carrier hubs in Atlanta and Dubai.
- Helicopters:Rotorcraft hydraulic systems demand specialized fire-resistant formulations for transmission lubrication, with offshore oil-and-gas operators in the North Sea maintaining distinct inventory pools.
- General Aviation:Piston-engine mineral oils and legacy turbine formulations serve flight training and private operator segments with less stringent specification requirements.
Commercial aviation maintains procurement frequency leadership; military aviation commands the deepest contract duration.
End User:
Maintenance providers fragment purchasing authority across third-party MRO networks, while defense contractors consolidate volume through prime vendor arrangements with synthetic ester suppliers.
- Maintenance Providers:Third-party MRO facilities in Singapore, Frankfurt, and Dallas execute high-frequency line-replaceable unit exchanges, with just-in-time replenishment tied to sensor-triggered consumption analytics.
- Defense Contractors:Lockheed Martin and Raytheon specify synthetic turbine oils through multi-year sole-source agreements, with backward integration into additive package formulation protecting margin structures.
- Aerospace OEMs:Boeing and Airbus embed SAE AS5780 and AMS specifications into procurement contracts for new airframe production, locking suppliers into parallel qualification tracks.
- Airlines:Delta, United, and Lufthansa operate centralized fluid inventory at hub-and-spoke maintenance facilities, with predictive maintenance platforms compressing reorder cycles.
Defense contractors anchor contract value; maintenance providers drive transaction velocity.
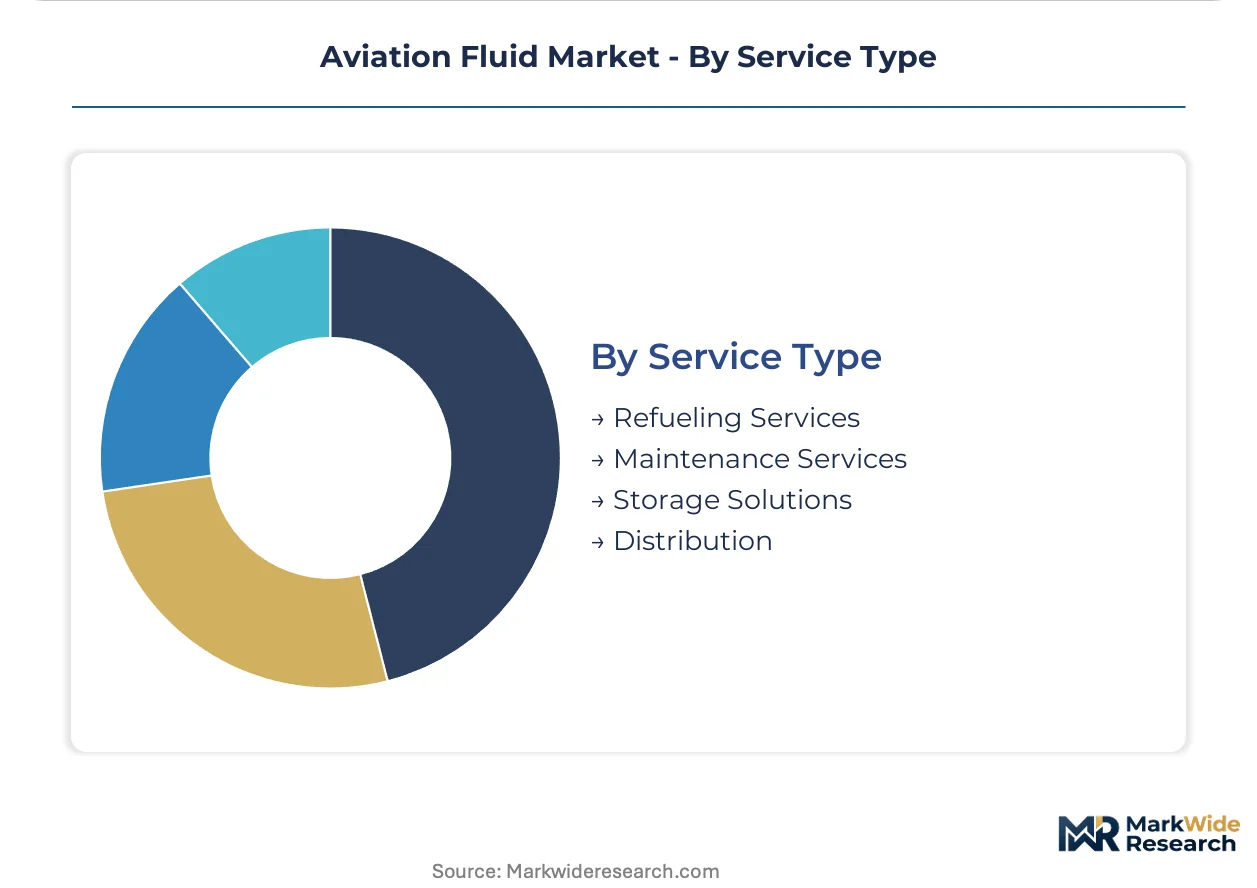
Service Type:
Distribution and storage infrastructure concentrates in United States and United Kingdom logistics hubs, while refueling services face sustainable aviation fuel blending retrofit requirements under ASTM D4054 pathways.
- Distribution:Integrated logistics providers control last-mile delivery to military airbases and commercial hubs, with NATO supply chains in Germany and Italy requiring dual-use compatibility for conventional and bio-derived formulations.
- Maintenance Services:Predictive analytics penetration is compressing scheduled overhaul intervals, with fluid replenishment bundled into sensor-triggered service contracts at United States and United Kingdom facilities.
- Storage Solutions:Bulk tankage and mobile refueling assets concentrate at Atlanta Hartsfield-Jackson, Dubai International, and RAF Mildenhall, with fire-resistant hydraulic fluid segregation requirements complicating inventory management.
- Refueling Services:Sustainable aviation fuel intermediates are reshaping blending infrastructure, with EPA and ECHA regulatory timelines creating retrofit demand across existing distribution networks.
Distribution commands infrastructure investment; maintenance services capture recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic ester production clusters in Germany and the United States concentrate supply-side leverage for aviation fluid formulations. Military procurement offices in NATO member states anchor demand volume through multi-year synthetic turbine oil contracts. Regulatory divergence between FAA specifications and ECHA authorization timelines fragments qualification pathways across Atlantic supply chains.
United States
Defense contractors in Texas and Virginia specify MIL-PRF-23699 certified synthetic turbine oils for fighter platform readiness programs. FAA mandates under 14 CFR Part 43 govern fluid specifications for US-registered aircraft, embedding SAE AS5780 thermal stability benchmarks into procurement contracts. Atlanta Hartsfield-Jackson and Dallas-Fort Worth concentrate bulk storage infrastructure for commercial carrier hub-and-spoke operations.
Germany
Specialty chemical producers in North Rhine-Westphalia manufacture high-purity neopentyl polyol esters for next-generation engine oil formulations. REACH Annex XIV authorization requirements for phosphate ester flame retardants accelerate hydraulic fluid substitution timelines at NATO airbases. Frankfurt and Hamburg anchor distribution networks serving European MRO facilities with just-in-time replenishment contracts.
United Kingdom
Integrated logistics providers at RAF Mildenhall and commercial hubs near London manage dual-use inventory for conventional and bio-derived formulations. The UK Civil Aviation Authority enforces parallel qualification tracks for MIL-PRF-23699 and SAE AS5780 specifications. Southeast England concentrates predictive maintenance analytics platforms compressing scheduled overhaul intervals for carrier fleets.
France
TotalEnergies and aerospace OEMs in the Île-de-France region coordinate SAE AS5780 specification embedding for new airframe production. The French national aviation authority aligns with EASA frameworks on sustainable aviation fuel blending requirements under ASTM D4054 pathways. Toulouse and Paris-Le Bourget cluster refueling services infrastructure facing retrofit demand from SAF intermediate distribution.
Italy
Leonardo and defense operators in Rome specify fire-resistant hydraulic fluids for fly-by-wire actuator systems in next-generation fighter platforms. ECHA regulatory timelines pressure NATO-aligned operators toward vegetable oil-based alternatives at airbases in central Italy. Milan Malpensa anchors commercial MRO fluid procurement with sensor-triggered consumption analytics penetration.
Aviation Fluid Market Competitive Landscape
Concentration sits with integrated oil majors possessing backward integration into synthetic ester feedstock production and multi-decade military supply relationships. The vendor base separates into three tiers: global energy conglomerates with full-spectrum aviation portfolios, regional refiners specializing in sustainable aviation fuel intermediates, and niche formulators serving specific MIL-SPEC certification tiers. Strategic moves center on capacity expansion in neopentyl polyol ester production and geographic extension of NATO-aligned military logistics contracts.
Among the integrated energy majors, Exxon Mobil Corporation and Shell plc exemplify the archetype of suppliers anchoring military supply chains through synthetic turbine oil portfolios and aviation fuel logistics networks. BP plc occupies a position representing specialization in hydraulic fluid formulations engineered for defense applications. These three entities collectively demonstrate how qualification barriers under MIL-PRF-23699 and SAE AS5780 specifications protect incumbent positions while constraining supply elasticity for new entrants.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP plc |
| Shell plc |
| TotalEnergies |
| Valero Energy Corporation |
| Phillips 66 |
| Neste |
| World Fuel Services |
| Others |
Value Network & Pricing Analysis
Multi-year sole-source agreements with defense contractors lock in synthetic ester supply access while capping price volatility for MIL-PRF-23699 certified formulations. These contract structures concentrate purchasing power with United States and NATO procurement offices, compressing margin negotiation leverage for qualified suppliers.
Pricing Analysis
MIL-PRF-23699 certification tiers dictate the pricing tier structure across synthetic turbine oil procurement. Three-tier pricing separates high-performance polyol ester formulations from standard diester grades and legacy mineral oil positions. Price differentiation rests on thermal stability benchmarks and FST certification levels rather than brand premium. Cost compression in hydraulic fluids is intensifying because EPA TSCA Section 6 assessments pressure phosphate ester formulations toward unproven bio-derived alternatives. Third-party MRO facilities exhibit highest price sensitivity due to fragmented purchasing volumes, while defense contractors demonstrate lowest sensitivity through multi-year budget commitments.
Supply Chain Analysis
Strategic stockpiling of neopentyl polyol ester feedstocks dominates military procurement, while commercial carriers favor just-in-time replenishment tied to predictive maintenance signals. Geographic supply concentrates in Germany and the United States for high-purity synthetic ester production, with secondary clustering in France for additive package formulation. Raw material dependencies include neopentyl glycol, polyol ester base stocks, and phosphate ester flame retardants. Single-source vulnerability characterizes specialty chemical producers in North Rhine-Westphalia. Distribution runs through integrated logistics providers at Atlanta Hartsfield-Jackson, Dallas-Fort Worth, and RAF Mildenhall.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward defense contractors consolidating procurement through prime vendor arrangements, fragmenting third-party MRO purchasing authority across high-velocity transaction networks.
For Market Incumbents: Secure backward integration into neopentyl polyol ester feedstock production to defend margin structures against specialty chemical supplier concentration. Lock in NATO-aligned military logistics contract extensions before qualification pathway revisions under SAE AS5780 tighten. Capacity addition in Germany protects supply access for European defense procurement offices facing REACH Annex XIV substitution timelines. For New Entrants and Emerging Players: Predictive maintenance analytics integration represents the most penetrable service-layer gap where incumbents under-serve third-party MRO facilities. Target sensor-triggered replenishment contracts at Singapore and Frankfurt maintenance hubs where purchasing fragmentation creates entry pathways. Bio-derived hydraulic fluid formulations for Italian and German NATO airbases offer fastest qualification traction under EPA phosphate ester pressure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated logistics providers controlling last-mile delivery to military airbases and commercial hubs. Long-term viability over the next decade favors suppliers with captive synthetic ester production and dual MIL-PRF-23699 and SAE AS5780 qualification tracks. Watch ASTM D4054 SAF blending infrastructure retrofit demand as inflection indicator for distribution asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Feedstock | Captive neopentyl polyol supply secures margin protection against German chemical producer concentration. |
| Dual Certification Investment | Parallel MIL-PRF-23699 and SAE AS5780 qualifications unlock defense and commercial procurement channels simultaneously. |
| Bio-Derived Hydraulic Formulation Development | Pre-qualified vegetable oil alternatives capture NATO retrofit contracts under EPA phosphate ester scrutiny. |
| Predictive Maintenance Platform Partnership | Sensor-triggered replenishment contracts concentrate purchasing authority with integrated logistics providers. |
| SAF Infrastructure Retrofit Positioning | ASTM D4054 blending compatibility creates first-mover advantage across existing distribution networks. |
Research Methodology
Operator-level perspectives from defense procurement officers, MRO facility managers, synthetic ester plant engineers, and aviation fuel logistics coordinators anchored the qualitative base. Primary interviews combined with secondary validation from FAA 14 CFR Part 43 regulatory filings, SAE International specification databases, EPA TSCA Section 6 toxicity assessments, and NATO supply chain documentation. Bottom-up volume modeling across product types and applications triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across alternative scenarios for military procurement acceleration and regulatory substitution timelines. Segmentation dimensions modeled include product type, application, end user, and service type, with additional stratification by certification tier and geographic procurement cluster. CAGRs were derived from trend extrapolation anchored in historical consumption patterns and projected fleet expansion programs. Industry-specific inputs encompassed synthetic ester production capacity utilization and predictive maintenance analytics penetration rates.
Forecasts assume regulatory continuity in FAA, EPA, and ECHA frameworks; material policy shifts would require re-modeling. Specific risks include REACH Annex XIV authorization acceleration for phosphate esters and unilateral MIL-PRF-23699 specification revisions. Revision becomes warranted when sustainable aviation fuel blending mandates cross infrastructure retrofit thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market