
 Aviation Satellite Antenna Systems Market | 2026-2036
Aviation Satellite Antenna Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Satellite Antenna Systems Market Analytics
RTCA DO-160 environmental qualification is bifurcating the supplier landscape into certified incumbents and emerging challengers. Honeywell International Inc. leverages its integrated avionics heritage to dominate embedded SATCOM architectures for commercial platforms. Viasat sustains technology leadership through high-throughput Ka-band payload designs that anchor its airline partnerships.
Aviation satellite antenna systems comprise airborne terminals that transmit and receive signals across Ku-band, Ka-band, and L-band frequencies, typically employing mechanically steered dishes or electronically scanned phased arrays to maintain satellite links during flight maneuvers. These systems enable passenger broadband, cockpit communications, and real-time weather data for flight safety. Phased array antennas are capturing disproportionate R&D investment as airlines seek drag-reducing fuselage integrations without radome protrusions. Ku-band antennas retain installed-base dominance across commercial retrofit programs where certification pathways are established. Military aviation end users are driving demand for multi-band terminals that fuse SATCOM with surveillance and weather monitoring functions.
The FAA mandates RTCA DO-160G and DO-178C software assurance for all civil antenna installations, while the EU AI Act and EASA certification requirements are extending compliance burdens for connectivity systems with embedded intelligence. Military procurement channels impose additional MIL-STD-810 and NSA Type-1 encryption standards that filter accessible vendor pools. Stakeholders must monitor evolving spectrum allocation rulings from the FCC and ITU, as Ka-band congestion threatens to reshape terminal architecture roadmaps and supplier competitive positions.
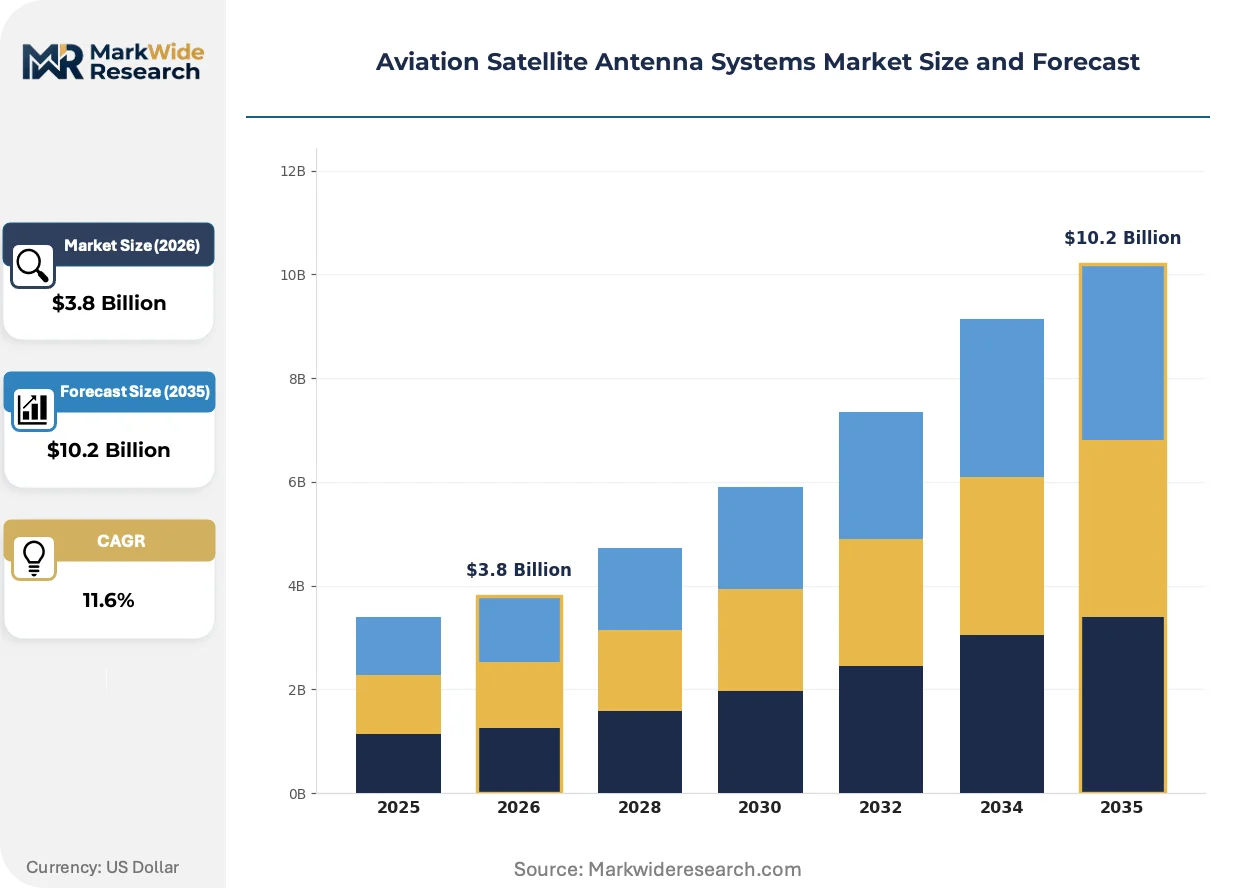
Market Dynamics
Phased array architectures are decomposing the installed base of mechanically steered Ku-band radomes, compressing supplier margins while opening fuselage-integration contracts to new entrants.
Growth Catalysts
- Commercial Airline Fleet Retrofit:Narrow-body carriers in the United States are mandating flat-panel SATCOM terminals to match passenger connectivity expectations on short-haul routes.
- FAA Certification Pathways:RTCA DO-160G environmental qualification creates predictable approval timelines that accelerate procurement cycles for qualified suppliers.
- Ka-band Throughput Expansion:High-capacity satellite payloads are enabling streaming-grade broadband that differentiates premium cabin service tiers.
Market Restraints
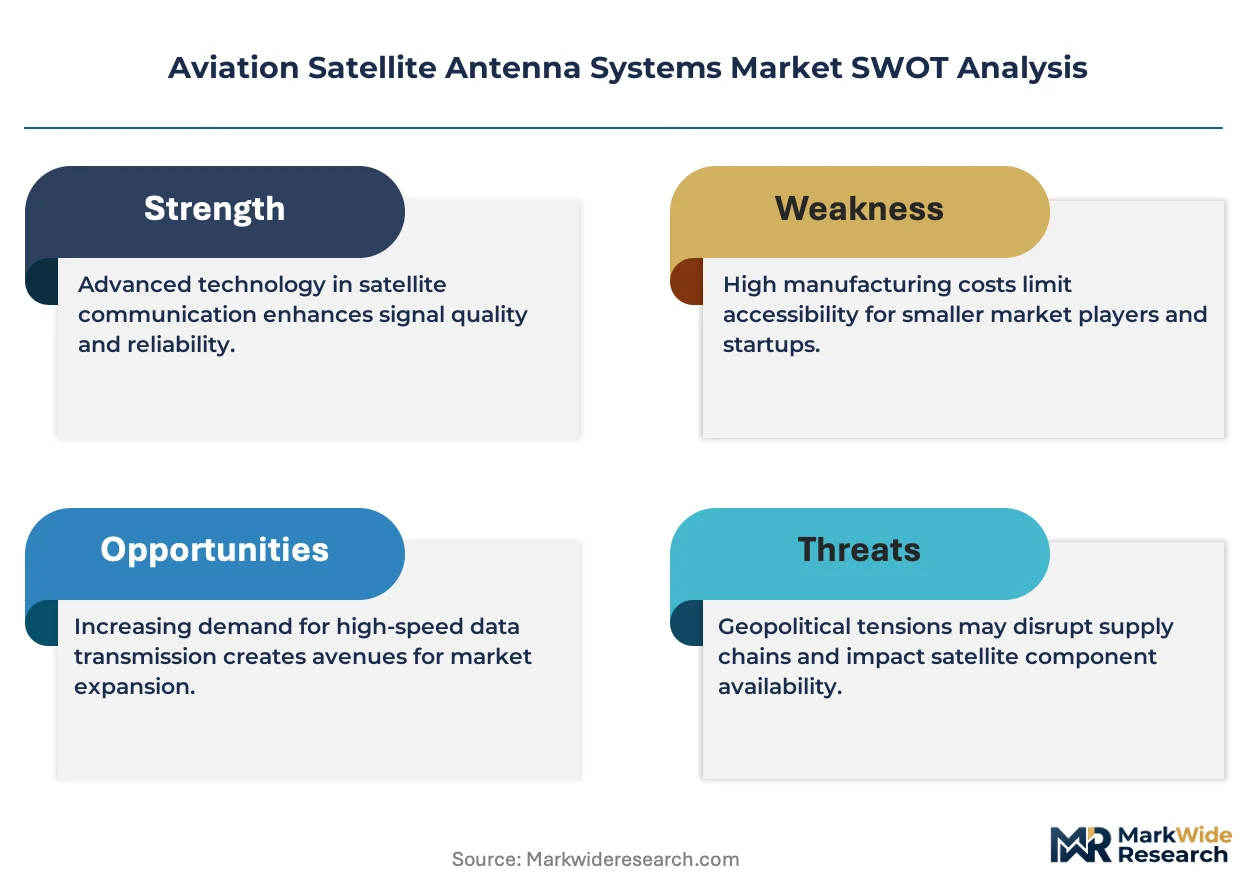
- Gallium Nitride Supply Concentration:RF semiconductor fabrication for phased array front-ends depends on foundries concentrated in East Asia, exposing lead times to geopolitical friction.
- Certification Cost Burden:RTCA DO-178C software assurance requirements impose seven-figure validation costs that filter small suppliers from civil aviation channels.
- Mechanical Steering Legacy:Ku-band dish antennas retain cost advantages for cargo and regional operators with lower bandwidth requirements, delaying full technology transition.
Strategic Opportunities
- Business Aviation Penetration:Fractional ownership fleets in the United States represent an under-served segment where drag-reducing phased arrays command premium pricing.
- Multi-band Military Convergence:Terminals fusing SATCOM with weather radar and surveillance functions capture defense procurement budgets through platform consolidation.
- EASA Streamlined Certification:The European regulator's phased array fast-track initiative reduces time-to-market for qualified suppliers entering EU airline retrofit programs.
Industry Challenges
- Phased Array Thermal Management:Power dissipation from dense transmit-receive modules requires advanced cooling architectures that extend design cycles.
- Cross-certification Complexity:Suppliers must maintain parallel FAA and EASA qualification teams, duplicating documentation and test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Satellite Antenna Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadband Antennas, Phased Array Antennas, Ku-Band Antennas, Ka-Band Antennas Technology: SATCOM, In-Flight Connectivity, Weather Monitoring, Surveillance Systems End User: Commercial Aviation, Military Aviation, Private Aviation, Cargo Aviation Installation: Embedded Systems, Retrofit Systems, Mobile Installations, Fixed Installations |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Viasat, Kymeta, The Boeing Company, Cobham, L3Harris Technologies, ThinKom, Astronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Satellite Antenna Systems Market Evolving Landscape
Aviation SATCOM terminals are transitioning from discrete hardware procurement to integrated connectivity platforms, embedding software-defined radio architectures that compress hardware refresh cycles.
Electronically scanned phased arrays are decomposing the market for mechanically steered antennas. These solid-state architectures eliminate gimbal maintenance and radome protrusion drag. Major United States carriers are adopting them for narrow-body retrofits at accelerated procurement pace. The technology is decomposing supplier revenue models from hardware sales toward recurring connectivity service contracts.
EASA certification requirements for embedded intelligence are extending compliance burdens under the EU AI Act. Connectivity systems with predictive maintenance algorithms now face algorithmic transparency mandates. European operators are responding by demanding supplier documentation packages that map decision pathways for regulatory audit trails.
Airline procurement departments are consolidating antenna decisions with connectivity service contracts, bundling hardware, bandwidth, and maintenance into unified agreements. This compresses the vendor base toward integrated platform providers. The shift is most visible among United States legacy carriers restructuring supplier panels to reduce integration complexity.
Aviation Satellite Antenna Systems Market Segmentation
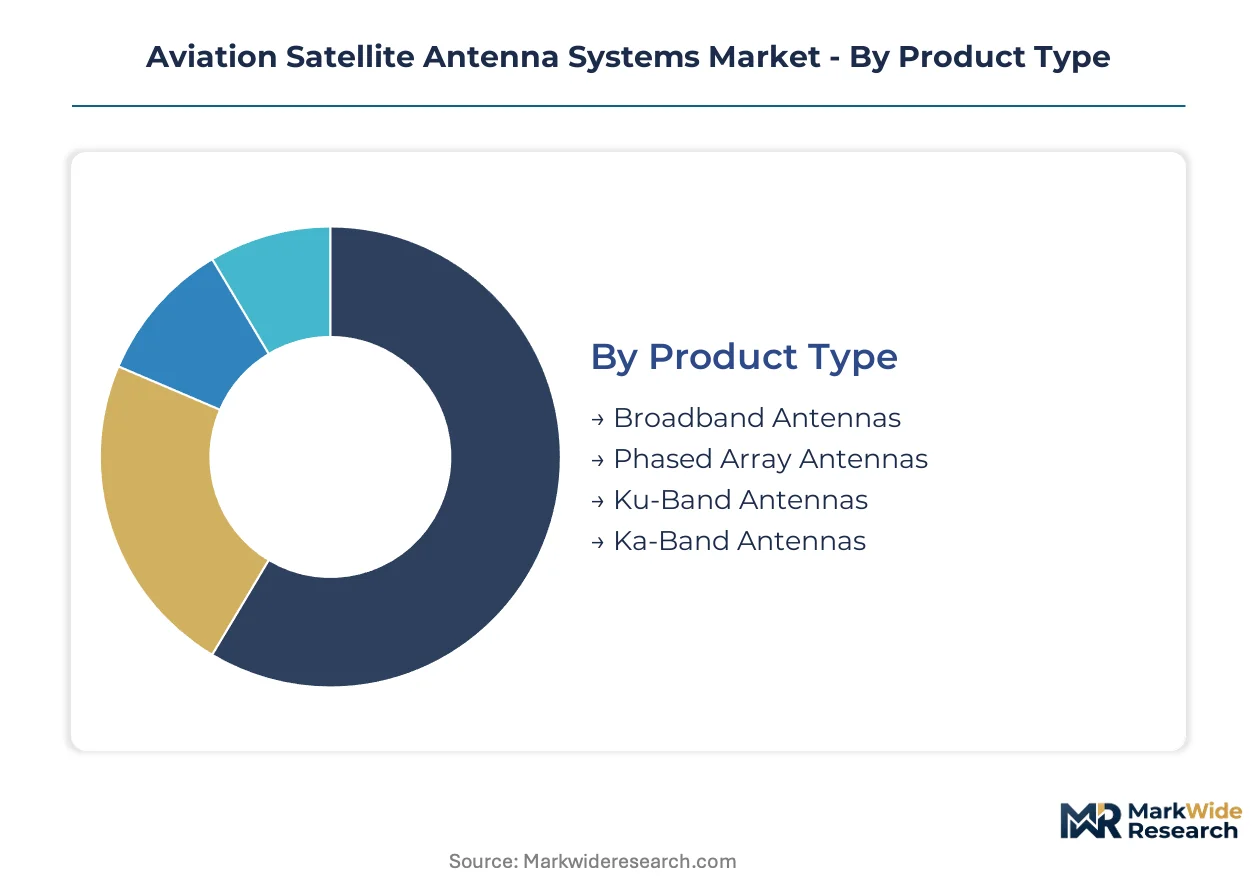
Segmentation in aviation satellite antenna systems reveals how procurement channels bifurcate between airframe-embedded OEM contracts and aftermarket retrofit programs. Each dimension—product architecture, application technology, operator type, and installation method—channels through distinct qualification requirements and margin structures.
Product Type:
Channel mix splits sharply between OEM airframe integrations and aftermarket retrofit procurement, with certification pathways determining supplier access.
- Phased Array Antennas:Solid-state electronically scanned architectures eliminate mechanical steering components and radome protrusions. United States narrow-body carriers are driving demand through fleet retrofit mandates that prioritize drag reduction and fuel efficiency.
- Broadband Antennas:High-throughput terminals aggregate Ku-band and Ka-band capabilities for streaming-grade passenger connectivity. Premium cabin service tiers on transcontinental routes concentrate procurement, with airlines bundling hardware into long-term connectivity service contracts.
- Ku-Band Antennas:Mechanically steered dish systems retain cost advantages for regional operators with established certification pathways.
- Ka-Band Antennas:High-capacity terminals leverage HTS satellite payloads for bandwidth-intensive applications requiring low latency.
Ku-band antennas dominate installed base across commercial retrofit programs. Phased array architectures are where expansion concentrates.
Technology:
Application maturity varies sharply, with SATCOM infrastructure commanding integrated platform investments while surveillance functions remain discrete procurements.
- SATCOM:Core signal transmission and reception infrastructure enabling voice, data, and broadband services across all flight phases. Military aviation procurement channels are driving multi-band terminal convergence that fuses communications with sensor functions.
- In-Flight Connectivity:Passenger broadband and crew communications systems with software-defined radio architectures. Commercial airlines in the United States are consolidating antenna decisions with bandwidth service contracts, compressing vendor bases toward integrated providers.
- Weather Monitoring:Real-time meteorological data reception for flight safety and route optimization.
- Surveillance Systems:Airborne early warning and reconnaissance data links for defense platforms.
SATCOM anchors technology investment. In-flight connectivity is climbing the fastest as airlines restructure supplier panels.
End User:
Operator type dictates specification intensity, with military procurement imposing encryption and environmental standards that filter accessible vendor pools.
- Commercial Aviation:Scheduled passenger carriers operating narrow-body and wide-body fleets with standardized connectivity service tiers. Major United States legacy carriers are retrofitting entire narrow-body fleets with flat-panel SATCOM terminals to match passenger expectations on short-haul routes.
- Military Aviation:Defense platforms requiring MIL-STD-810 environmental qualification and NSA Type-1 encryption for secure communications. Multi-band terminal convergence is capturing procurement budgets through platform consolidation that merges SATCOM with weather and surveillance functions.
- Private Aviation:Fractional ownership and charter fleets where drag-reducing phased arrays command premium pricing.
- Cargo Aviation:Freight operators prioritizing cost-efficient Ku-band solutions with lower bandwidth requirements.
Commercial aviation commands volume concentration. Military aviation is where specification premiums expand fastest.
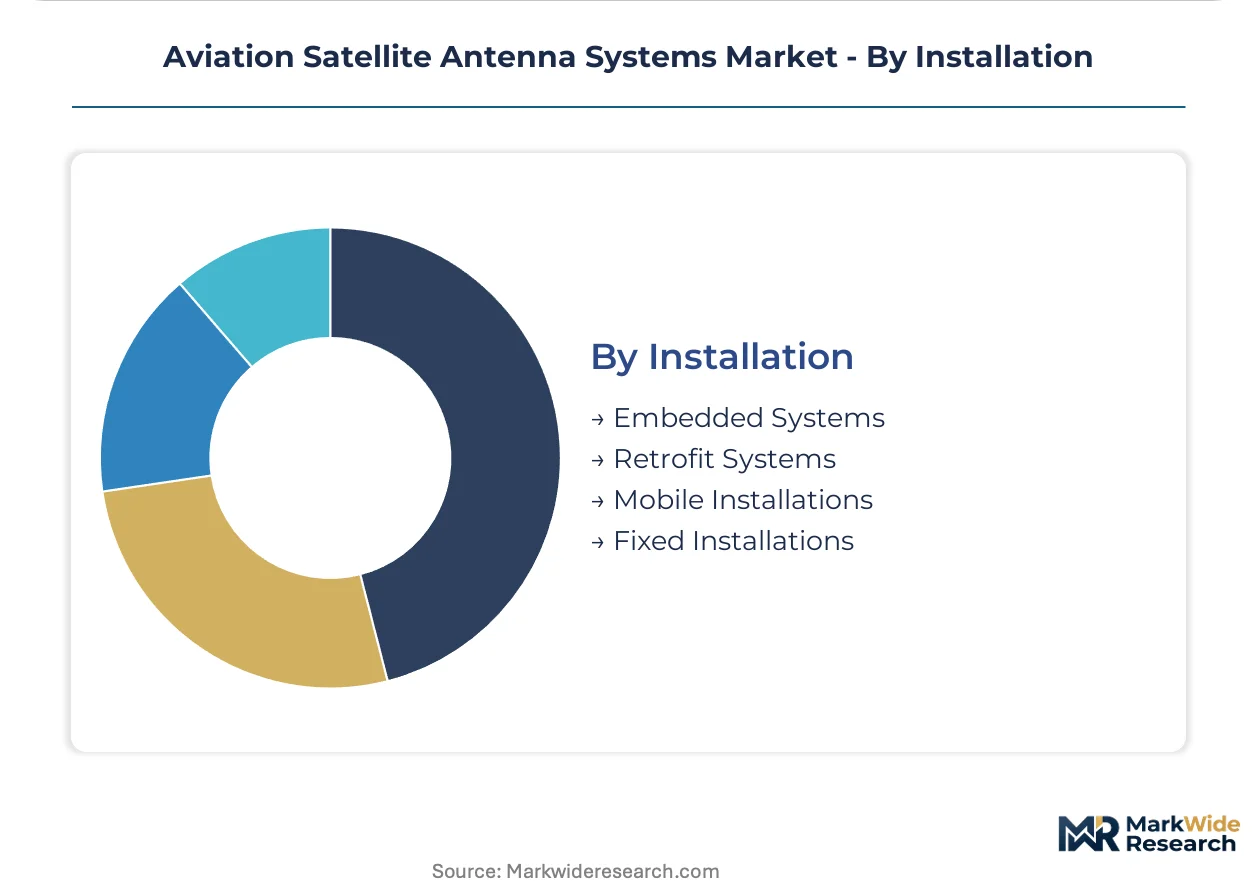
Installation:
Installation method determines margin structure, with embedded OEM contracts locking in long-term supplier relationships while retrofits open competitive rebidding.
- Retrofit Systems:Aftermarket installations on in-service aircraft requiring STC approvals and minimal airframe modification. United States narrow-body fleet mandates are accelerating procurement cycles for qualified suppliers with established FAA certification pathways.
- Embedded Systems:Factory-integrated antennas specified during airframe production with multi-year supplier agreements. Honeywell leverages integrated avionics heritage to dominate this channel for commercial platforms through cockpit connectivity bundling.
- Mobile Installations:Rapidly deployable terminals for special mission and temporary communications requirements.
- Fixed Installations:Permanent ground-based aviation communications infrastructure supporting fleet operations.
Embedded systems dominate OEM channel value. Retrofit systems are gaining share fastest as fleet-wide connectivity mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kansas City Aviation Center and Dallas-Fort Worth International Airport anchor North American demand concentration for aviation satellite antenna systems, with transcontinental passenger routes driving retrofit procurement cycles.
United States
Major legacy carriers are retrofitting narrow-body fleets with flat-panel SATCOM terminals to match passenger connectivity expectations on short-haul routes. The FAA's RTCA DO-160G environmental qualification creates predictable approval timelines that accelerate procurement for qualified suppliers. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate airline procurement headquarters and MRO facilities where installation contracts concentrate.
Germany
Lufthansa Group's fleet standardization programs drive demand for embedded OEM antenna systems on new airframe deliveries. EASA certification requirements for phased array installations extend compliance burdens under EU AI Act algorithmic transparency mandates. Hamburg and Munich aerospace clusters host major MRO operations where retrofit installations accelerate.
China
Domestic carriers are expanding in-flight connectivity fleets to meet rising passenger expectations on high-density trunk routes. MIIT spectrum allocation rulings for Ka-band usage reshape terminal architecture roadmaps for indigenous suppliers. Shanghai and Beijing metropolitan regions concentrate COMAC assembly operations and airline headquarters where procurement decisions centralize.
United Kingdom
British Airways and Virgin Atlantic fleet renewal programs prioritize drag-reducing phased array architectures for fuel efficiency gains. CAA alignment with EASA certification pathways streamlines approval processes for suppliers qualified under RTCA standards. London Heathrow and Gatwick airport vicinities concentrate connectivity service provider operations and installation capacity.
Japan
ANA and JAL are retrofitting domestic narrow-body fleets with SATCOM terminals to differentiate premium cabin service tiers. METI industrial policy supports indigenous phased array development through targeted R&D consortia. Nagoya and Tokyo aerospace manufacturing clusters concentrate avionics integration facilities where antenna system testing occurs.
Aviation Satellite Antenna Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification-qualified and emerging technology tiers. The supplier landscape bifurcates sharply between RTCA DO-160G certified incumbents with established FAA pathways and challengers pursuing EASA fast-track initiatives. Three archetypes dominate: integrated avionics conglomerates, satellite payload specialists, and phased array technology pure-plays. Competitive moves concentrate on strategic partnerships for bandwidth service bundling and vertical integration into RF semiconductor fabrication.
Within the integrated avionics tier, Honeywell International Inc. and Collins Aerospace exemplify scale-driven positions leveraging cockpit connectivity bundling. Viasat anchors the satellite payload specialist archetype through high-throughput Ka-band designs. Among emerging technology pure-plays, Kymeta and ThinKom occupy positions representing electronically scanned phased array innovation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Viasat |
| Kymeta |
| The Boeing Company |
| Cobham |
| L3Harris Technologies |
| ThinKom |
| Astronics Corporation |
| Others |
Value Network & Pricing Analysis
Gallium Nitride foundry migration from legacy silicon processes redraws procurement geography toward East Asian semiconductor clusters while compressing RF front-end pricing economics across phased array tiers. This substrate transition simultaneously elevates certification-grade antenna premiums and erodes margins for mechanically steered Ku-band alternatives.
Pricing Analysis
Three-tier pricing structure across RTCA DO-160G certified, EASA fast-track qualified, and uncertified development tiers stratifies supplier positioning. Price differentiation hinges on FAA certification completion and GaN RF module integration depth. Pricing pressure stems from airline fleet procurement consolidation into bundled connectivity service contracts. Regional cargo operators exhibit highest price sensitivity, while fractional ownership fleets accept premium positioning for drag-reducing phased arrays.
Supply Chain Analysis
Inventory cycles for GaN RF semiconductors extend to twenty-six weeks, constraining phased array production scheduling. Supply concentrates in Taiwan, South Korea, and Japan for compound semiconductor fabrication. Raw material dependencies span GaN-on-SiC wafers, high-frequency laminates, and precision gimbal motors. Single-source vulnerability concentrates in East Asian foundry capacity. Distribution runs through airframe OEM specification channels and aftermarket STC installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where RTCA DO-160G certification entrenchment creates switching costs that lock airline procurement panels. Network effects concentrate among integrated avionics providers bundling cockpit connectivity with passenger broadband.
For Market Incumbents: Compound certification advantages by accelerating EASA fast-track qualification for dual-approval positioning. Deepen backward integration into GaN RF module fabrication to insulate margins from foundry concentration. Threat exposure centers on emerging phased array pure-plays leveraging EASA streamlined pathways.
For New Entrants and Emerging Players: EASA phased array fast-track initiative offers the most penetrable entry vector for EU airline retrofit procurement. Target business aviation fractional ownership fleets where drag-reducing architectures command premium pricing absent fleet-scale volume requirements. Go-to-market positioning should emphasize software-defined radio architectures enabling rapid frequency reconfiguration.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated avionics conglomerates with established FAA pathway dominance and cockpit connectivity bundling leverage. Long-term viability favors suppliers controlling both terminal hardware and bandwidth service contracts. Signal to monitor: airline procurement panel restructuring toward single-source integrated platform providers.
| Strategic Initiative | Industry Significance |
|---|---|
| RTC DO-160G Certification Acceleration | FAA qualification locks airline procurement panels against emerging challengers. |
| GaN RF Module Backward Integration | In-house semiconductor fabrication insulates margins from East Asian foundry concentration. |
| EASA Fast-Track Qualification | European streamlined approval reduces time-to-market for qualified suppliers. |
| Connectivity Service Contract Bundling | Unified hardware-bandwidth-maintenance agreements compress vendor bases. |
| Software-Defined Radio Architecture | Programmable frequency agility extends terminal lifecycle without hardware refresh. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Primary fieldwork engaged avionics engineering directors, airline procurement executives, MRO installation managers, and FAA certification specialists. Secondary sources encompassed RTCA documentation, EASA airworthiness directives, FCC spectrum allocation rulings, and supplier SEC disclosures. Bottom-up terminal shipment modeling triangulated against top-down airline fleet connectivity penetration estimates.
Sensitivity analysis tested forecast robustness across GaN supply disruption scenarios and certification timeline variations. Segmentation dimensions encompassed product architecture, frequency band, installation method, and operator type. CAGRs derived from logistic diffusion modeling of fleet retrofit penetration curves. Industry-specific inputs included HTS satellite capacity expansion schedules and airline passenger connectivity satisfaction benchmarks.
Decision-makers should treat outputs as directional under assumptions of stable FAA-EASA regulatory alignment and continued HTS payload deployment; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Launch Vehicle Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
North America Mobile Satellite Services Market
Satellite
Satellite Data Analytics Services Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Europe Small Satellite Market
Satellite
Satellite Imaging Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Global Satellite Propulsion System Market
Satellite
Satellite Link Emulator Market
Satellite
Indonesia Satellite Communications Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
South Korea Satellite-Based Earth Observation Market