
 Crystalline Polyethylene Terephthalate Market | 2026-2036
Crystalline Polyethylene Terephthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Crystalline Polyethylene Terephthalate Market Analysis
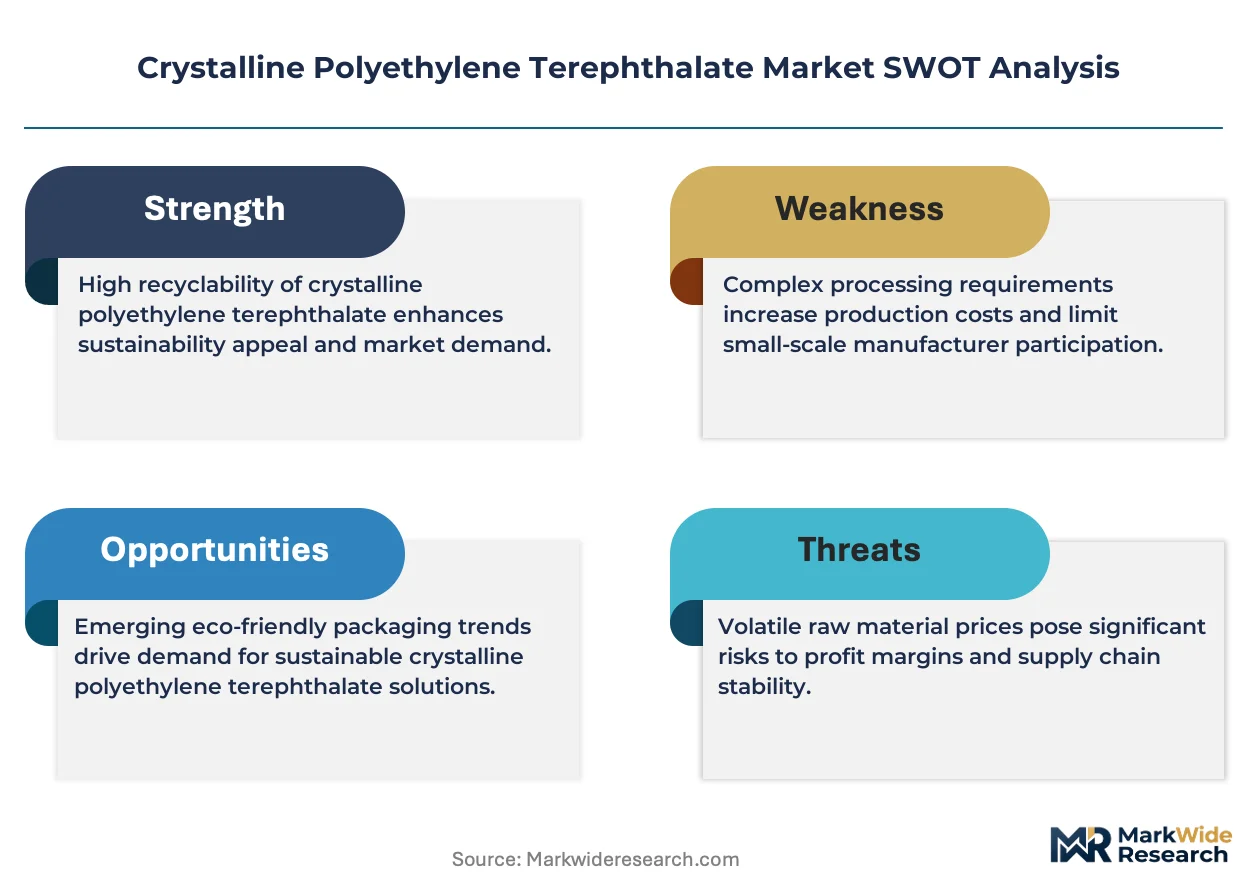
Recycled-content verification and bottle-to-bottle reprocessing is rewriting margin allocation across the value chain. Indorama Ventures leverages its integrated PET resin and recycling footprint to capture value from closed-loop supply agreements. SABIC anchors its position through high-purity crystalline PET output for premium beverage and pharmaceutical packaging. NOVAPET S.A. specializes in food-grade recycled chip production, differentiating its offering against virgin-resin competitors.
Crystalline polyethylene terephthalate is a semi-crystalline thermoplastic polyester produced through solid-state polymerization, exhibiting high tensile strength, optical clarity, and barrier properties against moisture and gases. Manufacturers employ melt-phase polymerization followed by solid-stating to achieve the crystallinity required for carbonated beverage bottles and thermoformed food trays. Bottles command the largest volume share within product type segments, though sheet formats for thermoformed packaging gain traction as retailers demand thinner-gauge, higher-clarity alternatives. Packaging dominates application-level demand, while the Automotive segment occupies a narrower but higher-margin niche for under-hood electrical components and interior trim where dimensional stability under thermal cycling matters.
FDA food-contact regulations and EU REACH chemical safety standards govern monomer purity and additive use, directly influencing which resin grades qualify for export into North American and European downstream markets. China's SAMR enforces GB standards for food-packaging plastics, creating a parallel compliance pathway that domestic producers like Reliance Industries navigate for Asia-Pacific distribution. Stakeholders must monitor evolving extended-producer-responsibility frameworks and recycled-content mandates, as these policy instruments will determine which crystalline PET supply configurations retain market access across major consumption zones.
Market Dynamics
Closed-loop recycling mandates and solid-state polymerization efficiency gains are compressing the cost gap between virgin and food-grade recycled crystalline PET, forcing resin producers to reconfigure feedstock strategies and capital allocation.
Growth Catalysts
- EU REACH chemical safety standards:Stringent monomer purity requirements for food-contact applications are elevating technical barriers, favoring producers with advanced solid-stating capabilities and certified supply chains.
- Carbonated beverage bottling:Major bottlers are converting lightweight bottle formats to crystalline PET for improved barrier performance and reduced transport costs, sustaining volume pull-through.
- China's blow-molding infrastructure expansion:Domestic resin capacity additions and downstream processing investments are accelerating regional self-sufficiency and export competitiveness.
Market Restraints
- Ethylene glycol feedstock volatility:Purified terephthalic acid and ethylene glycol prices fluctuate with crude oil and paraxylene markets, compressing resin margins unpredictably.
- Asian resin supply concentration:Production gravity in China and Southeast Asia creates exposure to regional energy policy shifts and port logistics disruptions.
- Polypropylene substitution in hot-fill applications:Enhanced PP barrier technologies and lower thermal processing costs threaten crystalline PET in certain beverage segments.
Strategic Opportunities
- India's FSSAI food-contact compliance pathway:Evolving domestic standards for recycled-content packaging create first-mover advantages for integrated resin-to-recycling operators.
- Pharmaceutical blister packaging:High-purity crystalline PET formats for moisture-sensitive drug delivery remain underpenetrated relative to PVC and aluminum alternatives.
- EU Green Deal recycled-content mandates:Binding targets for post-consumer recycled material in single-use packaging will privilege suppliers with verified bottle-to-bottle reprocessing capabilities.
Industry Challenges
- Food-grade rPET certification timelines:EFSA and FDA novel food-contact notifications require 18-24 month validation cycles, delaying commercialization of new recycling streams.
- Solid-state polymerization reactor scarcity:Specialized equipment for achieving required crystallinity and intrinsic viscosity faces 14-18 month order backlogs, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystalline Polyethylene Terephthalate Market |
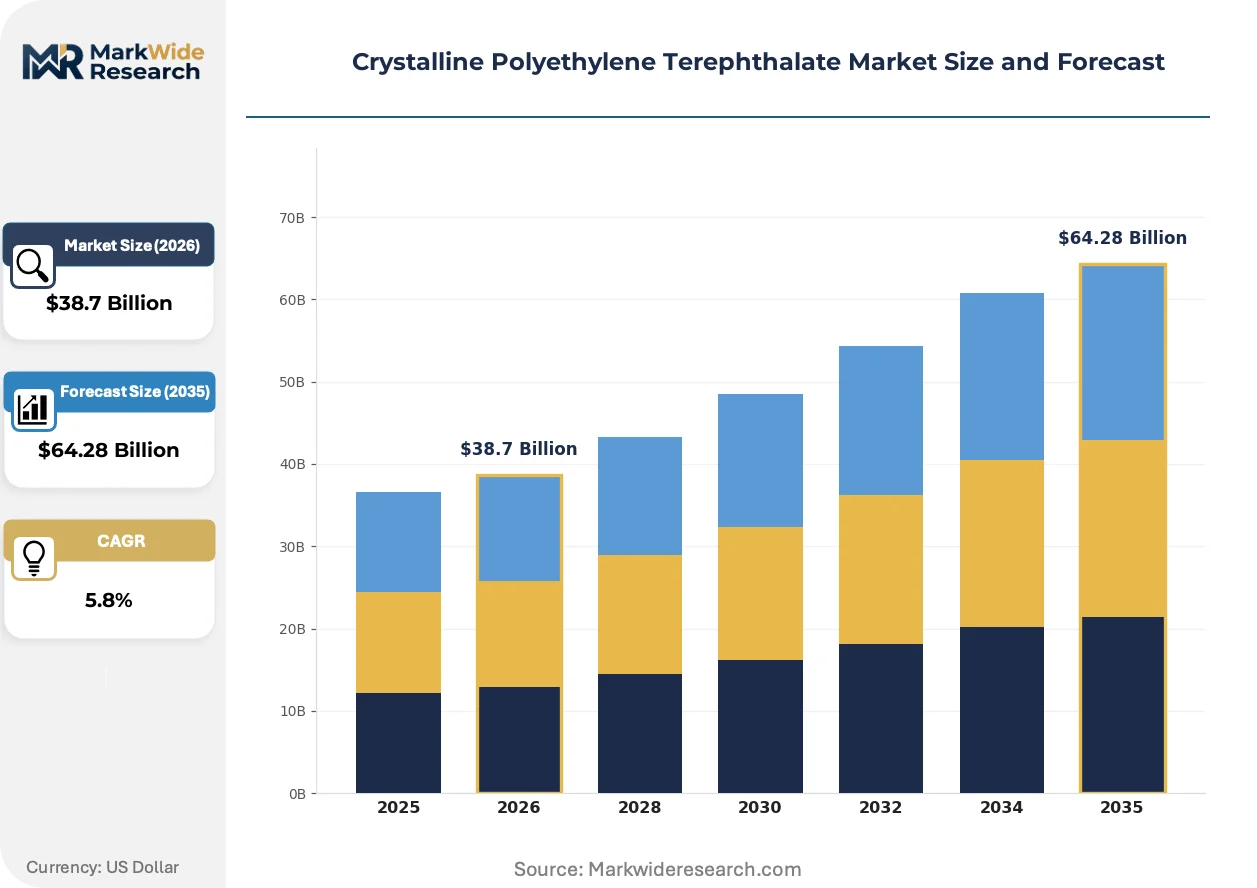
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Fiber, Sheet, Bottles Application: Packaging, Textiles, Automotive, Electronics End User: Food & Beverage, Consumer Goods, Healthcare, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Importers |
| Companies Covered | Indorama Ventures Public Company Limited, Mitsubishi Chemical Group, Amcor plc, Pactiv Evergreen Inc., Reliance Industries Limited, SABIC, NOVAPET S.A., Teijin Limited, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystalline Polyethylene Terephthalate Market Emerging Trajectories
Process intensification and regulatory compression are converging to eliminate marginal virgin-resin capacity while rewarding integrated producers with captive recycling feedstocks and advanced purification assets.
Advanced glycolysis and methanolysis depolymerization technologies are collapsing the quality differential between mechanically recycled and virgin crystalline PET resin. Beverage brand owners with net-zero commitments are specifying chemically recycled content for premium bottle lines, forcing traditional resin suppliers to license or acquire these capabilities to retain shelf-space access. This technology shift is collapsing the historical price premium for virgin-grade material in North American and European procurement contracts.
EU REACH Annex XVII restrictions on intentionally added microplastics are extending to synthetic polymer pellets and powder handling, compelling resin producers to invest in closed conveying systems and dust suppression infrastructure. The industrial consequence is elevated capital intensity for new entrant greenfield projects, particularly in Baltic and Eastern European production zones. Pharmaceutical packaging grades face heightened scrutiny under the EU Medical Device Regulation, driving substitution toward pre-validated, audit-documented supply chains.
Retailer-led sustainable packaging scorecards are reshaping procurement evaluation criteria for bottled water and soft drink converters. Walmart's Project Gigaton and Tesco's packaging sustainability indices now weight recycled-content percentage and carbon footprint above unit price in supplier selection, displacing traditional spot-market purchasing in North American and UK beverage supply chains. This behavioral shift is most visible in Germany, where discount retailers have accelerated rPET adoption to meet corporate binding targets ahead of regulatory deadlines.
Crystalline Polyethylene Terephthalate Market Segmentation
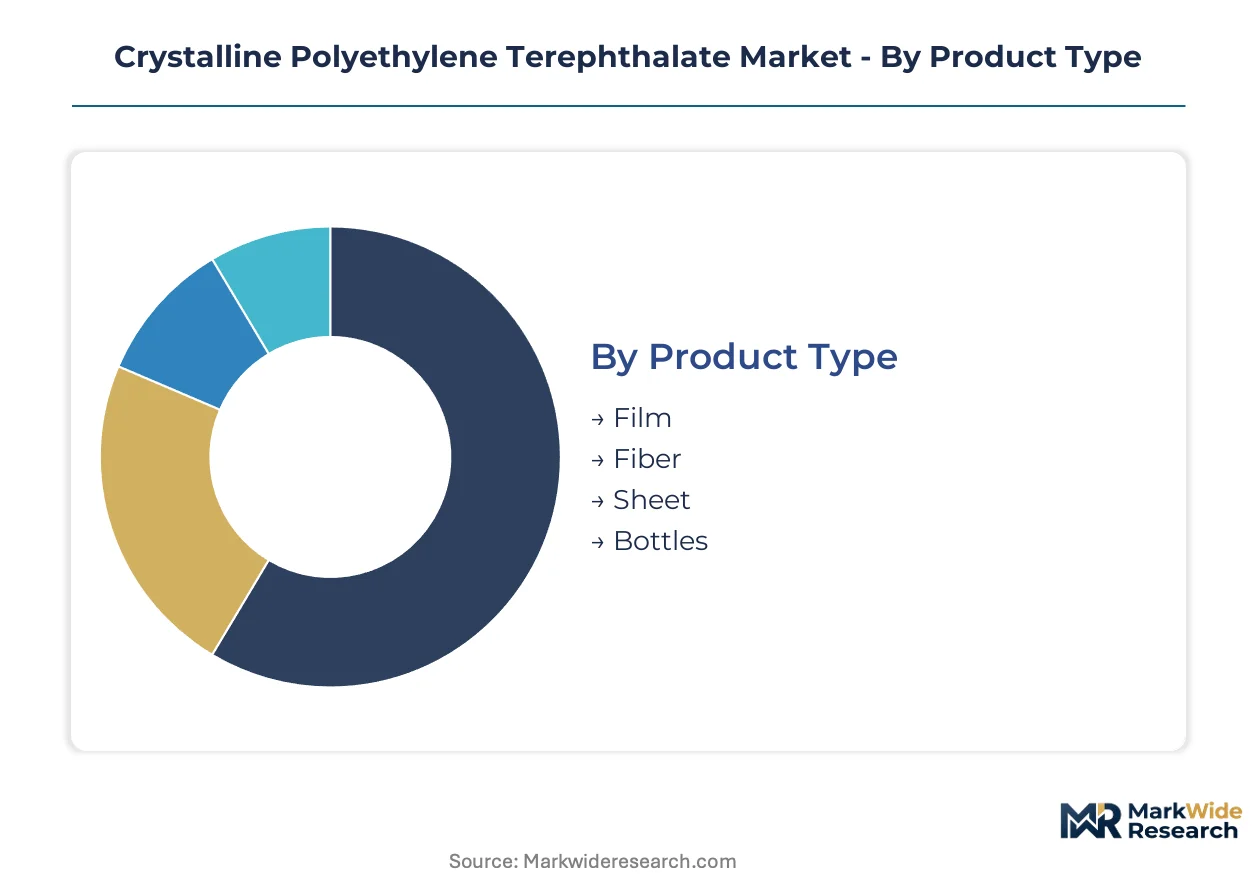
Crystalline PET grades vary sharply in crystallinity, intrinsic viscosity, and barrier specifications, forcing converters to match material properties precisely to thermal and mechanical stress requirements. Segmentation clarity determines procurement strategy as food-contact certifications and recycled-content mandates fragment supply availability across end-use categories.
Product Type:
Mature formats dominate volume flows while emerging configurations capture premium positioning through performance specialization.
- Bottles:Solid-state polymerization yields high-IV crystalline PET with superior carbonation retention and drop resistance. Carbonated beverage bottlers in China and Germany specify lightweight preform designs that reduce resin consumption per unit while maintaining burst pressure ratings.
- Sheet:Extruded crystalline PET sheet serves thermoformed food trays and blister packs requiring deep-draw capability without stress whitening. Retailers in the UK and France are accelerating adoption for ready-meal packaging to meet EU Green Deal recycled-content thresholds.
- Film:Biaxially oriented crystalline PET film delivers optical clarity and dimensional stability for flexible packaging laminates.
- Fiber:Textile-grade crystalline PET fiber exhibits high tenacity and low moisture regain for industrial yarn and staple applications.
Bottles retain volume leadership; Sheet holds the steepest expansion curve as thermoforming converters pivot toward thinner-gauge, higher-recycled-content formats.
Application:
Application mix tracks directly with regulatory intensity, where food-contact approvals and automotive thermal specifications create divergent qualification pathways.
- Packaging:Encompasses rigid bottles, trays, and films for food, beverage, and consumer goods protection. FDA and EFSA food-contact notifications govern monomer purity thresholds, while EU REACH Annex XVII restricts additive migration into fatty food simulants.
- Automotive:Under-hood electrical connectors and interior trim components exploit crystalline PET's dimensional stability across thermal cycling from -40°C to 150°C. German and Japanese OEMs specify glass-filled grades for connector housings to replace costlier polyamide formulations.
- Textiles:Industrial fiber applications include tire cord, seatbelt webbing, and geotextile substrates.
- Electronics:Film substrates for capacitors and display components leverage dielectric strength and moisture resistance.
Packaging commands absolute volume dominance; Automotive generates the highest margin per kilogram despite narrower offtake.
End User:
End-user concentration reflects the penetration of extended-producer-responsibility schemes and the differential pace of recycled-content mandate adoption.
- Food & Beverage:Bottled water and carbonated soft drink producers represent the foundational demand base. China's SAMR enforces GB standards for food-contact plastics, creating compliance complexity for imported resin grades that domestic producers like Reliance Industries navigate more efficiently.
- Healthcare:Pharmaceutical blister packs and medical device packaging require ultra-high purity with extractables documentation. The EU Medical Device Regulation imposes audit-documented supply chains that privilege pre-validated resin sources over spot-market procurement.
- Consumer Goods:Personal care and household product containers drive demand for clarified, color-stable grades.
- Industrial:Strapping, film, and fiber applications serve logistics and manufacturing sectors with less stringent purity requirements.
Food & Beverage anchors procurement volumes; Healthcare is climbing fastest as pharmaceutical packaging specifications tighten beyond PVC and aluminum incumbent capabilities.
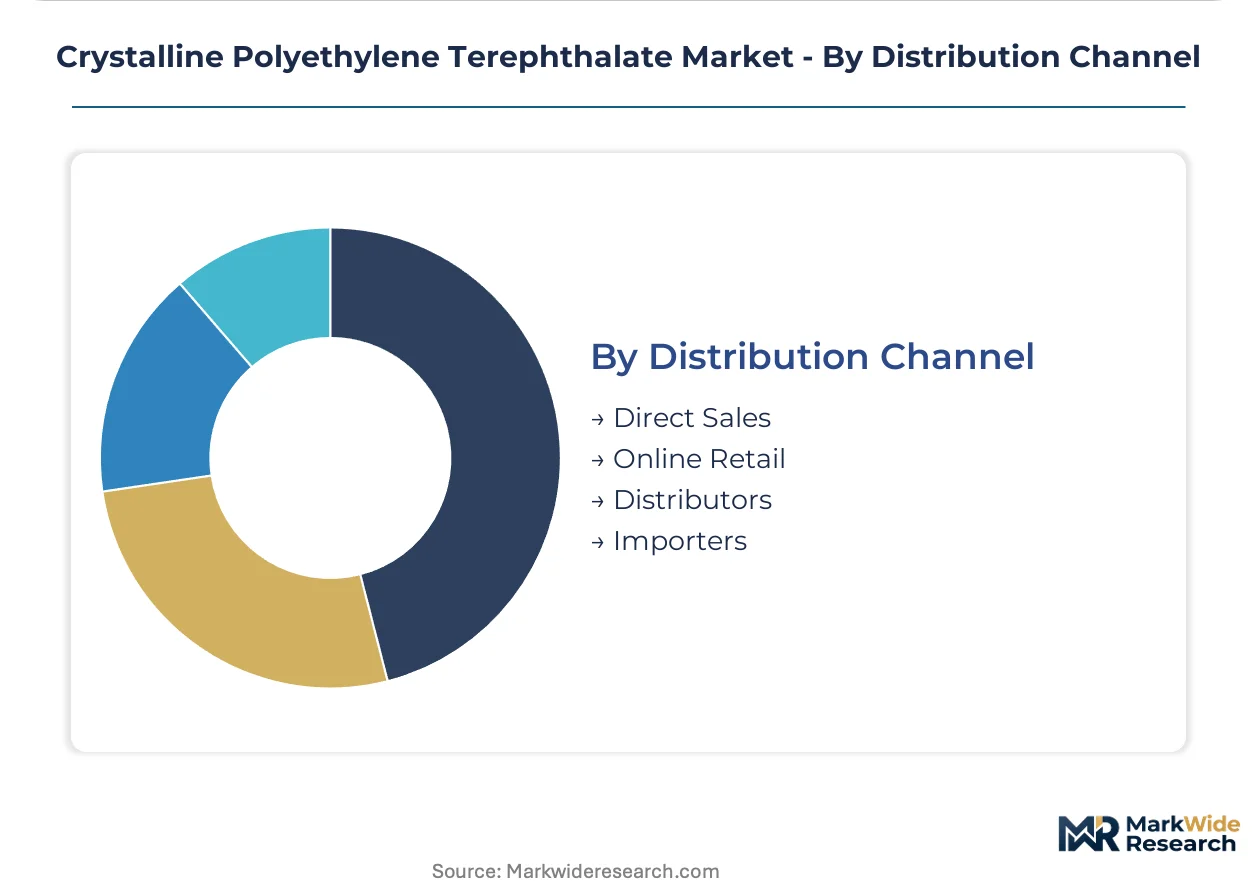
Distribution Channel:
Channel structure reveals the tension between converter integration and the need for technical service support in specialized grades.
- Distributors:Regional stocking distributors provide technical service and just-in-time delivery for small-to-mid converters lacking silo storage capacity. Distributor networks concentrate in the US Midwest and Germany's Rhine-Ruhr industrial corridor to serve blow-molding and thermoforming clusters.
- Direct Sales:Major resin producers negotiate frame contracts directly with multinational bottlers and packaging converters. Indorama Ventures and SABIC deploy technical service engineers to customer preform and sheet extrusion lines to optimize processing parameters.
- Online Retail:Emerging channel for specialty film and fiber samples, though bulk resin remains physically delivered.
- Importers:Trading houses bridge supply gaps in markets lacking domestic solid-state polymerization capacity.
Distributors retain channel leadership for mid-tier converters; Direct Sales is expanding most quickly as major bottlers consolidate procurement under strategic supplier partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin capacity clusters in China, Germany, the United States, and India, with each geography responding to distinct regulatory pressures and downstream packaging demand patterns.
China
Blow-molding infrastructure expansion in Jiangsu and Zhejiang provinces absorbs domestic resin output for carbonated beverage bottles. SAMR enforces GB standards for food-contact plastics, creating compliance complexity for imported grades. The Yangtze River Delta hosts the densest concentration of solid-state polymerization reactors serving both domestic bottlers and export markets.
Germany
Discount retailers accelerate rPET adoption to meet corporate binding targets ahead of EU Green Deal deadlines. ECHA REACH Annex XVII restrictions on microplastic pellet handling elevate capital intensity for new resin handling facilities. The Rhine-Ruhr industrial corridor anchors distributor networks serving thermoforming converters across Western Europe.
United States
Carbonated beverage bottlers specify lightweight preform designs to reduce resin consumption per unit. FDA food-contact notifications govern monomer purity thresholds for domestic and export-qualified grades. The US Midwest concentrates regional stocking distributors serving small-to-mid blow-molding operations lacking silo storage capacity.
India
Domestic resin producers navigate FSSAI evolving standards for recycled-content packaging to capture first-mover positioning. Reliance Industries leverages integrated resin-to-recycling operations for Asia-Pacific distribution. Gujarat and Maharashtra host expanding blow-molding clusters serving both local beverage markets and export channels.
Japan
Automotive OEMs specify glass-filled crystalline PET grades for under-hood electrical connectors replacing polyamide formulations. METI industrial standards shape material qualification pathways for high-thermal-stability applications. The Chubu region around Nagoya concentrates precision molding operations serving Toyota and Honda supply chains.
Crystalline Polyethylene Terephthalate Market Vendor Landscape
Integrated petrochemical conglomerates and specialized recycling operators split the market between scale-driven virgin resin production and circular-economy positioning. The structure tilts toward consolidation at the resin synthesis tier while fragmenting across mechanical recycling and specialty compounding. Three archetypes dominate: Asian petrochemical majors with backward integration into paraxylene feedstocks, European specialists in food-grade rPET certification, and North American packaging converters with captive resin offtake agreements. Capacity expansion and technology licensing constitute the dominant competitive moves, with solid-state polymerization reactor scarcity constraining greenfield entry.
Among Asian petrochemical conglomerates, Reliance Industries and Mitsubishi Chemical Group exemplify the integrated archetype combining captive PTA production with downstream resin and recycling assets. SABIC anchors the high-purity specialty tier through certified pharmaceutical-grade output. NOVAPET S.A. occupies a distinct position within the European recycling specialist tier, representing the bottle-to-bottle reprocessing capability that EU Green Deal mandates privilege.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Mitsubishi Chemical Group |
| Amcor plc |
| Pactiv Evergreen Inc. |
| Reliance Industries Limited |
| SABIC |
| NOVAPET S.A. |
| Teijin Limited |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity warnings from Jiangsu province solid-state polymerization reactors are forcing crystalline PET producers into aggressive contract pricing to maintain utilization rates, compressing margins for non-integrated operators while rewarding those with captive PTA feedstock positions.
Pricing Analysis
After-sales technical service contracts for blow-molding parameter optimization now generate margin premiums exceeding base resin sales. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial-grade crystalline PET separates premium SABIC pharmaceutical output from standard beverage-grade Indorama supply. Cost compression in food-contact recycled chip is intensifying because chemically recycled content commands price parity with virgin resin in EU procurement. Small-to-mid converters in the US Midwest exhibit highest price sensitivity, while pharmaceutical packers accept substantial premiums for documented extractables compliance.
Supply Chain Analysis
Purified terephthalic acid and ethylene glycol feedstock availability hinges on paraxylene cracking economics in China, Saudi Arabia, and India. Solid-state polymerization reactor fabrication draws from specialized German and Japanese equipment suppliers facing 14-month order backlogs. Single-source vulnerability concentrates in Yangtze River Delta port logistics for export-qualified resin grades. Distribution runs through regional stocking distributors in Germany's Rhine-Ruhr corridor and the US Midwest serving thermoforming clusters lacking silo infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state polymerization reactor scarcity and 18-month EFSA food-contact certification timelines have created a bottleneck where only producers with pre-qualified assets and regulatory dossiers can capture expanding EU recycled-content mandates.
For Market Incumbents: Insulate margin positions by securing captive methanolysis depolymerization licenses before chemical recycling technology premiums collapse. Lock in long-term offtake with multinational bottlers converting to lightweight preform designs, as polypropylene substitution threats intensify in hot-fill beverage segments. Prioritize backward integration into PTA production to buffer ethylene glycol feedstock volatility. For New Entrants and Emerging Players: Pursue pharmaceutical blister packaging white-space where PVC and aluminum incumbents face EU Medical Device Regulation compliance gaps. India's FSSAI evolving standards for recycled-content packaging offer the most penetrable regulatory pathway for integrated resin-to-recycling operations. Lead with technical service engineering support to differentiate against commodity virgin-resin suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemically recycled crystalline PET sub-segments as EU Green Deal mandates accelerate bottle-to-bottle reprocessing infrastructure deployment. Target acquisition archetypes combine verified food-grade rPET certification with existing solid-state polymerization reactor assets. Monitor EFSA novel food-contact notification approval velocities as the key inflection signal for recycled-content supply viability.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds solid-state polymerization reactors in Jiangsu to capture China's blow-molding infrastructure growth. |
| Backward Integration | Captive PTA production buffers Reliance Industries against paraxylene price volatility in Asia-Pacific markets. |
| Long-term Supply Agreement | Closed-loop contracts with Coca-Cola and PepsiCo secure volume for Indorama's integrated recycling footprint. |
| Joint Venture | NOVAPET's bottle-to-bottle partnerships with EU discount retailers accelerate rPET adoption ahead of mandate deadlines. |
| Green Manufacturing Transition | Chemically recycled content licensing allows Eastman to meet Walmart Project Gigaton procurement criteria. |
Methodological Framework
Initial hypotheses were tested against primary input from solid-state polymerization plant managers, beverage bottler procurement leads, thermoforming converter technical directors, and pharmaceutical packaging regulatory affairs specialists, then refined through customs trade data, SEC resin producer filings, EU ECHA registration dossiers, and FDA food-contact notification databases, with bottom-up volume builds cross-checked against top-down petrochemical capacity assessments.
Demand-supply-balance modeling across the analysis window incorporated grade-tier crystallinity specifications, end-use industry qualification pathways, regional production hub cost structures, and packaging format conversion rates. CAGRs were derived from intrinsic viscosity demand curves and lightweight preform adoption velocities, with pharmaceutical-grade purity premiums and recycled-content mandate compliance timelines serving as industry-specific forecast inputs.
Sensitivities concentrate around EFSA certification timeline delays, solid-state reactor equipment delivery backlogs, and ethylene glycol feedstock price spikes. Cross-checking against EU Plastics Recyclers trade association volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market