
 Cupcake Containers Market | 2026-2036
Cupcake Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Cupcake Containers Market Outlook
Modular multi-count configurations with removable inserts is restructuring how bakeries and foodservice operators manage inventory and presentation. Pactiv Evergreen Inc. leverages its thermoforming scale to supply standardized cup counts across North American retail channels. Huhtamäki Oyj anchors European demand through molded fiber expertise aligned with circular packaging mandates. Dart Container Corporation dominates the North American foam and plastic segment with deep distribution into institutional foodservice.
Cupcake containers are rigid or semi-rigid packaging units engineered to protect individual or grouped baked goods during transport, display, and storage, typically manufactured through thermoforming, injection molding, or pressed-pulp processes with dimensions calibrated to standard bakery tray formats. Plastic containers lead volume due to cost efficiency and clarity, though fiber-based alternatives are gaining fastest as food-contact compostability certifications multiply across European and North American supply chains. Closure type stratifies by channel: snap-on lids prevail in retail grocery for resealability, while hinge designs concentrate in foodservice for speed of service.
FDA food-contact substance regulations govern material safety and migration limits in the United States, while the EU's Packaging and Packaging Waste Directive alongside national extended producer responsibility schemes reshape material selection and end-of-life obligations for suppliers serving European markets. The EU Green Deal's 2030 packaging recyclability targets are forcing reformulation timelines for fossil-based plastics. Stakeholders must monitor evolving state-level plastic bans in the United States and emerging fiber certification standards to align capital allocation with compliance trajectories.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing demand timelines for fossil-based packaging while accelerating capital flows into fiber-forming equipment and compostable material streams across bakery supply chains.
Growth Catalysts
- Compostability Certification Surge:Food-contact compostability standards from BPI and TÜV Austria are unlocking shelf-space access for fiber-based containers in premium retail channels across Germany and France.
- Commercial Bakery Expansion:Specialty dessert chains are standardizing single-serve and multi-count formats for takeaway and delivery, driving container volume through centralized procurement.
- Circular Packaging Mandates:Extended producer responsibility schemes in EU member states are creating compliance-driven demand for recyclable and fiber-based alternatives over conventional plastics.
Market Restraints
- Pulp Input Cost Volatility:Recycled fiber and agricultural residue prices fluctuate with weather patterns and competing demand from corrugated packaging, squeezing margin stability for molded-fiber producers.
- Barrier Performance Gap:Fiber-based containers lack the moisture and grease resistance of polypropylene and PET without synthetic coatings, limiting application in high-fat bakery products.
- Thermoforming Equipment Concentration:Large-scale thermoforming capacity clusters in the United States and Germany, creating supply risk for buyers dependent on imported equipment and tooling.
Strategic Opportunities
- India Foodservice Penetration:Quick-service bakery chains in Mumbai and Bangalore are adopting standardized takeaway packaging, creating first-mover advantage for container suppliers with localized production.
- Smart Packaging Convergence:Integration of QR-coded traceability and temperature indicators into container lids is opening premium pricing in cold-chain dessert logistics.
- EU Green Deal Tailwinds:The 2030 packaging recyclability targets are forcing reformulation timelines that favor early movers with certified fiber-based product lines already in market.
Industry Challenges
- Composting Infrastructure Mismatch:Industrial composting facility coverage remains patchy across EU member states and North American municipalities, creating end-of-life credibility gaps for certified products.
- Legacy Equipment Stranding:Bakeries with sunk investment in automated sealing lines for plastic clamshells face high switching costs to accommodate fiber-based dimensional tolerances.
- Food-Contact Migration Testing:Novel bio-based coatings require extended FDA and EFSA migration study timelines, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cupcake Containers Market |
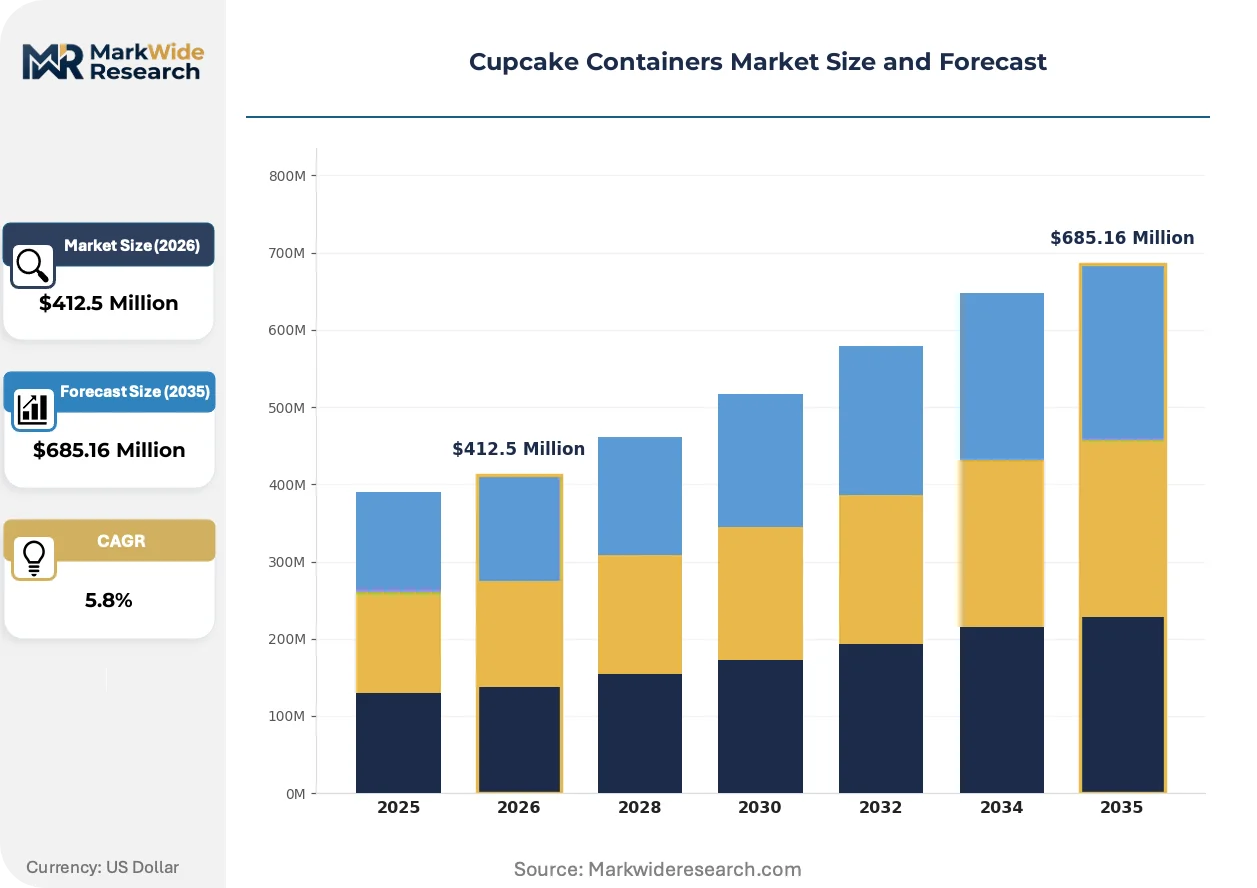
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Aluminum, Glass Size: Small, Medium, Large, Extra Large Shape: Round, Square, Rectangular, Oval Closure Type: Snap-on, Lids, Heat-sealed, Hinge |
| Companies Covered | Amcor plc, Pactiv Evergreen Inc., Huhtamäki Oyj, Dart Container Corporation, Plastic Package, Inc., GenPak, LLC, Detroit Forming Inc, TEMMA SHIKI CO., LTD, LINDAR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cupcake Containers Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redefine performance standards and procurement criteria across bakery packaging value chains.
Pressed-pulp forming with proprietary barrier coatings is overtaking conventional thermoformed PET in European premium retail channels. German and French bakery chains are mandating fiber-based containers for private-label lines within 24-month procurement windows. This shift is compressing demand for virgin plastic resins while expanding contract manufacturing capacity for molded-fiber specialists.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from food-contact applications. Industrial bakers must now qualify fluorine-free alternatives or redesign product formulations to reduce fat migration. The directive is accelerating most visibly in Nordic markets, where national regulators have advanced implementation timelines ahead of EU harmonization.
Bakery procurement teams are consolidating supplier rosters around full-service packaging partners capable of co-designing custom inserts and seasonal formats. This consolidation displaces fragmented purchasing of commodity containers through distribution intermediaries. The pattern concentrates in United Kingdom specialty chains, where centralized category management now controls packaging specification across franchise networks.
Cupcake Containers Market Segmentation
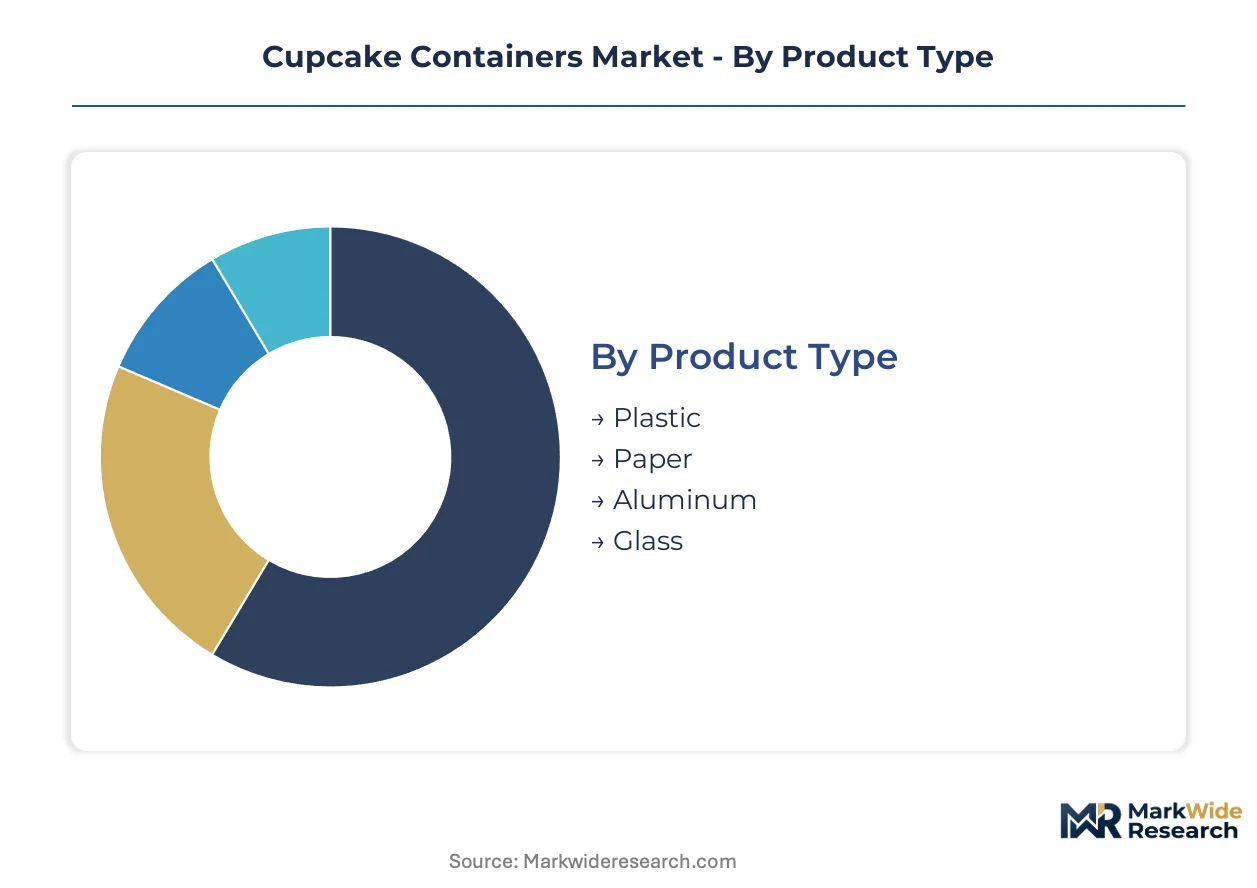
Cupcake container segmentation reveals how material selection, dimensional specifications, and closure mechanics align with distinct channel requirements and capital deployment strategies across bakery supply chains. Procurement teams optimize inventory turns by matching container architecture to product moisture content, transport distance, and retail display constraints.
Product Type:
Capital intensity peaks with thermoforming lines for plastic and pressed-pulp molding systems for fiber-based alternatives, while aluminum and glass require substantially lower tooling investment but higher per-unit material costs.
- Plastic:Polypropylene and PET thermoformed clamshells dominate volume through cost efficiency and optical clarity for retail display. Demand concentrates in United States grocery chains and German discount retailers where automated sealing lines favor standardized snap-fit dimensions. Barrier performance against moisture migration supports extended shelf-life applications in centralized bakery distribution.
- Paper:Molded fiber containers with proprietary bio-based coatings are gaining fastest in European premium channels as BPI and TÜV Austria certifications unlock shelf-space access. French and German bakery chains now mandate fiber-based formats for private-label procurement windows, compressing demand timelines for fossil-based alternatives.
- Aluminum:Lightweight rigid trays serve institutional foodservice and airline catering segments where heat tolerance and reuse cycles justify higher unit economics.
- Glass:Premium gifting and specialty dessert applications in Japan and Switzerland leverage optical clarity and perceived value, though weight and fragility constrain transport logistics.
Most installed capacity flows through Plastic. Expansion is steepest in Paper as EU Green Deal compliance deadlines accelerate fiber-forming equipment deployment.
Size:
Volume scale and margin structure diverge sharply across size tiers, with medium formats capturing the bulk of commercial bakery procurement while small single-serve units command premium pricing in takeaway channels.
- Small:Individual cupcake pods optimize for foodservice speed-of-service and premium gifting applications in Tokyo and Paris boutique bakeries.
- Medium:Standard six-count configurations align with North American bakery tray formats and European retail multipack norms. United Kingdom specialty chains centralize procurement around this tier for franchise network consistency.
- Large:Twelve-count formats serve event catering and club-store channels in the United States where volume purchasing patterns dominate.
- Extra Large:Bulk bakery and institutional foodservice in India and Brazil utilize twenty-four-plus counts, though logistics complexity limits adoption in fragmented retail environments.
Procurement volume peaks at Medium. Pricing power concentrates in Small formats where customization and premium positioning offset lower unit throughput.
Shape:
Manufacturing complexity and nesting efficiency in transport cartons vary substantially by geometry, with round formats requiring dedicated tooling and rectangular designs maximizing pallet density.
- Round:Classic aesthetic alignment with cupcake form factor supports premium positioning in French and Italian patisserie channels. Thermoforming tool costs run higher than angular alternatives.
- Square:Optimal nesting density reduces freight cost per unit in United States distribution networks. Standardization across bakery equipment lines simplifies procurement for multi-format suppliers.
- Rectangular:Efficient pallet utilization and display case compatibility drive adoption in German and United Kingdom grocery retail. Modular insert systems accommodate mixed product configurations.
- Oval:Niche positioning for gourmet and seasonal limited editions, primarily in Japanese and South Korean premium confectionery markets.
Freight economics favor Rectangular. Brand differentiation value peaks with Round in artisan bakery positioning.
Closure Type:
Automation compatibility and resealability requirements split demand between retail grocery and foodservice channels, with capital allocation to sealing equipment determining supplier selection criteria.
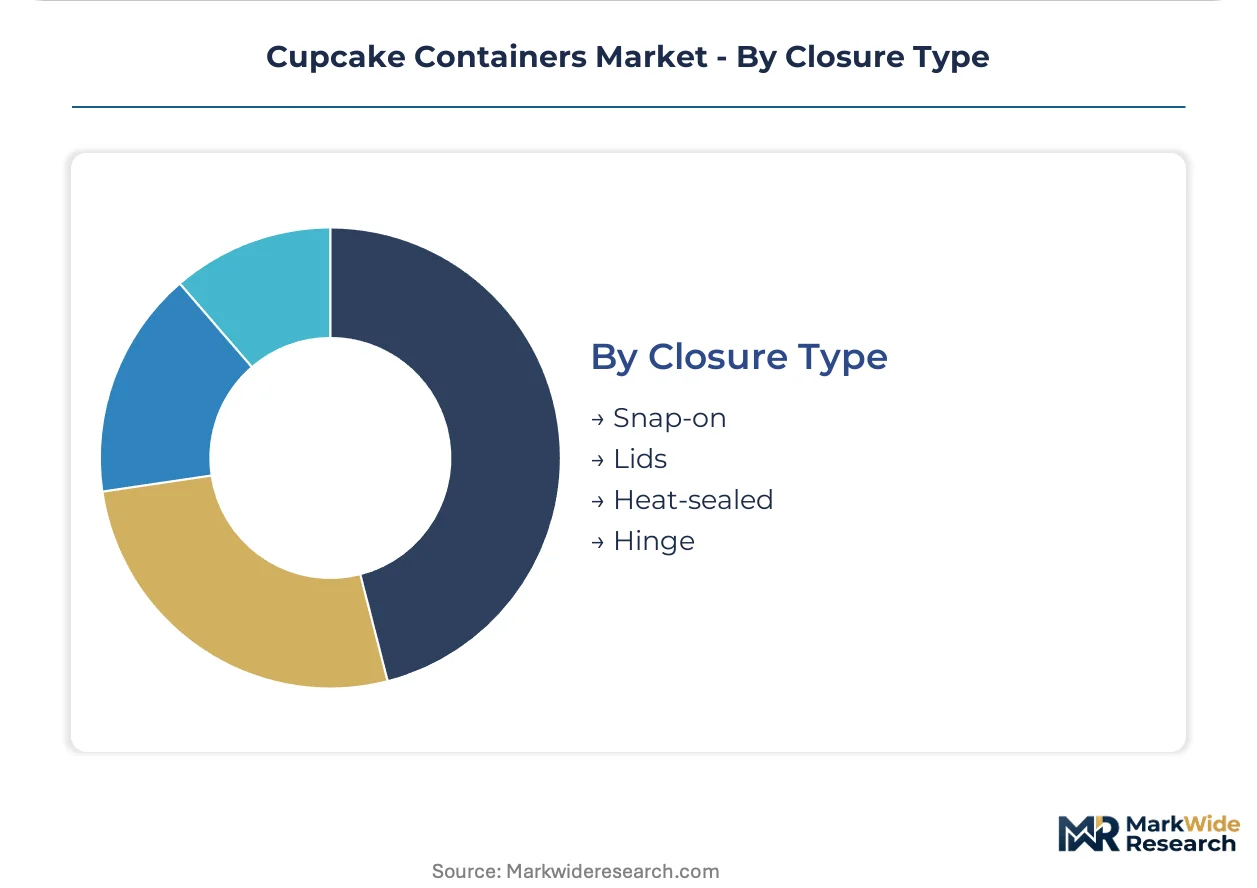
- Snap-on:Resealable lids dominate United States retail grocery where consumer storage convenience drives repeat purchase. Tooling investment for multi-point snap fits runs substantial.
- Lids:Separate cover components enable mix-and-match color branding for seasonal promotions in United Kingdom and Australian bakery chains. Inventory complexity increases with SKU proliferation.
- Heat-sealed:Tamper-evident security supports extended distribution radius for centralized bakery production in France and Germany. Sealing line capital requirements filter supplier base toward integrated packaging partners.
- Hinge:Integrated lid designs accelerate service speed in quick-service bakery and coffee shop channels across India and Southeast Asia. Lower unit cost offsets limited resealability.
Equipment lock-in is deepest with Heat-sealed. Adoption velocity is climbing fastest in Hinge formats as Asian quick-service bakery chains expand standardized takeaway packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cupcake container industry traces its commercial origins to mid-20th century United States bakery automation, where standardized tray formats and thermoforming technology first enabled mass-produced single-serve packaging for retail distribution.
United States
Centralized bakery chains and quick-service coffee shops drive container procurement volumes through standardized takeaway formats. FDA food-contact substance regulations govern material migration limits and safety certifications for all packaging entering interstate commerce. Chicago and Atlanta host dense clusters of thermoforming equipment suppliers serving national grocery and foodservice networks.
Germany
Discount grocery retailers and premium bakery chains are compressing procurement timelines for fiber-based alternatives ahead of EU Green Deal deadlines. Extended producer responsibility schemes under the Packaging and Packaging Waste Directive reshape end-of-life obligations for suppliers. Munich and Hamburg concentrate molded-fiber production capacity aligned with circular packaging mandates.
France
Patisserie chains and boutique bakeries prioritize aesthetic presentation in single-serve formats for high-margin takeaway segments. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-resistant coatings from food-contact applications. Paris and Lyon anchor demand for certified compostable containers in premium retail channels.
United Kingdom
Specialty dessert franchises are consolidating supplier rosters around full-service packaging partners capable of custom insert design. National regulators enforce packaging recyclability targets ahead of 2030 EU alignment deadlines. London and Manchester standardize procurement specifications across franchise networks for consistency.
India
Quick-service bakery chains in metropolitan centers are adopting standardized takeaway packaging for delivery and grab-and-go formats. FSSAI food safety standards govern material compliance for all food-contact packaging entering commercial distribution. Mumbai and Bangalore concentrate first-mover adoption among organized retail bakery operators.
Cupcake Containers Market Competitive Environment
The competitive structure tilts toward integrated packaging conglomerates with thermoforming scale and fiber-forming expertise. Market concentration is moderate, with tier-one players commanding premium shelf-space access through certification portfolios while regional specialists compete on customization velocity. Three archetypes dominate: multinational rigid packaging conglomerates with bakery-dedicated divisions, molded-fiber specialists capitalizing on regulatory tailwinds, and regional thermoforming job shops serving fragmented foodservice channels. Competitive moves center on capacity expansion in fiber-forming equipment and strategic partnerships with centralized bakery procurement teams.
Among the multinational tier, Pactiv Evergreen Inc., Huhtamäki Oyj, and Dart Container Corporation exemplify divergent strategic positions. Pactiv Evergreen occupies a scale-driven role in North American retail distribution. Huhtamäki Oyj represents the fiber-forming archetype aligned with European circular mandates. Dart Container Corporation anchors the institutional foodservice segment with legacy plastic and foam expertise. These three entities collectively illustrate how geographic footprint and material specialization determine competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| Amcor plc |
| Pactiv Evergreen Inc. |
| Huhtamäki Oyj |
| Dart Container Corporation |
| Plastic Package, Inc. |
| GenPak, LLC |
| Detroit Forming Inc |
| TEMMA SHIKI CO., LTD |
| LINDAR Corporation |
| Others |
Value Chain & Pricing Dynamics
Pulp fiber and polypropylene resin costs cascade through three distinct pricing tiers before reaching bakery procurement desks, with EU Green Deal compliance deadlines compressing margin structures for fossil-based suppliers while fiber-forming equipment investments reshape competitive cost positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with BPI and TÜV Austria certification tiers commanding 15-25% premiums over uncertified alternatives. Price differentiation hinges on compostability credentials and volume scale, with centralized bakery chains extracting favorable terms through multi-year offtake commitments. Cost compression in standard-grade plastic containers is intensifying because German and French discount retailers are consolidating supplier rosters around full-service packaging partners. Quick-service bakery chains in India and Southeast Asia exhibit highest price sensitivity, while Japanese patisserie boutiques absorb premium positioning costs without volume negotiation.
Supply Chain Analysis
Thermoforming equipment and molded-fiber production lines rest on concentrated manufacturing clusters in the United States, Germany, and China, with tooling fabrication and press-pulp molding systems drawing from overlapping but distinct supplier bases. Raw material dependencies span recycled fiber grades, agricultural residues, polypropylene pellets, and proprietary bio-based barrier coatings. Single-source vulnerability runs through German precision tooling houses that dominate high-speed thermoforming die production. Distribution runs through integrated packaging conglomerates with direct bakery procurement relationships, bypassing traditional distribution intermediaries in consolidated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cupcake container market functions as a stable compounder anchored by regulatory-driven material substitution cycles that guarantee replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Cement fiber-forming capacity leadership through backward integration into agricultural residue supply chains, locking in input cost stability against pulp price volatility. Defend against molded-fiber specialists by accelerating fluorine-free barrier coating R&D ahead of REACH enforcement waves. Channel control through exclusive equipment-leasing programs for bakery sealing lines creates switching-cost moats. For New Entrants and Emerging Players: Quick-service bakery chains in Indian metropolitan centers offer the most penetrable entry vector, with standardized takeaway packaging adoption running 3-5 years behind European maturity curves. Localized production partnerships with Mumbai and Bangalore equipment fabricators overcome import duty barriers. A co-design service model targeting seasonal insert customization for United Kingdom specialty franchises bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional molded-fiber specialists because EU extended producer responsibility schemes are fragmenting compliance obligations across member-state borders, favoring acquirers with pan-European certification management capabilities. Target mid-cap fiber-forming operators with existing TÜV Austria portfolios and underutilized press capacity. Watch industrial composting facility buildout rates in France and Germany as inflection signal for certified container demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Molded-Fiber | EU Green Deal deadlines force 24-month procurement windows for fiber-based alternatives. |
| Backward Integration into Agricultural Residues | Captive supply of wheat straw and bagasse insulates margin against recycled fiber volatility. |
| Fluorine-Free Barrier Coating Development | REACH restrictions on PFAS eliminate legacy grease-resistant treatments from food-contact applications. |
| Strategic Partnership with Centralized Bakery Chains | Co-design capabilities for custom inserts displace fragmented commodity purchasing. |
| Sustainability Repositioning through BPI Certification | Certified compostability unlocks premium shelf-space access in German and French retail channels. |
Study Parameters
Multiple input streams — structured interviews with bakery procurement directors and packaging R&D leads, trade data from EU and North American customs authorities, and regulatory filing analysis from ECHA and FDA dockets — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from thermoforming equipment operators, molded-fiber production managers, and centralized bakery category managers across Germany, France, the United Kingdom, and the United States. Secondary validation drew from Packaging and Packaging Waste Directive implementation reports, BPI certification databases, and SEC disclosures from publicly traded packaging conglomerates.
Data-stream reconciliation across volume shipments, material input costs, and end-use demand indicators shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include material type, closure mechanism, size tier, and channel format alongside regional regulatory cluster intensity. CAGRs were derived from curve-fitting techniques applied to historical shipment data and forward-looking procurement intention surveys. Forecast inputs incorporated EU member-state composting infrastructure buildout schedules and bakery automation investment cycles.
Revisions become necessary when industrial composting facility coverage expansion stalls, when novel bio-based coatings fail extended FDA migration study timelines, or when thermoforming equipment lead times compress unexpectedly. Forecasts reflect documented assumptions about regulatory enforcement consistency and bakery chain consolidation trajectories. A small set of named triggers — PFAS restriction acceleration, fiber input cost spikes, and quick-service bakery penetration rates in India — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Hot Drinks Packaging Market