
 Fibreglass Trays Market | 2026-2036
Fibreglass Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Fibreglass Trays Market Foresight
The capital-intensity divergence between automated pultrusion specialists and labor-dependent molders is unwinding competitive stability in fibreglass tray supply. Owens Corning leverages its captive glass fiber supply to control input costs across industrial-grade tray lines. Molded Fiber Glass Tray Company anchors North American production with deep tooling expertise in custom-shaped formats. Roltex NV differentiates through European hospitality channel relationships and slimline product specialization.
Fibreglass trays are reinforced thermoset composite vessels manufactured through resin transfer molding or compression molding, typically incorporating E-glass fiber mat with polyester or vinyl ester resin matrices, designed to withstand temperatures exceeding 120°C while resisting corrosion and impact damage in commercial foodservice and industrial handling environments. The product type dimension shows serving trays and catering trays commanding the dominant volume share due to institutional procurement scale, while decorative trays concentrate margin pools in premium retail channels. Application segmentation reveals commercial and institutional end-uses outpacing residential uptake as contract foodservice operators standardize on fiberglass over metal alternatives for weight reduction and dishwasher compatibility.
US FDA food-contact material regulations and EU REACH chemical safety frameworks jointly govern resin formulation compliance, compelling manufacturers to migrate from conventional styrene-based systems to low-VOC alternatives. Germany's KBA and France's ANSM coordinate with ECHA on composite material safety assessments, tightening market access for non-compliant imports. Stakeholders must monitor evolving biobased resin certification pathways and regional dishwasher-safety testing protocols to sustain product positioning.
Market Dynamics
The EU REACH regulation is forcing resin formulation migration across fibreglass tray supply chains, compressing margins for conventional styrene-based manufacturers while rewarding early adopters of low-VOC systems in Germany's Solingen industrial cluster.
Growth Catalysts
- Commercial Kitchen Modernization:Contract foodservice operators in Germany's hospitality sector are standardizing procurement of heat-resistant serving trays for weight reduction and dishwasher compatibility.
- REACH Chemical Safety Mandate:ECHA's tightened composite material assessments are accelerating demand for compliant low-emission resin formulations across European institutional buyers.
- Pultrusion Automation:Automated fiber placement systems are reducing labor dependency in tray manufacturing, enabling scale economies for industrial-grade product lines.
Market Restraints
- Raw Material Concentration:E-glass fiber supply concentrates among three major producers, creating input cost volatility for mold-dependent manufacturers lacking captive fiber sources.
- Substitution Threat:Molded pulp and biopolymer alternatives are capturing premium retail tray segments where weight tolerance exceeds heat performance requirements.
- Regulatory Friction:Divergent FDA food-contact rules and EU REACH compliance pathways force dual-formulation inventories for cross-Atlantic suppliers.
Strategic Opportunities
- Biobased Resin Certification:Emerging ASTM and ISO standards for renewable-content composites open positioning for manufacturers ahead of EU Green Deal procurement mandates.
- Healthcare Channel Expansion:Hospital foodservice operators present underpenetrated demand for antimicrobial tray surfaces in France and Belgium's institutional networks.
- Direct E-Commerce Distribution:Bypassing traditional hospitality distributors through B2B platform sales captures margin from small-format catering operators.
Industry Challenges
- Tooling Capex Burden:Compression mold fabrication for custom-shaped formats demands six-figure capital commitments, constraining product line expansion for mid-scale producers.
- Cross-Border Certification Timelines:Parallel KBA and ANSM safety assessments extend market access delays for new resin formulations by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibreglass Trays Market |
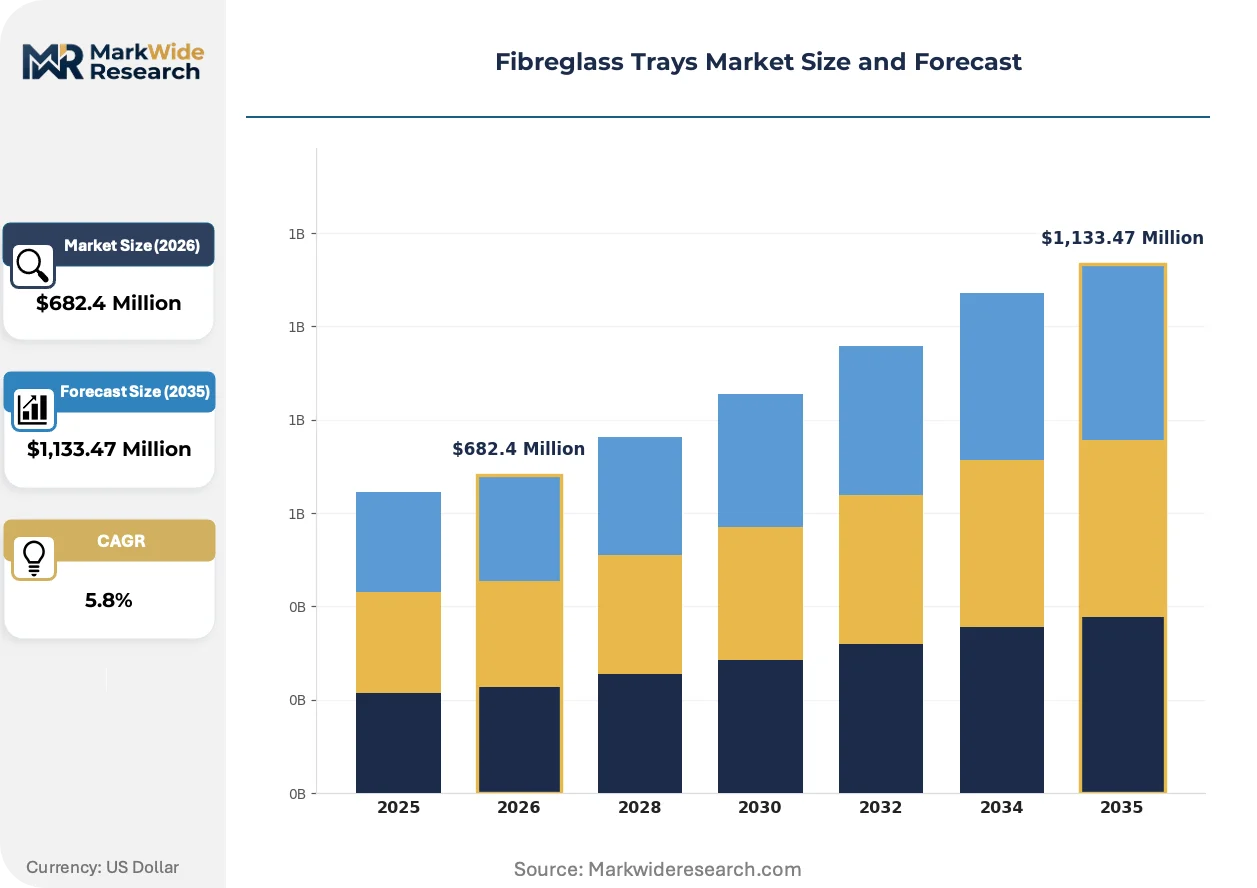
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,133.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Trays, Storage Trays, Serving Trays, Catering Trays Application: Residential, Commercial, Industrial, Institutional Form: Stackable, Collapsible, Custom Shaped, Slimline End User: Hospitality, Catering Services, Retailers, Home Users |
| Companies Covered | Molded Fiber Glass Tray Company, Owens Corning, Huhtamaki Group, BASF, Carlisle FoodService Products, Roltex NV, U.S. Composites, FiberGlass Systems, Enduro Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibreglass Trays Market Shifts & Advancements
Resin chemistry and manufacturing process evolution are compressing cost structures while regulatory alignment creates first-mover advantages in formulation compliance.
Vinyl ester resin systems are displacing conventional polyester matrices in high-temperature tray applications. Institutional foodservice buyers in Germany and France are specifying these materials for dishwasher-cycle durability above 120°C. This displacement is compressing margins for legacy polyester specialists unable to reformulate at scale.
REACH Annex XVII restrictions on styrene emissions are compelling resin suppliers to accelerate low-VOC unsaturated polyester development. Manufacturers serving EU institutional channels must certify formulations through ECHA-recognized laboratories before market access. Germany's KBA coordination with France's ANSM is tightening enforcement consistency, raising compliance barriers for non-EU imports.
Consolidated procurement by contract foodservice management companies is compressing supplier bases and extending contract durations. Multi-site operators in the Netherlands and Belgium are mandating single-source tray standardization across property portfolios. This concentration is most visible in airport and stadium catering concessions where volume scale justifies direct manufacturer relationships.
Fibreglass Trays Market Segmentation
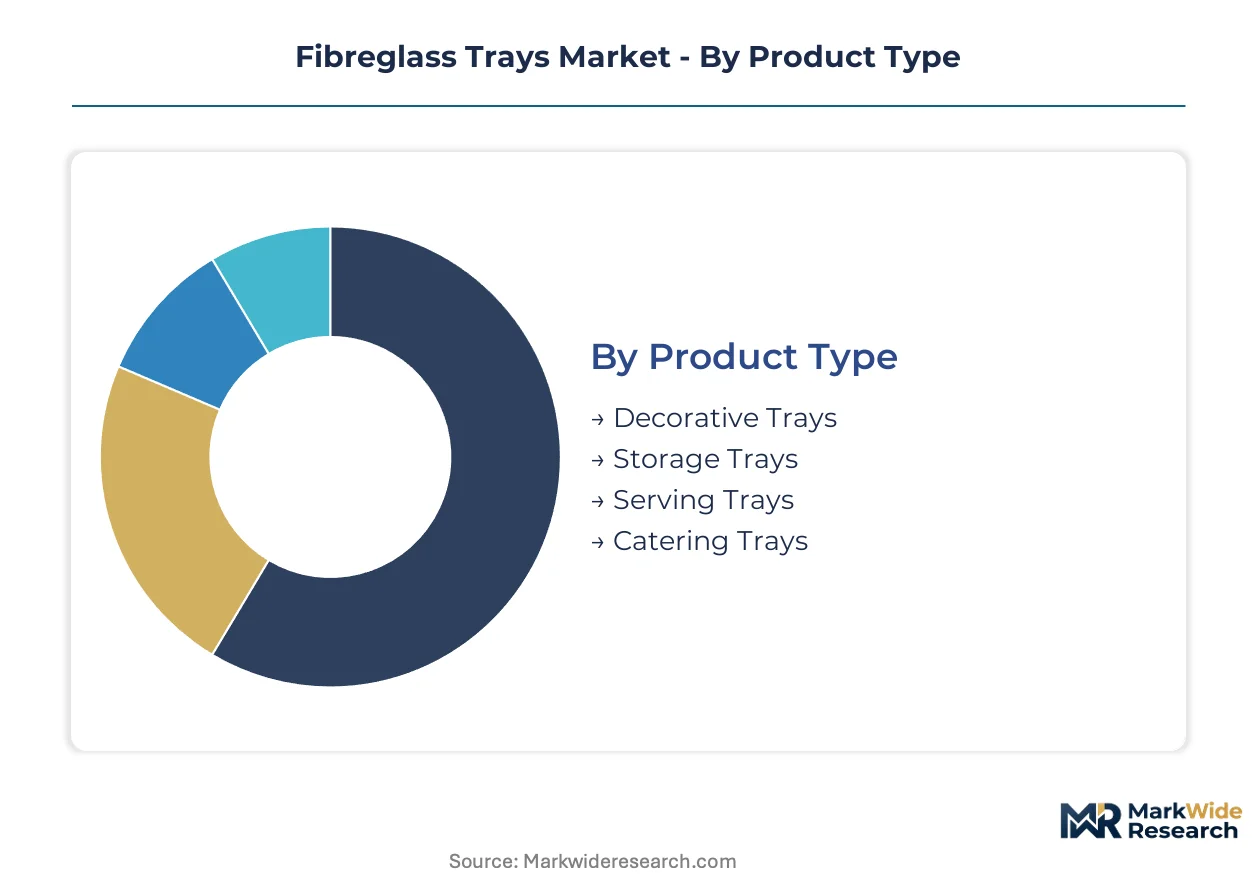
Segmentation in fibreglass trays reveals divergent vulnerability to material substitution across use cases. Heat-performance requirements and procurement scale determine which categories withstand pressure from molded pulp and biopolymer alternatives.
Product Type:
Substitution pressure concentrates in segments where thermal tolerance is non-critical, exposing decorative and storage formats to biopolymer displacement while serving and catering lines defend position through dishwasher-cycle durability requirements.
- Serving Trays:E-glass reinforced vinyl ester construction withstands sustained exposure above 120°C in commercial dishwasher environments. Institutional foodservice operators in Germany's Solingen cluster specify these for weight reduction and corrosion resistance in high-cycle operations.
- Catering Trays:Compression-molded formats with polyester resin matrices balance impact resistance against unit economics for volume contract operators. Multi-site hospitality groups in the Netherlands standardize procurement across property portfolios, compressing supplier bases.
- Decorative Trays:Surface-finish variety drives premium retail positioning where heat performance is secondary to aesthetic differentiation.
- Storage Trays:Industrial handling applications favor durability but face selective substitution from molded fiber in static-load environments.
Catering trays anchor the volume base while serving trays gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive institutional deployments from price-sensitive residential uptake, with mid-tier commercial operators driving standardization toward dishwasher-compatible specifications.
- Commercial:Contract foodservice management companies consolidate procurement specifications across airport and stadium concessions. These operators mandate fiberglass over metal for weight reduction and compatibility with automated dishwashing infrastructure.
- Institutional:Hospital and healthcare foodservice networks in France and Belgium present underpenetrated demand for antimicrobial surface treatments. ANSM safety assessments govern resin formulation compliance for patient-contact applications.
- Industrial:Material handling and logistics operations specify impact-resistant formats for warehouse and distribution center deployment.
- Residential:Retail channel distribution concentrates margin pools in premium finish categories where substitution from alternative materials is most advanced.
Commercial application anchors the volume base while institutional use climbs the fastest.
Form:
Volume scale concentrates in formats that optimize logistics density, with stackable and slimline configurations defending position against collapsible alternatives in high-throughput environments.
- Stackable:Interlocking rim designs maximize storage density in commercial kitchen environments. These formats dominate procurement by contract operators with centralized distribution requirements.
- Slimline:Reduced-profile construction enables efficient transport and storage in space-constrained hospitality settings. Roltex NV specializes in this format for European channel relationships.
- Custom Shaped:Tooling-intensive compression molds demand six-figure capital commitments, constraining mid-scale producer participation.
- Collapsible:Hinge mechanisms add cost and failure points, limiting penetration to premium retail segments where storage convenience outweighs durability priorities.
Stackable form anchors the volume base while slimline gains share at the steepest rate.
End User:
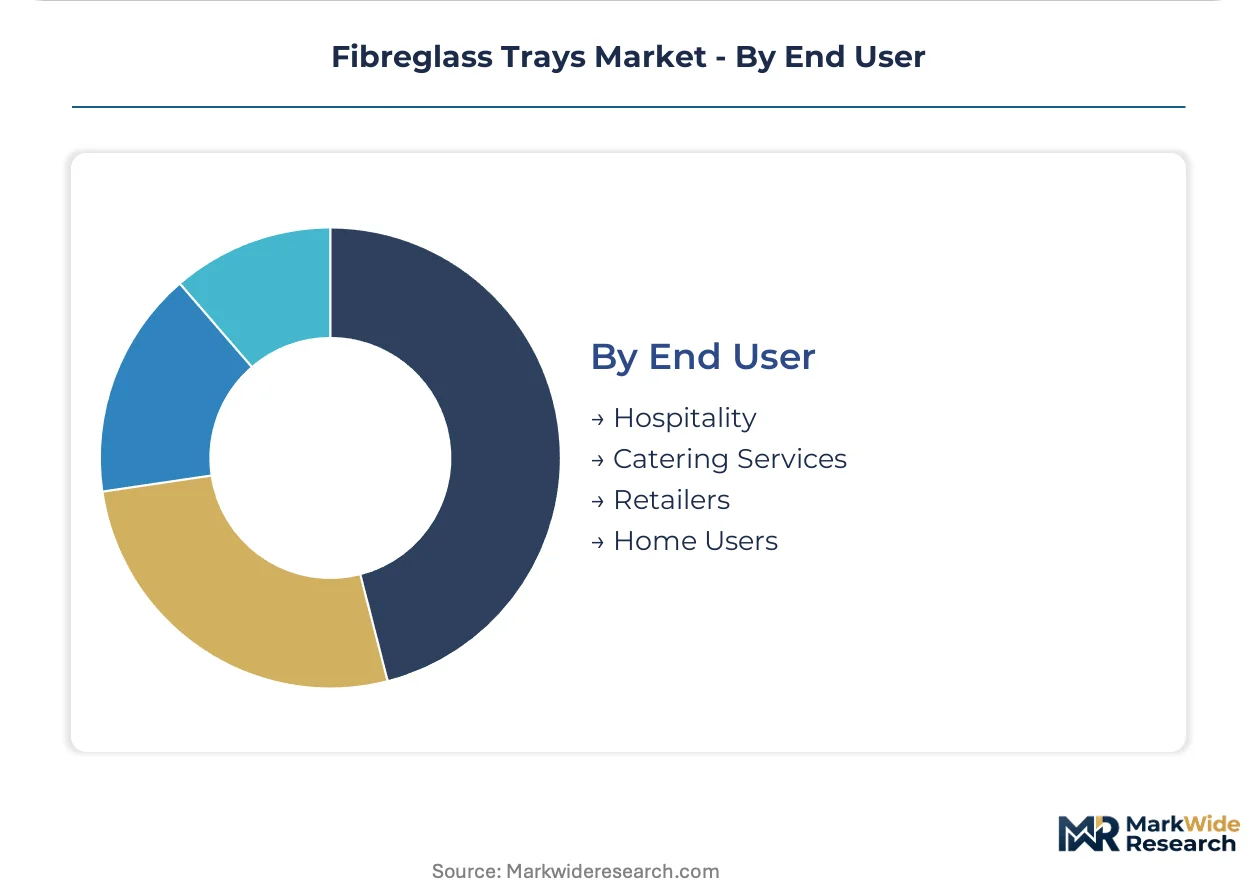
Customer type determines channel structure and margin capture, with hospitality and catering services consolidating procurement through direct manufacturer relationships while retail intermediaries fragment residential demand.
- Hospitality:Hotel and restaurant groups standardize tray specifications across property portfolios. REACH-compliant low-VOC resin formulations are mandatory for EU procurement tenders.
- Catering Services:Multi-site operators in Belgium and the Netherlands mandate single-source standardization for operational consistency. These buyers prioritize dishwasher-cycle durability and weight reduction for transport efficiency.
- Retailers:Premium and mass-market channels diverge in specification requirements, with specialty retailers capturing margin in decorative finish categories.
- Home Users:E-commerce direct distribution is emerging as a channel for small-format catering operators seeking to bypass traditional hospitality distributors.
Hospitality anchors the volume base while catering services expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's institutional foodservice operators deploy fibreglass trays for high-cycle dishwasher environments, while US commercial kitchens prioritize weight reduction for transport efficiency. France and Belgium concentrate healthcare procurement with antimicrobial specifications. China's manufacturing base supplies cost-optimized formats for export markets.
Germany
Contract foodservice management companies in the Solingen industrial cluster specify vinyl ester resin trays for sustained heat exposure above 120°C. ECHA's REACH Annex XVII enforcement tightens styrene emission limits for composite manufacturers. Tooling specialists around Solingen compress mold fabrication lead European production of custom-shaped institutional formats.
United States
Airport and stadium catering concessions mandate fiberglass over metal alternatives for automated dishwashing compatibility. FDA food-contact material regulations govern resin formulation compliance for interstate commerce. Molded Fiber Glass Tray Company anchors North American supply from its tooling-intensive production base.
France
Hospital foodservice networks in Paris and Lyon present underpenetrated demand for antimicrobial surface treatments. ANSM coordinates with ECHA on composite safety assessments for patient-contact applications. The Île-de-France region concentrates procurement decision-making for national healthcare catering contracts.
Belgium
Multi-site hospitality operators in Brussels and Antwerp standardize single-source tray procurement across property portfolios. EU Green Deal procurement mandates accelerate biobased resin certification requirements. Roltex NV leverages its slimline specialization for European channel relationships concentrated in the Low Countries.
China
Export-oriented manufacturers supply cost-optimized polyester resin trays for price-sensitive commercial segments. MIIT oversees industrial standards for composite material production licensing. The Yangtze River Delta cluster concentrates mold fabrication capacity serving international foodservice equipment buyers.
Fibreglass Trays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fibreglass tray supply. Captive glass fiber supply distinguishes the upper tier from mold-dependent fabricators exposed to input volatility. Three archetypes populate the competitive map: integrated fiber-to-tray producers, custom tooling specialists, and regional hospitality channel players. Consolidation pressure operates through contract foodservice procurement standardization and REACH compliance cost burdens.
Among North American fabricators, Molded Fiber Glass Tray Company exemplifies the tooling-intensive custom format specialist, while Owens Corning represents integrated fiber supply control. Roltex NV occupies a position within the European hospitality channel tier, leveraging geographic proximity to institutional buyers in the Low Countries.
| Leading Market Players |
|---|
| Molded Fiber Glass Tray Company |
| Owens Corning |
| Huhtamaki Group |
| BASF |
| Carlisle FoodService Products |
| Roltex NV |
| U.S. Composites |
| FiberGlass Systems |
| Enduro Composites |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with E-glass fiber suppliers lock in input cost visibility for German and Belgian tray manufacturers while insulating them from spot-market volatility in composite raw materials. These arrangements simultaneously secure REACH-compliant resin allocation and compress working capital requirements for mold-fabrication specialists serving institutional foodservice channels.
Pricing Analysis
After-sales service bundling with antimicrobial surface treatments drives lifetime value capture in healthcare channel deployments. Three-tier pricing structure across premium vinyl ester, standard polyester, and economy-grade formulations separates certification tiers for EU institutional buyers. Pricing pressure stems from REACH compliance migration costs compressing legacy styrene-based manufacturer margins. Contract foodservice operators exhibit lowest price sensitivity due to consolidated procurement scale, while residential retail channels face acute substitution pressure from molded pulp alternatives.
Supply Chain Analysis
Inventory buffers for compression molds stretch lead times to 14-18 weeks for custom-shaped institutional formats. E-glass fiber supply concentrates in Germany, China, and the United States, while vinyl ester resin formulation clusters around Belgian and Dutch chemical processing hubs. Raw material dependency on styrene derivatives and glass fiber mat creates exposure to energy-cost volatility in European production zones. Distribution runs through contract foodservice management companies and hospitality equipment distributors serving multi-site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fibreglass tray market operates as a regulatory-moat defensive structure where REACH compliance entrenchment and multi-year institutional procurement contracts create switching-cost barriers for incumbent suppliers.
For Market Incumbents: Secure captive E-glass fiber supply through backward integration or long-term offtake agreements with Owens Corning-tier suppliers to defend against input cost volatility. Accelerate vinyl ester resin certification through ECHA-recognized laboratories ahead of Annex XVII enforcement tightening, locking out reformulation-lagged competitors from German institutional tenders. For New Entrants and Emerging Players: ECHA fast-track certification for low-VOC unsaturated polyester formulations opens procurement access to Netherlands and Belgium multi-site hospitality operators seeking second-source supply security. Target underpenetrated hospital foodservice networks in France's Île-de-France region with antimicrobial surface treatment differentiation, leveraging direct B2B platform distribution to bypass established hospitality distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom tooling specialists with embedded relationships in airport and stadium concession operators. Five-to-ten year viability favors mold-fabrication assets with REACH-compliant resin formulation capabilities and concentrated exposure to contract foodservice procurement consolidation. Monitor ECHA enforcement intensity against non-compliant imports as inflection signal for margin expansion in certified domestic production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Fiber Supply | Owens Corning's captive fiber control demonstrates margin defense against styrene resin volatility. |
| REACH-Compliant Resin Certification Program | ECHA-recognized laboratory validation accelerates market access for low-VOC formulations ahead of enforcement. |
| Healthcare Channel Antimicrobial Development | ANSM safety assessment alignment opens hospital foodservice procurement in France and Belgium. |
| Direct B2B Platform Distribution Launch | Bypassing traditional hospitality distributors captures margin from small-format catering operators. |
| Custom Mold Fabrication Capacity Expansion | Solingen industrial cluster tooling expertise supports institutional format specialization. |
Research Methodology
The analysis maps serving tray, catering tray, decorative tray, and storage tray sub-sectors, each validated through procurement directors at contract foodservice management companies, resin formulation technical leads, and hospitality equipment distributors. Primary interviews with plant managers at German and Belgian compression molding facilities combined with secondary validation from ECHA regulatory filings, EU customs trade data, and foodservice equipment industry association reports. Bottom-up unit economics triangulate against top-down market sizing across product type and application segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, application, form, and end user dimensions with CAGRs derived from regression analysis of historical procurement patterns and regulatory phase-in timelines. Forecast inputs included REACH Annex XVII enforcement schedules, contract foodservice operator consolidation trajectories, and resin formulation substitution elasticities.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable E-glass fiber supply concentration; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Molded Fiber Cup Market