
 Europe Molded Fiber Packaging Market | 2026-2036
Europe Molded Fiber Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molded Fiber Packaging Market Foresight
The EU Packaging and Packaging Waste Regulation is expanding the addressable market for molded fiber alternatives as brand owners face binding recyclability targets. Huhtamaki Oyj leverages its integrated pulp-to-package manufacturing footprint across Finland and beyond to capture food service demand. Brødrene Hartmann A/S anchors its position through recycled paper-based egg packaging and protective formats for industrial applications. Mondi Group competes with kraft paper and molded fiber hybrid solutions that extend its fiber packaging portfolio into premium consumer segments.
Molded fiber packaging comprises cellulose-based containers formed under heat and pressure from slurried recycled paper, wood pulp, or agricultural residues such as sugarcane bagasse, serving primarily as protective and food-contact packaging with inherent biodegradability. Trays and clamshells dominate volume as food industry buyers shift from expanded polystyrene toward compostable serving formats. Sugarcane bagasse and bamboo fiber represent the fastest-expanding material categories where processors seek agricultural residue streams with lower water intensity than virgin wood pulp. Wood pulp sustains margin concentration in medical and electronics inserts where dimensional stability and surface smoothness command specification premiums.
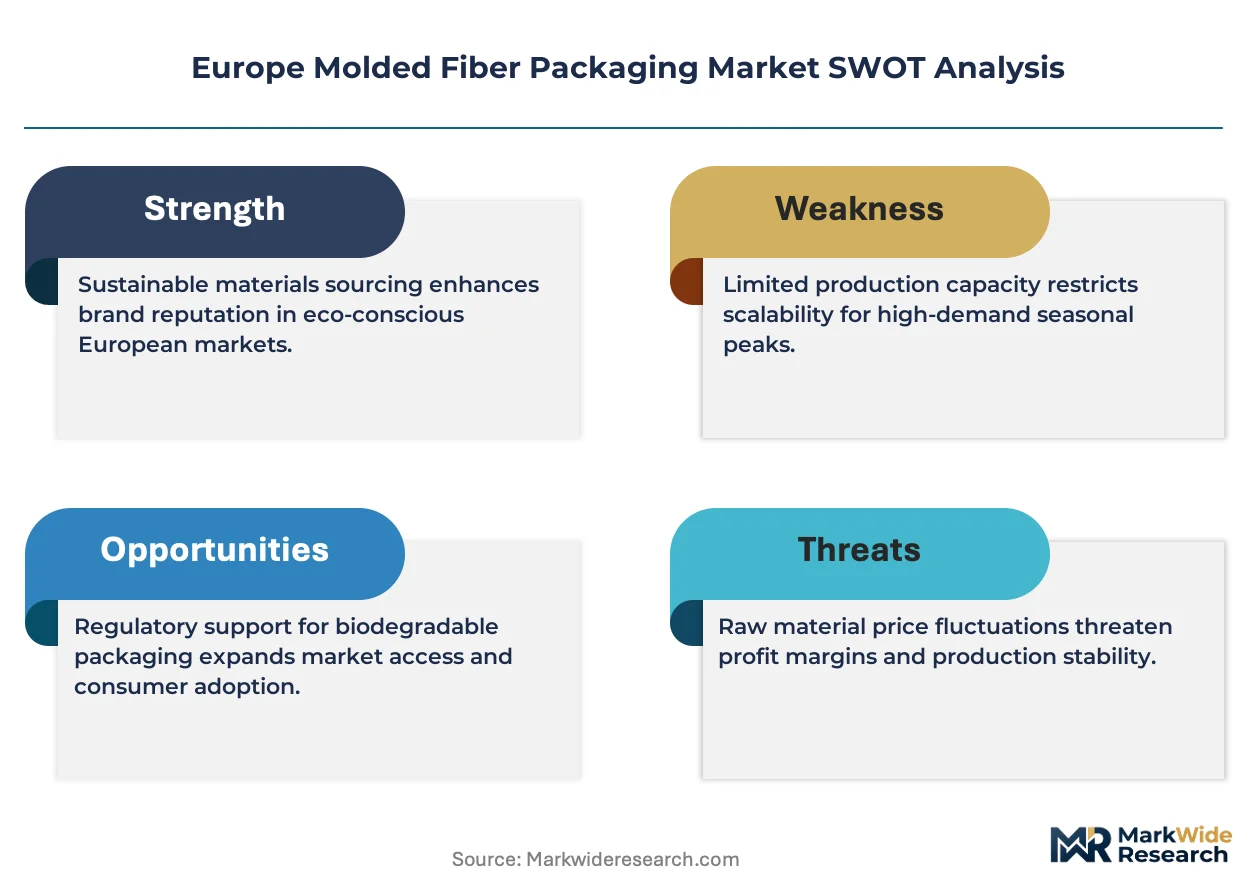
REACH compliance and CE marking requirements govern chemical safety and product conformity for molded fiber articles entering European commerce, while the EU Green Deal's circular economy action plan accelerates substitution mandates for non-recyclable packaging substrates. ECHA's evolving restrictions on per- and polyfluoroalkyl substances in food contact materials are forcing reformulation of oil-resistant additives across the supply base. Stakeholders must monitor regulatory timelines for extended producer responsibility fee structures and decide whether to invest in captive pulp molding capacity or secure long-term supply agreements with specialized converters.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing substitution timelines for food service operators, forcing rapid conversion from expanded polystyrene to cellulose-based formats across Germany, France, and Benelux markets.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding recyclability thresholds under the EU Packaging and Packaging Waste Regulation are eliminating plastic alternatives from quick-service restaurant supply chains.
- Agricultural residue valorization:Sugarcane bagasse processing is expanding molded fiber capacity in Southern European farming regions with lower water intensity than virgin pulp routes.
- Retailer sustainability scorecards:Carrefour and Ahold Delhaize procurement policies now exclude non-compostable single-use containers from private-label food service contracts.
Market Restraints
- Recycled pulp cost volatility:Old corrugated containerboard price swings in Iberian and Italian collection markets squeeze converter margins without long-term fiber supply agreements.
- Per- and polyfluoroalkyl substance restrictions:ECHA's evolving food-contact limitations on oil-resistant additives force expensive reformulation cycles for molded fiber tray producers.
- Molded pulp dimensional tolerances:Electronics and medical device inserts require surface smoothness specifications that agricultural fiber struggles to meet against virgin wood pulp benchmarks.
Strategic Opportunities
- Central and Eastern European penetration:Poland and Romania food service markets remain underdeveloped for molded fiber clamshells relative to Western European saturation levels.
- Pharmaceutical cold-chain formats:Insulated molded fiber shippers for temperature-sensitive biologics represent a premium application segment with limited incumbent competition.
- Extended producer responsibility fee structures:Pending EU EPR implementation creates first-mover advantage for brand owners with certified compostable packaging portfolios.
Industry Challenges
- Hot-press tooling capex cycles:Multi-cavity mold fabrication for high-throughput tray production requires 18-24 month lead times that constrain capacity responsiveness.
- CE marking conformity assessment:Food contact material migration testing timelines delay product launches for converters without established laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molded Fiber Packaging Market |
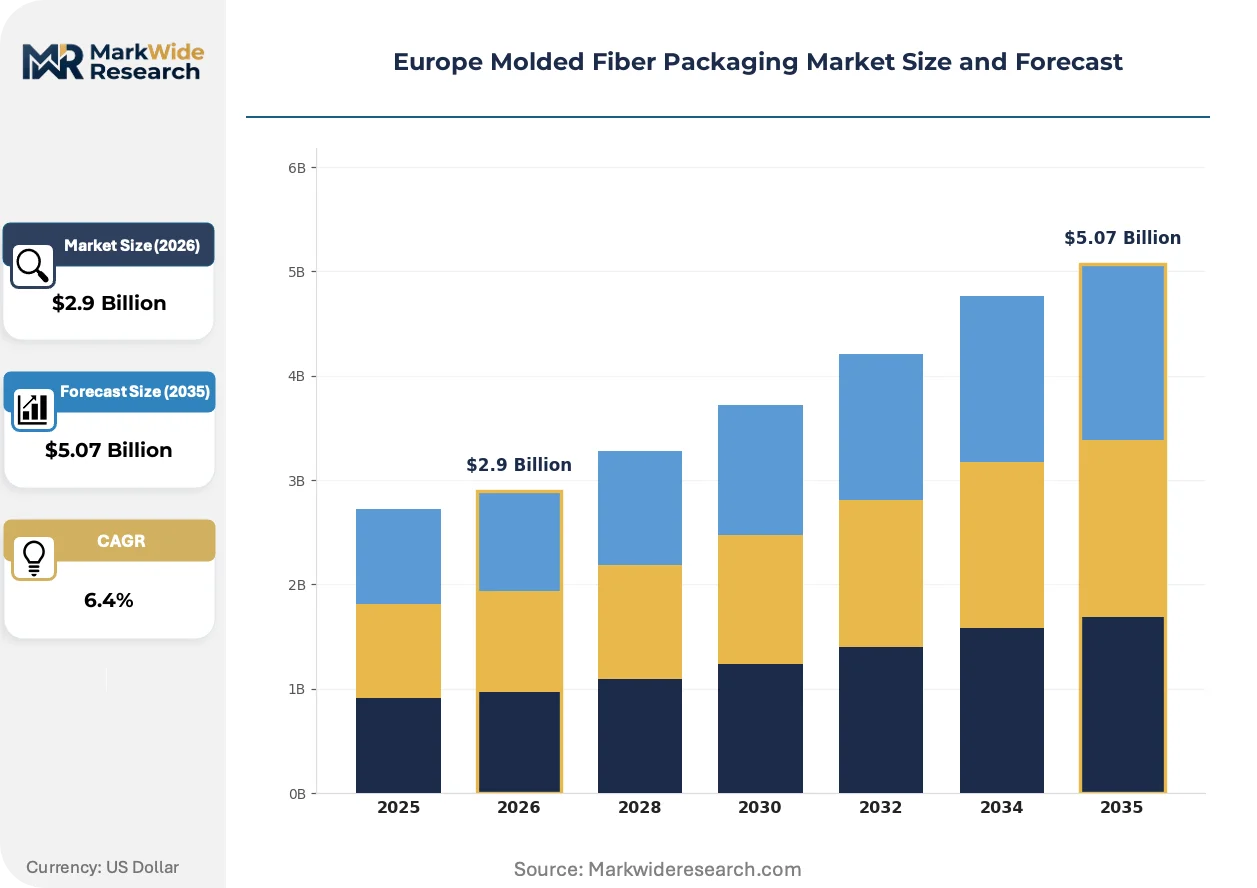
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Containers, Inserts End User: Food Industry, Electronics, Healthcare, Consumer Goods Material: Recycled Paper, Wood Pulp, Sugarcane Bagasse, Bamboo Fiber Distribution Channel: Online Retail, Direct Sales, Wholesale, Others |
| Companies Covered | Huhtamaki Oyj, Brødrene Hartmann A/S, Sonoco Products Company, Pactiv Evergreen, Omni-PAC Group UK, Mondi Group, PulpWorks, Molded Fiber Solutions, Robert Cullen Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molded Fiber Packaging Market Shifts & Advancements
Heat-press molding automation and barrier coating chemistry are converging to expand molded fiber into premium food service and protective packaging segments previously reserved for plastic formats.
Precision thermoforming with in-mold labeling capability is absorbing demand from gourmet ready-meal producers in France and Italy who require high-definition branding on compostable trays. Premium supermarket chains are specifying these formats for private-label prepared foods. The technology is absorbing margin compression from conventional plastic thermoforming by commanding 15-20% price premiums in specialty retail channels.
REACH compliance deadlines for per- and polyfluoroalkyl substance restrictions are accelerating additive supplier consolidation across European chemical markets. Molded fiber converters face reformulation costs for oil and grease resistance without fluorinated chemistries. Food service tray manufacturers in Germany and the Netherlands are responding by partnering with bio-based barrier coating developers to secure compliant supply ahead of enforcement phases.
Direct procurement relationships between quick-service restaurant chains and molded fiber converters are displacing traditional distribution intermediaries in the UK and Nordic markets. Buyers are consolidating supplier panels to three-to-five approved vendors with integrated pulp-to-package capabilities. This pattern is most visible in McDonald's and Burger King supply chain reconfigurations across the British Isles, where long-term volume commitments are replacing spot purchasing through packaging distributors.
Europe Molded Fiber Packaging Market Segmentation
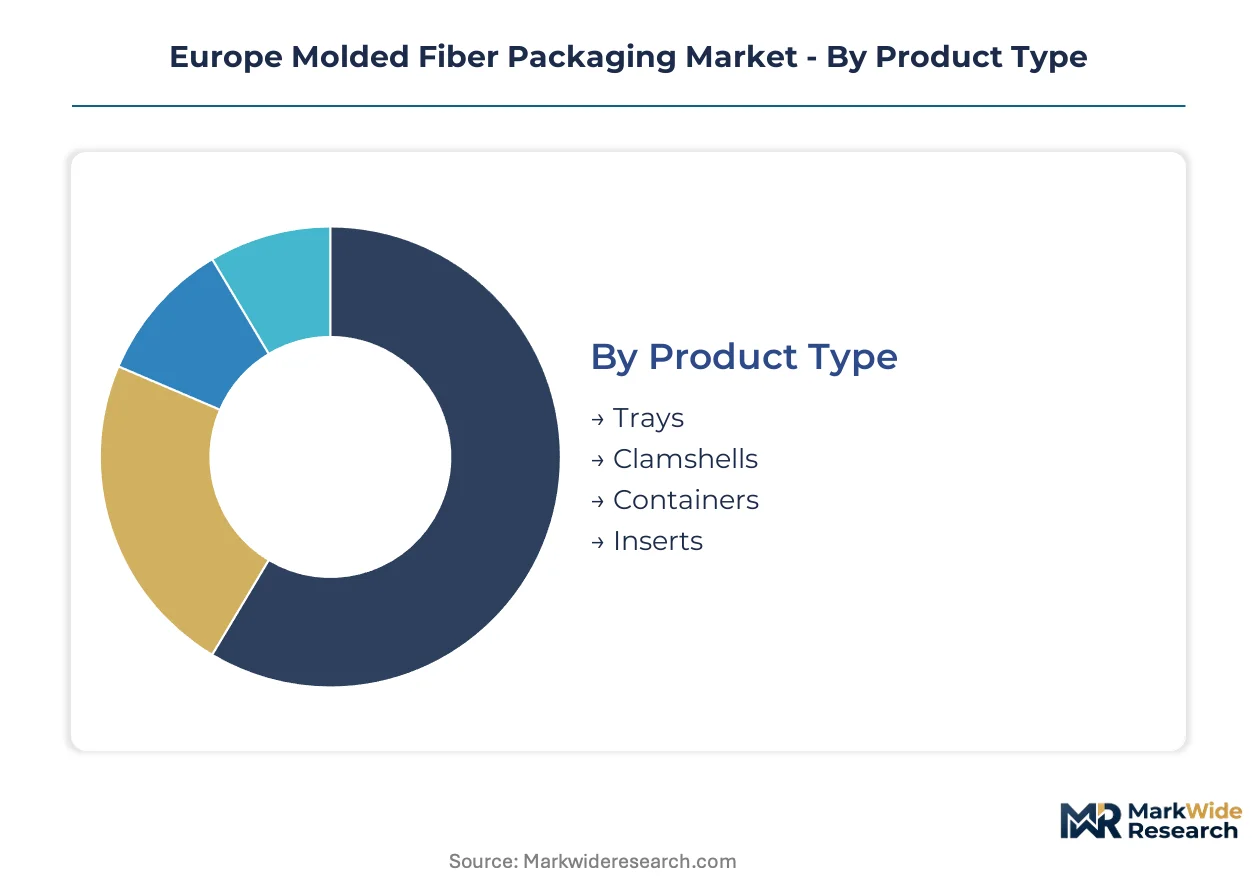
Segmentation in molded fiber packaging reveals divergent margin structures across material grades and end-use specifications. Food service operators drive volume throughput while medical and electronics segments command specification premiums.
Product Type:
Volume concentrates in standardized serving formats while premium applications absorb tooling investments for dimensional precision.
- Trays:Flat-bottomed cellulose formats with formed edges serve quick-service restaurants and institutional catering across Germany and France. Carrefour and Ahold Delhaize procurement policies now mandate compostable trays for private-label prepared foods, displacing expanded polystyrene at scale.
- Clamshells:Hinged-lid containers formed through precision thermoforming protect ready-meals and produce with integrated sealing surfaces. Gourmet retail channels in France and Italy specify these formats for high-definition branding capability, commanding price premiums over conventional plastic thermoforming.
- Containers:Lidded vessels with separate closures serve soup and liquid food applications where barrier coating chemistry prevents leakage.
- Inserts:Custom-molded protective shapes cushion electronics and medical devices during transit, requiring surface smoothness specifications that virgin wood pulp routes satisfy.
Mature deployment sits with Trays. Newer deployment is concentrated in Inserts.
End User:
Customer concentration varies sharply between high-volume food service contracts and specification-driven industrial procurement.
- Food Industry:Quick-service restaurant chains across the British Isles and Nordic markets consolidate supplier panels to three-to-five approved vendors with integrated pulp-to-package capabilities. McDonald's and Burger King supply chain reconfigurations displace traditional distribution intermediaries through direct procurement relationships.
- Electronics:Protective molded fiber formats for consumer electronics and industrial components demand dimensional tolerances that agricultural fiber struggles to meet against virgin wood pulp benchmarks.
- Healthcare:Medical device inserts and pharmaceutical cold-chain formats require CE marking conformity assessment and migration testing timelines that delay product launches without established laboratory partnerships.
- Consumer Goods:Protective packaging for cosmetics and premium retail applications absorbs margin compression through aesthetic surface finishes.
Procurement consolidation is most advanced in Food Industry. Specification complexity is highest in Healthcare.
Material:
Water intensity and collection infrastructure determine regional competitiveness of fiber sourcing routes.
- Recycled Paper:Old corrugated containerboard streams feed Iberian and Italian converter capacity, though price swings squeeze margins without long-term supply agreements.
- Wood Pulp:Virgin cellulose from Nordic and Baltic forests sustains margin concentration in medical and electronics inserts where dimensional stability and surface smoothness command specification premiums.
- Sugarcane Bagasse:Agricultural residue processing expands capacity in Southern European farming regions with lower water intensity than virgin pulp routes, climbing fastest as processors seek alternative feedstocks.
- Bamboo Fiber:Rapid-growth grass pulp offers fiber yield advantages in select Mediterranean cultivation zones with established processing infrastructure.
Established supply sits with Recycled Paper. Capacity expansion is concentrating in Sugarcane Bagasse.
Distribution Channel:
Channel structure reflects the displacement of intermediaries by direct volume commitments at the top of the market.
- Online Retail:E-commerce platforms aggregate small-batch orders from specialty food producers and artisan manufacturers seeking compostable packaging without minimum volume thresholds.
- Direct Sales:Long-term volume commitments between quick-service restaurant chains and molded fiber converters replace spot purchasing through packaging distributors in the UK and Nordic markets.
- Wholesale:Traditional packaging distributors serve mid-tier food service operators and regional bakery chains with standardized tray and clamshell formats.
- Others:Cooperative purchasing arrangements and industry consortium procurement cover institutional buyers with fragmented demand profiles.
Relationship depth is greatest in Direct Sales. Transactional volume persists in Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Randstad corridor spanning Amsterdam-Rotterdam-Antwerp anchors European molded fiber packaging demand through dense food service logistics and port-accessible pulp supply chains.
Germany
Quick-service restaurant chains in North Rhine-Westphalia and Bavaria are consolidating supplier panels to three-to-five approved vendors with integrated pulp-to-package capabilities. The German Packaging Act implements strict recyclability thresholds that eliminate expanded polystyrene from McDonald's and Burger King supply chains across the British Isles. The Rhine-Ruhr industrial cluster hosts converters responding to ECHA's evolving per- and polyfluoroalkyl substance restrictions through bio-based barrier coating partnerships.
France
Gourmet ready-meal producers in Île-de-France specify precision thermoformed clamshells with in-mold labeling capability for high-definition branding on compostable trays. The French Anti-Waste Law for a Circular Economy mandates single-use plastic elimination timelines that accelerate substitution toward cellulose-based formats. The Lyon-Saint-Étienne corridor concentrates capacity for premium supermarket private-label prepared foods commanding price premiums over conventional plastic thermoforming.
United Kingdom
Direct procurement relationships between quick-service restaurant chains and molded fiber converters are displacing traditional distribution intermediaries across British food service markets. UK REACH maintains chemical safety standards for food contact materials that align with EU restrictions on fluorinated oil-resistant additives. The Midlands manufacturing belt hosts converters securing long-term volume commitments from major fast-food brands replacing spot purchasing through packaging distributors.
Italy
Old corrugated containerboard price swings in Iberian and Italian collection markets squeeze converter margins without long-term fiber supply agreements binding food service operators to standardized tray formats. Italy's National Packaging Consortium enforces extended producer responsibility fee structures that favor certified compostable packaging portfolios. The Emilia-Romagna packaging district concentrates recycled paper-based capacity serving mid-tier regional bakery chains through wholesale distribution channels.
Poland
Food service markets in Warsaw and Krakow remain underdeveloped for molded fiber clamshells relative to Western European saturation levels, presenting penetration opportunities for tray and container formats. Poland's alignment with EU Packaging and Packaging Waste Regulation timelines compresses substitution schedules for quick-service operators. The Silesian industrial region attracts capacity expansion from converters seeking lower-cost manufacturing positions with access to Central European distribution networks.
Europe Molded Fiber Packaging Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-package specialists with captive fiber supply and hot-press tooling capabilities. Market concentration clusters around Nordic and Benelux players with backward integration into recycled paper collection and virgin pulp sourcing. Three archetypes dominate: integrated multinational converters with pan-European manufacturing footprints, regional specialists focused on agricultural residue processing, and protective packaging engineers serving electronics and medical device specifications. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure long-term supply agreements with quick-service restaurant chains ahead of EU extended producer responsibility implementation.
Among Nordic-based integrated converters, Huhtamaki Oyj and Brødrene Hartmann A/S exemplify the pulp-to-package archetype with manufacturing footprints spanning Finland and Denmark respectively. Mondi Group occupies a position bridging kraft paper and molded fiber hybrid solutions that extend fiber packaging portfolios into premium consumer segments. These three represent the tier of players consolidating direct procurement relationships with multinational food service operators across Germany, France, and the British Isles.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Brødrene Hartmann A/S |
| Sonoco Products Company |
| Pactiv Evergreen |
| Omni-PAC Group UK |
| Mondi Group |
| PulpWorks |
| Molded Fiber Solutions |
| Robert Cullen Ltd |
| Others |
Supply & Pricing Matrix
Family-owned Nordic converters with captive pulp sourcing anchor supply discipline across the European molded fiber packaging market, translating fiber cost stability into contract pricing power against spot-market dependent competitors serving quick-service restaurant chains in Germany and France.
Pricing Analysis
Value-based pricing anchored to compostability certification tiers stratifies the European molded fiber packaging market into three distinct levels. Premium tiers command substantial markups for CE-marked food-contact formats with bio-based barrier coatings that satisfy ECHA's evolving per- and polyfluoroalkyl substance restrictions, while standard grades serve high-volume quick-service restaurant contracts through long-term offtake agreements. Price differentiation stems from certification grade and volume scale, with agricultural fiber routes undercutting virgin pulp on unit economics. Cost compression in recycled paper tiers intensifies because old corrugated containerboard price swings in Iberian and Italian collection markets squeeze converter margins. Food service operators in the British Isles demonstrate highest price sensitivity, whereas pharmaceutical cold-chain buyers accept premium positioning for dimensional stability specifications.
Supply Chain Analysis
Recycled paper supply rests on collection infrastructure across Germany, France, and Italy, where old corrugated containerboard streams feed converter capacity with varying quality consistency. Virgin wood pulp draws from Nordic and Baltic forest operations, while sugarcane bagasse processing expands across Southern European farming regions in Spain and Portugal. Raw material dependencies span agricultural residue streams, specialty barrier coating chemistries, and precision hot-press tooling fabricated predominantly in German industrial clusters. Single-source vulnerability concentrates in fluorine-free oil-resistant additive supply ahead of REACH enforcement phases. Distribution runs through direct procurement relationships between multinational quick-service chains and integrated converters, displacing traditional wholesale intermediaries across UK and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European molded fiber packaging market constitutes a vertical-integration race where control over agricultural residue processing and captive pulp molding capacity determines margin capture ahead of extended producer responsibility implementation.
For Market Incumbents: Deepen backward integration into sugarcane bagasse processing across Southern European farming regions to secure feedstock cost advantages against recycled paper price volatility. Expand hot-press tooling fabrication partnerships in German industrial clusters to compress 18-24 month capacity lead times threatening responsiveness to quick-service restaurant demand surges. ECHA's per- and polyfluoroalkyl substance restrictions represent the critical regulatory threat requiring bio-based barrier coating R&D investment to maintain food-contact certification portfolios. For New Entrants and Emerging Players: The EU Packaging and Packaging Waste Regulation in Poland and Romania opens a window for clamshell format penetration in underdeveloped Central European food service markets relative to Western European saturation levels. Target pharmaceutical cold-chain insulated shippers as a premium white-space segment with limited incumbent competition and specification barriers that agricultural fiber can satisfy. Pursue direct procurement relationships with mid-tier regional bakery chains as a go-to-market angle bypassing consolidated supplier panels at multinational quick-service chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor agricultural residue processing specialists in Iberian and Italian markets facing recycled paper cost volatility without long-term fiber supply agreements. The five-to-ten year viability window favors converters with integrated pulp-to-package capabilities and established laboratory partnerships for CE marking conformity assessment. Watch EPR fee structure implementation timelines across EU member states as the decisive inflection indicator for first-mover advantage in certified compostable packaging portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Processing | Captive sugarcane bagasse supply in Spain and Portugal insulates margins from recycled paper price swings. |
| Bio-Based Barrier Coating R&D Partnership | Collaboration with chemical developers ahead of ECHA enforcement secures compliant food-contact material portfolios. |
| Direct Procurement Relationship Expansion | Long-term volume commitments with McDonald's and Burger King displace wholesale intermediaries across British markets. |
| Hot-Press Tooling Capacity Addition | German industrial cluster partnerships compress 18-24 month lead times constraining responsiveness to demand surges. |
| Pharmaceutical Cold-Chain Format Development | Insulated molded fiber shippers for temperature-sensitive biologics access premium segments with limited competition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this European molded fiber packaging market analysis, combining primary interviews with plant managers at integrated converters, procurement leads at quick-service restaurant chains, distribution channel partners, and technical R&D directors with secondary validation against CE marking databases, ECHA substance restriction notifications, and EU Packaging and Packaging Waste Regulation implementation documents. Bottom-up fiber supply modeling and top-down food service demand estimation were triangulated to establish volume and value benchmarks.
Data-stream reconciliation across material-grade supply curves, end-use demand segmentation, and regional regulatory implementation timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user industry, material sourcing route, and distribution channel structure. CAGRs were derived from fiber supply expansion trajectories and substitution elasticity estimates for expanded polystyrene displacement under EU Green Deal mandates. Industry-specific forecast inputs incorporated EPR fee structure implementation schedules and REACH compliance deadlines for per- and polyfluoroalkyl substance restrictions.
The model assumes a particular technology adoption path; alternative pathways for heat-press molding automation and precision thermoforming capability would alter the outlook for premium ready-meal packaging penetration. Forecasts reflect assumptions regarding EU member state alignment with Packaging and Packaging Waste Regulation timelines and ECHA enforcement phases for fluorinated additive restrictions. A small set of named triggers—EPR fee differential implementation, agricultural fiber processing cost curves, and barrier coating chemistry breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market