
 Fiber Bale Packaging Film Market | 2026-2036
Fiber Bale Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Bale Packaging Film Market Foresight
Market Context
Advanced multilayer coextrusion technology is reshaping fiber bale packaging film manufacturing, enabling thinner gauges with equivalent tensile strength and puncture resistance. Stein Fibers, Ltd. leverages vertical integration from resin sourcing to finished film production, sustaining cost advantages across agricultural supply chains. Bischof + Klein SE & Co. KG anchors European demand through specialized high-UV stabilization formulations for extended field exposure. Lenzing Plastics GmbH & Co KG differentiates via bio-based feedstock integration, occupying a niche in premium sustainable packaging segments.
Technical Definition and Segment Structure
Fiber bale packaging film denotes engineered polymeric sheeting designed to encase compressed agricultural fibers, typically manufactured in 20-50 micron thicknesses with 150-500% elongation capacity to accommodate irregular bale geometries and maintain anaerobic conditions for silage fermentation. Stretch film commands the largest volume share within product type segmentation due to its mechanical cling properties and equipment compatibility across existing farm infrastructure, while biodegradable materials represent the fastest-expanding material category as compostability certifications unlock premium pricing in regulated European and North American jurisdictions. Moisture barrier film segments concentrate margin pools where vapor transmission rates below 5 g/m²/day justify specialized coextruded constructions for high-value forage preservation.
Regulatory Framework
EPA agricultural plastic waste guidelines and EU REACH chemical registration requirements are tightening compliance burdens for conventional polyethylene formulations, redirecting R&D investment toward certified biodegradable alternatives. FDA indirect food contact regulations and ISO 9001 quality management standards further constrain material selection for bale films entering dairy and meat production supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and bioplastics certification schemes to anticipate procurement specification shifts before mandates crystallize into binding requirements.
Market Dynamics
Multilayer coextrusion technology is compressing film gauges while preserving mechanical performance, forcing capital retooling across mid-tier manufacturers and widening the gap between integrated resin producers and pure-play converters.
Growth Catalysts
- EPA Agricultural Plastic Waste Guidelines:Federal pressure on polyethylene disposal is redirecting procurement budgets toward certified compostable alternatives, expanding addressable demand for bio-based film formulations.
- Silage Fermentation Requirements:Dairy operations in Wisconsin and New York demand vapor transmission rates below 5 g/m²/day, pulling specialized five-layer coextruded constructions into premium forage preservation applications.
- Canadian Prairie Expansion:Large-scale hay operations across Alberta and Saskatchewan are consolidating farm numbers while increasing per-film bale volumes, concentrating equipment-compatible stretch film demand.
Market Restraints
- Ethylene Feedstock Volatility:Crude oil price swings transmit directly to polyethylene resin contracts, squeezing margin predictability for non-integrated converters lacking captive ethylene supply.
- UV Stabilizer Supply Concentration:Hindered amine light stabilizer production clusters in BASF and Songwon facilities, creating single-source vulnerability for films requiring 12+ month field exposure durability.
- Mechanical Recycling Contamination:Soil and moisture residues on used agricultural film degrade reprocessed polyethylene quality, limiting circular economy pathways and elevating virgin resin dependency.
Strategic Opportunities
- Minnesota-Texas Dairy Corridor:Underpenetrated mid-size operations between the Upper Midwest and Southwest present equipment upgrade cycles compatible with next-generation biodegradable film trials.
- USDA BioPreferred Program:Federal procurement preference for certified biobased products creates a mandated demand channel for films meeting ASTM D6866 testing standards.
- IoT-Enabled Bale Monitoring:Integration of RFID temperature sensors with packaging films enables premium service bundling for high-value alfalfa and equine forage segments.
Industry Challenges
- Multilayer Extrusion Technician Scarcity:Coextrusion die calibration and layer ratio optimization require specialized polymer processing expertise that vocational programs have not scaled to match equipment deployment rates.
- Compostability Certification Timelines:BPI and TÜV OK compost HOME certifications demand 180-day field and laboratory testing cycles, delaying product launches and compressing commercialization windows against faster conventional film iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Bale Packaging Film Market |
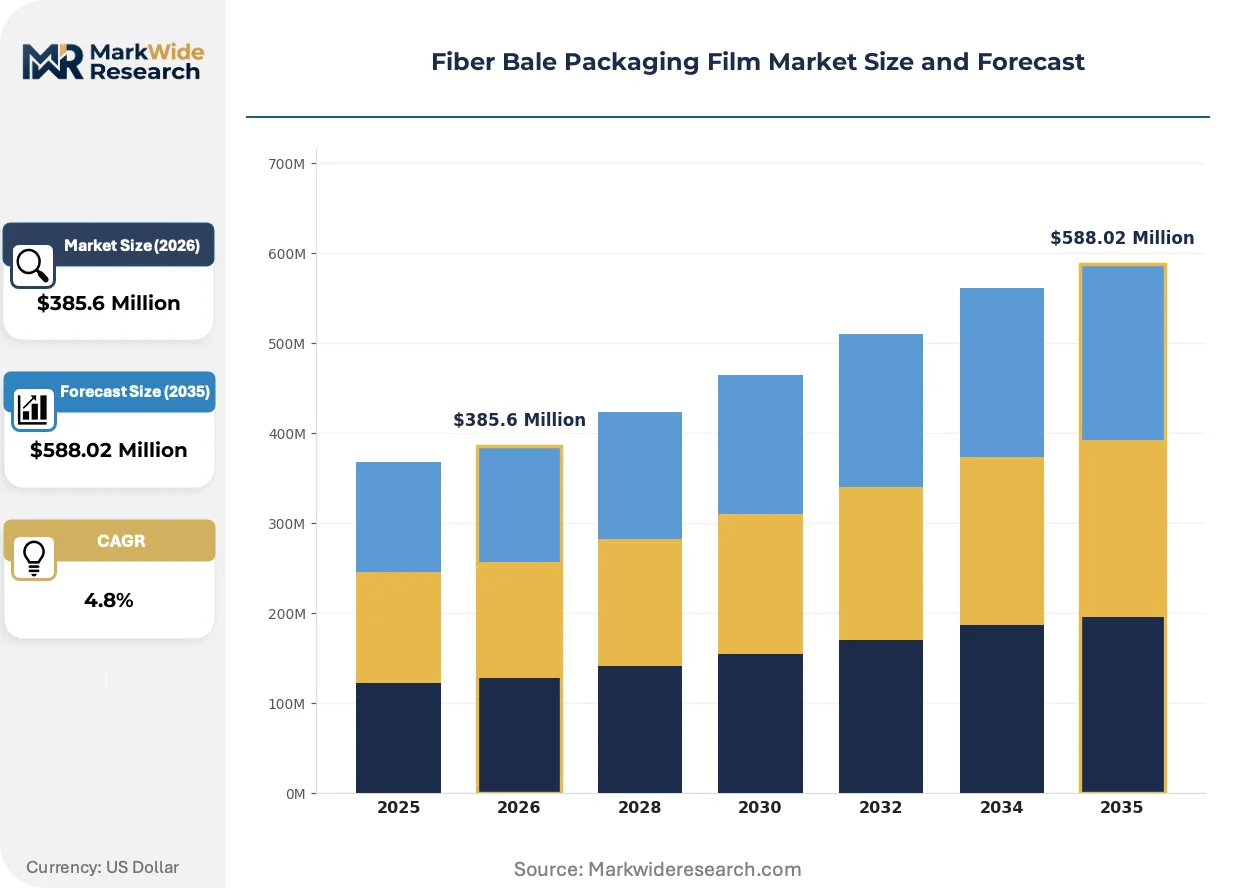
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Pallet Wrap, Moisture Barrier Film Material: Polyethylene, Polypropylene, Nylon, Biodegradable Materials End User: Agriculture, Food & Beverage, Textile, Manufacturing Application: Bale Wrapping, Surface Protection, Shipping, Storage |
| Companies Covered | Stein Fibers, Ltd., Bischof + Klein SE & Co. KG, Lenzing Plastics GmbH & Co KG, Conitex, Balemaster, Sonoco Products Company, Proag Products Ltd., AUTEFA, ITW Signode India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Bale Packaging Film Market Shifts & Advancements
Film manufacturing is pivoting toward thinner-gauge, higher-performance constructions while regulatory pressure accelerates material substitution timelines and buyer procurement models favor total-cost-of-ownership metrics over unit pricing.
Five-layer coextrusion with ethylene-vinyl alcohol core barriers is migrating from premium silage applications into standard hay wrapping as dairy cooperatives in Vermont and Pennsylvania consolidate purchasing and demand extended anaerobic preservation. Equipment manufacturers including Kuhn and Claas are calibrating stretch wrappers for 20-micron films, enabling 30% raw material reduction per bale without puncture failure.
REACH chemical registration requirements for hindered amine light stabilizers are forcing reformulation of UV-resistant films destined for European export, with ECHA substance evaluation timelines creating 18-month approval gaps that block market access. German and Dutch distributors are pre-qualifying alternative stabilizer packages to avoid supply interruptions during regulatory transition periods.
Cooperative procurement platforms in the Wisconsin Dairy Business Association are displacing individual farm purchasing through volume aggregation and specification standardization, compressing supplier margins while demanding extended payment terms and technical field support. These buying collectives prioritize films with documented biodegradation pathways, shifting competitive differentiation toward certification depth rather than gauge or clarity metrics alone.
Fiber Bale Packaging Film Market Segmentation
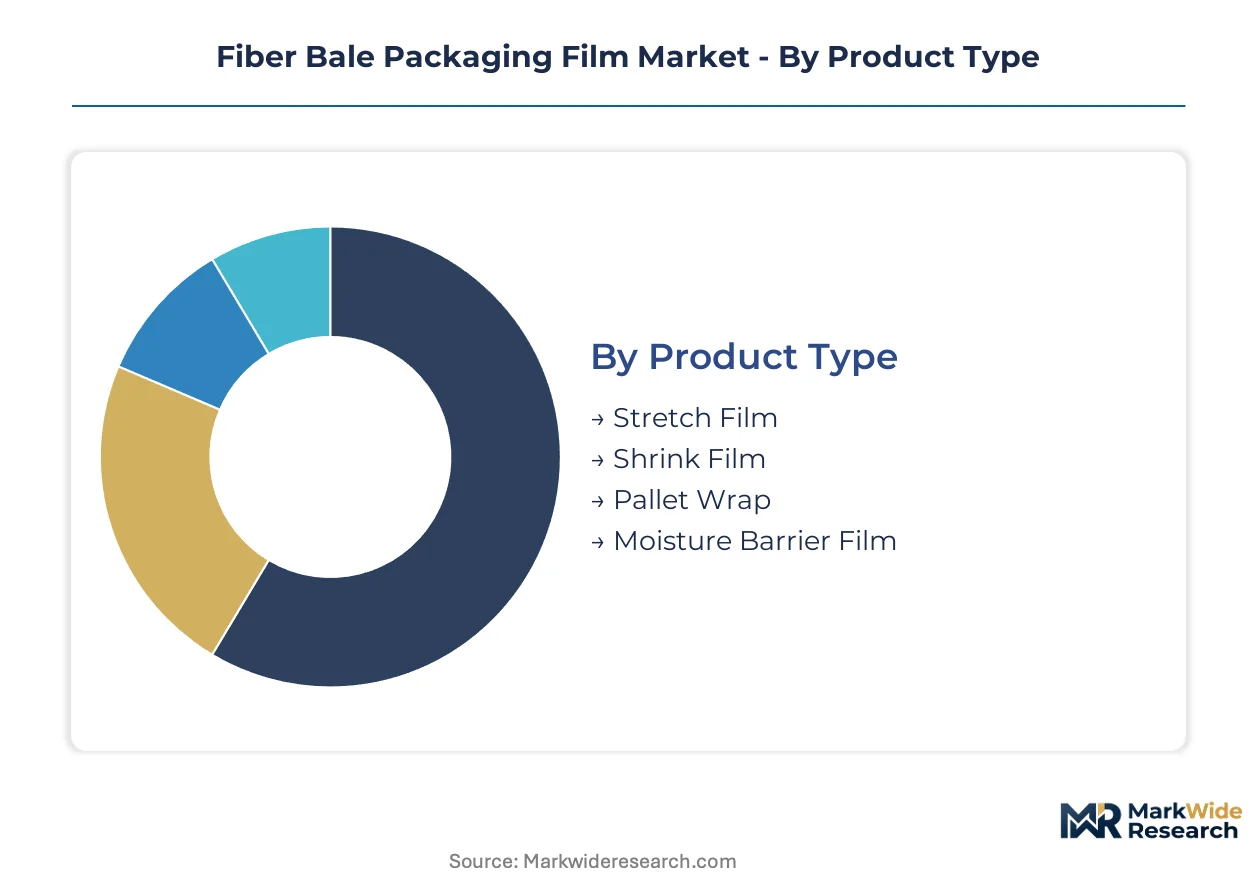
Segmentation in fiber bale packaging film reflects divergent technical requirements across agricultural preservation, industrial logistics, and emerging sustainability mandates. Each dimension—product construction, material chemistry, end-use environment, and functional application—carries distinct specification pressures that reshape supplier R&D priorities and procurement specifications.
Product Type:
Use-case spectrum spans mechanical containment for field-wrapped silage through vapor-sealed long-distance transport of compressed textiles.
- Stretch Film:Manufactured with 150-500% elongation capacity and mechanical cling properties, this construction dominates dairy and livestock operations across Wisconsin and New York where equipment-compatible wrapping demands standardized gauge consistency. Claas and Kuhn wrapper calibration for 20-micron specifications is compressing raw material inputs while preserving puncture resistance.
- Moisture Barrier Film:Five-layer coextruded constructions with ethylene-vinyl alcohol cores achieve vapor transmission rates below 5 g/m²/day, commanding premium positioning in high-value alfalfa and equine forage preservation where anaerobic fermentation quality determines nutritional value.
- Shrink Film:Heat-activated contraction properties suit palletized textile bales and manufacturing feedstocks where dimensional stability during transit outweighs field exposure durability requirements.
- Pallet Wrap:Standardized 17-23 micron specifications serve logistics-intensive food and beverage distribution networks, prioritizing tear propagation resistance over UV stabilization.
The dominant share belongs to Stretch Film, while Moisture Barrier Film is closing the gap fastest.
Material:
Cost tier stratification separates commodity resin formulations from certified biodegradable alternatives commanding 40-60% price premiums.
- Polyethylene:Linear low-density and metallocene grades supply 80%+ of agricultural volume, with ethylene feedstock volatility directly transmitting to converter margin predictability. Stein Fibers' captive resin sourcing insulates against crude oil price swings.
- Biodegradable Materials:PLA-PHA blends and starch-based formulations are expanding most quickly under EPA agricultural plastic waste pressure and BPI certification requirements, though 180-day compostability testing timelines delay commercialization against conventional film iterations.
- Polypropylene:Higher stiffness and temperature resistance suit textile manufacturing applications where bale compression forces exceed polyethylene mechanical limits.
- Nylon:Niche deployment in puncture-critical surface protection for high-value synthetic fiber shipments where abrasion resistance justifies material cost multiples.
Polyethylene retains volume leadership, though Biodegradable Materials are gaining share fastest on regulatory tailwinds.
End User:
Customer type concentration determines specification stringency, from FDA-compliant dairy supply chains to commodity textile logistics.
- Agriculture:Dairy cooperatives in the Wisconsin Dairy Business Association are aggregating procurement through cooperative platforms, demanding documented biodegradation pathways and extended payment terms. Silage fermentation requirements pull five-layer coextruded constructions into premium forage preservation.
- Food & Beverage:FDA indirect food contact regulations constrain material selection for bale films entering dairy and meat production supply chains, with ISO 9001 quality management standards further tightening compliance.
- Textile:Synthetic fiber manufacturers prioritize UV stabilization and dimensional stability for outdoor storage of compressed raw materials.
- Manufacturing:Industrial feedstock bales tolerate thinner gauges where mechanical recycling contamination risks are lower than agricultural soil exposure.
Agriculture commands the dominant position, while Food & Beverage is climbing fastest on traceability and safety certification demands.
Application:
Functional purpose dictates performance tier, from anaerobic preservation through transient shipping protection.
- Bale Wrapping:Field-deployed mechanical containment requires 12+ month UV durability through hindered amine light stabilizer packages, with BASF and Songwon supply concentration creating single-source vulnerability for extended exposure specifications.
- Storage:Long-duration anaerobic conditions for silage fermentation demand vapor transmission control that five-layer coextrusion technology is migrating from premium into standard hay wrapping applications.
- Surface Protection:Abrasion and moisture shielding for textile and manufacturing feedstocks prioritizes puncture resistance over elongation capacity.
- Shipping:Transit-oriented applications emphasize tear propagation resistance and pallet stability for intermodal logistics.
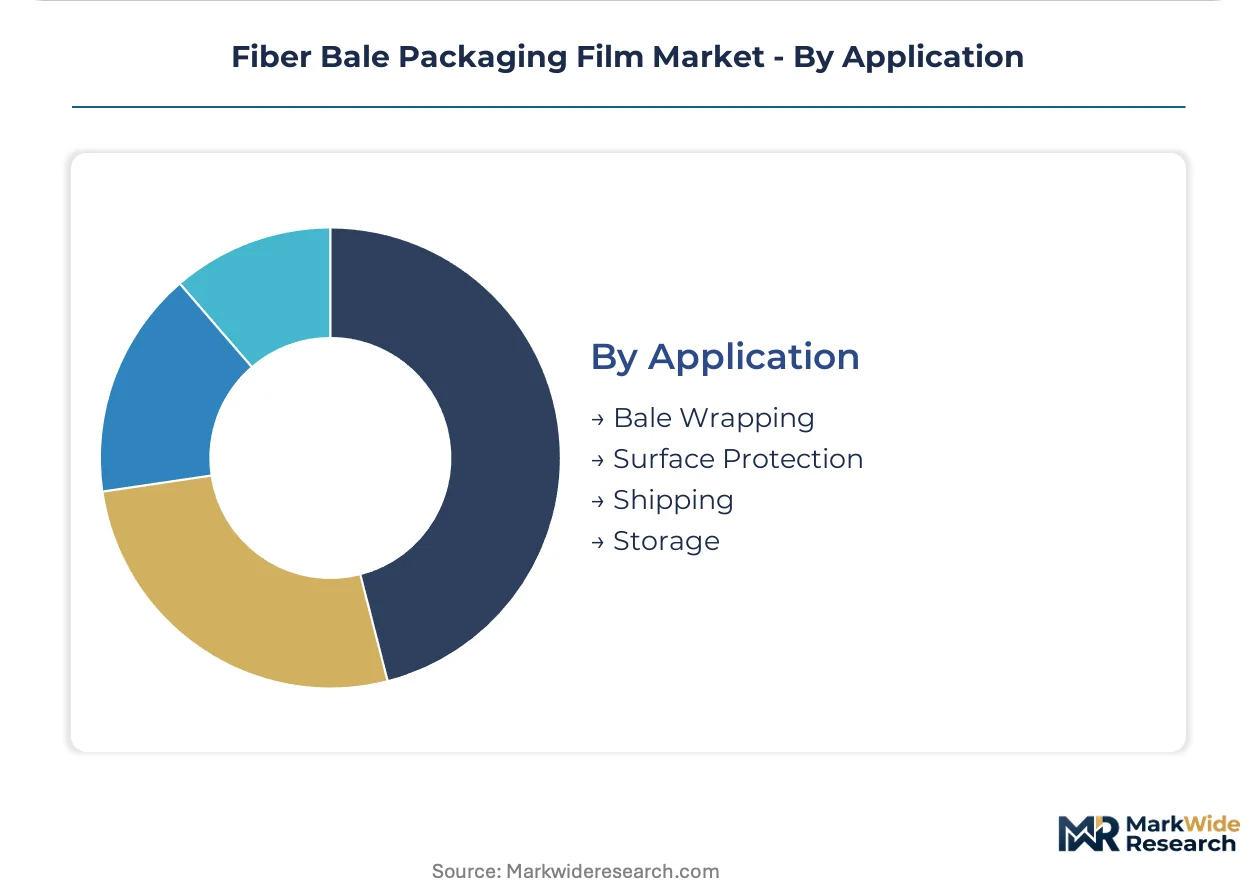
Bale Wrapping holds the largest share, while Storage applications are expanding most quickly on dairy cooperative consolidation and extended preservation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fiber bale packaging film tilt toward net production surplus in resin-integrated economies, with agricultural demand density determining regional consumption gravity. Trade patterns concentrate polyethylene-based formulations in dairy-intensive temperate zones while biodegradable alternatives penetrate regulated European and North American jurisdictions.
United States
Dairy cooperatives across Wisconsin and New York consolidate procurement through volume aggregation platforms, pulling five-layer coextruded constructions into premium forage preservation. EPA agricultural plastic waste guidelines redirect federal procurement toward certified compostable alternatives under USDA BioPreferred program mandates. The Corn Belt cluster from Minnesota through Iowa anchors stretch film consumption for large-scale hay and silage operations.
Germany
REACH chemical registration requirements for hindered amine light stabilizers force reformulation of UV-resistant films destined for extended field exposure. ECHA substance evaluation timelines create 18-month approval gaps that block market access for non-compliant formulations. The Bavarian and Lower Saxony dairy belts concentrate demand for high-UV stabilization films through specialized distribution networks.
Canada
Large-scale hay operations across Alberta and Saskatchewan consolidate farm numbers while increasing per-film bale volumes, concentrating equipment-compatible stretch film demand. Health Canada and PMRA guidelines on agricultural plastics residue management elevate compostability certification requirements for imported films. The Prairie provinces cluster represents the densest North American consumption zone outside the US Corn Belt.
France
Dairy operations in Brittany and Normandy demand vapor transmission rates below 5 g/m²/day for extended anaerobic preservation, pulling specialized coextruded constructions into premium segments. EU Green Deal agricultural sustainability targets accelerate substitution timelines for conventional polyethylene in bale wrapping applications. The northwestern dairy corridor anchors French consumption through cooperative procurement structures.
China
Dual carbon goals and MEE agricultural plastic pollution action plans redirect domestic film production toward biodegradable feedstock integration. NMPA and GB standards on food-contact materials constrain resin selection for bale films entering dairy supply chains. The Yangtze River Delta manufacturing cluster supplies both domestic agricultural demand and export formulations for Southeast Asian markets.
Fiber Bale Packaging Film Market Competitive Landscape
On the supply side, the industry is bifurcating between resin-integrated majors and specialized converters lacking captive ethylene supply. Mid-tier manufacturers face capital retooling pressures as multilayer coextrusion technology compresses film gauges while preserving mechanical performance. Two strategic archetypes dominate: vertically integrated resin-to-film producers with feedstock cost insulation, and technology-focused specialists commanding premium positioning through bio-based feedstock integration. Competitive moves concentrate on backward integration into resin sourcing and geographic expansion through distributor pre-qualification partnerships.
Among European specialists, Bischof + Klein SE & Co. KG and Lenzing Plastics GmbH & Co KG occupy positions within the premium sustainable packaging segment, with the latter exemplifying bio-based feedstock integration archetypes. Stein Fibers, Ltd. represents the vertically integrated model, leveraging captive resin sourcing to sustain cost advantages across agricultural supply chains. These three entities anchor the competitive structure, with their respective strategic postures reflecting broader industry segmentation between commodity scale and sustainability premium positioning.
| Leading Market Players |
|---|
| Stein Fibers, Ltd. |
| Bischof + Klein SE & Co. KG |
| Lenzing Plastics GmbH & Co KG |
| Conitex |
| Balemaster |
| Sonoco Products Company |
| Proag Products Ltd. |
| AUTEFA |
| ITW Signode India Limited |
| Others |
Supply & Pricing Matrix
Ethylene feedstock concentration in Gulf Coast petrochemical complexes directly determines margin distribution across converter tiers, with integrated resin producers capturing value pools that pure-play film manufacturers cannot access.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in the mid-tier segment is intensifying because cooperative procurement platforms aggregate demand and squeeze supplier margins. Dairy cooperatives exhibit the highest price sensitivity due to consolidated purchasing power, while equine forage operations demonstrate lower sensitivity given nutritional value preservation priorities.
Supply Chain Analysis
Contract manufacturing capacity clusters with Stein Fibers' captive resin operations and specialized converters in Germany and Canada. Raw material flows draw from linear low-density polyethylene resin, hindered amine light stabilizers, and ethylene-vinyl alcohol barrier resins. Single-source vulnerability for UV stabilizer supply from BASF and Songwon facilities creates structural risk. Distribution runs through agricultural cooperative platforms and specialized film distributors serving dairy belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment, as EPA agricultural plastic waste guidelines and compostability certification requirements erect compliance barriers that favor incumbent technical depth.
For Market Incumbents: Entrench market position through backward integration into bio-based resin sourcing and accelerated BPI certification investment. Biodegradable material substitution threatens conventional polyethylene volumes, requiring preemptive capacity reallocation toward PLA-PHA blend production. Channel control through exclusive distributor pre-qualification partnerships in the Wisconsin Dairy Business Association locks out emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in the Minnesota-Texas dairy corridor where mid-size operations lack cooperative procurement coverage and equipment upgrade cycles create trial opportunities for next-generation biodegradable formulations. IoT-enabled bale monitoring integration offers a differentiated go-to-market angle for premium service bundling. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated resin-to-film producers with captive ethylene supply and established compostability certification pipelines. Long-term viability hinges on regulatory tailwinds persisting across North American and European jurisdictions. Watch for EPA mandate crystallization into binding extended producer responsibility frameworks as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resin Sourcing | Captive PLA-PHA feedstock supply insulates margin pools from crude oil volatility. |
| BPI Certification Acceleration | 180-day testing completion unlocks premium positioning in EPA-regulated procurement channels. |
| Cooperative Platform Partnership | Wisconsin Dairy Business Association volume aggregation secures offtake commitment and specification influence. |
| IoT Sensor Integration Development | RFID temperature monitoring enables premium service bundling for high-value alfalfa segments. |
| Five-layer Coextrusion Capacity Expansion | Specialized barrier film production captures vapor transmission rate specifications below 5 g/m²/day. |
Research Methodology
Operator-level perspectives from agricultural cooperative procurement managers, dairy farm operations directors, multilayer extrusion technicians, resin sourcing executives, and distribution channel partners anchored the qualitative base. Primary fieldwork combined with secondary validation through EPA agricultural plastic waste guidelines, USDA BioPreferred program specifications, customs and trade data on polyethylene resin flows, and SEC filings from integrated resin producers. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Scenario-bracketing across regulatory acceleration and feedstock volatility bounds framed the analytical envelope. Segmentation dimensions spanned product construction type, material chemistry tier, end-use environment, and functional application purpose across the projection horizon. CAGRs derived from installed equipment base expansion, per-film bale volume trends, and substitution elasticity parameters for biodegradable alternatives. Silage fermentation quality requirements and UV stabilization durability specifications informed industry-specific forecast inputs.
Stress conditions across ethylene price bands, compostability certification timeline delays, and cooperative procurement consolidation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and equipment replacement cycle timing. Quarterly review of EPA mandate progression, BPI certification backlog indicators, and dairy cooperative procurement platform expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market