
 Malaysia and Thailand Thermoformed Plastic Market | 2026-2036
Malaysia and Thailand Thermoformed Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia and Thailand Thermoformed Plastic Market Foresight
Aftermarket packaging redesign services is rewriting margin capture across the value chain. SCG Packaging Public Company Limited anchors Thailand's integrated pulp-to-sheet infrastructure. Beltec Sdn Bhd specializes in precision medical-grade forming for diagnostic kit trays. Sonoco Products Company extends its North American technical standards into Southeast Asian co-manufacturing partnerships.
Thermoformed plastic denotes sheet stock heated above its glass transition temperature, vacuum- or pressure-drawn over a mold, then trimmed into rigid packaging with wall thickness typically ranging from 0.005 to 0.125 inches. This process yields lightweight, barrier-resistant containers for temperature-sensitive and sterile contents. Food Packaging dominates application value as quick-service chains and ready-meal brands scale chilled distribution networks. PET sheet commands material preference due to clarity, recyclability alignment with ASEAN circular economy roadmaps, and compatibility with modified-atmosphere sealing. Trays lead product type volume, though container formats for medical supplies are gaining faster growth rates driven by hospital sterilization protocol upgrades.
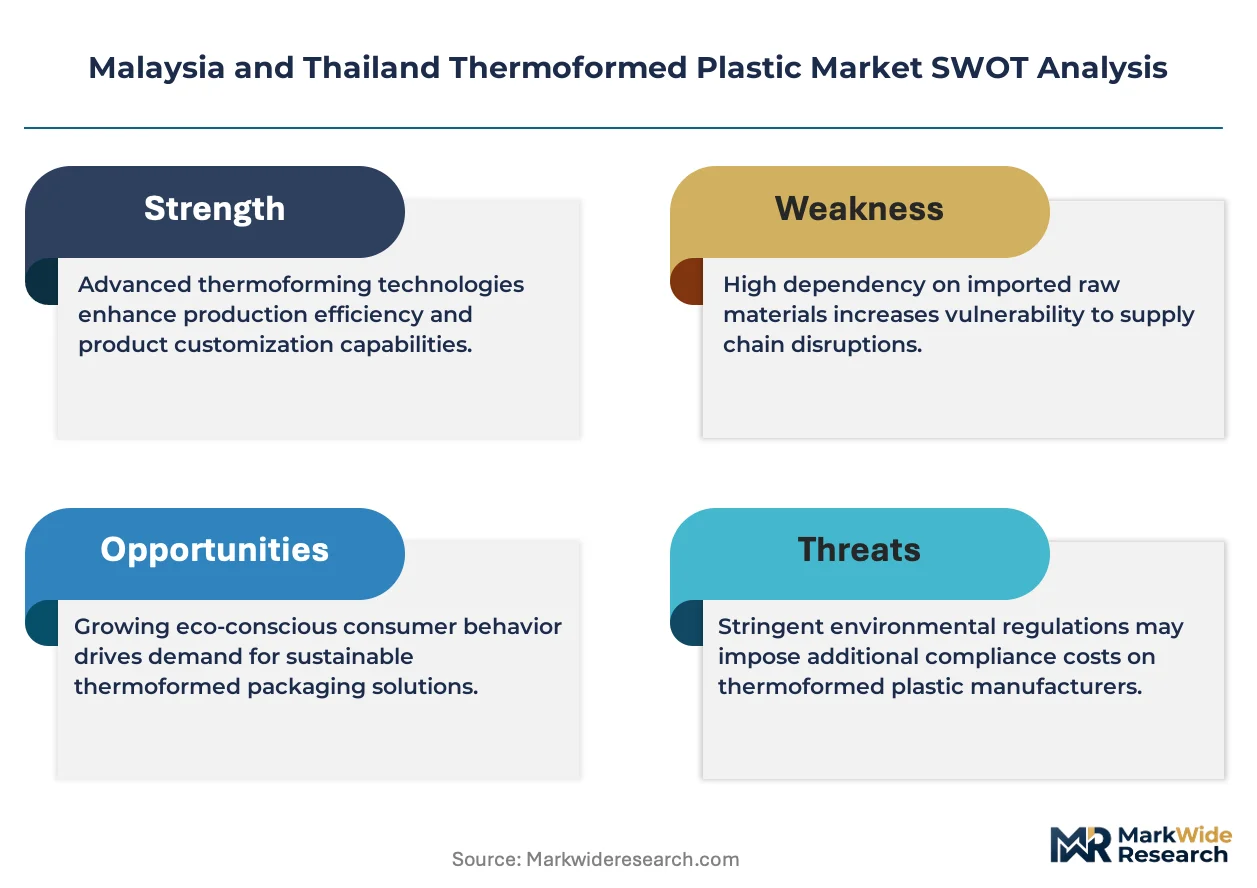
Thailand's Ministry of Industry enforces factory licensing under the Factory Act B.E. 2535 for thermoforming operations above specified capacity thresholds, while Malaysia's Department of Environment administers Environmental Quality Act schedules governing VOC emissions from sheet extrusion. Both frameworks elevate capital requirements for new entrants and favor producers with in-house recycling and emission control systems. Stakeholders must track evolving extended producer responsibility drafts in both jurisdictions to anticipate compliance cost shifts and recyclate content mandates.
Market Dynamics
Thailand's Board of Investment incentives for recycled PET sheet lines are redirecting capital flows and compressing lead times for circular-economy-compliant capacity. This policy lever is restructuring competitive positioning by favoring producers with integrated recycling and extrusion assets over toll-dependent converters.
Growth Catalysts
- Environmental Quality Act schedules:Malaysia's Department of Environment enforces VOC emission controls from sheet extrusion, elevating capital barriers that favor established producers with captive emission control systems.
- Quick-service chain expansion:Food service operators across both countries are scaling cold-chain packaging procurement for chilled ready-meal distribution networks.
- Klang Valley corridor concentration:Electronics and food processing clusters co-locate in Malaysia's industrial corridor, generating dense demand for precision thermoformed trays and diagnostic kit packaging.
Market Restraints
- Recycled PET flake supply concentration:Post-consumer PET collection infrastructure remains concentrated in Bangkok and Kuala Lumpur metropolitan zones, creating feedstock access disparities for provincial converters.
- Factory Act B.E. 2535 licensing thresholds:Thailand's Ministry of Industry mandates factory licensing for thermoforming operations above specified capacity, extending regulatory approval timelines for capacity expansion.
- Glass and aluminum substitution:Premium food brands in both markets retain rigid container preference for high-visibility shelf applications, capping PET tray penetration in certain product categories.
Strategic Opportunities
- Extended producer responsibility drafts:Both jurisdictions are developing recyclate content mandates that will create first-mover advantage for producers with in-house rPET sheet lines.
- Medical sterilization protocol upgrades:Hospital supply chains are accelerating demand for barrier-grade thermoformed containers with validated sterilization compatibility.
- Modified-atmosphere sealing convergence:Tray-sealing technology integration with thermoforming lines is opening ready-meal and fresh-protein packaging segments previously served by pre-formed container suppliers.
Industry Challenges
- Vacuum-forming tooling design expertise:Precision medical-grade forming requires specialized mold flow simulation capabilities that remain scarce in the regional workforce.
- Multi-layer sheet coextrusion capex:Barrier-enhanced structures for oxygen-sensitive contents require capital-intensive cast film lines that strain mid-scale producer balance sheets.
- ISO 15378 certification timelines:Pharmaceutical primary packaging qualification processes extend 18-24 months, compressing revenue realization for medical segment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia and Thailand Thermoformed Plastic Market |
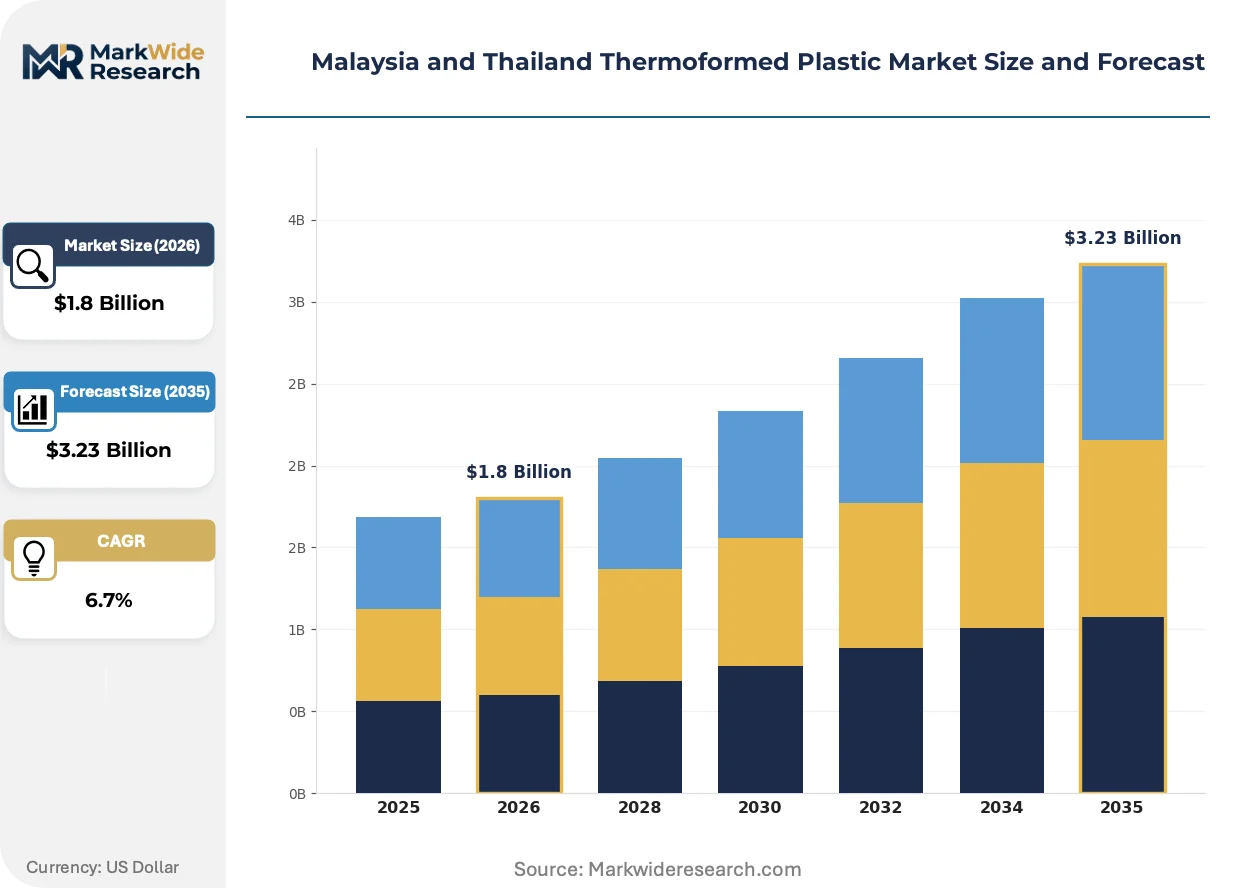
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Trays, Containers, Tubs Application: Food Packaging, Medical Supplies, Consumer Goods, Automotive Parts Material: ABS, PET, PVC, PS End User: Manufacturers, Retailers, Distributors, Food Service |
| Companies Covered | Season Group, Vitalo Packaging (Thailand) Ltd., Beltec Sdn Bhd, Sonoco Products Company, SCG Packaging Public Company Limited, Nizza Plastics, TOLI PACKAGING, Thai Plastic and Chemicals Public Company Limited, Guang Heng Plastic Industries Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia and Thailand Thermoformed Plastic Market Shifts & Advancements
Active developments across material science, regulatory compliance architecture, and buyer procurement models are compressing traditional value chain boundaries. These shifts favor integrated producers capable of spanning sheet extrusion through precision forming.
Direct-to-sheet extrusion with inline thermoforming is rendering obsolete the conventional two-stage model of merchant sheet purchase followed by conversion. Electronics manufacturers in Penang and Bangkok are adopting this integrated approach to reduce handling damage and lot-to-lot thickness variation. The structural consequence is margin compression for standalone thermoformers lacking captive extrusion capacity.
Thailand's Factory Act B.E. 2535 amendments under consideration would mandate real-time emissions monitoring for sheet extrusion operations above revised tonnage thresholds. Industrial consequence includes accelerated capital deployment into regenerative thermal oxidizer systems. Food packaging producers in the Eastern Economic Corridor are responding by consolidating operations into fewer, larger licensed facilities.
Brand-led sustainability scorecards now dominate packaging supplier selection for multinational quick-service chains operating across the Malay Peninsula. Centralized procurement teams are displacing distributed restaurant-level purchasing, consolidating volume with converters demonstrating verified rPET content and carbon footprint documentation. This concentration is most visible in Kuala Lumpur and Bangkok metropolitan supply contracts.
Malaysia and Thailand Thermoformed Plastic Market Segmentation
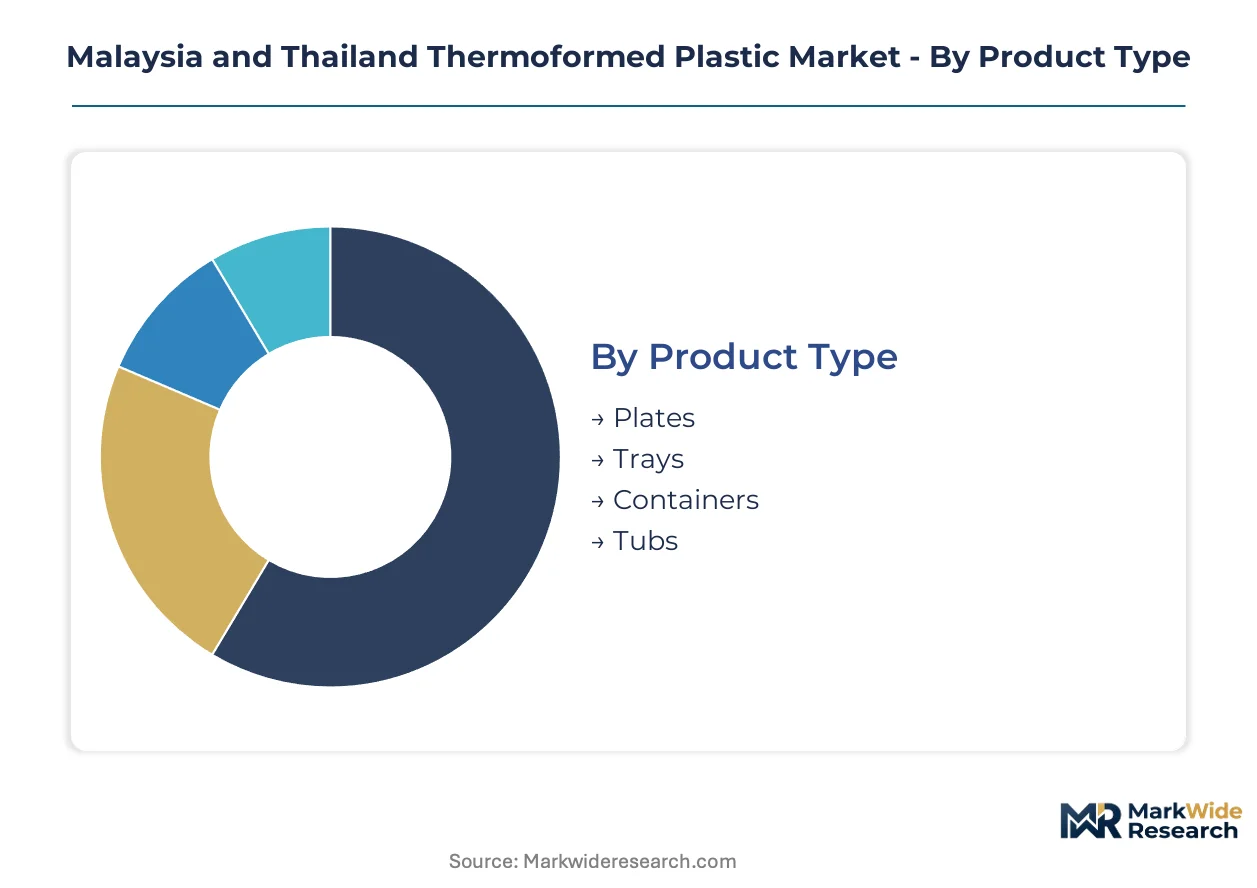
Segmentation in the Malaysia and Thailand thermoformed plastic market exposes how material specifications, product geometries, and end-use sterilization requirements create divergent margin profiles across converters. Understanding these splits enables targeted capacity investment and regulatory compliance planning.
Product Type:
Product geometries span single-use disposables through reusable industrial formats, each demanding distinct mold complexity and cycle time economics.
- Plates:Shallow-draw geometries with wall thickness below 0.030 inches serve institutional catering and quick-service chains. Penang electronics corridor cafeterias and Bangkok hospital food courts concentrate procurement for portion-controlled meal delivery.
- Trays:Multi-cavity designs with ribbed reinforcement dominate precision component handling and medical kit organization. Klang Valley diagnostic manufacturers specify anti-static grades for semiconductor wafer transport, while Thai pharmaceutical distributors prioritize stackability for cold-chain logistics.
- Containers:Deep-draw formats with integrated lid retention clips address modified-atmosphere requirements for fresh proteins and ready-meals.
- Tubs:Large-volume formats with tamper-evident rims serve institutional food preparation and industrial chemical containment.
Established volume favors Trays; emerging adoption favors Containers.
Application:
Application segments separate commodity food service from regulated medical channels with divergent certification burdens and pricing power.
- Food Packaging:Barrier-grade PET structures with oxygen transmission rates below 0.5 cc/m²/day enable extended shelf-life for chilled ready-meals. Malaysian quick-service chains in Kuala Lumpur and Johor Bahru are consolidating procurement around verified rPET content thresholds.
- Medical Supplies:ISO 15378-compliant primary packaging for sterile devices requires validated sterilization compatibility and particulate control. Bangkok hospital network upgrades are accelerating demand for diagnostic kit trays with ethylene oxide and gamma radiation stability.
- Consumer Goods:Blister packs and clamshells for electronics and personal care items emphasize clarity and theft deterrence.
- Automotive Parts:Heavy-gauge ABS and TPO formats protect interior trim components during assembly plant logistics.
Food Packaging commands current volume leadership; Medical Supplies demonstrate the steepest expansion trajectory driven by hospital sterilization protocol harmonization.
Material:
Material selection balances optical clarity, impact resistance, recyclability credentials, and regulatory acceptance for food and medical contact.
- PET:Amorphous and crystalline grades deliver exceptional clarity and post-consumer recyclability alignment with ASEAN circular economy roadmaps. Thailand's Board of Investment incentives for rPET sheet extrusion are concentrating investment in Eastern Economic Corridor integrated lines.
- PS:General-purpose and high-impact grades offer lowest unit cost for disposable food service items with limited durability requirements.
- PVC:Rigid formulations with plasticizer-free medical grades retain niche positions in oxygen-barrier pharmaceutical blister packs.
- ABS:Terpolymer structures provide superior impact resistance and dimensional stability for automotive interior trim protection and electronic device housings.
PET dominates value capture; ABS maintains premium positioning in automotive and electronics logistics.
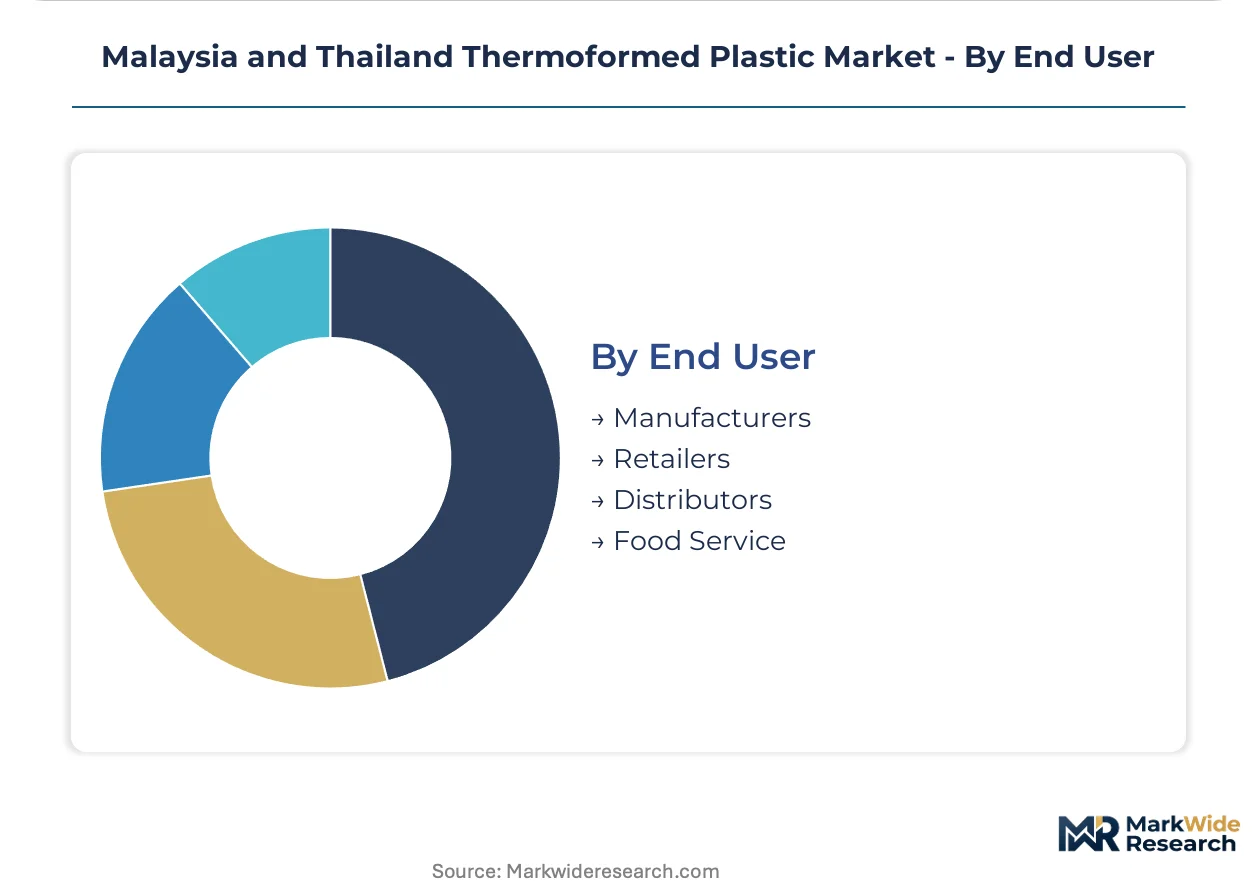
End User:
End user categories reflect procurement centralization trends and sustainability verification requirements reshaping supplier relationships.
- Food Service:Quick-service chains and institutional caterers are displacing distributed restaurant-level purchasing with centralized procurement teams demanding carbon footprint documentation. Kuala Lumpur and Bangkok metropolitan contracts now consolidate volume with converters demonstrating closed-loop rPET verification.
- Manufacturers:Electronics and medical device producers specify precision tolerances and lot traceability for component handling and sterile packaging.
- Retailers:Private-label ready-meal brands and fresh-protein counters drive modified-atmosphere tray specifications with shelf-life extension requirements.
- Distributors:Medical supply intermediaries aggregate fragmented hospital demand and manage inventory pooling for sterilization-compatible packaging formats.
Food Service procurement concentration is accelerating fastest; Manufacturer relationships retain longest contract duration and highest switching costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian buyers demonstrate acute price sensitivity in commodity food service disposables, whereas Thai medical device manufacturers absorb premium pricing for validated sterile packaging. This demand-elasticity contrast shapes capital deployment patterns across the Malay Peninsula.
Malaysia
Electronics manufacturers in Penang and Selangor drive precision tray demand for semiconductor wafer transport and diagnostic kit handling. The Department of Environment enforces Environmental Quality Act schedules governing VOC emissions from sheet extrusion operations. Klang Valley corridor clusters co-locate food processing and electronics packaging procurement, generating dense demand for multi-cavity thermoformed formats.
Thailand
Quick-service chains and ready-meal brands scale cold-chain packaging procurement for chilled distribution networks. The Board of Investment incentivizes recycled PET sheet extrusion lines through tax holidays and import duty exemptions. Eastern Economic Corridor integrated facilities concentrate rPET capacity investment, compressing lead times for circular-economy-compliant production.
Vietnam
Foreign-owned electronics assembly plants in Bac Ninh and Ho Chi Minh City generate pull-through for component handling trays and anti-static packaging formats. The Ministry of Natural Resources and Environment administers Circular 36 on plastic waste management, elevating recyclate content expectations. Northern industrial zones attract thermoforming investment serving Samsung and Foxconn supply chains.
Indonesia
Instant noodle and palm oil packaging converters in Java sustain volume demand for shallow-draw disposable formats. The Ministry of Industry's Making Indonesia 4.0 roadmap prioritizes packaging automation upgrades. Bekasi and Tangerang manufacturing belts concentrate mid-scale thermoforming operations serving domestic FMCG distribution.
Singapore
Pharmaceutical multinationals in Tuas and Changi demand ISO 15378-compliant primary packaging for sterile device export. The National Environment Agency mandates extended producer responsibility frameworks for plastic packaging waste. Biomedical manufacturing clusters drive specifications for barrier-grade containers with validated sterilization compatibility.
Malaysia and Thailand Thermoformed Plastic Market Competitive Landscape
Integrated pulp-to-sheet producers and standalone precision formers split the market along capability boundaries. Thailand's Factory Act licensing thresholds and Malaysia's emission control schedules elevate capital barriers, compressing the viable producer base. Three archetypes dominate: conglomerate-affiliated packaging divisions with captive resin supply, mid-scale regional specialists with medical-grade certification, and toll-dependent converters lacking extrusion assets. Competitive moves concentrate on backward integration into sheet extrusion and geographic expansion into Vietnam and Indonesia.
Among Thailand-based integrated producers, SCG Packaging Public Company Limited anchors domestic pulp-to-sheet infrastructure. Beltec Sdn Bhd occupies a specialist position within Malaysia's precision medical-grade forming segment. Sonoco Products Company represents North American technical standards extended through Southeast Asian co-manufacturing structures. These three exemplify how geographic origin and corporate structure map onto strategic positioning across the value chain.
| Leading Market Players |
|---|
| Season Group |
| Vitalo Packaging (Thailand) Ltd. |
| Beltec Sdn Bhd |
| Sonoco Products Company |
| SCG Packaging Public Company Limited |
| Nizza Plastics |
| TOLI PACKAGING |
| Thai Plastic and Chemicals Public Company Limited |
| Guang Heng Plastic Industries Sdn Bhd |
| Others |
Supply & Pricing Matrix
Overcapacity in Thailand's Eastern Economic Corridor sheet extrusion segment is compressing spot pricing for standard-grade PET while elevating premium tiers for integrated rPET-verified supply. This utilization divergence rewards converters with captive recycling assets and penalizes toll-dependent operators facing feedstock access premiums.
Pricing Analysis
Aftermarket packaging redesign services and extended technical support contracts now capture margin equivalent to 18-24 months of initial tray supply, shifting lifetime value toward service-tier bundling. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified medical-grade formats from commodity food service disposables, with brand-verified rPET content commanding additional uplift. Cost compression in standard-grade food packaging is intensifying because Bangkok and Kuala Lumpur procurement teams are consolidating volume around carbon-footprint documentation requirements. Quick-service chains demonstrate acute price sensitivity in shallow-draw disposables, while Thai hospital networks absorb premium positioning for validated sterile barrier systems.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities anchored by Thai banking consortiums are restructuring working capital requirements for mid-scale converters. Feedstock concentration in Thailand, Malaysia, and Vietnam shapes procurement risk profiles, with post-consumer PET flake collection infrastructure drawing from Bangkok and Kuala Lumpur metropolitan zones. Virgin PET resin, recycled PET flake, and multi-layer coextrusion equipment rest on single-source vulnerability from Chinese machinery suppliers and regional resin distributors. Distribution runs through Eastern Economic Corridor integrated facilities for Thai quick-service networks and Klang Valley co-located converters serving Penang electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates across ASEAN jurisdictions are disrupting legacy converter economics, with recyclate content thresholds becoming the decisive competitive filter.
For Market Incumbents: Insulate margin position through backward integration into rPET sheet extrusion ahead of Board of Investment incentive expiration, while consolidating toll-dependent conversion capacity into licensed facilities compliant with Factory Act B.E. 2535 amendments. Threats from glass and aluminum substitution in premium food visibility applications demand barrier-grade PET innovation investment. Channel control through direct-to-sheet extrusion with inline thermoforming locks in electronics manufacturer relationships in Penang and Bangkok.
For New Entrants and Emerging Players: Provincial Thai converters outside Bangkok metropolitan feedstock zones represent the most penetrable entry point, exploiting rPET flake supply disparities through mobile collection infrastructure partnerships. Malaysian medical-grade forming for diagnostic kit trays offers certification-barrier protection with 18-24 month ISO 15378 qualification timelines limiting competitive response. Go-to-market execution should target hospital supply chain intermediaries managing sterilization-compatible inventory pooling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive rPET sheet lines serving multinational quick-service chain centralized procurement contracts. Long-term viability over the next decade hinges on regulatory compliance infrastructure and verified circular economy credentials. Acquisition target archetype: mid-scale regional specialists with medical-grade certification and extrusion asset backing. The signal to watch is Board of Investment incentive restructuring affecting Eastern Economic Corridor capacity economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Sheet Extrusion | Captures Board of Investment tax holidays while meeting emerging recyclate content mandates. |
| ISO 15378 Certification Investment | Opens pharmaceutical primary packaging segments with 18-24 month competitive moats. |
| Modified-Atmosphere Sealing Technology Convergence | Penetrates ready-meal and fresh-protein segments previously served by pre-formed container suppliers. |
| Geographic Expansion into Vietnam | Positions for Samsung and Foxconn supply chain pull-through in Bac Ninh electronics corridors. |
| Regenerative Thermal Oxidizer Deployment | Anticipates Factory Act B.E. 2535 real-time emissions monitoring mandates for sheet extrusion operations. |
Research Methodology
The analysis maps food packaging, medical supplies, consumer goods, and automotive parts sub-sectors, each validated through plant managers at integrated extrusion facilities, procurement leads at multinational quick-service chains, and technical R&D directors at precision medical-grade formers. Primary interview intelligence triangulates against customs and trade data, Thailand Board of Investment incentive disclosures, Malaysian Department of Environment Environmental Quality Act schedules, and SEC filings from packaging conglomerates. Bottom-up capacity installation tracking and top-down end-use demand estimation converge through iterative reconciliation.
Assumption sets held regulatory timelines and incentive structures fixed while varying rPET feedstock availability and quick-service chain procurement centralization velocity across the projection horizon. Segmentation dimensions span product geometry, material grade, application sterility requirements, and end-user procurement model. CAGRs derive from installed capacity utilization curves and buyer substitution elasticity parameters. Industry-specific forecast inputs include Eastern Economic Corridor investment pipeline tracking and Klang Valley electronics cluster expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, resin price volatility, or ASEAN circular economy roadmap implementation pace would shift the trajectory. Forecasts reflect documented assumptions regarding incentive continuity and feedstock infrastructure development. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market