
 Vertical Strapping Machines Market | 2026-2036
Vertical Strapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Strapping Machines Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for European suppliers of vertical strapping machines. Mosca GmbH leverages its German engineering base to dominate electromechanical system development. FROMM Packaging Systems sustains broad geographic coverage across industrial packaging channels. Signode Industrial Group LLC anchors its position through captive supply of steel and plastic strap consumables.
Vertical strapping machines apply tensioned polymer or steel bands around boxes, bundles, or pallet loads, typically achieving strap tensions of 100-600 N depending on frame size and drive configuration. These systems seal joints through heat welding, friction welding, or mechanical sealing to secure goods for handling and transport. Automatic and fully-automatic product types command the widest installed base in high-volume manufacturing environments where throughput exceeds 40 cycles per minute. Servo technology segments attract premium positioning due to precision tension control and reduced strap waste compared with pneumatic alternatives.
FDA guidelines on pharmaceutical packaging integrity and OSHA machine guarding standards shape equipment specifications for US end users, while CE marking and EU Machinery Directive requirements govern European market access. China's GB standards and SAMR certification protocols create parallel compliance tracks for domestic and export-bound manufacturers. Stakeholders must monitor evolving servo drive efficiency regulations and strap recyclability mandates as these will determine next-generation product development priorities.
Market Dynamics
Servo-electric drive architecture is displacing pneumatic systems across high-throughput packaging lines, compressing energy consumption while tightening tension precision to sub-5% variance bands.
Growth Catalysts
- EU Machinery Directive revision:Safety mandate upgrades force replacement cycles in German automotive component plants, accelerating electromechanical system procurement.
- Polypropylene strap recyclability protocols:Circular economy frameworks in France and Italy mandate closed-loop material recovery, favoring heat-seal welding over mechanical closures.
- E-commerce fulfillment density:Automated parcel handling in Netherlands distribution centers requires 60+ cycles per minute throughput, driving fully-automatic system deployment.
Market Restraints
- Steel strap price volatility:Scrap metal input costs swing 15-30% quarterly, compressing margin predictability for heavy-load applications in construction materials.
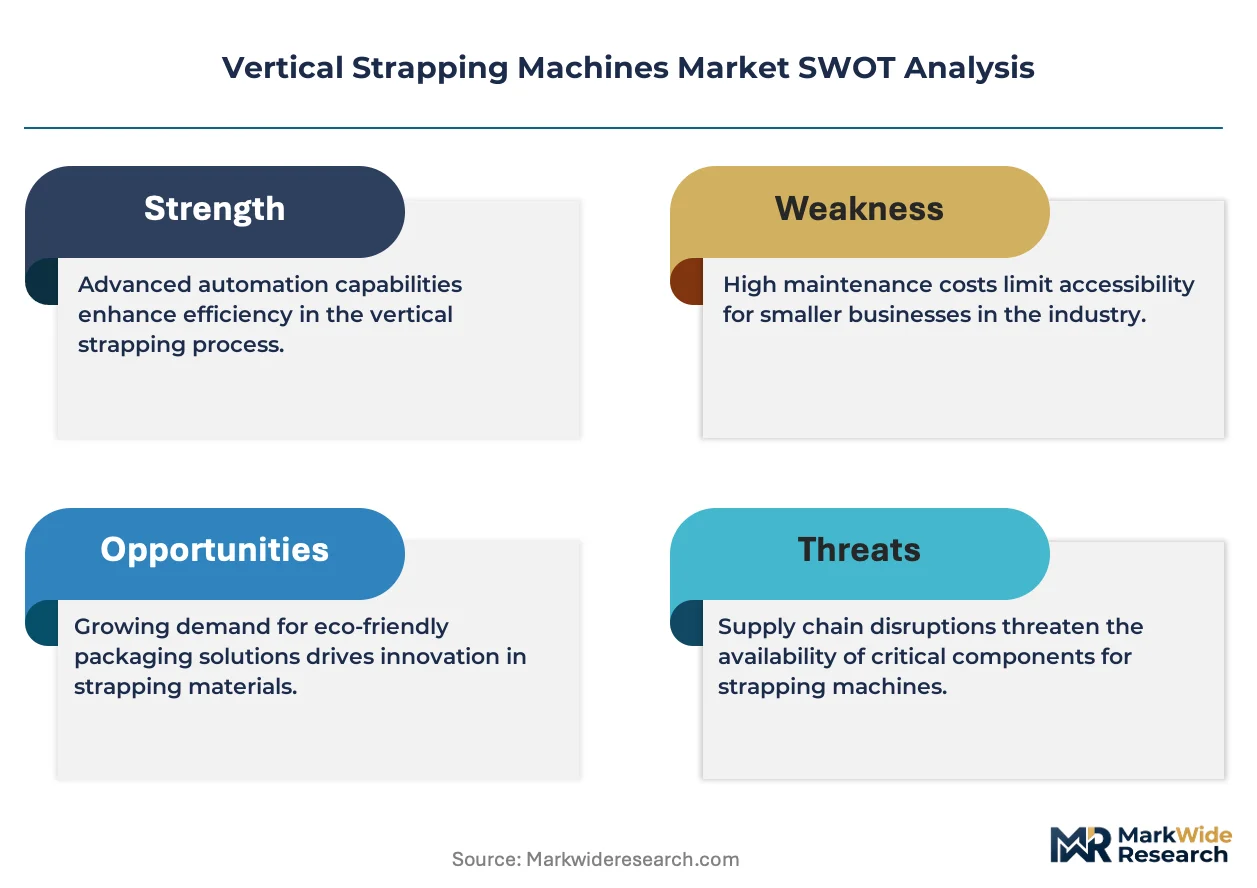
- Electronics supply concentration:Servo drive controllers source predominantly from East Asian semiconductor foundries, exposing European OEMs to single-point disruption risk.
- Friction welding speed ceiling:Mechanical sealing tops out at 45 cycles per minute, capping adoption in pharmaceutical high-volume lines where 60+ rates are standard.
Strategic Opportunities
- India PLI scheme for packaging machinery:Domestic production incentives reduce import duty exposure for mid-cap manufacturers establishing Bengaluru and Pune assembly operations.
- Pharmaceutical serialization integration:Track-and-trace mandates converge with strapping verification, creating bundled system demand from FDA-regulated US drug distributors.
- Subscription-based maintenance models:Predictive sensor analytics enable uptime-guarantee contracts, shifting revenue from equipment sale to recurring service streams in Nordic markets.
Industry Challenges
- Servo commissioning expertise scarcity:Field technicians with electromechanical calibration skills command 40% wage premiums, constraining deployment velocity in Eastern European markets.
- CE-GB dual certification burden:Parallel testing protocols for EU and China market entry extend product launch timelines by 8-12 months for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Strapping Machines Market |
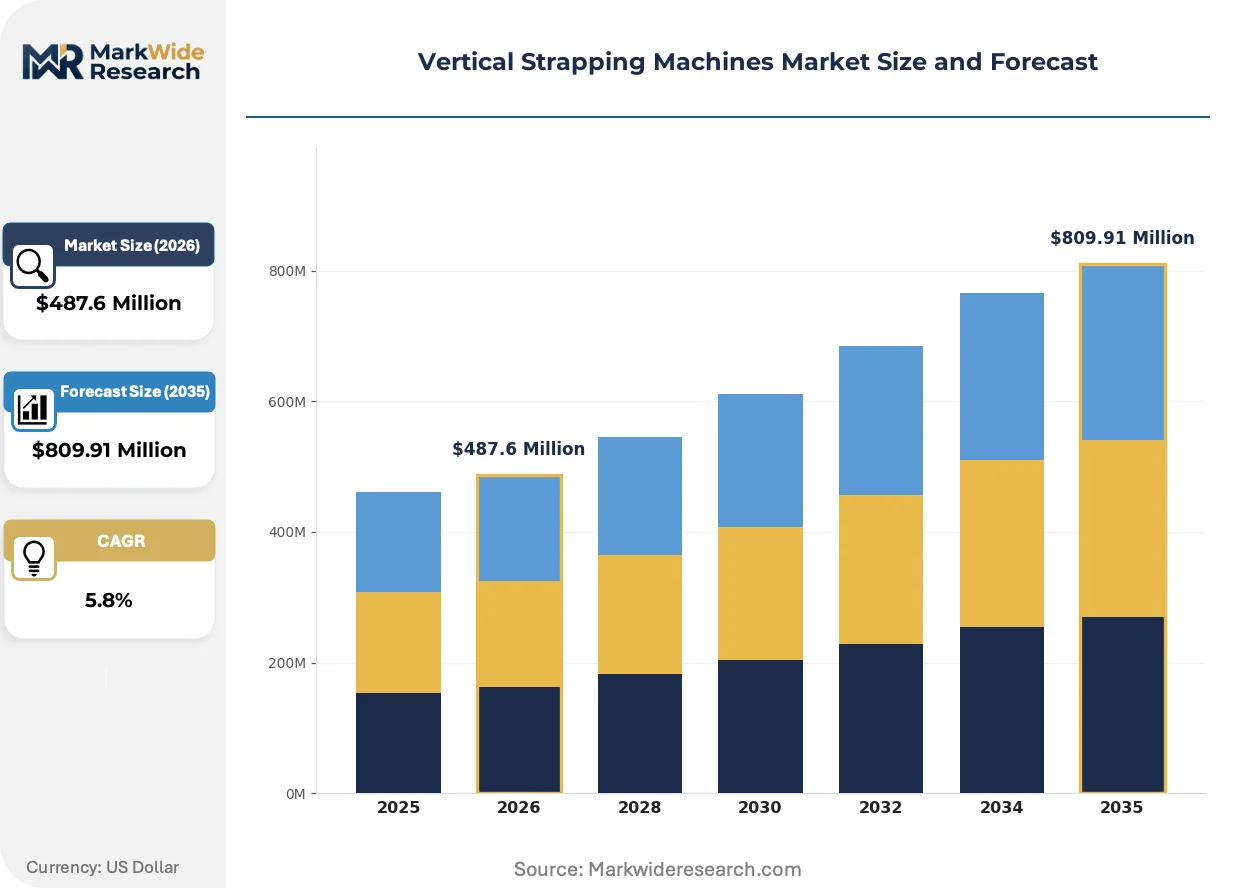
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Fully-Automatic Application: Packaging, Bundling, Palletizing, Freight End User: Manufacturing, Warehousing, Logistics, Retail Technology: Electromechanical, Pneumatic, Hydraulic, Servo |
| Companies Covered | Signode Industrial Group LLC, Mosca GmbH, FROMM Packaging Systems, Polychem Corporation, Dynaric Inc., StraPack Inc., Cyklop International, Messersì Packaging S.r.l., Transpak Equipment Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Strapping Machines Market Evolving Landscape
Intelligent tension feedback loops and material science advances are compressing the performance gap between steel and polymer strapping, while regulatory pressure on energy efficiency reshapes drive architecture roadmaps.
Brushless servo motor systems with integrated load cells are modularizing vertical strapping platforms, enabling food processors in Spain and Portugal to reconfigure line layouts without controller replacement. Bakery and frozen goods facilities adopt these systems at 25-30% annual replacement rates. Component standardization across frame sizes is modularizing supplier ecosystems, allowing third-party maintenance providers to enter previously captive service relationships.
REACH chemical restriction expansions are tightening phthalate content limits in plastic strap formulations, forcing compound reformulation across European supply chains. Industrial packaging OEMs face 18-month retooling windows to certify alternative polymer blends. Pharmaceutical and food-contact applications bear the steepest compliance burden, with German chemical regulators conducting unannounced strap composition audits.
Leasing structures with bundled consumable supply are displacing outright equipment purchase in UK third-party logistics networks, compressing capital deployment cycles from 5-year amortization to 36-month refresh intervals. Distributors like Wincanton and GXO Logistics pilot these arrangements in grocery and consumer electronics verticals. The model concentrates most rapidly in temperature-controlled warehousing, where equipment redundancy requirements inflate upfront ownership costs.
Vertical Strapping Machines Market Segmentation
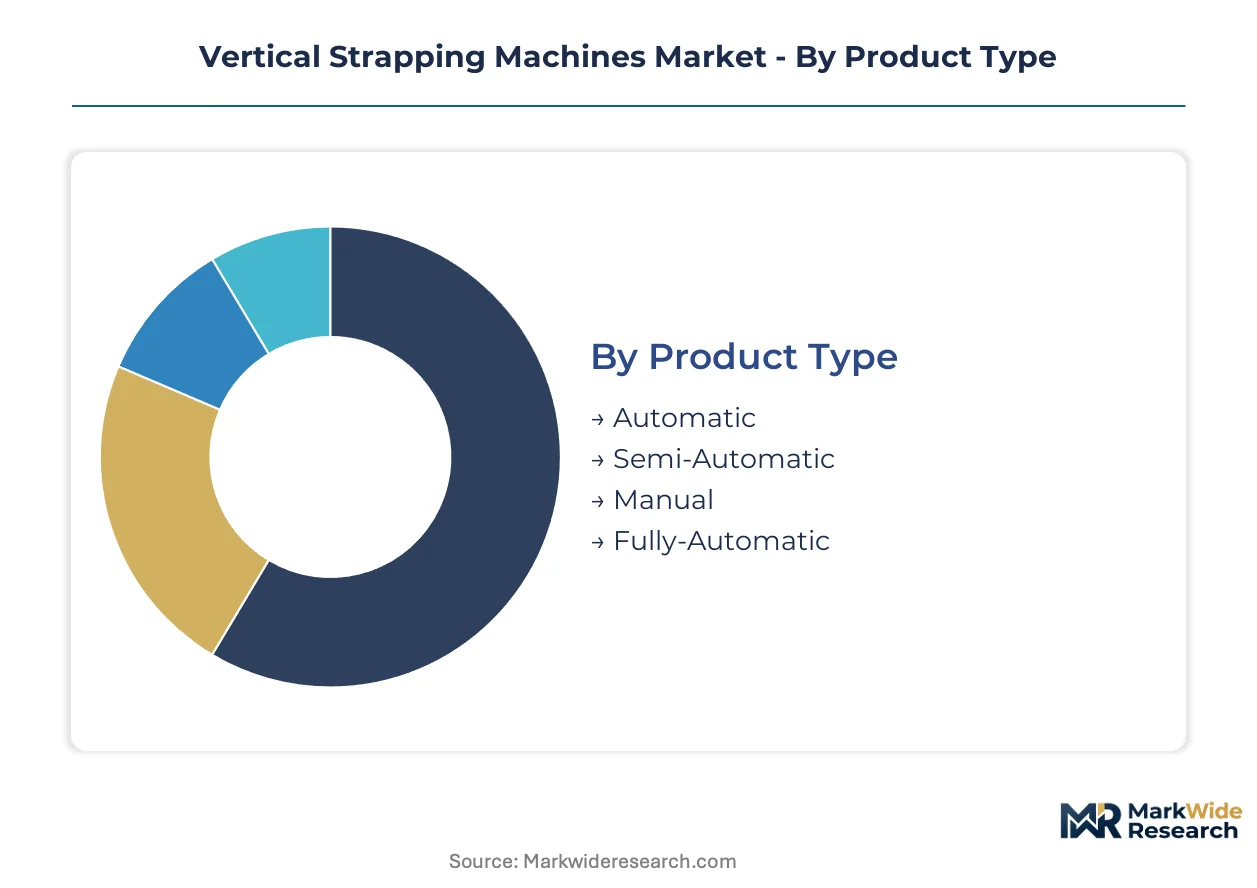
Vertical strapping machine procurement cycles diverge sharply across automation tiers and drive technologies, with replacement decisions increasingly tied to energy efficiency mandates and throughput requirements rather than mechanical failure. Equipment specification varies systematically by end-use intensity, creating distinct margin profiles and service attach rates for suppliers.
Product Type:
Upgrade cycles accelerate where labor cost inflation and throughput mandates converge, compressing payback periods for higher-automation tiers.
- Fully-Automatic:These systems integrate conveyor-fed strap dispensing, tensioning, sealing, and cut-off without operator intervention, achieving cycle rates exceeding 60 straps per minute. Demand concentrates in Netherlands and German e-commerce fulfillment centers where parcel density mandates continuous-flow automation and 24-hour operational windows.
- Automatic:Machines require manual load positioning but execute strapping sequences autonomously, typically delivering 25-40 cycles per minute with pneumatic or electromechanical drives. Spanish and Portuguese food processors favor these units for line flexibility, with bakery and frozen goods facilities driving 25-30% annual replacement rates as servo retrofits displace legacy pneumatic systems.
- Semi-Automatic:Operator-dependent systems suit low-volume, high-mix environments where capital constraints predominate over throughput optimization.
- Manual:Hand-held tensioning tools serve construction materials yards and small freight terminals with intermittent strapping requirements.
Fully-Automatic sits at the top of the volume ranking, with Automatic climbing the fastest as mid-tier manufacturers accelerate servo retrofits.
Application:
Application selection tracks directly to load stability requirements and downstream handling intensity, with palletizing commanding the highest equipment specification.
- Palletizing:Secures unitized loads for forklift handling and containerized shipping, requiring strap tensions of 400-600 N and steel or heavy-duty polymer specifications. China's coastal export manufacturing provinces in Guangdong and Jiangsu drive concentrated demand as factory-to-port logistics mandate damage-free international transit.
- Packaging:Encloses individual boxes or case packs for retail distribution, typically employing polypropylene strap at 100-250 N tension. FDA-regulated US pharmaceutical distributors specify heat-seal welding systems to maintain packaging integrity under serialization mandates.
- Bundling:Aggregates multiple units for intermediate handling, common in printing and corrugated materials.
- Freight:Secures loose cargo in LTL and container load contexts with minimal equipment standardization.
Palletizing captures the largest equipment spend, with Packaging gaining share fastest as pharmaceutical track-and-trace requirements expand.
End User:
End-user procurement sophistication spans from total-cost-of-ownership analysis in integrated logistics to first-cost minimization in fragmented retail.
- Logistics:Third-party operators in UK temperature-controlled warehousing pilot subscription-based equipment models with bundled consumable supply, compressing capital deployment cycles from 60-month amortization to 36-month refresh intervals. GXO Logistics and Wincanton drive adoption of leasing structures in grocery and consumer electronics verticals.
- Manufacturing:Automotive component plants in Germany's Baden-Württemberg and Bavaria regions accelerate replacement cycles under EU Machinery Directive safety mandate upgrades, favoring electromechanical systems with integrated guarding.
- Warehousing:General storage operations prioritize equipment reliability over cycle speed.
- Retail:Store-level and distribution center procurement remains price-sensitive with limited service contract penetration.
Logistics leads absolute unit deployment, with Manufacturing showing the steepest expansion trajectory as safety-driven replacement accelerates.
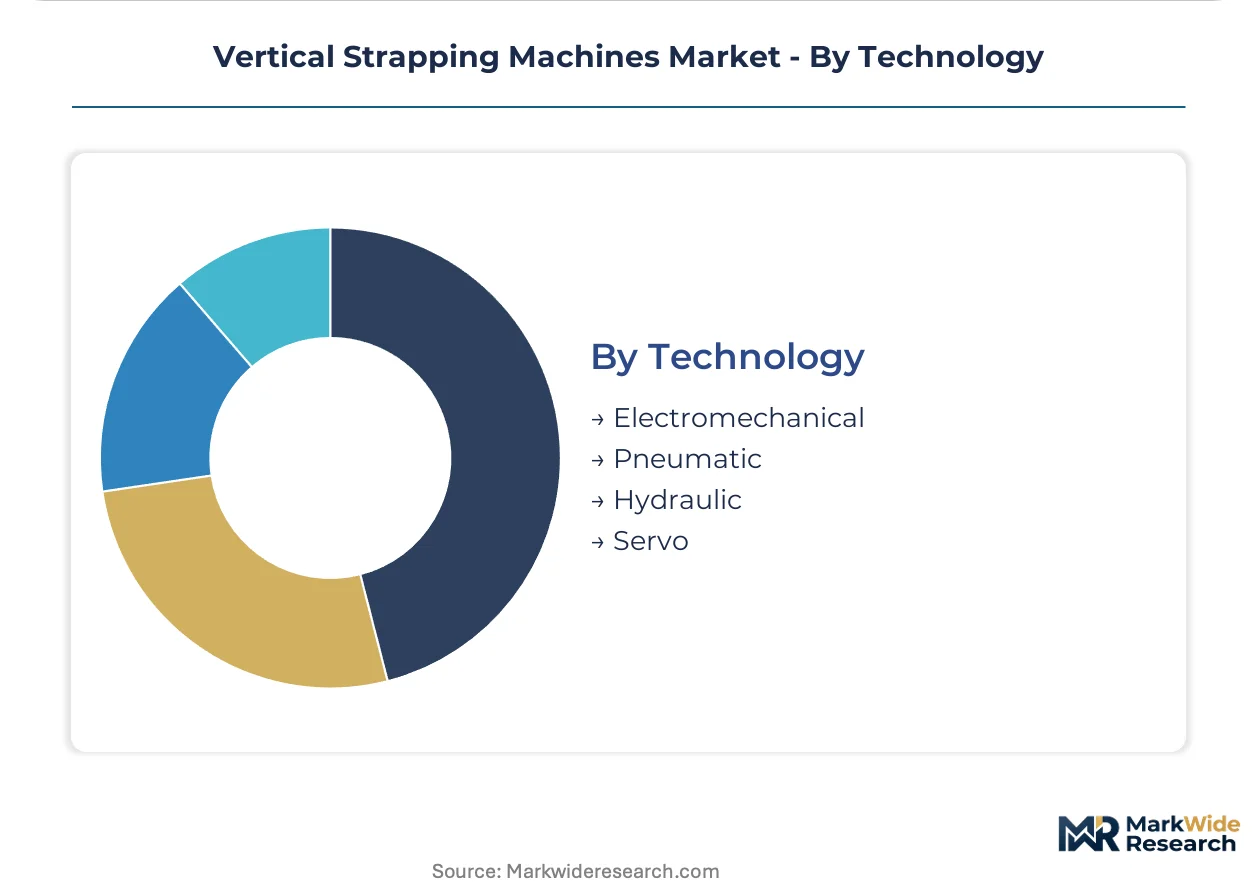
Technology:
Technology selection increasingly determines operating cost trajectories as energy efficiency regulations tighten and precision requirements escalate.
- Servo:Brushless motor systems with integrated load cells deliver sub-5% tension variance and 30-40% energy reduction versus pneumatic alternatives. REACH chemical restriction expansions favor these systems in French and Italian circular economy frameworks where heat-seal welding supports closed-loop polypropylene recovery.
- Electromechanical:Cam-driven and clutch-based systems offer intermediate precision at moderate cost, dominating mid-volume applications in Eastern European markets where servo commissioning expertise scarcity constrains premium system deployment.
- Pneumatic:Compressed-air systems face displacement as energy costs rise and precision requirements tighten.
- Hydraulic:Heavy-load applications in construction materials persist where steel strap and extreme tension requirements dominate.
Servo commands the premium tier by installed value, with Electromechanical expanding most quickly as mid-market buyers bridge cost-performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses pioneered vertical strapping automation during the post-war industrial expansion, establishing technical standards that persist across European packaging lines today. This heritage shapes contemporary procurement patterns in high-precision manufacturing clusters.
Germany
Automotive component plants in Baden-Württemberg and Bavaria drive electromechanical system demand as EU Machinery Directive safety mandates accelerate replacement cycles. CE marking requirements under the Directive's 2023 revision force guarding upgrades on legacy pneumatic installations. Stuttgart and Munich industrial corridors concentrate procurement for 24-hour automotive supply chains.
China
Export-oriented factories in Guangdong and Jiangsu provinces require high-throughput palletizing solutions for factory-to-port logistics. SAMR certification protocols and GB standards create dual compliance tracks for domestic and export-bound equipment manufacturers. Shenzhen and Suzhou manufacturing clusters lead servo system adoption for electronics export packaging.
United States
FDA-regulated pharmaceutical distributors specify heat-seal welding systems to maintain packaging integrity under track-and-trace mandates. OSHA machine guarding standards shape equipment specifications for end users in high-volume manufacturing. New Jersey and Pennsylvania distribution corridors concentrate demand from generic drug distributors.
Netherlands
E-commerce fulfillment centers in Rotterdam and Tilburg distribution clusters require 60-plus cycles per minute throughput, driving fully-automatic system deployment. REACH chemical restrictions on phthalate content influence strap formulation selection for circular economy compliance. Dutch logistics operators pilot predictive maintenance subscriptions with uptime guarantees.
India
Domestic production incentives under the PLI scheme for packaging machinery reduce import duty exposure for mid-cap manufacturers. BIS certification requirements and DGFT trade protocols govern equipment standards for food-contact and pharmaceutical applications. Bengaluru and Pune assembly operations expand to serve Southeast Asian export markets.
Vertical Strapping Machines Market Competitive Landscape
The competitive structure tilts toward engineering-specialist dominance with selective scale-driven consolidation. German and Italian precision fabricators occupy premium positioning through electromechanical system development, while broader industrial packaging conglomerates sustain geographic coverage through diversified portfolio breadth. Two strategic archetypes define the field: captive consumable suppliers integrating strap production with equipment sales, and pure-play machinery specialists focusing on servo-drive innovation. Consolidation pressures favor M&A activity among mid-tier European fabricators, while technology licensing agreements accelerate servo architecture diffusion across Asian assembly operations.
Among Germany-based engineering houses, Mosca GmbH exemplifies the precision-drive archetype through its electromechanical development focus. FROMM Packaging Systems occupies a position spanning broad geographic coverage across industrial packaging channels. Signode Industrial Group LLC anchors the captive supply model through integrated steel and plastic strap production. These three entities represent distinct competitive vectors: engineering depth, distribution breadth, and vertical integration into consumables.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Mosca GmbH |
| FROMM Packaging Systems |
| Polychem Corporation |
| Dynaric Inc. |
| StraPack Inc. |
| Cyklop International |
| Messersì Packaging S.r.l. |
| Transpak Equipment Corp. |
| Others |
Value Network & Pricing Analysis
Electromechanical calibration specialists in Stuttgart and Munich command wage premiums that compress margin structures across German-engineered equipment tiers, widening spreads between servo-equipped premium systems and pneumatic standard offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with CE marking grade and after-sales service bundling as primary differentiation levers. Cost compression in economy tiers intensifies because Indian PLI-subsidized domestic assembly undercuts import landed costs. Small freight terminals and construction materials yards exhibit highest price sensitivity, while pharmaceutical distributors under FDA serialization mandates show least.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for mid-cap assembly operations in Bengaluru and Pune. Semiconductor servo controllers draw from Taiwan and South Korea, steel strap feedstock rests on German and Chinese metallurgical capacity, and polymer compounds hinge on Saudi and US petrochemical output. Single-source vulnerability in East Asian semiconductor foundries threatens European OEM controller availability. Distribution runs through captive strap-supplier networks and third-party industrial packaging channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU Machinery Directive's 2023 revision forcing replacement cycles that sustain demand independent of macro cyclicality.
For Market Incumbents: Hedge against servo controller supply disruption by qualifying secondary semiconductor sources in India and Southeast Asia. Deepen captive strap production to defend margin position against polymer price volatility. CE-GB dual certification investment protects market access as Chinese SAMR protocols tighten.
For New Entrants and Emerging Players: Predictive sensor analytics with subscription-based uptime guarantees offer a technology-first wedge into Nordic logistics networks where Wincanton and GXO pilot service-based procurement. Target temperature-controlled warehousing in UK grocery verticals as most penetrable segment. Pursue white-label assembly partnerships with Indian PLI beneficiaries to bypass duty exposure.
For Investors and Strategic Acquirers: Industrial packaging conglomerates with broad geographic coverage are the most active acquirer in this space, consolidating mid-tier European fabricators to capture servo architecture capabilities. Five-to-ten year viability hinges on electromechanical system development depth rather than pneumatic legacy installed base. Watch for REACH chemical restriction expansions triggering 18-month compound reformulation windows as inflection indicator for strap-supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Architecture Licensing | Accelerates technology diffusion to Indian and Southeast Asian assembly operations under PLI incentives. |
| Backward Integration into Polymer Compounding | Captures margin pool as REACH phthalate restrictions force European supply chain reformulation. |
| Predictive Maintenance Platform Launch | Shifts revenue from equipment sale to recurring service streams in Netherlands and Nordic logistics markets. |
| CE-GB Dual Certification Investment | Compresses product launch timelines for mid-tier suppliers targeting EU and China market entry simultaneously. |
| Pharmaceutical Serialization Integration Partnership | Bundles strapping verification with track-and-trace mandates from FDA-regulated US drug distributors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and logistics maintenance directors with secondary validation against customs records, SEC machinery filings, EU Machinery Directive implementation guidance, and BIS certification databases. Bottom-up equipment shipment tallies and top-down industrial packaging spend estimates were triangulated to anchor volume figures.
Segment-weighting approaches applied product type, drive technology, end-use intensity, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from equipment replacement cycle modeling and energy efficiency mandate compliance timelines. Forecast inputs incorporated servo adoption curves in food processing and pharmaceutical serialization integration penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruption, steel scrap price volatility, and REACH chemical restriction expansion scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Powder Auger Fillers Market