
 Molded Pulp Basket Market | 2026-2036
Molded Pulp Basket Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Pulp Basket Market Foresight
Consolidation among North American grocery retailers is realigning volume commitments toward suppliers capable of national-scale molded pulp fulfillment. Huhtamaki leverages its integrated fiber sourcing network to secure multi-year produce chain contracts. Brodrene Hartmann anchors European capacity through thermoformed fiber lines optimized for horticulture trays. UFP Technologies differentiates via medical-adjacent precision molding expertise transferable to premium food packaging formats.
Molded pulp baskets are engineered from wet-pressed cellulose fibers, typically derived from recycled corrugated or agricultural residues, formed under heat and pressure into rigid, breathable containers with moisture resistance ranging from basic water repellency to wax-barrier grades. Their primary commercial purpose centers on protective transport and retail display of fresh produce, nursery stock, and fragile consumer goods. Packaging Baskets leads product type value generation due to foodservice and retail produce chain standardization, while Horticulture application demand accelerates fastest as European nursery operators phase out petroleum-based trays. Composite Materials segment margins concentrate where manufacturers blend long-fiber agricultural waste with post-consumer paper to achieve wet strength without synthetic additives.
The EPA promotes fiber-based packaging through sustainable materials management guidelines, while EU REACH restrictions on perfluorinated chemicals in food contact materials directly accelerate molded pulp substitution for coated paperboard. California's SB 54 extended producer responsibility framework mandates 30% post-consumer recycled content thresholds that molded pulp baskets routinely exceed. Stakeholders must monitor evolving state-level plastic restriction timelines and certify compostability through BPI or OK Compost HOME to maintain shelf placement at regulated retailers.
Market Dynamics
Extended producer responsibility laws are forcing packaging buyers to consolidate procurement around compostable formats, compressing supplier qualification timelines and privileging molded pulp producers with certified fiber sourcing networks.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal's packaging waste directives require fiber-based alternatives to plastic containers in fresh produce retail, accelerating molded pulp basket adoption across German and French grocery chains.
- Horticulture tray replacement:European nursery operators are systematically phasing out petroleum-based trays, creating concentrated demand for thermoformed fiber solutions in plant propagation and distribution.
- California SB 54 thresholds:California's extended producer responsibility framework mandates 30% post-consumer recycled content that molded pulp baskets routinely exceed, securing shelf placement at regulated retailers.
Market Restraints
- Recycled corrugated fiber cost volatility:Post-consumer OCC pricing swings directly compress molded pulp margins, particularly for producers without captive fiber sourcing or long-term supply contracts.
- Wet strength additive dependency:Technical limitations in achieving moisture resistance without synthetic additives create compliance friction under EU REACH perfluorinated chemical restrictions.
- Plastic tray residual cost advantage:Virgin polypropylene trays retain 15-25% cost edge in high-volume horticulture applications where compostability mandates remain unenforced.
Strategic Opportunities
- Medical-adjacent precision migration:Transferable expertise from medical device fiber molding is unifying with premium food packaging formats, opening white space in pharmaceutical and cosmetic basket applications.
- Indian organized retail expansion:Underpenetrated demand from India's consolidating supermarket chains presents volume opportunity for exporters with BPI or OK Compost HOME certification.
- Agricultural residue fiber convergence:Blending long-fiber wheat straw with post-consumer paper is creating margin-advantaged composite materials without wet strength additives.
Industry Challenges
- Compostability certification timelines:BPI and OK Compost HOME approval cycles stretch 8-14 months, delaying contract execution with procurement-consolidated retail chains.
- Thermoformed fiber equipment capex intensity:Automated thermoforming lines for horticulture-grade trays require capital deployment that mid-scale producers struggle to finance.
- Cross-state regulatory fragmentation:Divergent implementation timelines between California SB 54 and New York's pending EPR framework complicate national fulfillment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Pulp Basket Market |
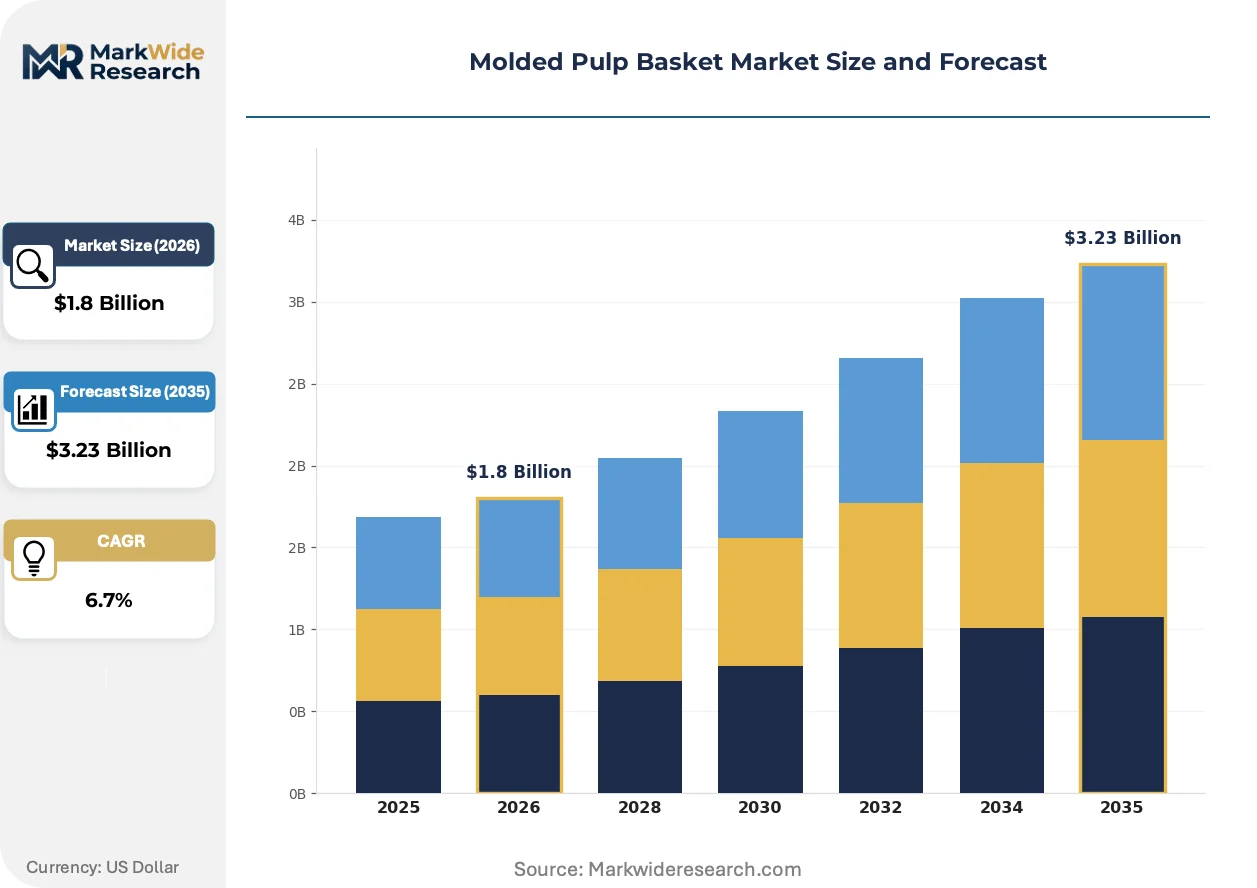
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Baskets, Garden Baskets, Storage Baskets, Packaging Baskets End User: Retailers, Wholesalers, E-commerce Platforms, Agriculture Material: Pulp, Recycled Paper, Biodegradable Materials, Composite Materials Application: Food Packaging, Horticulture, Specialty Retail, Event Management |
| Companies Covered | Huhtamaki, Brodrene Hartmann, UFP Technologies, Pactiv Evergreen, EnviroPAK, Sonoco Products, Sabert Corporation, Genpak, Hartmann Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Pulp Basket Market Shifts & Advancements
Wet-pressing automation and barrier coating chemistry are converging to expand molded pulp performance envelopes, enabling displacement of coated paperboard in moisture-sensitive applications previously closed to fiber solutions.
Precision thermoforming is unifying agricultural residue fibers with post-consumer paper streams to achieve wet strength without synthetic additives. German horticulture distributors are adopting these composite formulations fastest, compressing the performance gap between molded pulp and plastic trays in nursery stock transport. Equipment suppliers are responding with heated-plate presses calibrated for variable fiber blends.
REACH restrictions on perfluorinated chemicals in food contact materials are eliminating coated paperboard options for fresh produce packaging. The ECHA enforcement timeline is compressing supplier transition windows, with Dutch and Belgian retail chains now requiring PFAS-free certification for all fiber-based containers. Molded pulp producers with barrier-coating R&D programs are capturing displaced volume.
Produce procurement consolidation is rotating volume toward suppliers with multi-region certification coverage. National grocery chains in the United States are unbundling legacy regional supplier relationships, replacing them with master service agreements that mandate BPI compostability and national fulfillment capability. This behavioral shift is most visible in California and New York, where state EPR laws have activated procurement compliance functions.
Molded Pulp Basket Market Segmentation
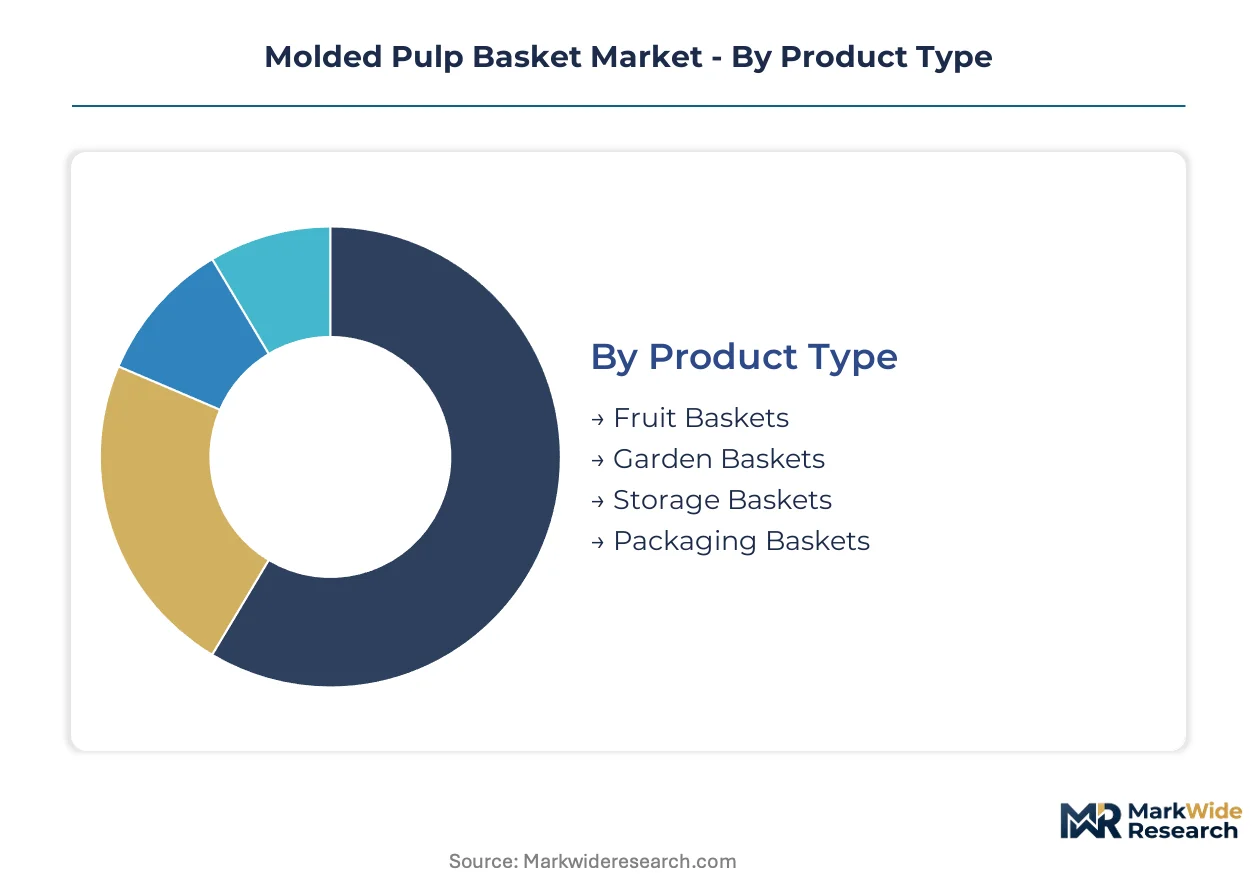
Molded pulp basket segmentation reflects divergent performance requirements across moisture sensitivity, load-bearing capacity, and compostability certification tiers. Procurement teams at consolidated retail chains are collapsing these categories into unified specifications that privilege suppliers with cross-segment manufacturing flexibility.
Product Type:
Standardization pressure from grocery chain procurement consolidation is compressing SKU diversity, while premium formats retain customization latitude through barrier-coating specifications and dimensional precision.
- Packaging Baskets:Engineered from wet-pressed recycled corrugated with wax or clay-barrier coatings achieving moisture resistance grades from basic water repellency to extended cold-chain durability. German and French retail chains are mandating these for produce display following EU Green Deal packaging waste directives, displacing coated paperboard formats restricted under ECHA perfluorinated chemical rules.
- Garden Baskets:Thermoformed fiber constructions with reinforced rim structures for nursery stock transport and retail presentation. European horticulture distributors in the Netherlands and Belgium are adopting these fastest as petroleum-based tray phase-outs accelerate under national plastic restriction timelines.
- Fruit Baskets:Breathable open-weave designs for countertop produce display.
- Storage Baskets:Rigid multi-use containers for household organization applications.
Leading the category by volume: Packaging Baskets. Growing fastest: Garden Baskets.
End User:
Volume concentration tracks regulatory activation sequencing, with California and New York procurement functions ahead of national fulfillment curve.
- Retailers:National grocery chains are unbundling regional supplier relationships for master service agreements requiring BPI compostability and multi-region certification coverage. California SB 54 mandates are activating procurement compliance functions ahead of New York's pending EPR framework, compressing supplier qualification timelines to 8-14 month certification cycles.
- Agriculture:Nursery operators and produce growers are specifying thermoformed fiber trays for propagation and distribution. German horticulture distributors are replacing plastic trays systematically, creating concentrated demand for composite fiber formulations blending wheat straw with post-consumer paper.
- Wholesalers:Intermediate distributors serving independent retail accounts.
- E-commerce Platforms:Direct-to-consumer fulfillment requiring protective transit packaging.
Dominant volume share: Retailers. Steepest expansion trajectory: Agriculture.
Material:
Margin structure stratifies across fiber sourcing control, with captive agricultural residue supply conferring cost advantage over spot-market recycled paper dependence.
- Composite Materials:Blended formulations combining long-fiber agricultural residues with post-consumer paper streams to achieve wet strength without synthetic additives. German equipment suppliers are calibrating heated-plate presses for these variable fiber blends, enabling displacement of plastic trays in moisture-sensitive nursery applications.
- Recycled Paper:Post-consumer OCC-based pulps subject to pricing volatility that compresses margins for producers without long-term supply contracts or captive fiber sourcing networks.
- Pulp:Virgin cellulose fiber for premium precision-molding applications.
- Biodegradable Materials:Certifiable compostable formulations for regulated retail environments.
Highest margin concentration: Composite Materials. Fastest formulation adoption: Biodegradable Materials.
Application:
Performance requirements diverge across moisture exposure duration, structural load, and aesthetic presentation thresholds.
- Horticulture:Thermoformed fiber trays for plant propagation, transport, and retail display requiring wet strength without synthetic additives. European nursery operators are phasing out petroleum-based trays fastest in Germany, the Netherlands, and Belgium, compressing the performance gap with plastic through precision thermoforming of agricultural residue composites.
- Food Packaging:Protective containers for fresh produce retail display and cold-chain distribution. ECHA enforcement timelines for PFAS-free certification are eliminating coated paperboard options, redirecting volume toward molded pulp producers with barrier-coating R&D programs.
- Specialty Retail:Premium presentation formats for gift and cosmetic applications.
- Event Management:Single-use serving and display containers for catering.
Primary volume anchor: Food Packaging. Climbing the fastest: Horticulture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement consolidation among German retail chains and California's SB 54 enforcement timeline are concentrating demand in jurisdictions with activated extended producer responsibility frameworks, compressing supplier qualification windows to certification-cycle durations.
United States
California's SB 54 mandates 30% post-consumer recycled content thresholds that molded pulp baskets routinely exceed, activating procurement compliance functions ahead of New York's pending EPR framework. The EPA promotes fiber-based packaging through sustainable materials management guidelines. Los Angeles and San Francisco Bay Area distribution clusters are unbundling regional supplier relationships for master service agreements requiring BPI compostability certification.
Germany
Retail chains and horticulture distributors are replacing plastic trays with molded pulp for produce and nursery applications under EU Green Deal packaging waste directives. ECHA enforcement of REACH restrictions on perfluorinated chemicals eliminates coated paperboard alternatives. The Rhine-Ruhr industrial corridor anchors thermoformed fiber capacity expansion for horticulture-grade trays optimized through heated-plate press calibration.
Netherlands
Dutch retail chains now require PFAS-free certification for all fiber-based containers, compressing supplier transition windows following ECHA timelines. The country's national packaging regulator enforces EU Green Deal compliance through accelerated inspection protocols. Rotterdam distribution hubs are consolidating procurement specifications around compostable formats for re-export throughout Northern Europe.
France
French grocery chains are mandating fiber-based alternatives to plastic containers in fresh produce retail under EU Green Deal directives. The national environmental agency enforces packaging waste reduction targets through retailer audit programs. The Île-de-France logistics cluster is standardizing on molded pulp packaging baskets for cold-chain distribution to Paris metropolitan retail networks.
India
Organized retail expansion among consolidating supermarket chains presents volume opportunity for exporters with BPI or OK Compost HOME certification. The Bureau of Indian Standards is developing compostability benchmarks aligned with ISO standards. Mumbai and Delhi-NCR procurement functions are piloting molded pulp specifications for premium produce display formats in modern trade outlets.
Molded Pulp Basket Market Competitive Landscape
European producers anchor one tier through thermoformed fiber specialization; North American fabricators hold national-scale fulfillment capability through integrated fiber sourcing networks. Market structure stratifies across three tiers: multinational packaging conglomerates with captive pulp supply, mid-scale regional specialists with certification depth, and equipment-integrated converters serving horticulture niches. Dominant competitive moves include backward integration into agricultural residue fiber sourcing and multi-year master service agreement pursuit with consolidating retail procurement functions.
Within the multinational conglomerate tier, Huhtamaki Oyj and Brodrene Hartmann A/S exemplify geographic anchoring strategies—Finnish and Danish origins respectively—while occupying positions defined by integrated fiber network scale. UFP Technologies, Inc. represents the precision-molding specialist archetype, sitting within a tier where medical-adjacent expertise transfers to premium food packaging formats. These three entities collectively illustrate how competitive positioning concentrates around certification coverage breadth and captive supply chain control rather than product differentiation alone.
| Leading Market Players |
|---|
| Huhtamaki |
| Brodrene Hartmann |
| UFP Technologies |
| Pactiv Evergreen |
| EnviroPAK |
| Sonoco Products |
| Sabert Corporation |
| Genpak |
| Hartmann Packaging |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging waste directives gate qualified supply for premium-tier molded pulp baskets, restricting shelf placement to producers with BPI or OK Compost HOME certification and compressing margin structures for uncertified competitors. California SB 54 and pending New York EPR frameworks extend this gating mechanism to North American procurement, concentrating pricing power among suppliers with multi-region compliance coverage.
Pricing Analysis
Volume-margin splits stratify across certification tiers, with BPI-certified producers commanding premium positioning against standard-grade competitors. Price differentiation hinges on compostability certification grade and captive agricultural residue fiber sourcing, while cost compression in recycled corrugated-dependent tiers intensifies from OCC spot-market volatility. National grocery chains exhibit lowest price sensitivity due to EPR compliance mandates, whereas independent horticulture distributors retain residual plastic tray preference where compostability enforcement lags.
Supply Chain Analysis
California SB 54 and EU Green Deal domestic-content-equivalent mandates are reshaping sourcing toward regional fiber processing hubs. Supply concentrates in Germany, the United States, and the Netherlands, drawing from recycled corrugated OCC, wheat straw agricultural residue, and post-consumer paper pulp inputs. Single-source vulnerability runs through thermoformed fiber equipment suppliers calibrated for variable fiber blends. Distribution runs through Rotterdam, Los Angeles, and Rhine-Ruhr logistics clusters serving consolidated retail procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive agricultural residue fiber supply and multi-region certification coverage determine competitive survival. Players are pursuing backward integration into wheat straw and post-consumer paper sourcing networks to escape OCC spot-market dependency.
For Market Incumbents: Cement multi-year master service agreements with consolidating national grocery chains before New York EPR activation compresses qualification windows further. Expand thermoformed fiber capacity in the Rhine-Ruhr corridor to capture accelerating German horticulture demand. Prioritize barrier-coating R&D programs to displace coated paperboard volume under ECHA perfluorinated chemical restrictions.
For New Entrants and Emerging Players: California SB 54 opens a window for certified producers to penetrate underrepresented independent retail accounts before national procurement consolidation completes. Target India's organized retail expansion with BPI-certified export formulations for premium produce display formats. Pursue equipment-integrated conversion partnerships with German press suppliers to bypass thermoforming line capex barriers.
For Investors and Strategic Acquirers: New York's pending EPR framework publication is the leading indicator that certification-capable mid-scale producers will command acquisition premiums. Long-term viability centers on five-to-ten-year fiber sourcing control and cross-regional compliance coverage. Monitor BPI approval cycle compression as the inflection signal for supplier scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Sourcing | Captive wheat straw supply insulates margins from OCC price volatility under California SB 54. |
| Thermoformed Fiber Capacity Expansion | Heated-plate press deployment in the Rhine-Ruhr corridor captures German horticulture tray replacement demand. |
| Multi-Region Certification Coverage | BPI and OK Compost HOME dual certification unlocks master service agreements with national grocery chains. |
| Barrier-Coating R&D Investment | PFAS-free moisture resistance development displaces coated paperboard under ECHA enforcement timelines. |
| Equipment-Integrated Conversion Partnership | Collaboration with German press suppliers enables mid-scale producers to bypass thermoforming capex barriers. |
Research Methodology
Independent corroboration across procurement executives at consolidating grocery chains, horticulture distributors in Germany and the Netherlands, molded pulp equipment suppliers, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with sustainability officers at retail chains and fiber sourcing managers at packaging producers combined with secondary validation from EPA sustainable materials management guidelines, EU REACH restriction databases, California SB 54 implementation documents, and BPI certification records. Bottom-up volume modeling and top-down market sizing triangulate across these sources.
Comparable-period anchoring to historical EPR activation sequences in California and Germany established the forecast framework baseline across the analysis window. Segmentation dimensions modeled include product type, end-user category, material formulation, and application with cross-tabulation against regional regulatory cluster adoption curves. CAGRs derive from regression analysis of procurement consolidation timelines and certification penetration rates, incorporating fiber cost volatility indices and thermoformed equipment deployment schedules as industry-specific inputs.
The model assumes a particular technology adoption path for PFAS-free barrier coatings; alternative pathways for synthetic additive-free wet strength achievement would alter the outlook. Forecasts reflect documented assumptions regarding EPR enforcement sequencing and compostability certification cycle durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Fiberboard Packaging Market