
 Global Molded Pulp Packaging Market | 2026-2036
Global Molded Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Pulp Packaging Market Foresight
Electronics manufacturing is expanding its reliance on molded pulp cushioning as brands phase out expanded polystyrene. Huhtamaki Oyj leverages its European thermoforming footprint to supply precision-fit trays for smartphones and laptops. Sonoco Products Co. anchors North American demand through its dedicated molded fiber operations serving consumer electronics distribution hubs. Brødrene Hartmann A/S specializes in high-volume egg packaging while extending capabilities into industrial protective applications.
Molded pulp packaging consists of cellulose fibers formed under heat and pressure into rigid, three-dimensional shapes with engineered wall thickness typically ranging from 0.8 to 3.0 millimeters, designed primarily to cushion, contain, and display products during transit and retail presentation. Virgin pulp commands premium positioning in medical and cosmetic segments where fiber consistency and cleanliness determine compliance thresholds. Recycled pulp competes aggressively on unit cost within food service applications where regulatory acceptance of post-consumer content is broadest. Thermoforming dominates electronics packaging due to dimensional precision, while pressed molding sustains margin pools in high-volume egg tray production where cycle speed outweighs customization needs.
The U.S. EPA and FDA shape fiber contact standards for food applications, while the EU Green Deal and REACH constrain chemical additives in pulp slurries. China's SAMR enforces GB standards for packaging recyclability that directly affect export-bound molded pulp specifications. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions to anticipate compliance-driven material substitutions and certification requirements that will determine market access.
Market Dynamics
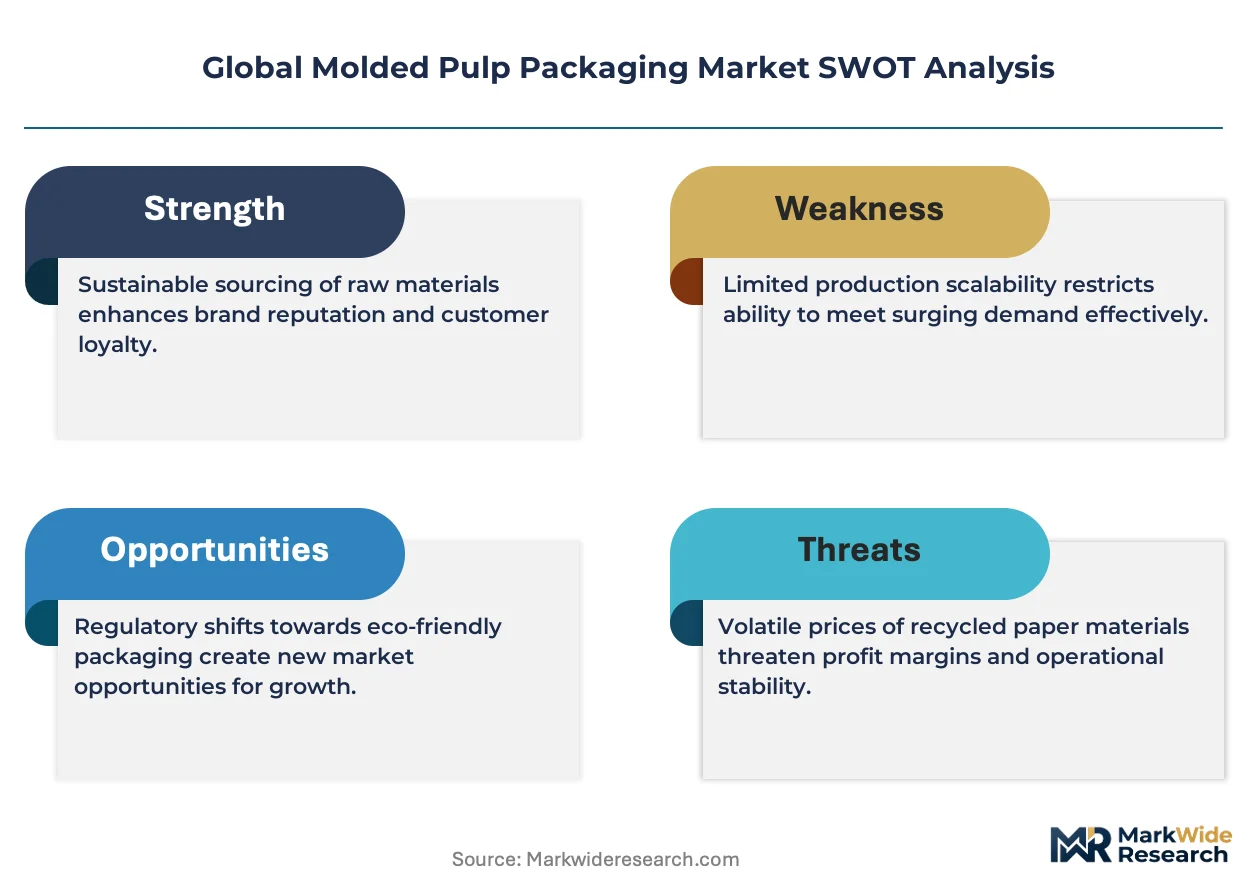
The EU Green Deal's single-use plastics ban is forcing rapid material substitution across European supply chains, while electronics brands simultaneously phase out expanded polystyrene cushioning. This dual regulatory-commercial pressure is compressing adoption timelines for fiber-based protective solutions.
Growth Catalysts
- REACH chemical restrictions:The EU's constraints on additives in petroleum-based packaging accelerate pulp slurry formulations as compliant alternatives for food-contact applications.
- Electronics manufacturing:Smartphone and laptop producers require precision-fit trays that thermoformed pulp delivers with dimensional tolerances matching legacy plastic solutions.
- China's dual carbon goals:SAMR-enforced GB standards for packaging recyclability redirect export-bound production toward molded fiber specifications.
Market Restraints
- Pulp fiber cost volatility:Recycled OCC (old corrugated containers) pricing fluctuates with Chinese import policy shifts, squeezing converter margins unpredictably.
- Mold precision limitations:Pressed molding cycles optimized for egg tray throughput cannot achieve the wall-thinning and corner radii required for premium electronics fitments.
- Barrier coating performance gaps:Water-based coatings meeting FDA contact standards still underperform against polyethylene in high-moisture food service environments.
Strategic Opportunities
- India's FSSAI packaging mandates:Food safety regulations banning certain plastic formats in quick-service restaurants open virgin pulp entry points for global converters.
- Medical device sterilizable trays:Gamma-stable molded fiber formats for surgical kits remain underdeveloped relative to pharmaceutical blister packaging maturity.
- Direct-to-consumer fulfillment:E-commerce brands require damage-resistant unboxing experiences that printed pulp inserts provide versus generic corrugated dunnage.
Industry Challenges
- Thermoforming tooling lead times:Precision aluminum molds for electronics trays require 14-18 week fabrication cycles that mismatch agile product launch schedules.
- Composting infrastructure fragmentation:Industrial composting facility availability varies dramatically between Germany's organized waste streams and US municipal gaps, complicating end-of-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Pulp Packaging Market |
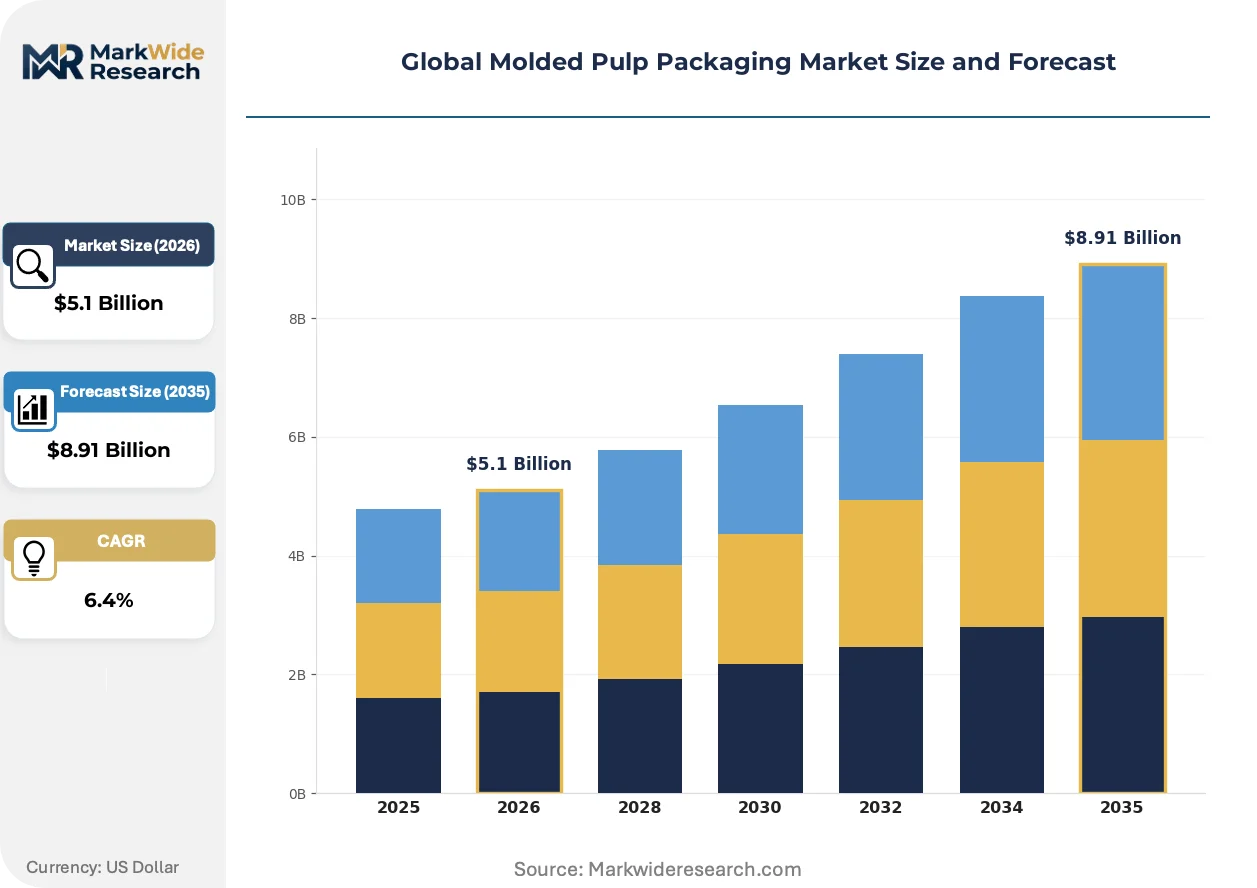
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Egg Trays, Food Containers, Electronics Packaging, Beverage Carriers, Medical Packaging, Cosmetic Boxes Material Grade: Virgin Pulp, Recycled Pulp, Bleached Pulp, Unbleached Pulp, Specialty Fibers, Coated Pulp End User Industry: Food & Beverage, Electronics Manufacturing, Healthcare Facilities, Personal Care, Consumer Goods, Agricultural Supplies Manufacturing Technology: Thermoforming, Pressed Molding, Injection Molding, Vacuum Forming, Hot Pressing, Compression Molding |
| Companies Covered | Huhtamaki Oyj, Sonoco Products Co., Brødrene Hartmann A/S, Genpak LLC, UFP Technologies, Sabert Corporation, Pactiv Evergreen Inc., Henry Molded Products Inc., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Pulp Packaging Market Shifts & Advancements
Material science advances and regulatory enforcement timelines are compressing the window for legacy plastic substitution. Three developments are actively restructuring competitive capability requirements.
Thermoformed molded pulp is expanding into high-tolerance electronics protection applications previously dominated by vacuum-formed PET. Smartphone original equipment manufacturers in China and Vietnam specify fiber trays with sub-millimeter dimensional stability for automated assembly line feeding. This capability expansion is compressing the addressable market for petroleum-based cushioning in premium device categories.
The EU Green Deal's packaging and packaging waste regulation revision tightens extended producer responsibility frameworks across member states. Industrial producers face mandatory recyclability targets and modulated fee structures that penalize non-fiber formats. Food service operators in France and Germany are responding with accelerated pulp plate and clamshell conversions ahead of 2025 enforcement milestones.
Brand-led sustainability scorecards now weight packaging circularity in supplier selection criteria. Major consumer goods retailers in the United States and United Kingdom require documented fiber sourcing and composting pathway verification from private-label food packaging vendors. This behavioral shift elevates certified pulp suppliers above uncertified competitors in procurement shortlists regardless of unit cost parity.
Global Molded Pulp Packaging Market Segmentation
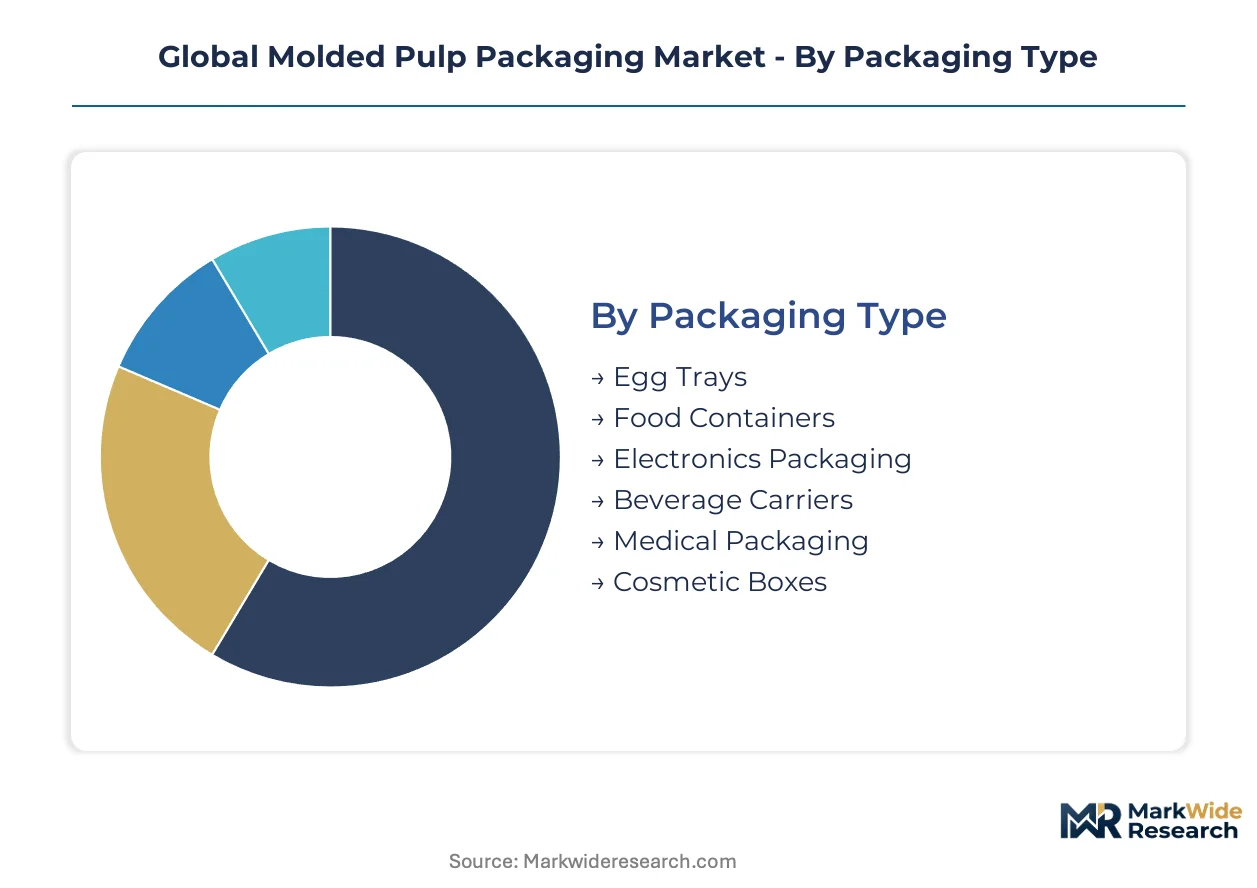
Molded pulp packaging segments diverge sharply in capital requirements, tooling lead times, and margin profiles. Understanding these structural differences clarifies where converter investments cluster and which technologies attract strategic capital deployment.
Packaging Type:
Capital intensity peaks in electronics packaging where precision aluminum molds demand 14-18 week fabrication cycles, while egg trays run on commodity tooling with rapid amortization.
- Egg Trays:High-volume pressed molding dominates with cycle speeds optimized for throughput over customization. China's poultry processing belt and Germany's organized retail chains absorb the majority of global production volume.
- Food Containers:Thermoformed clamshells and hinged boxes serve quick-service restaurant chains and grocery deli counters. EU Green Deal enforcement timelines are compressing adoption schedules across French and German food service networks.
- Electronics Packaging:Sub-millimeter dimensional tolerances match vacuum-formed PET performance for smartphone and laptop protection. Vietnam and China's device assembly corridors specify these trays for automated feeding lines.
- Beverage Carriers:Molded pulp six-pack rings and cup holders displace plastic in craft brewing and specialty coffee channels. FDA fiber contact standards govern US market entry.
- Medical Packaging:Gamma-stable sterilizable trays for surgical kits remain underdeveloped relative to pharmaceutical blister formats. FDA device regulations and EU MDR compliance thresholds limit supplier pools.
- Cosmetic Boxes:Virgin pulp formulations with enhanced surface finish support premium unboxing experiences for skincare and fragrance brands.
Egg trays absorb the bulk of installed capacity; electronics packaging is expanding most quickly.
Material Grade:
Cost tier stratification separates medical and cosmetic segments demanding fiber consistency from food service applications competing on unit economics.
- Virgin Pulp:Medical and cosmetic applications require cleanliness thresholds that recycled streams cannot guarantee. FDA and EU EFSA contact standards enforce strict fiber sourcing documentation.
- Recycled Pulp:Post-consumer OCC content dominates food service trays and egg packaging where regulatory acceptance is broadest. Chinese SAMR GB standards and US EPA guidelines shape export-bound specifications.
- Bleached Pulp:Whitened fiber surfaces support high-graphics printing for retail cosmetic and premium food presentations.
- Unbleached Pulp:Natural brown aesthetics align with sustainability messaging in organic food and artisanal beverage segments.
- Specialty Fibers:Bamboo, wheat straw, and bagasse inputs reduce virgin wood dependency for brands targeting agricultural waste narratives.
- Coated Pulp:Water-based barrier treatments address moisture resistance gaps versus polyethylene in high-humidity food service environments.
Recycled pulp commands the largest volume footprint; specialty fibers are climbing the fastest as agricultural waste sourcing scales.
End User Industry:
Application maturity varies dramatically, with food and beverage representing legacy demand while healthcare penetration remains nascent.
- Food & Beverage:Quick-service restaurants, grocery chains, and food processors drive baseline demand across all material grades. India's FSSAI packaging mandates are opening virgin pulp entry points for global converters.
- Electronics Manufacturing:Smartphone OEMs in China and Vietnam specify precision-fit trays with dimensional stability matching legacy polystyrene. Thermoforming investments concentrate near Shenzhen and Ho Chi Minh City assembly corridors.
- Healthcare Facilities:Surgical kit sterilization trays and pharmaceutical distribution packaging face gamma stability and barrier performance hurdles that fiber formats have not fully cleared.
- Personal Care:Cosmetic brands leverage molded pulp for premium unboxing experiences and sustainability scorecard compliance.
- Consumer Goods:E-commerce fulfillment demands damage-resistant printed inserts that outperform generic corrugated dunnage in direct-to-consumer channels.
- Agricultural Supplies:Nursery pots, seed trays, and produce containers serve horticultural operations with biodegradability requirements that align with composting infrastructure availability.
Food and beverage retains the deepest supplier relationships; electronics manufacturing is gaining share fastest as polystyrene phase-outs accelerate.
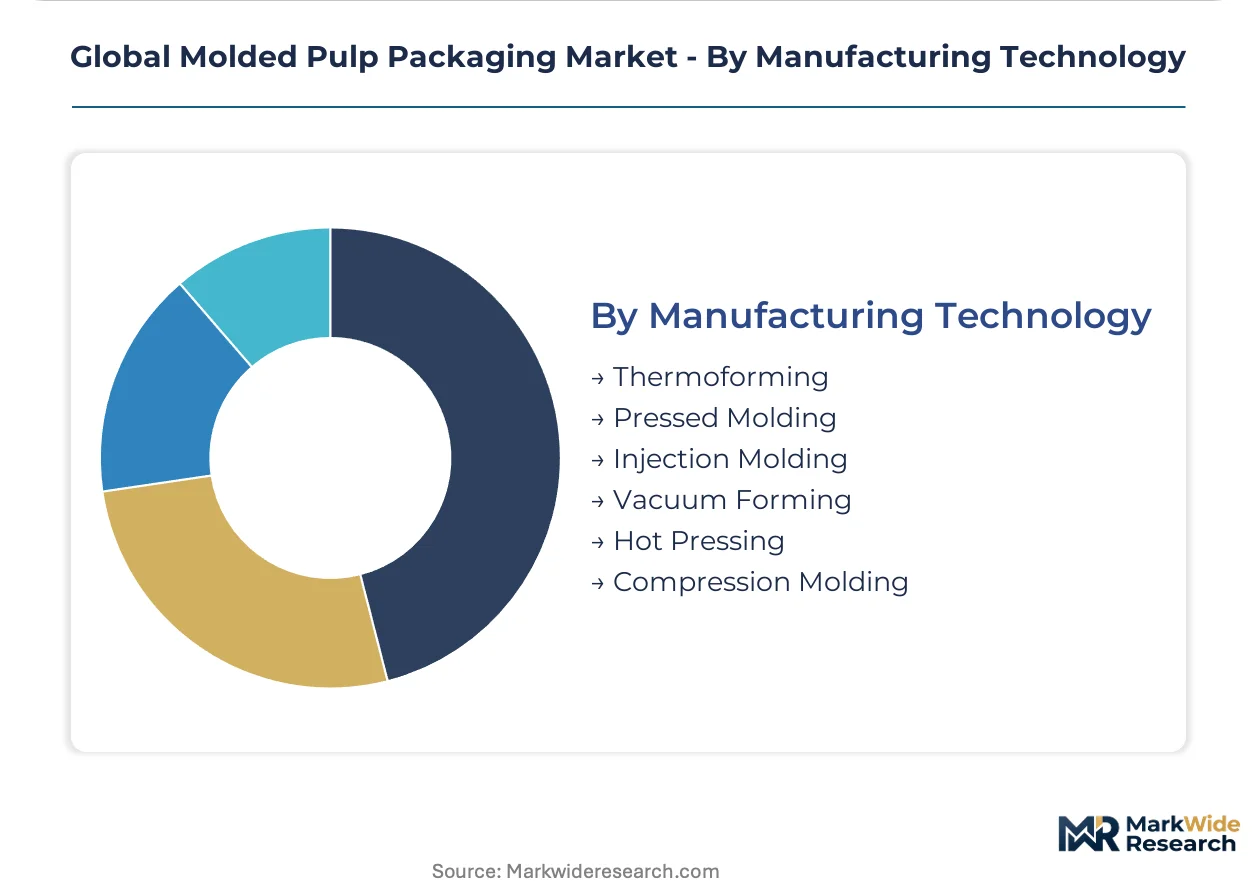
Manufacturing Technology:
Technology selection locks in capability boundaries, with thermoforming enabling precision electronics fitments while pressed molding sustains egg tray margins through cycle speed.
- Thermoforming:Heated pulp slurry vacuum-drawn over precision molds achieves sub-millimeter tolerances for electronics protection. Tooling costs and lead times restrict adoption to high-value applications.
- Pressed Molding:Matched metal dies compress fiber mats at high speed for egg trays and food service plates. German and Chinese converter networks concentrate capacity near poultry processing and quick-service restaurant distribution hubs.
- Injection Molding:Pulp slurry injection into closed molds supports complex geometries with undercuts and deep draws that thermoforming cannot achieve.
- Vacuum Forming:Lower-pressure fiber drawing suits shallow-draw applications with less stringent dimensional requirements.
- Hot Pressing:Post-mold densification improves surface smoothness and structural rigidity for premium cosmetic and medical applications.
- Compression Molding:Bulk fiber compression without slurry preparation suits thick-walled industrial protective packaging with lower finish requirements.
Pressed molding holds the largest installed base; thermoforming is scaling fastest as electronics specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's bonded logistics zones near Shenzhen and Dongguan concentrate thermoforming investments serving smartphone OEM assembly corridors. Germany's Industrie 4.0 tax incentives and France's green industrial zones anchor European converter expansion.
China
Electronics OEMs in Shenzhen and Dongguan specify precision-fit pulp trays for automated assembly lines. SAMR enforces GB standards for packaging recyclability that redirect export-bound production toward fiber specifications. Thermoforming capacity clusters in the Pearl River Delta where converter investments track smartphone manufacturing expansion.
Germany
Quick-service restaurant chains and organized retail drive food container demand across Baden-Württemberg and North Rhine-Westphalia. The EU Green Deal's single-use plastics ban compresses adoption timelines for pulp plate conversions ahead of 2025 milestones. Industrial composting infrastructure in Bavaria supports end-of-life claims that converters leverage for French and Benelux export.
United States
Consumer electronics distribution hubs in Texas and California absorb thermoformed protective packaging from dedicated molded fiber operations. FDA fiber contact standards and EPA guidelines shape specifications for food service applications. E-commerce fulfillment centers in the Midwest specify printed pulp inserts for damage-resistant unboxing experiences.
India
FSSAI packaging mandates banning certain plastic formats in quick-service restaurants open virgin pulp entry points for global converters. Food safety regulations in Maharashtra and Karnataka redirect procurement toward fiber-based alternatives. Converter investments cluster near Mumbai and Bengaluru to serve quick-service restaurant chain expansion.
Vietnam
Smartphone assembly corridors in Bac Ninh and Thai Nguyen provinces specify thermoformed trays with dimensional tolerances matching legacy polystyrene. Export-oriented manufacturing zones attract thermoforming capacity to serve Samsung and Apple supplier networks. Converter operations concentrate near Haiphong port logistics to minimize electronics shipment lead times.
Global Molded Pulp Packaging Market Competitive Landscape
Top-tier vendors anchor precision electronics and medical segments, while mid-cap specialists dominate high-volume egg tray and food service applications. The vendor base stratifies across thermoforming capability, pressed molding scale, and virgin pulp certification tiers. Three archetypes define competitive positioning: European precision thermoformers, North American integrated fiber converters, and Asian volume producers. Dominant moves include backward integration into pulp supply and geographic expansion near electronics assembly corridors.
Among Nordic and European specialists, Huhtamaki Oyj and Brødrene Hartmann A/S exemplify contrasting scale-positioning archetypes. Huhtamaki occupies a position within precision thermoforming for electronics protection, while Hartmann represents high-volume pressed molding specialization. Sonoco Products Co. anchors North American competitive positioning through integrated molded fiber operations. These three entities collectively illustrate the geographic and capability fragmentation that shapes procurement decisions across end-use segments.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Sonoco Products Co. |
| Brødrene Hartmann A/S |
| Genpak LLC |
| UFP Technologies |
| Sabert Corporation |
| Pactiv Evergreen Inc. |
| Henry Molded Products Inc. |
| WestRock Company |
| Others |
Supply & Pricing Matrix
The EU Green Deal's single-use plastics ban gates qualified supply and premium-tier pricing access for converters demonstrating certified fiber sourcing and composting pathway verification. Buyers in French and German food service networks pay premiums for documented compliance, while uncertified competitors face margin compression in spot markets.
Pricing Analysis
Short lead-time premiums apply to thermoformed electronics trays where precision aluminum mold fabrication cycles constrain rapid response capability. Three-tier pricing structure across premium, standard, and economy levels separates virgin pulp medical grades from recycled food service tiers and unbleached agricultural formats. Cost compression in recycled OCC tiers intensifies because Chinese import policy shifts create raw material volatility. Quick-service restaurant chains exhibit highest price sensitivity, while smartphone OEMs prioritize dimensional precision over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale electronics demand from Shenzhen and Bac Ninh assembly corridors, while distributor networks serve fragmented food service accounts. Raw material supply concentrates in China, Germany, and the United States where converter investments cluster near poultry processing belts and device manufacturing zones. Pulp slurry formulations draw from recycled OCC streams, virgin fiber certification pools, and agricultural waste inputs including wheat straw and bagasse. Single-source vulnerability runs through precision thermoforming tooling suppliers serving sub-millimeter tolerance specifications. Distribution runs through bonded logistics zones near Pearl River Delta ports and Haiphong export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoformed molded pulp is displacing vacuum-formed PET in electronics protection, compressing the addressable market for petroleum-based cushioning and rewriting capability requirements across converter tiers.
For Market Incumbents: Deploy backward integration into pulp supply to secure fiber certification documentation that meets EU EFSA and FDA contact standards. Add thermoforming capacity near Vietnam's Bac Ninh smartphone assembly corridor to capture Samsung and Apple supplier network demand. Counter polystyrene substitution threats by demonstrating automated assembly line feeding compatibility at sub-millimeter tolerances. For New Entrants and Emerging Players: Enter via India's FSSAI-mandated quick-service restaurant conversions in Maharashtra and Karnataka, where plastic format bans create immediate virgin pulp demand without established supplier relationships. Target medical device sterilizable trays as an underdeveloped segment relative to pharmaceutical blister packaging maturity. Lead with gamma stability certification and surgical kit compliance documentation as the go-to-market anchor. For Investors and Strategic Acquirers: SAMR enforcement of GB standards for packaging recyclability is the leading indicator that export-bound Chinese production will redirect toward fiber specifications at scale. Five-to-ten year viability centers on converters with thermoforming precision capability and certified pulp supply chain control. Acquire mid-cap specialists with virgin pulp certification and European composting infrastructure partnerships. Watch for EU Green Deal packaging waste regulation revision milestones as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Thermoforming Capacity Expansion | Sub-millimeter tolerance capability captures smartphone OEM tray specifications from Shenzhen to Ho Chi Minh City. |
| Virgin Pulp Certification Investment | FDA and EU EFSA contact standard documentation unlocks medical and cosmetic segment premium pricing tiers. |
| Backward Integration into Agricultural Waste Sourcing | Wheat straw and bagasse inputs reduce virgin wood dependency for brands targeting sustainability scorecard compliance. |
| Industrial Composting Infrastructure Partnerships | Bavaria and organized German waste streams support end-of-life claims that converters leverage for Benelux export. |
| Direct-to-OEM Channel Development | Hyperscale electronics buyers in Dongguan and Bac Ninh require dedicated supply agreements with automated feeding line compatibility. |
Research Methodology
Independent corroboration across converter operations data, regulatory filing databases, and OEM procurement specifications underwrites the qualitative findings in this study. Primary interviews with thermoforming plant managers, pulp procurement leads at major converters, food service category buyers, and electronics OEM packaging engineers combined with secondary validation from SAMR GB standards documentation, EU ECHA REACH substance restrictions, FDA fiber contact guidelines, and trade flow customs records. Bottom-up capacity assessments and top-down demand segmentation triangulate volume estimates across the analysis window.
Historical reference periods anchored the forecast framework to observed adoption curves for polystyrene substitution in electronics and EU Green Deal compliance timelines in food service. Segmentation dimensions modeled include packaging type, material grade, manufacturing technology, and end-use industry vertical. CAGRs were derived from growth rate convergence analysis across multiple scenario assumptions. Industry-specific forecast inputs incorporated smartphone assembly line automation requirements and extended producer responsibility fee structures.
Revisions become necessary when Chinese OCC import policy shifts, EU packaging waste regulation enforcement timelines, or thermoforming tooling capacity constraints materialize differently than assumed. Forecasts reflect documented assumptions about substitution elasticity and certification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Molded Fiber Trays Market