
 Foamer Bottle Market | 2026-2036
Foamer Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Foamer Bottle Market Foresight
REACH compliance is consolidating the European cost-of-entry calculus for foamer bottle suppliers seeking polymer chemistry approvals. Graham Packaging leverages captive blow-molding infrastructure across multiple continents to sustain volume commitments to multinational hygiene brands. Alpla anchors its position through backward integration into recycled PET flake processing for cosmetic-grade foamers. Gerresheimer competes in the premium pharmaceutical segment with borosilicate glass foamer assemblies that command specialized regulatory dossiers.
A foamer bottle integrates a dispensing pump mechanism with a specialized mesh or air-liquid mixing chamber to aerate liquid formulations into stable foam without propellants, typically constructed from polypropylene or polyethylene components with silicone valve elements to control viscosity flow and prevent back-contamination. The device serves industrial and consumer markets requiring metered, touch-free, or portable application of soaps, sanitizers, and cleaning chemistries. Refillable foamer systems capture expanding margin pools as foodservice providers and hospitality chains adopt closed-loop dispensing programs to reduce single-use plastic penalties. Automatic foamer units lead growth in healthcare sanitation applications where sensor-activated delivery minimizes cross-contamination risk in surgical suites and patient rooms. Standard foamers retain volume dominance in commercial hand hygiene installations though face substitution pressure from wall-mounted alternatives in space-constrained facilities.
The EPA regulates antimicrobial claims on foamer-dispensed sanitizers in the United States, requiring substantiated efficacy data that shapes product labeling and channel access for institutional buyers. ECHA enforces REACH restrictions on per- and polyfluoroalkyl substances that are displacing certain lubricant additives historically used in pump mechanism assemblies across European supply chains. ISO 22196 antimicrobial surface testing standards influence procurement specifications for medical facility end users evaluating material performance in high-touch environments. Stakeholders must monitor evolving state-level extended producer responsibility legislation and determine whether regional formulation registration investments or platform standardization strategies offer superior capital efficiency.
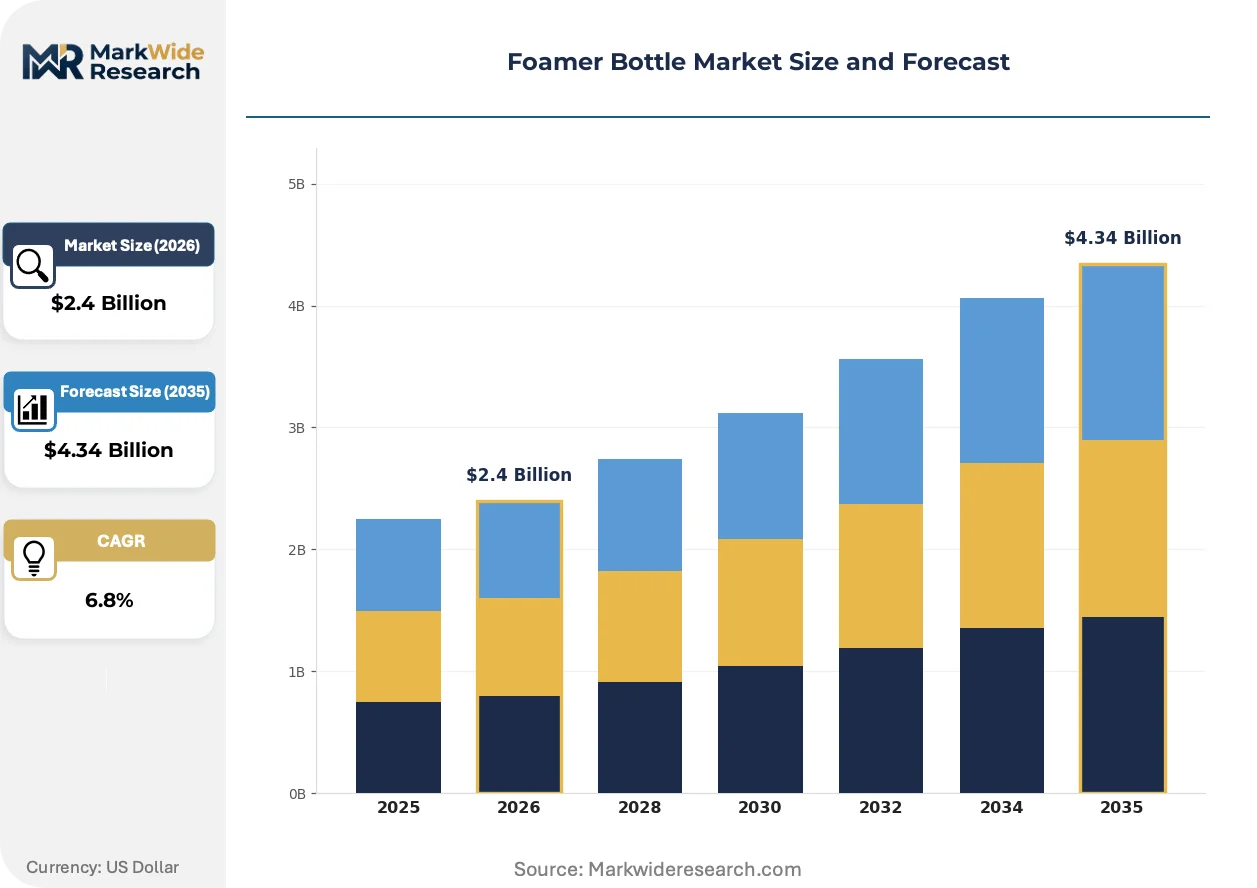
Market Dynamics
EU Green Deal packaging waste directives are compressing polymer selection windows for foamer bottle manufacturers, forcing rapid material transitions before circular economy mandates take full effect across European supply chains.
Growth Catalysts
- Healthcare sanitation protocols:Infection control tightening in surgical suites and patient rooms drives sensor-activated automatic foamer unit installations.
- REACH compliance consolidation:Polymer chemistry approval requirements in Europe raise barriers for new entrants, protecting established suppliers with dossier-ready formulations.
- Closed-loop dispensing programs:Foodservice and hospitality chains adopt refillable foamer systems to preempt single-use plastic penalties.
Market Restraints
- Recycled PET flake supply concentration:Cosmetic-grade foamer production depends on limited European processors with food-contact certification.
- Per- and polyfluoroalkyl substance restrictions:ECHA REACH rules displace legacy lubricant additives, requiring pump mechanism redesigns.
- Borosilicate glass cost structure:Premium pharmaceutical foamers face input cost volatility from energy-intensive glass manufacturing.
Strategic Opportunities
- Underpenetrated Indian institutional sector:Hospital and hotel chains lack standardized foamer dispensing infrastructure despite rising hygiene investment.
- Sensor-foam technology convergence:Integration of IoT-enabled usage tracking with touch-free delivery creates premium positioning in medical facilities.
- Extended producer responsibility tailwinds:German packaging waste legislation creates first-mover advantage for refillable platform providers.
Industry Challenges
- Polymer formulation certification timelines:FDA and EMA bioavailability studies for pharmaceutical-grade foamers extend product development cycles.
- Antimicrobial surface testing complexity:ISO 22196 compliance requires specialized laboratory partnerships that concentrate in Germany and Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foamer Bottle Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Foamer, Wall-Mounted Foamer, Refillable Foamer, Automatic Foamer, Portable Foamer Application: Hand Hygiene, Industrial Cleaning, Food Preparation, Healthcare Sanitation, Hospitality Services Material: Plastic, Stainless Steel, Aluminum, Glass, Silicone End User: Commercial Establishments, Foodservice Providers, Medical Facilities, Educational Institutions, Laboratories |
| Companies Covered | Graham Packaging, NOVIO, Alpla, Taplast, Cambrian Packaging, Gerresheimer, Plastipak Holdings, MJS Packaging, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foamer Bottle Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are simultaneously expanding performance requirements and constraining formulation freedom for foamer bottle producers across medical and cosmetic applications.
Air-liquid mixing chamber geometries with computational fluid dynamics optimization are rewriting foam stability benchmarks for high-viscosity pharmaceutical formulations. Surgical suite procurement teams specify these enhanced designs for metered dosing applications. The technology is compressing competitive differentiation around legacy mesh-based systems.
REACH restrictions on per- and polyfluoroalkyl substances eliminate certain pump lubricant chemistries from European supply chains. Manufacturers reformulate silicone valve elements to maintain viscosity flow control without prohibited additives. Medical device assemblers in Germany and France face the tightest compliance deadlines.
Refillable platform contracts now dominate institutional purchasing for foodservice and hospitality chains. Bulk concentrate supply agreements replace single-unit procurement, shifting margin capture toward closed-loop logistics providers. This pattern concentrates in German-speaking markets with mature reverse logistics infrastructure.
Foamer Bottle Market Segmentation
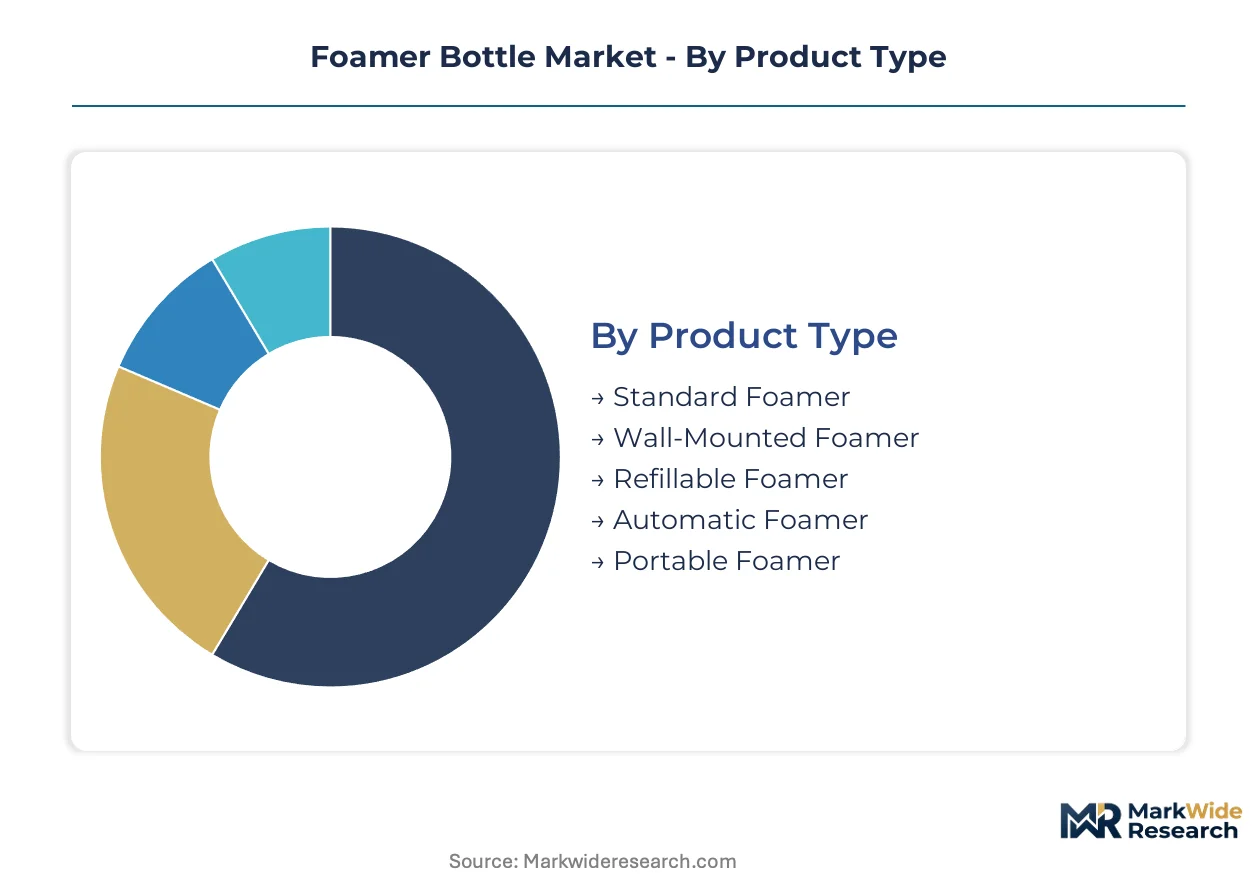
Foamer bottle segmentation reveals how technical specifications, regulatory requirements, and end-use environments fragment demand across incompatible product architectures. Manufacturers optimize pump mechanisms, material selection, and mounting configurations for distinct operational contexts rather than pursuing universal platforms.
Product Type:
Technical differentiation in dispensing mechanisms creates five distinct performance tiers, each engineered for specific installation constraints and user interaction patterns.
- Standard Foamer:Manual pump systems with polypropylene mesh chambers dominate commercial hand hygiene installations. Demand concentrates in North American office buildings and retail spaces where cost-per-unit drives procurement decisions. EPA antimicrobial claim requirements shape formulation compatibility testing.
- Automatic Foamer:Sensor-activated units with solenoid-driven air-liquid mixing eliminate cross-contamination touchpoints. Surgical suites in German and French hospitals specify these for infection control protocols. IoT-enabled usage tracking creates premium positioning in medical procurement.
- Wall-Mounted Foamer:Fixed installation systems optimize space-constrained facility layouts.
- Refillable Foamer:Closed-loop concentrate systems serve hospitality chains with reverse logistics infrastructure.
- Portable Foamer:Compact handheld units target field service and mobile healthcare applications.
Standard foamers lead on scale; automatic foamers lead on momentum.
Application:
End-use environments impose divergent performance specifications on foam stability, chemical compatibility, and contamination prevention.
- Healthcare Sanitation:Metered dosing systems with borosilicate glass or medical-grade polymer assemblies meet EMA bioavailability requirements. German hospital procurement teams specify ISO 22196 antimicrobial surface compliance. Regulatory dossier complexity extends product development timelines.
- Hand Hygiene:High-frequency dispensing in commercial restrooms demands durability-optimized polypropylene pumps. Volume concentrates in US institutional buyers subject to OSHA workplace sanitation guidelines. Formulation registration with EPA shapes channel access.
- Industrial Cleaning:Heavy-duty chemical compatibility drives material selection toward stainless steel and fluoropolymer seals.
- Food Preparation:Food-contact certification requirements from EFSA and national regulators constrain polymer choices.
- Hospitality Services:Aesthetic customization and brand differentiation influence premium segment procurement.
Hand hygiene leads on scale; healthcare sanitation climbs the fastest.
Material:
Supply chain configuration and circular economy mandates drive material substitution patterns across regulatory jurisdictions.
- Plastic:Polypropylene and polyethylene formulations with recycled content integration serve cost-sensitive volume segments. EU Green Deal packaging waste directives accelerate rPET flake adoption in cosmetic-grade applications. REACH compliance requirements consolidate supplier bases.
- Glass:Borosilicate assemblies command pharmaceutical premium pricing due to chemical inertness and regulatory dossier acceptance. Energy-intensive manufacturing creates input cost volatility. Swissmedic and EMA approvals concentrate demand in German-speaking markets.
- Stainless Steel:Industrial-grade corrosion resistance targets chemical processing environments.
- Aluminum:Lightweight metal options serve portable and premium cosmetic segments.
- Silicone:Valve element applications depend on reformulation to eliminate per- and polyfluoroalkyl substances under ECHA restrictions.
Plastic leads on scale; glass leads on margin expansion.
End User:
Procurement sophistication and compliance burden vary sharply across institutional buyer categories.
- Medical Facilities:Hospital systems impose stringent FDA and EMA device classification requirements on pharmaceutical-grade foamers. German and French surgical suite procurement drives specification intensity. Antimicrobial surface testing partnerships concentrate in Switzerland and Germany.
- Foodservice Providers:Chain operators adopt closed-loop refillable platforms to preempt extended producer responsibility penalties. German packaging waste legislation creates first-mover advantage for logistics-integrated suppliers.
- Commercial Establishments:Office and retail buyers prioritize total cost of ownership in high-volume installations.
- Educational Institutions:Public sector procurement rules and budget cycles shape demand patterns.
- Laboratories:Research facilities specify precision dosing and chemical compatibility for specialized formulations.
Medical facilities lead on specification intensity; foodservice providers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision blow-molding techniques for pharmaceutical dispensing systems during the 1980s, establishing technical standards that now govern European foamer bottle specifications. This industrial lineage continues to shape procurement patterns across medical and cosmetic end-use segments.
Germany
Pharmaceutical OEMs in Bavaria and North Rhine-Westphalia drive demand for EMA-compliant borosilicate glass foamers with specialized regulatory dossiers. The EU Green Deal packaging waste directives compel rapid transitions to recycled PET flake processing for cosmetic-grade applications. Stuttgart-based polymer compounders now supply REACH-certified formulations to medical device assemblers facing tightened compliance deadlines.
United States
OSHA workplace sanitation guidelines and EPA antimicrobial claim requirements shape institutional procurement for high-volume hand hygiene installations. Healthcare systems in Texas and California specify sensor-activated automatic foamers for infection control in surgical suites. Midwestern blow-molding clusters supply cost-optimized polypropylene systems to commercial restroom operators.
France
ANSM medical device regulations and hospital procurement centralization concentrate demand for ISO 22196 antimicrobial surface testing in the Île-de-France region. Lyon-based cosmetic formulators source refillable foamer platforms to preempt extended producer responsibility penalties. Strasbourg polymer processors specialize in silicone valve elements reformulated to eliminate per- and polyfluoroalkyl substances.
India
Hospital and hotel chains in Maharashtra and Karnataka lack standardized foamer dispensing infrastructure despite rising hygiene investment. CDSCO pharmaceutical regulations create compliance pathways for domestic medical-grade foamers. Ahmedabad packaging converters develop cost-adapted manual pump systems for foodservice providers expanding closed-loop programs.
China
Yangtze River Delta cosmetic manufacturers integrate air-liquid mixing chambers with computational fluid dynamics optimization for high-viscosity formulations. NMPA bioavailability studies extend product development timelines for pharmaceutical-grade exports. Shenzhen electronics assemblers supply IoT-enabled usage tracking modules for touch-free medical applications.
Foamer Bottle Market Competitive Landscape
The competitive structure tilts toward integrated packaging conglomerates with captive blow-molding infrastructure and specialized pharmaceutical specialists with regulatory dossier capabilities. Tier-one suppliers combine backward integration into recycled flake processing with multi-continent manufacturing footprints. Mid-scale converters compete on regional logistics efficiency and formulation registration speed. Dominant competitive moves include strategic partnerships with hygiene brand multinationals and capacity expansion in German-speaking medical device clusters.
Among European-based specialists, Gerresheimer exemplifies the premium pharmaceutical archetype through borosilicate glass foamer assemblies, while Alpla anchors the circular economy tier with in-house rPET flake processing for cosmetic applications. Graham Packaging represents the scale-driven multinational model with volume commitments across institutional hygiene segments.
| Leading Market Players |
|---|
| Graham Packaging |
| NOVIO |
| Alpla |
| Taplast |
| Cambrian Packaging |
| Gerresheimer |
| Plastipak Holdings |
| MJS Packaging |
| Berry Global |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EMA-compliant pharmaceutical foamers and commodity hand-hygiene units bifurcates both margin capture and supplier base concentration across European and North American supply chains. Premium-tier borosilicate glass assemblies command dedicated regulatory dossier investments while polypropylene volume segments compete on resin cost pass-through efficiency.
Pricing Analysis
Bundled closed-loop logistics contracts versus unbundled per-unit procurement splits the pricing architecture for institutional buyers. Three-tier pricing structure across premium pharmaceutical, standard commercial, and economy foodservice levels reflects certification intensity and after-sales service integration. Pricing pressure stems from recycled PET flake supply bottlenecks in cosmetic-grade applications. Foodservice chains exhibit highest price sensitivity due to extended producer responsibility penalty exposure, while German hospital systems prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German pharmaceutical polymer compounders and Chinese IoT sensor module suppliers for automatic foamer assemblies. Manufacturing concentrates in Germany, China, and the United States across distinct tier specializations. Raw material dependencies encompass medical-grade polypropylene, borosilicate glass tubing, and silicone valve elastomers reformulated for REACH compliance. Tariff exposure on Chinese electronics components threatens automatic foamer cost structures. Distribution runs through hygiene brand multinational direct procurement channels and regional packaging converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in sensor-integrated automatic foamer platforms where IoT-enabled usage tracking commands premium positioning above commodity manual pump systems.
For Market Incumbents: Deepen backward integration into recycled PET flake processing to preempt cosmetic-grade supply constraints under EU Green Deal mandates. Lock in long-term concentrate supply agreements with foodservice chains before extended producer responsibility legislation hardens in German-speaking markets. Defend against Asian electronics assemblers entering medical-grade automatic foamer segments by accelerating FDA 510(k) dossier filings. For New Entrants and Emerging Players: Sensor-foam technology convergence with antimicrobial surface testing partnerships offers entry leverage into underpenetrated Indian hospital procurement. Target Maharashtra and Karnataka medical facilities lacking standardized dispensing infrastructure. Pursue CDSCO regulatory pathway investments to outpace domestic packaging converters on compliance timelines. Lead with refillable platform economics against single-use plastic penalties in hospitality chains. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs exceed standalone revenue bases for mid-scale European polymer compounders. Five-to-ten year viability favors integrated players with captive blow-molding and regulatory dossier capabilities. Acquisition target archetype: German medical device assemblers with ISO 22196 testing partnerships and EMA submission track records. Signal to watch: CDSCO fast-track approvals triggering multinational licensing interest in Indian manufacturing partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Polymer Reformulation | Stuttgart compounders supply certified formulations ahead of ECHA deadline compression. |
| Closed-Loop Refillable Platform Expansion | German packaging waste legislation rewards logistics-integrated hospitality suppliers. |
| IoT-Enabled Sensor Integration | Shenzhen electronics partnerships differentiate automatic foamers in surgical suite procurement. |
| Antimicrobial Surface Testing Partnership | Swiss and German laboratory relationships accelerate ISO 22196 compliance for medical facilities. |
| CDSCO Regulatory Pathway Investment | Domestic Indian approval positions converters for multinational hygiene brand licensing. |
Research Methodology
Bottom-up healthcare sanitation and foodservice demand modeling reconciled against top-down blow-molding capacity tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, cosmetic formulators, packaging converter operations heads, and regulatory affairs specialists at polymer compounders combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, EU packaging waste directive implementation schedules, and German reverse logistics infrastructure databases. Triangulation between end-use demand signals and supply-side manufacturing footprints ensures cross-verified volume estimates.
Input-output matrices map pump mechanism type, material grade tier, and end-use regulatory intensity across the projection horizon. Segmentation dimensions encompass product architecture, application environment, material certification level, and buyer procurement sophistication. CAGRs derive from installed base replacement cycles, infection control protocol adoption curves, and circular economy mandate compliance timelines. Pharmaceutical bioavailability study durations and food-contact certification processing speeds constitute industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction expansions, state-level extended producer responsibility adoption patterns in the United States, and CDSCO regulatory pathway streamlining effectiveness. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Biotainer Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market