
 Molded Fiber Cup Market | 2026-2036
Molded Fiber Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Cup Market Foresight
Food-grade barrier coating certification is rotating from niche premium to baseline procurement requirement across institutional buyers. Huhtamaki leverages its integrated pulp-to-package manufacturing footprint across Europe and North America to sustain volume leadership. Pactiv Evergreen anchors the North American quick-service channel through direct supply agreements with major burger and coffee chains. Brødrene Hartmann differentiates via molded fiber specialization in egg packaging that extends into foodservice cup formats with shared pulp sourcing infrastructure.
Molded fiber cups are rigid containers formed from recycled paper pulp or agricultural fibers through vacuum-forming or press-molding processes, typically featuring a thin bio-based or clay barrier coating to resist liquid penetration for minutes to hours. The primary commercial purpose is to replace expanded polystyrene and plastic-lined paper cups in foodservice takeaway and dine-in applications. Hot beverage cups dominate current volume owing to coffee chain procurement scale, while food containers capture expanding margin pools as grease-resistant formulations improve. Takeaway services lead application demand, though fast food outlets represent the fastest-growing channel as drive-through and delivery formats multiply.
The US FDA regulates food-contact substance migration limits for barrier coatings, while the EU F-Gas Regulation and REACH restrict certain chemical treatments used in pulp processing. California's SB 54 and New York's expanded polystyrene ban create state-level compliance layers that reshape product specifications and disqualify non-fiber alternatives from institutional bids. Stakeholders must monitor whether emerging PFAS restrictions in Washington State and Maine cascade into broader North American sourcing standards that would force second-generation barrier chemistry investments.
Market Dynamics
The EU Single-Use Plastics Directive and cascading state-level bans across the United States are forcing material substitution at scale, converting institutional procurement specifications from plastic-tolerant to fiber-mandatory within compressed compliance windows.
Growth Catalysts
- EU Single-Use Plastics Directive:Member states must eliminate expanded polystyrene foodservice containers by 2026, redirecting quick-service restaurant procurement toward molded fiber alternatives with certified barrier coatings.
- Quick-service restaurant channel:Major burger and coffee chains in the United States have committed to eliminating foam and plastic-lined cups by decade's end, creating guaranteed offtake volumes for domestic molded fiber suppliers.
- Agricultural fiber sourcing:Bagasse and wheat straw pulp processing is expanding beyond traditional paper markets, diversifying raw material inputs and reducing dependence on recycled OCC fiber.
Market Restraints
- Natural gas price volatility:Thermal energy for pulp drying and molded fiber press operations constitutes a significant production cost component, exposing margin structures to European and North American energy market fluctuations.
- Barrier coating chemistry limitations:Current bio-based and clay coatings achieve minutes to hours of liquid resistance, constraining adoption in extended-hold beverage applications where plastic-lined alternatives maintain performance superiority.
- Washington State PFAS restrictions:Emerging per- and polyfluoroalkyl substance prohibitions in food packaging create compliance uncertainty that delays long-term supply contracts until second-generation barrier formulations achieve certification.
Strategic Opportunities
- India foodservice expansion:Quick-service restaurant penetration in tier-2 and tier-3 Indian cities remains underdeveloped, presenting first-mover positioning for molded fiber cup suppliers as FSSAI food-contact regulations tighten.
- Drive-through format proliferation:Coffee and fast-food chains are expanding vehicle-centric service models that prioritize stackable, lightweight cup designs where molded fiber structural properties outperform rigid plastic alternatives.
- California SB 54 compliance:The state's extended producer responsibility framework creates preferential procurement pathways for fiber-based packaging meeting source reduction and recyclability benchmarks.
Industry Challenges
- Food-grade barrier certification timelines:FDA migration limit testing and EU EFSA novel food-contact substance approvals require 18-36 month validation cycles that delay product commercialization and lock in competitive positioning.
- Thermoforming press capacity constraints:Molded fiber cup production requires capital-intensive matched-die tooling and high-tonnage pressing equipment that limits rapid capacity scaling in response to demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Cup Market |
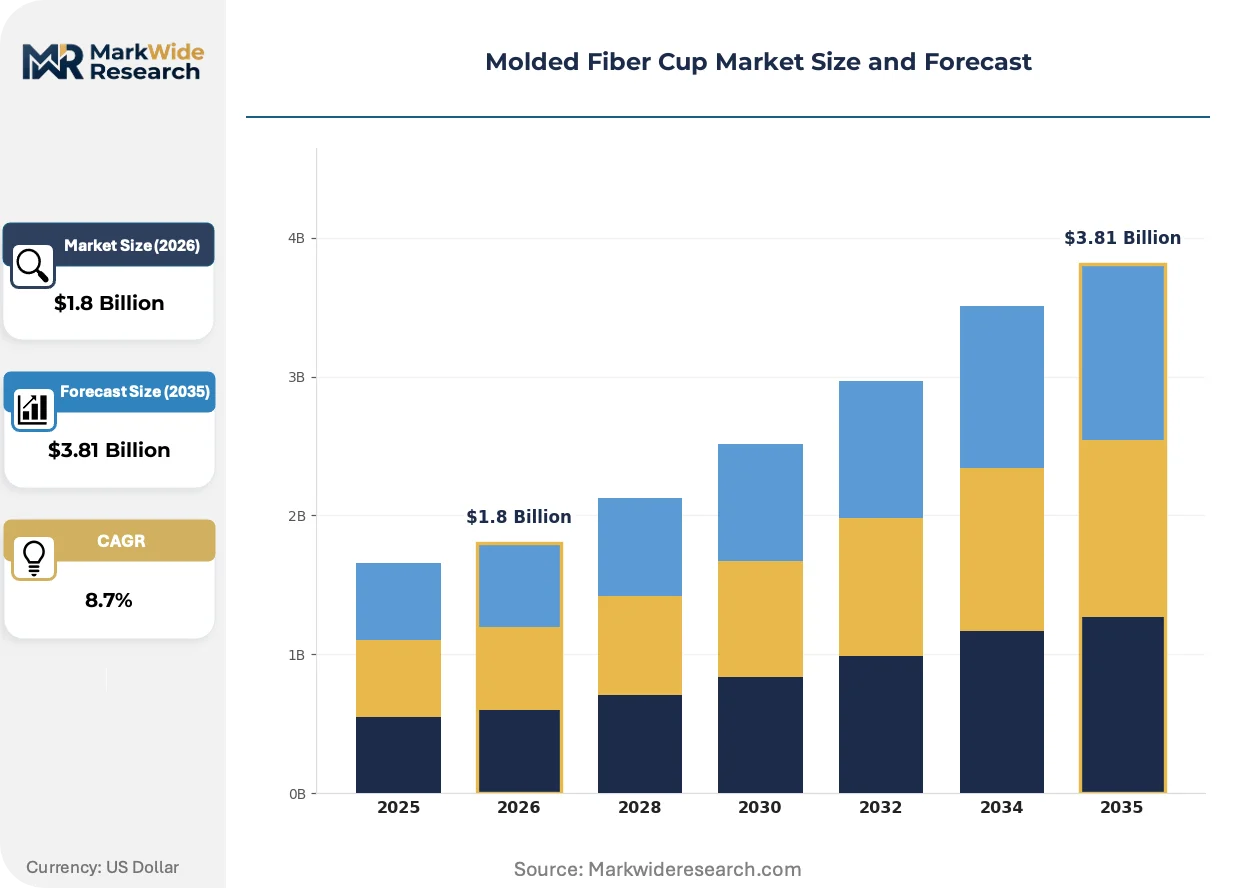
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Beverage Cups, Cold Drink Cups, Food Containers, Sushi Trays End User: Restaurants, Cafés, Catering Services, Food Retailers Distribution Channel: Online Retailers, Supermarkets, Wholesalers, Direct Sales Application: Takeaway Services, Events, Picnics, Fast Food Outlets |
| Companies Covered | Huhtamaki, Pactiv Evergreen, Genpak, Sonoco Products, Dart Container Corporation, Brødrene Hartmann, UFP Technologies, CKF Inc., Sabert Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Cup Market Shifts & Advancements
Barrier coating chemistry and fiber molding precision are advancing in parallel, collapsing the performance gap between molded fiber and plastic-lined alternatives while regulatory pressure accelerates procurement specification changes.
Aluminosilicate clay barrier coatings are decomposing the traditional trade-off between liquid resistance and end-of-life compostability. Coffee chains in the Pacific Northwest and Scandinavia have accelerated adoption of these formulations for hot beverage applications. The technology is decomposing incumbent petroleum-based liner market share by meeting both FDA migration limits and BPI compostability certification within single product architectures.
REACH restrictions on fluorinated substances are eliminating PFAS-treated molded fiber from European foodservice supply chains. Manufacturers are reformulating barrier layers around polysaccharide and plant-wax chemistries to maintain grease resistance. Hot food containers and extended-hold beverage cups face the steepest compliance redesign requirements, with German and French quick-service operators leading qualification programs for PFAS-free alternatives.
Direct supplier-chain contracting is consolidating procurement authority within quick-service restaurant headquarters, displacing distributor-mediated purchasing for cup specifications. Category managers now mandate fiber content percentages and certified compostability as non-negotiable bid criteria. This concentration is most visible in United States burger and coffee chains where sustainability commitments require supply base consolidation to achieve auditability and volume scale.
Molded Fiber Cup Market Segmentation
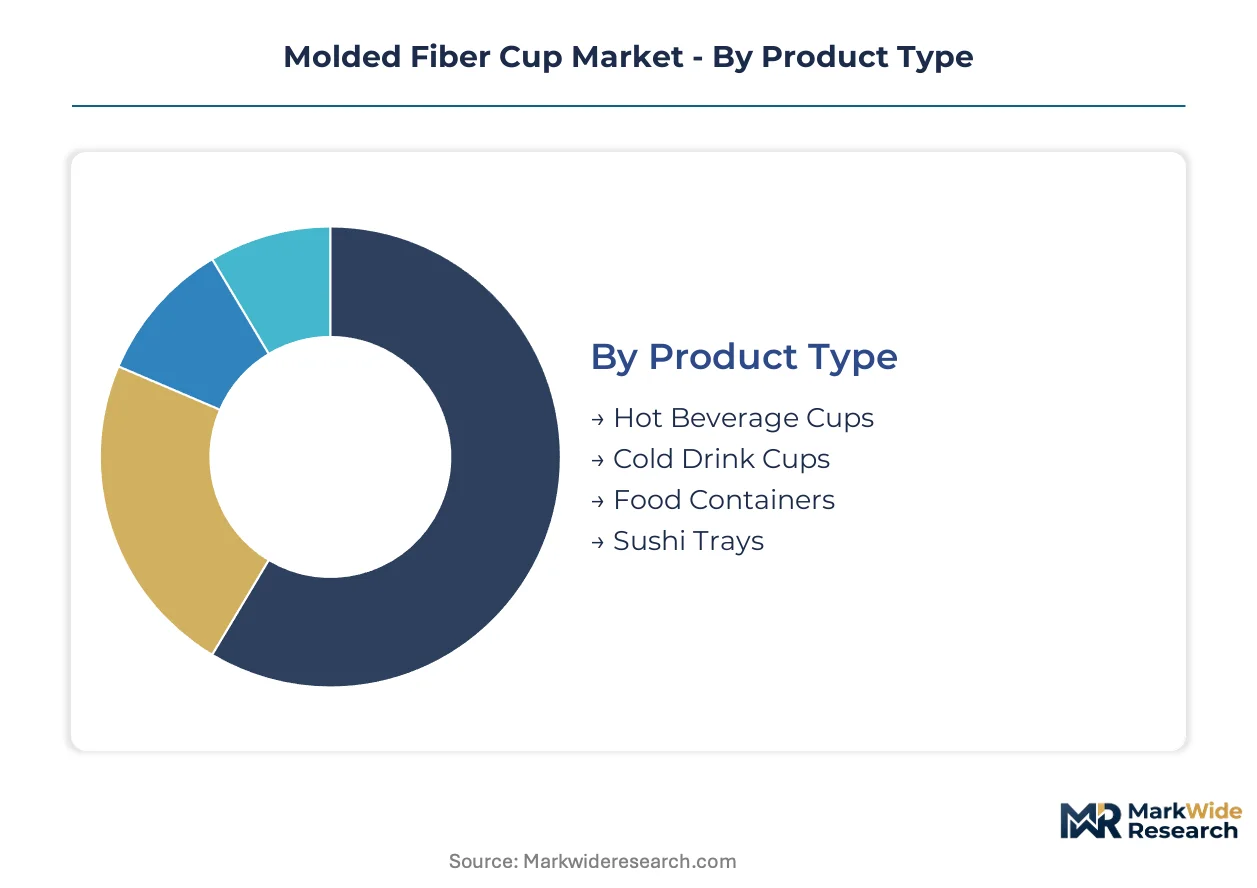
Molded fiber cup procurement varies sharply across end-use contexts, with quick-service restaurant headquarters driving consolidated volume while fragmented food retail channels demand flexible minimum order quantities. Segmentation reveals where barrier coating investments concentrate and which distribution pathways reward premium certification tiers.
Product Type:
Domestic production dominates hot beverage and food container formats, while cold drink cups and specialty trays see heavier export flows to European markets with stricter PFAS compliance timelines.
- Hot Beverage Cups:Double-walled vacuum-formed structures with aluminosilicate clay barrier coatings withstand temperatures exceeding 85°C for 30-60 minutes. Coffee chains in the United States and Germany anchor procurement scale, driven by EU Single-Use Plastics Directive deadlines eliminating foam alternatives.
- Food Containers:Press-molded clamshell and bowl configurations incorporate polysaccharide grease barriers for hot food contact. Quick-service burger chains and institutional catering operators in France and California specify these for extended-hold delivery applications.
- Cold Drink Cups:Single-wall formations with bio-based moisture resistance serve iced beverage formats.
- Sushi Trays:Precision-molded compartments with soy sauce compartmentalization target Japanese and North American premium food retail.
Hot beverage cups command the established base. The steepest expansion runs through food containers.
End User:
Cost tier stratification separates institutional buyers with dedicated sustainability procurement teams from price-sensitive independent operators purchasing through distributor catalogs.
- Restaurants:Full-service and fast-casual establishments specify molded fiber for dine-in and takeaway presentation. Chains with 50+ locations in the United States increasingly mandate direct supplier relationships to secure volume pricing and auditability.
- Cafés:Independent coffee shops and regional roasting chains prioritize stackability and printed branding compatibility. Scandinavian and Pacific Northwest markets lead compostability certification requirements.
- Catering Services:Event and institutional foodservice demands large-format containers with transport durability.
- Food Retailers:Supermarket deli and prepared food sections drive seasonal volume spikes around holidays.
Restaurants absorb the majority of current volume. Cafés are climbing the fastest as specialty coffee penetration deepens in tier-2 cities.
Distribution Channel:
Volume concentration tilts toward direct sales for national accounts, while fragmented regional players sustain wholesaler and supermarket private-label channels.
- Direct Sales:Manufacturer-to-headquarter contracts with quick-service restaurant chains lock in multi-year offtake agreements. Pactiv Evergreen and Huhtamaki dominate this pathway through dedicated account management and co-development programs.
- Wholesalers:Broadline foodservice distributors aggregate demand from independent restaurants and smaller chains. This channel carries higher inventory carrying costs but captures price-sensitive buyers outside major metropolitan procurement zones.
- Online Retailers:E-commerce platforms serve small-batch buyers and startup food brands.
- Supermarkets:Private-label molded fiber cup programs target consumer picnic and home entertaining segments.
Direct sales capture margin premiums through contract security. Online retailers are gaining share fastest as digital procurement habits solidify among small operators.
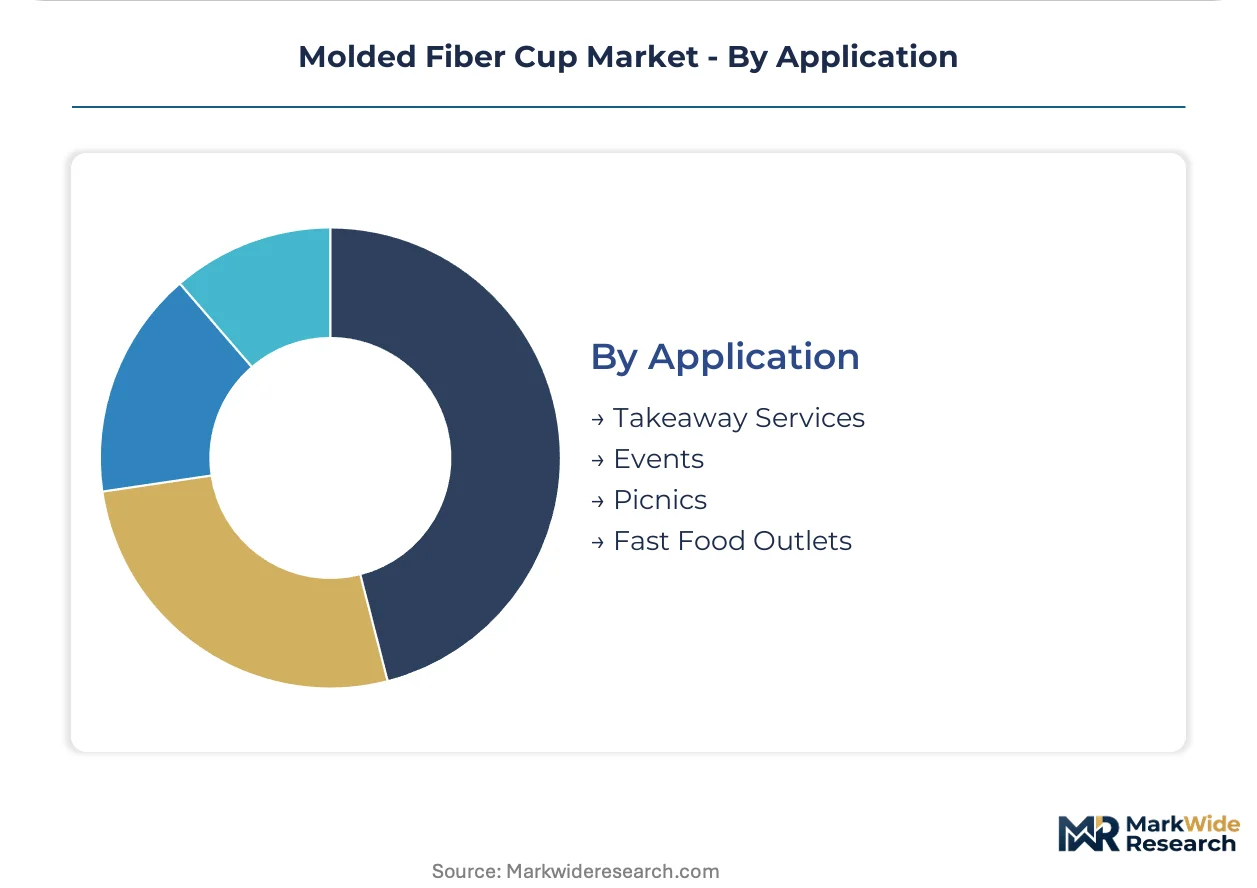
Application:
Takeaway and fast food formats reward structural rigidity and nesting density, while events and picnics prioritize retail-ready consumer packaging aesthetics.
- Takeaway Services:Delivery-optimized cup designs feature vented lids and spill-resistant rim geometries. Third-party delivery platform growth in the United States and United Kingdom sustains demand for stackable, lightweight formats.
- Fast Food Outlets:Drive-through and grab-and-go formats demand rapid-cup dispensability and standardized lid interchangeability. Major burger chains specify these parameters in supplier qualification protocols.
- Events:Stadium and festival catering requires high-volume disposability with visible sustainability credentials.
- Picnics:Consumer retail packs emphasize aesthetic presentation and multi-item assortment.
Takeaway services anchor current procurement volumes. Fast food outlets show the steepest expansion trajectory as drive-through format proliferation accelerates across suburban United States markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in molded fiber cup trade tilt toward deficit positions in European markets with stringent PFAS deadlines, while North American producers leverage integrated pulp-to-package infrastructure to serve cross-border quick-service restaurant procurement.
United States
Quick-service restaurant headquarters in Chicago and Seattle drive consolidated demand for certified compostable cups. California's SB 54 extended producer responsibility framework mandates source reduction benchmarks that favor fiber-based packaging in institutional bids. Georgia's pulp mill corridor supplies bagasse and recycled OCC fiber to Southeast molding operations serving drive-through chains.
Germany
REACH restrictions on fluorinated substances have eliminated PFAS-treated molded fiber from foodservice supply chains, forcing reformulation around polysaccharide barriers. The EU Single-Use Plastics Directive deadline of 2026 accelerates foam replacement procurement by quick-service operators. Hamburg's port logistics cluster handles imported agricultural fiber pulp from Southeast Asian processors.
France
Quick-service burger chains and institutional catering operators in Paris lead qualification programs for PFAS-free hot food containers with extended-hold grease resistance. ANSM food-contact substance notifications create 18-24 month approval timelines for novel barrier coatings. The Lyon-Auvergne-Rhône-Alpes corridor hosts specialized thermoforming press operations for precision-molded cup geometries.
India
Tier-2 and tier-3 city quick-service restaurant penetration remains underdeveloped, presenting positioning opportunities as FSSAI food-contact regulations tighten enforcement. The Plastic Waste Management Rules prohibit single-use plastic cups in foodservice, redirecting procurement toward molded fiber alternatives. Maharashtra's sugar belt supplies bagasse pulp to Western India molding facilities serving Mumbai-Pune foodservice clusters.
United Kingdom
Third-party delivery platform growth in London and Manchester sustains demand for stackable, lightweight takeaway cup formats. The Environment Agency's packaging waste regulations impose recycling targets that disadvantage plastic-lined alternatives in corporate procurement. Birmingham's manufacturing hub hosts distributors aggregating fragmented independent restaurant demand through broadline foodservice channels.
Molded Fiber Cup Market Competitive Landscape
Concentration sits with integrated pulp-to-package conglomerates and specialized molded fiber fabricators serving distinct channel tiers. The vendor base splits between volume leaders with captive fiber sourcing and regional specialists competing on barrier certification speed. Two strategic archetypes dominate: integrated conglomerates controlling upstream pulp supply, and precision thermoforming specialists optimizing press utilization across multiple foodservice formats. Capacity expansion and direct supplier-chain contracting constitute the dominant competitive moves, as quick-service restaurant headquarters consolidate procurement authority away from distributor-mediated purchasing.
Within the integrated conglomerate tier, Huhtamaki and Pactiv Evergreen occupy positions defined by geographic manufacturing footprints and direct account relationships with major quick-service chains. Brødrene Hartmann exemplifies the specialization archetype, leveraging shared pulp sourcing infrastructure across egg packaging and foodservice cup formats. These three anchors represent contrasting strategic postures: European-North American integrated production, North American quick-service channel anchoring, and Nordic molded fiber specialization extending into adjacent foodservice applications.
| Leading Market Players |
|---|
| Huhtamaki |
| Pactiv Evergreen |
| Genpak |
| Sonoco Products |
| Dart Container Corporation |
| Brødrene Hartmann |
| UFP Technologies |
| CKF Inc. |
| Sabert Corporation |
| Others |
Supply & Pricing Matrix
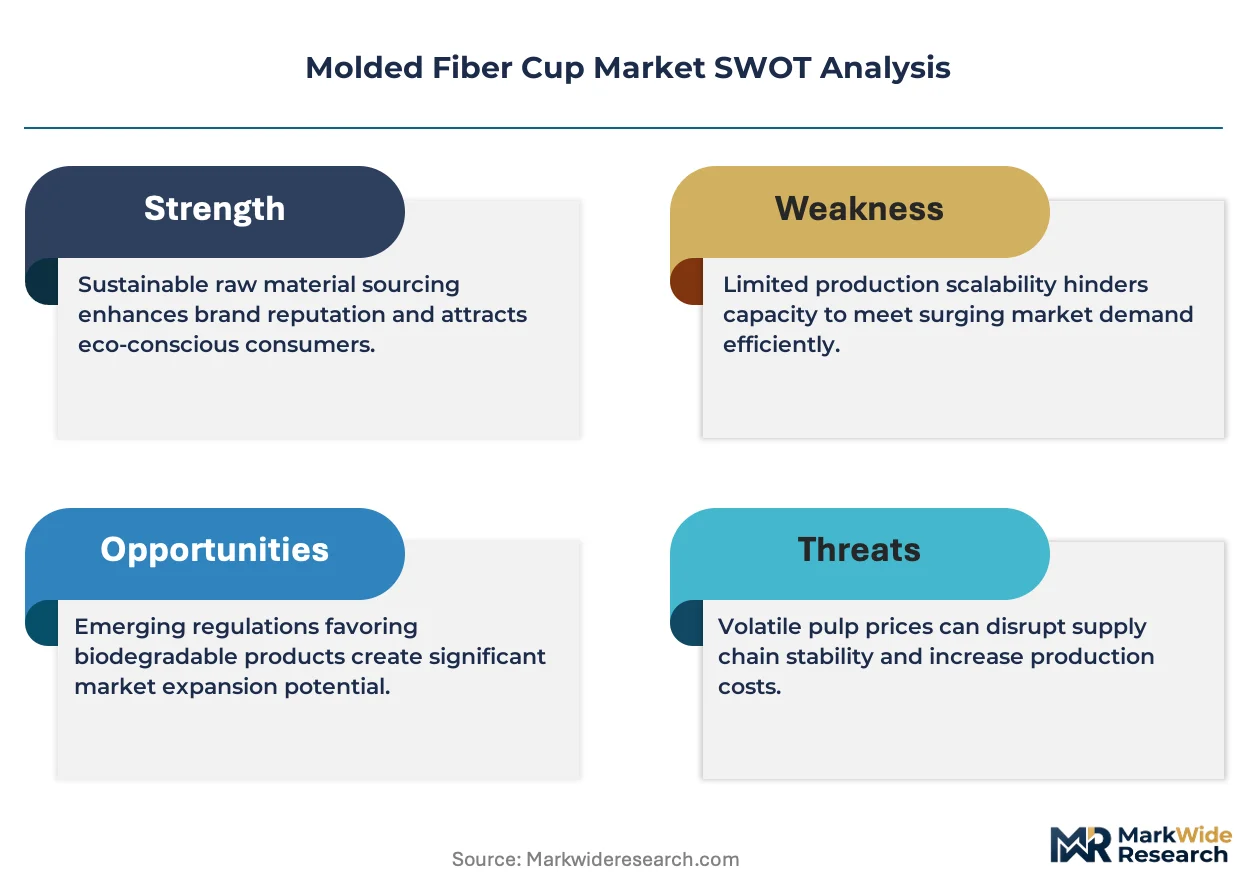
FDA food-contact substance migration limits gate both supplier qualification and price tier differentiation in the molded fiber cup market, compressing procurement timelines while elevating certified barrier coatings to premium positioning. Institutional buyers with direct supplier relationships capture volume discounts unavailable to fragmented foodservice operators purchasing through distributor channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for quick-service restaurant headquarters, while independent cafés and regional chains face spot-market exposure. Price differentiation rests on BPI compostability certification tier and FDA migration limit compliance grade, with PFAS-free formulations commanding substantial premiums over conventional clay barriers. Cost compression in standard-grade cups is intensifying because agricultural fiber pulp supply competition is expanding beyond traditional recycled OCC sources. National quick-service chains exhibit the lowest price sensitivity due to sustainability audit requirements, whereas independent restaurants purchasing through broadline distributors remain highly price-responsive.
Supply Chain Analysis
Strategic stockpiling of bagasse and wheat straw pulp is displacing just-in-time recycled fiber procurement as agricultural fiber processing scales beyond traditional paper markets. Supply concentration centers on Georgia's pulp mill corridor in the United States, Germany's Hamburg port logistics cluster, and Maharashtra's sugar belt in India. Raw material dependencies include agricultural fiber pulp, aluminosilicate clay barrier coatings, and high-tonnage thermoforming press equipment. Single-source vulnerability runs through European PFAS-compliant barrier coating suppliers facing REACH reformulation deadlines. Distribution runs through direct manufacturer-to-headquarter contracts for national accounts, with broadline wholesalers capturing fragmented regional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified thermoforming press capacity represents the critical scarce asset in this market, with qualified equipment operators and FDA-validated barrier chemists commanding decisive competitive positioning. The capability gap between integrated pulp-to-package conglomerates and regional specialists is widening as compliance timelines compress.
For Market Incumbents: Compound defensive positioning through captive agricultural fiber sourcing in Southeast United States sugar-processing regions and accelerated PFAS-free barrier certification investment ahead of Washington State and Maine regulatory deadlines. Threat substitution from rigid bioplastic alternatives demands preemptive volume lock-in with quick-service restaurant headquarters through co-development programs for next-generation grease-resistant formulations. For New Entrants and Emerging Players: FDA fast-track certification for novel polysaccharide barrier coatings opens procurement access to Pacific Northwest coffee chains and Scandinavian institutional buyers with the most aggressive compostability mandates. White-space concentration sits in tier-2 Indian city quick-service penetration and European extended-hold hot food container applications where PFAS elimination has eliminated incumbent supply bases. Go-to-market positioning through third-party delivery platform private-label programs bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoforming press capacity expansion as matched-die tooling lead times extend and qualified equipment operators become scarcer. Long-term viability over the next decade favors acquisition targets with validated FDA food-contact substance approvals and established direct supplier relationships with quick-service restaurant headquarters. The signal to watch is Washington State PFAS restriction enforcement cascading into broader North American sourcing standards, which would force second-generation barrier chemistry investments and disqualify non-compliant suppliers from institutional bids.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Fiber Sourcing | Captive bagasse and wheat straw supply from Georgia and Maharashtra pulp mills insulates margin structures from recycled OCC fiber price volatility. |
| PFAS-Free Barrier Certification Investment | Polysaccharide and plant-wax chemistry validation ahead of REACH and state-level restrictions secures European and Pacific Northwest quick-service procurement. |
| Thermoforming Press Capacity Expansion | High-tonnage matched-die equipment installation in Southeast United States manufacturing corridors captures drive-through chain volume growth. |
| Direct Supplier-Chain Contracting Consolidation | Manufacturer-to-headquarter relationships with burger and coffee chains displace distributor-mediated purchasing and lock in multi-year offtake security. |
| India Market Entry Positioning | FSSAI food-contact regulation alignment and tier-2 city distribution partnerships establish first-mover advantage as Plastic Waste Management Rules enforcement tightens. |
Research Methodology
The analysis maps hot beverage cups, food containers, cold drink cups, and sushi trays as product segments, each validated through procurement directors at quick-service restaurant headquarters, thermoforming press operators, barrier coating chemists, and broadline foodservice distributors. Primary interviews combined with secondary validation from FDA food-contact substance filings, EU EFSA novel food notifications, BPI compostability certification databases, and state-level extended producer responsibility regulatory texts. Bottom-up volume modeling across end-user segments triangulated against top-down pulp consumption and press capacity estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and application format, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from demand elasticity analysis relative to quick-service restaurant format expansion and substitution rates from foam and plastic-lined alternatives. Forecast inputs incorporated natural gas price volatility assumptions for pulp drying operations and PFAS restriction enforcement probability weighting.
Underlying assumptions cover sustained EU Single-Use Plastics Directive compliance deadlines and California SB 54 extended producer responsibility framework implementation, with deviation risk concentrated in Washington State PFAS restriction cascade timing and agricultural fiber pulp supply scaling rates. Revision becomes warranted when second-generation barrier coating certification timelines exceed 36 months or when thermoforming press capacity utilization crosses threshold levels that trigger equipment shortage pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market