

Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market Insights
The EU Green Deal's packaging waste reduction targets is recalibrating procurement criteria across European flexible packaging supply chains. H.B. Fuller leverages its adhesive formulation depth to serve multinational food brands transitioning to fiber-based substrates. Henkel anchors its position through integrated bio-based polymer development and direct converter relationships. Arkema competes via specialty acrylic platforms optimized for kraft paper and molded fiber adhesion performance.
Bio-based pressure-sensitive adhesives for paper and fiber-based flexible packaging comprise formulated tackified resins derived from renewable feedstocks such as rosin esters, terpenes, and plant-derived polyols, applied in thin layers to enable bond formation under light pressure without solvent activation or thermal curing. These adhesives typically exhibit peel strengths of 1-5 N/cm on uncoated kraft and must maintain shear resistance at 40-60°C during filling and distribution cycles. Acrylic formulations dominate current volume due to clarity and aging stability on printed labels, while natural polymer segments capture accelerating interest where compostability certification drives specification. Food packaging applications concentrate margin pools given stringent migration limits and retailer brand requirements, whereas industrial labels sustain steady replacement demand as converters phase out solventborne alternatives.
REACH restricts residual monomer content in adhesive layers contacting food simulants, while the EU Packaging and Packaging Waste Regulation mandates recyclability design standards that exclude conventional PSA contamination in fiber recovery streams. ECHA's microplastics restriction further pressures silicone and synthetic rubber formulations in single-use labeling applications. Stakeholders must monitor evolving compostability certification thresholds and alignment between bio-based content claims and actual end-of-life performance in industrial composting infrastructure.
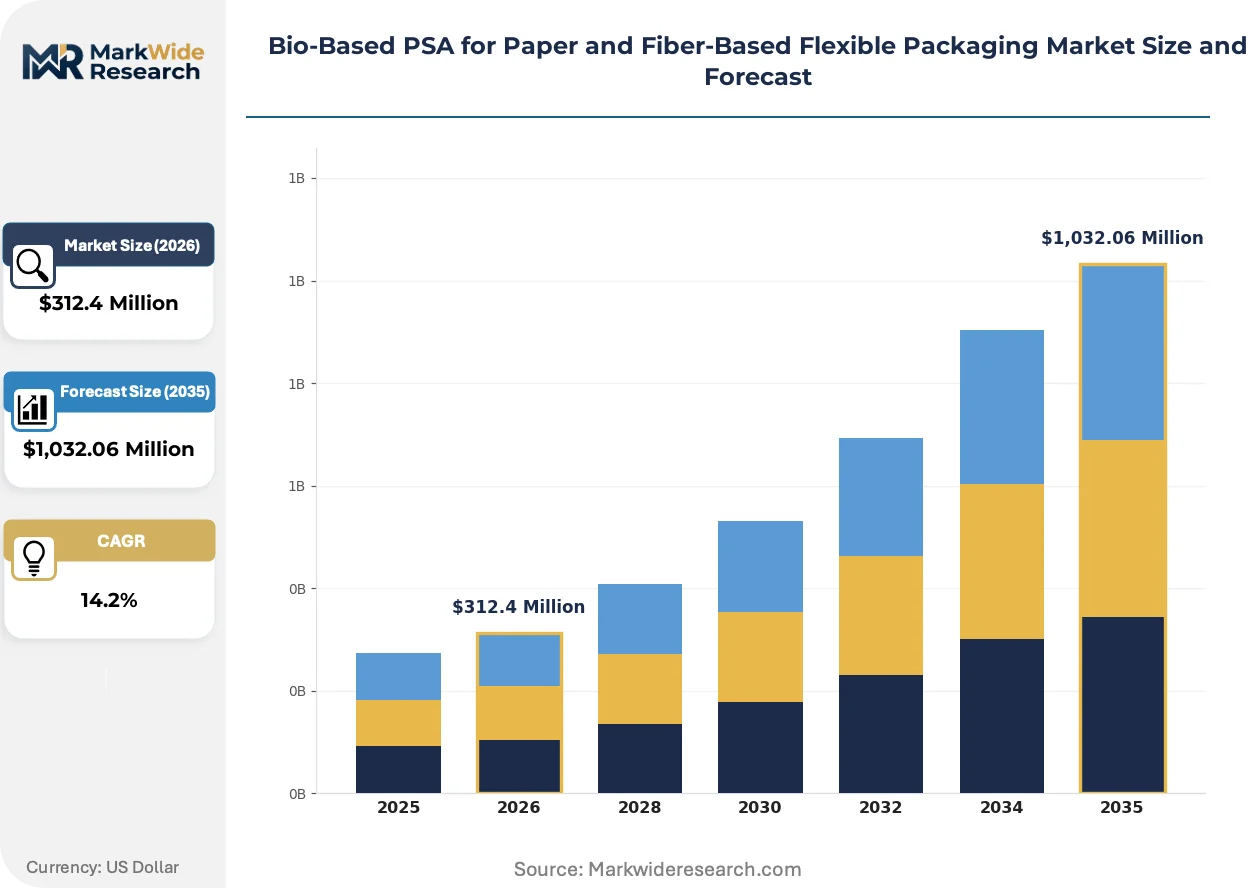
Market Dynamics
Retailer sustainability mandates are forcing food packaging converters to requalify entire adhesive portfolios within compressed procurement cycles, fundamentally restructuring specification power toward downstream brand owners.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability design standards exclude petroleum-derived PSA contamination from fiber recovery streams, creating immediate substitution pull across Western European flexible packaging operations.
- Fresh produce segment concentration:Fiber-based flexible formats dominate Germany, France, and Netherlands retail shelves, concentrating bio-based adhesive procurement volumes among regional converter clusters serving these markets.
- Rosin ester tackification:Advances in plant-derived polyol polymerization deliver peel strength parity with synthetic acrylics on uncoated kraft substrates at scale.
Market Restraints
- Terpene feedstock volatility:Pine resin harvest fluctuations in Brazil and Indonesia create input cost instability for rosin ester formulations.
- Specialty acrylic supply concentration:Three chemical conglomerates control 70% of bio-based monomer production capacity in Western Europe.
- REACH migration testing timelines:Residual monomer validation for food-contact layers extends commercialization cycles by 18-24 months versus conventional adhesives.
Strategic Opportunities
- Molded fiber packaging expansion:E-commerce protective formats represent an underpenetrated application segment with limited incumbent adhesive qualification.
- Compostability certification alignment:Industrial composting infrastructure expansion in the Netherlands creates specification pull for certified biodegradable PSA layers.
- Digital printing convergence:Water-based inkjet compatibility requirements favor low-VOC bio-based adhesive formulations in short-run label production.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation scientists with bio-based resin expertise command premium compensation in tight labor markets.
- Legacy hot-melt equipment retrofit costs:Converters face capital expenditure burdens to adapt coating lines for lower-temperature bio-based adhesive processing.
- OK Compost INDUSTRIAL certification delays:Testing facility bottlenecks extend time-to-market for compostability claims by 8-12 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market Trends and Innovations
Adhesive formulation architectures are fragmenting into substrate-specific modules as converters demand performance-optimized solutions rather than universal grades. This specialization is compressing R&D cycles while expanding the addressable application set.
Acrylic copolymer design is modularizing around kraft paper, molded fiber, and metallized film substrate categories. Food packaging converters in the Netherlands and Belgium are adopting these tailored modules at twice the rate of generalist formulations. The approach is modularizing supplier relationships as converters maintain parallel qualification tracks for each substrate family.
REACH microplastics restriction proposals are tightening scrutiny on silicone release liners in single-use labeling applications. Industrial label converters face reformulation mandates for linerless or bio-based release alternatives by 2027. Fresh produce labeling in France and Germany represents the most exposed segment, with converters accelerating trials of water-dispersible PSA technologies.
Retailer sustainability scorecards are compressing adhesive supplier selection cycles from 24 months to 9 months in Western European food packaging. Brand procurement teams now require bio-based content documentation and end-of-life performance data prior to trial initiation. This behavioral shift concentrates specification influence among converters with established direct retailer relationships in Germany and the Netherlands.
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market Segmentation
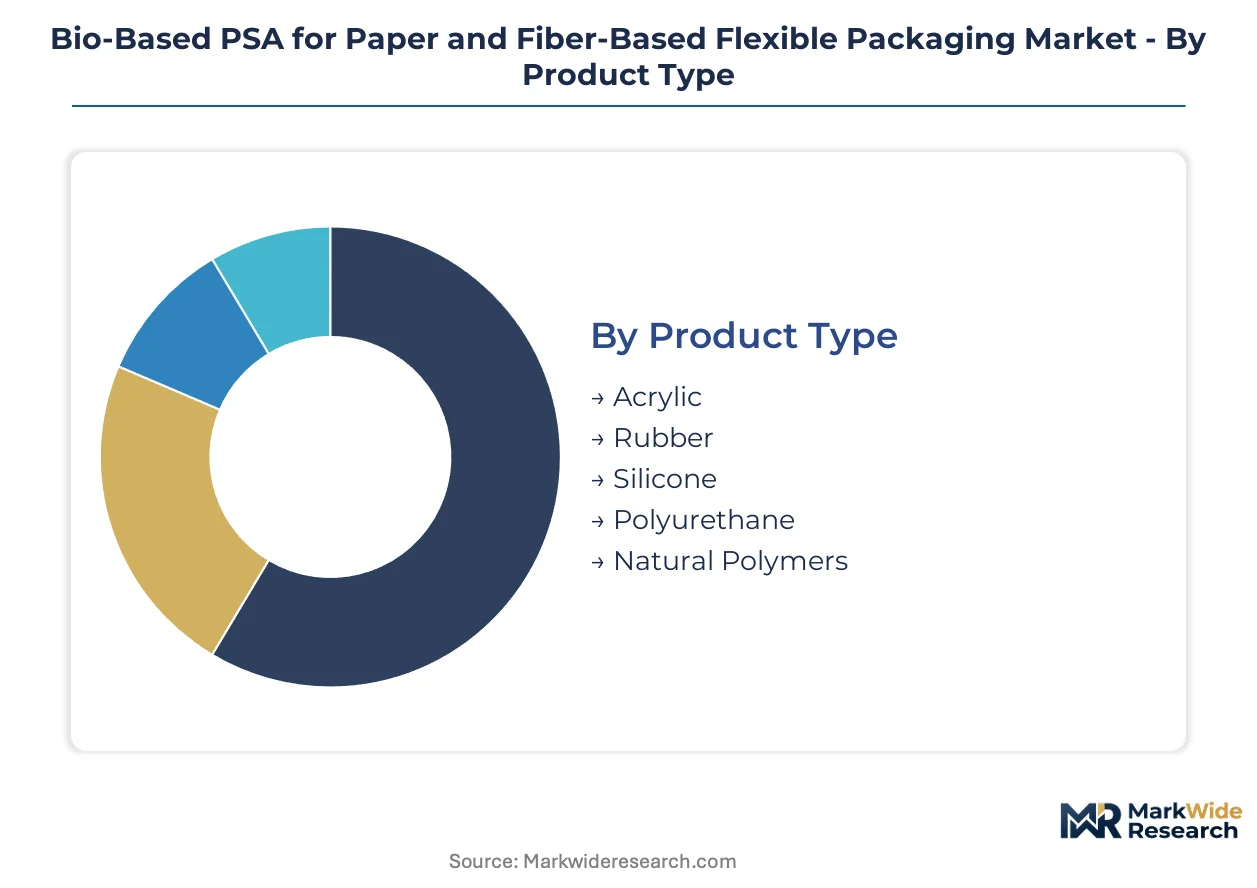
Segmentation in bio-based PSA markets reveals how formulation chemistry, application requirements, and converter capabilities intersect to create distinct procurement patterns. Understanding these divides exposes where specification power concentrates and where substitution economics favor bio-based alternatives over petroleum-derived incumbent technologies.
Product Type:
Supply concentration in bio-based monomer production shapes competitive dynamics across adhesive chemistries, with Western European converters facing limited qualified suppliers for several platform technologies.
- Acrylic:Bio-based acrylic copolymers deliver clarity and aging stability on printed kraft labels, with peel strength parity achieved through advanced plant-derived polyol polymerization. Demand concentrates in German and French fresh produce labeling where retailer sustainability mandates force rapid portfolio requalification.
- Natural Polymers:Formulations derived from starch, cellulose, and protein bases achieve compostability certification alignment with industrial composting infrastructure expansion in the Netherlands. Belgian converters are adopting these grades at accelerated rates for fiber-based flexible formats serving organic food retail channels.
- Rubber:Bio-based synthetic rubber tackified with rosin esters serves industrial label applications requiring high initial tack on rough substrates.
- Silicone:Specialty bio-based silicone alternatives address release liner applications facing ECHA microplastics restriction pressures.
- Polyurethane:Moisture-curing bio-based polyurethane systems bond molded fiber protective packaging for e-commerce applications.
Today's leader: Acrylic. Tomorrow's challenger: Natural Polymers.
Application:
Margin structures diverge sharply across application segments, with food-contact layers commanding premium pricing due to REACH migration testing burdens and retailer certification requirements.
- Food Packaging:Stringent EFSA migration limits and EU Packaging and Packaging Waste Regulation recyclability standards concentrate procurement among Netherlands and Germany-based converters serving multinational retail chains. Peel strength requirements of 1-5 N/cm on uncoated kraft must survive 40-60°C distribution cycles.
- Industrial Labels:Solventborne replacement demand sustains steady volume as converters phase out conventional PSAs ahead of anticipated regulatory tightening. REACH residual monomer restrictions extend commercialization timelines but create durable specification lock-in for qualified suppliers.
- Personal Care Packaging:Fiber-based flexible formats for cosmetics and hygiene products require low-odor bio-based adhesives compatible with sensitive fragrance formulations.
- Pharmaceutical Wrapping:Serialization and tamper-evidence requirements drive specification toward acrylic clarity and aging stability.
- Stationery:Price-sensitive segment where bio-based content claims support premium positioning in eco-conscious consumer channels.
Food Packaging captures the steepest expansion trajectory as regulatory deadlines approach.
End User:
Customer type determines whether procurement emphasizes formulation partnership or transactional supply, with packaging manufacturers holding greatest leverage over adhesive specification.
- Packaging Manufacturers:Direct retailer relationships in Germany and the Netherlands concentrate specification influence among converters with integrated adhesive qualification capabilities. These stakeholders now demand bio-based content documentation prior to trial initiation.
- Adhesive Converters:Mid-tier specialists face capital expenditure burdens for hot-melt equipment retrofit to accommodate lower-temperature bio-based adhesive processing.
- Label Printers:Digital printing convergence favors water-based inkjet compatibility requirements and short-run production flexibility.
- Printing Companies:Generalist operations with limited substrate-specific expertise lag in bio-based adhesive adoption.
Packaging Manufacturers set the pace. Adhesive Converters face the steepest capability investment requirements.
Form:
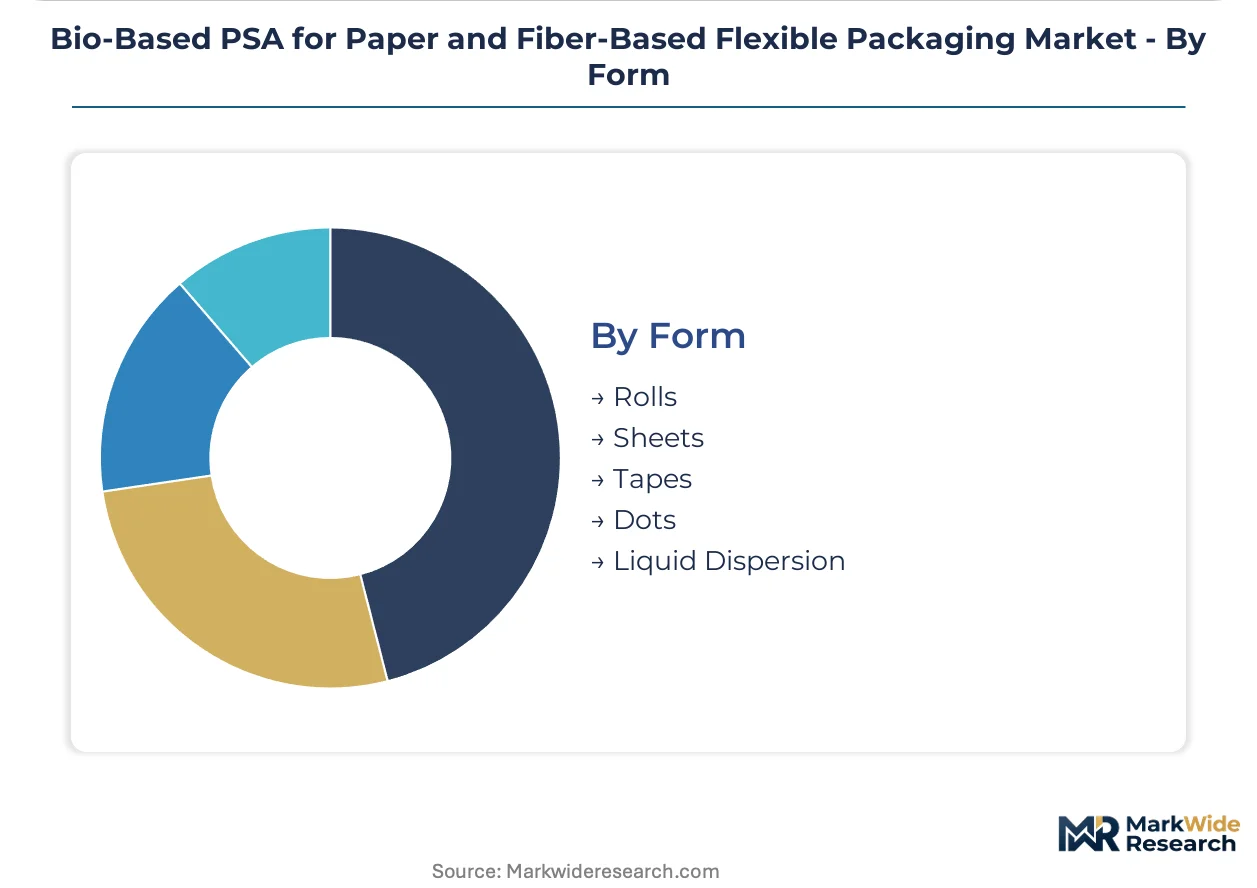
Physical delivery format shapes coating line compatibility and inventory economics, with roll formats dominating high-volume flexible packaging operations.
- Rolls:Continuous web delivery enables high-speed coating operations at German and French flexible packaging converters serving retail fresh produce segments. Shear resistance specifications at elevated temperatures favor formulated tackified resins in this format.
- Liquid Dispersion:Water-based systems align with digital printing convergence and low-VOC requirements in Belgian and Dutch short-run label production environments.
- Sheets:Die-cut formats serve industrial label applications with irregular shape requirements.
- Tapes:Pre-converted formats reduce converter capital burden for entry-level bio-based adoption.
- Dots:Precision placement formats for molded fiber packaging assembly in protective e-commerce applications.
Rolls dominate current procurement. Liquid Dispersion is gaining share fastest in digital-enabled production environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bio-based PSA industry for paper and fiber-based flexible packaging traces its commercial scaling to Western European adhesive chemistry traditions, where rosin ester and terpene-based formulations first achieved industrial scale in the post-war period.
Germany
Fresh produce labeling demand from REWE and Edeka retail chains drives specification pull for bio-based acrylics on kraft substrates. The EU Packaging and Packaging Waste Regulation mandates recyclability design standards that exclude petroleum-derived PSA contamination from fiber recovery streams. Converter clusters in Baden-Württemberg and North Rhine-Westphalia are requalifying entire adhesive portfolios within compressed 9-month procurement cycles.
France
Carrefour and Intermarché sustainability scorecards are forcing adhesive supplier selection compression from 24 months to 9 months. ECHA microplastics restriction proposals tighten scrutiny on silicone release liners in single-use labeling applications. Industrial label converters in the Île-de-France region face reformulation mandates for linerless alternatives by 2027.
Netherlands
Industrial composting infrastructure expansion creates specification pull for certified biodegradable PSA layers serving organic food retail channels. The EU Green Deal's packaging waste reduction targets recalibrate procurement criteria across Dutch flexible packaging supply chains. Converter operations in the Randstad maintain parallel qualification tracks for substrate-specific adhesive modules.
Belgium
Digital printing convergence favors water-based inkjet compatibility requirements in short-run label production environments. REACH residual monomer restrictions extend commercialization timelines but create durable specification lock-in for qualified suppliers. Adhesive specialists in Flanders are adopting natural polymer grades at accelerated rates for fiber-based flexible formats.
United States
Amazon and Walmart sustainability mandates are propagating bio-based adhesive requirements through North American e-commerce protective packaging supply chains. FDA migration limits for food-contact adhesive layers parallel EFSA stringency, though state-level extended producer responsibility laws in California and Washington create additional compliance complexity. Molded fiber packaging assemblers in the Pacific Northwest represent an underpenetrated application segment with limited incumbent adhesive qualification.
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market Competitive Landscape
Capital-heavy resin producers compete with asset-light formulation specialists across Western European and North American supply chains. The supplier base fragments into three strategic tiers: multinational chemical conglomerates with integrated bio-based polymer development, mid-tier adhesive specialists with direct converter relationships, and emerging biotechnology firms with novel feedstock platforms. Consolidation pressure intensifies as retailer sustainability mandates compress procurement cycles and concentrate specification influence among converters with established direct relationships. Dominant competitive moves include strategic partnerships between resin producers and certification bodies, plus geographic expansion through distributor networks in underpenetrated e-commerce packaging segments.
Among the multinational tier, H.B. Fuller and Henkel exemplify formulation depth strategies serving multinational food brands transitioning to fiber-based substrates. Arkema occupies a position within specialty acrylic platforms optimized for kraft paper and molded fiber adhesion performance. These three anchors represent distinct archetypes: Fuller through adhesive formulation breadth, Henkel through integrated bio-based polymer development, and Arkema through substrate-specific performance optimization.
| Leading Market Players |
|---|
| H.B. Fuller |
| Henkel |
| Arkema |
| Avery Dennison |
| UPM Adhesive Materials |
| Paramelt |
| EcoSynthetix |
| Ashland |
| Danimer Scientific |
| Others |
Pricing and Supply Chain Analysis
Pine resin spot indices in Santos and Surabaya ports cascade through rosin ester formulation costs, compressing margins for European converters while amplifying pricing power among integrated Brazilian and Indonesian feedstock processors serving premium-grade adhesive tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies bio-based PSA procurement in Western European flexible packaging. Premium tiers command positioning through OK Compost INDUSTRIAL certification and REACH-compliant food-contact validation, while standard grades compete on rosin ester content parity with synthetic acrylics. Cost compression in economy tiers intensifies because Indonesian pine resin harvest volatility feeds directly into spot-priced terpene inputs. Private-label converters in Belgium exhibit highest price sensitivity, whereas Netherlands-based organic food packaging specialists prioritize certification tier over unit cost.
Supply Chain Analysis
OK Compost INDUSTRIAL certification bottlenecks at TÜV Austria and DIN CERTCO facilities gate supply chain access for new adhesive formulations, extending qualification timelines and concentrating procurement among pre-certified supplier rosters. Feedstock extraction concentrates in Brazil, Indonesia, and Portugal, where pine resin tapping and cellulose pulp processing anchor upstream supply. Formulated adhesive production rests on rosin esters, plant-derived polyols, and bio-based acrylic monomers as critical inputs. Single-source vulnerability runs through Brazilian pine resin cooperatives facing climate-induced harvest variability. Distribution runs through converter-direct relationships in Germany and the Netherlands, bypassing traditional chemical distributor networks for high-volume food packaging accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage potential exists between EU REACH-mandated food-contact validation costs and FDA parallel pathway expenses, with US-based molded fiber packaging assemblers capturing margin relief from shorter residual monomer testing timelines.
For Market Incumbents: To counter terpene feedstock volatility threatening rosin ester margin stability, H.B. Fuller and Henkel should deepen backward integration into Portuguese and Brazilian pine resin processing assets while accelerating parallel qualification tracks for substrate-specific adhesive modules to lock converter relationships ahead of procurement cycle compression. For New Entrants and Emerging Players: A 40-60% price-point gap between premium certified grades and economy rosin ester formulations opens entry space for mid-tier specialists targeting Belgian digital label converters with water-based dispersion formats compatible with short-run inkjet production. Molded fiber protective packaging for Pacific Northwest e-commerce channels represents the most penetrable white-space segment, with limited incumbent qualification creating specification vacuum. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology firms possessing novel lignin-derived tackifier platforms, where industrial composting infrastructure expansion in the Netherlands and California EPR enforcement create demand inflection. Long-term viability over the next decade hinges on certification body partnerships that compress time-to-market for compostability claims. The signal to watch is TÜV Austria testing facility capacity expansion announcements as indicator of supply chain bottleneck easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pine Resin Processing | Portuguese and Brazilian feedstock control insulates H.B. Fuller from Santos port price volatility. |
| Substrate-Specific Module Qualification | Parallel kraft paper and molded fiber tracks lock German converter relationships ahead of retailer mandates. |
| OK Compost INDUSTRIAL Certification Partnership | DIN CERTCO alliance compresses 8-12 month testing delays for natural polymer entrants. |
| Water-Based Dispersion Format Expansion | Belgian digital printing convergence favors low-VOC formulations in short-run label environments. |
| Pacific Northwest E-Commerce Packaging Penetration | Amazon sustainability mandates propagate bio-based adhesive requirements through underqualified molded fiber channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulation scientists at H.B. Fuller and Henkel, procurement directors at REWE and Carrefour, and technical directors at Netherlands-based flexible packaging converters with secondary validation against ECHA regulatory filings, EU Packaging and Packaging Waste Regulation drafts, and TÜV Austria certification databases. Bottom-up volume modeling triangulated against top-down market sizing across chemistry, application, and geography dimensions.
Historical reference periods anchored the forecast window to pre- and post-EU Green Deal implementation phases, enabling elasticity estimation for regulatory shock effects. Segmentation modeling spanned formulation chemistry, substrate type, end-use application, and regional regulatory cluster. CAGRs derived from adhesive volume intensity per square meter of fiber-based packaging, cross-referenced with retailer sustainability mandate adoption curves and industrial composting infrastructure buildout schedules.
Caveats apply where ECHA microplastics restriction finalization or REACH residual monomer threshold revisions could materially shift the outlook for silicone and synthetic rubber formulation viability. Forecasts reflect documented assumptions on terpene harvest stability and certification body capacity expansion. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation enforcement timelines or TÜV Austria testing facility throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.