
 Fiber Based Packaging Market | 2026-2036
Fiber Based Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Based Packaging Market Intelligence
The EU Green Deal is repositioning fiber based packaging from alternative to primary material across European supply chains. International Paper leverages its North American containerboard network to serve e-commerce fulfillment demand. WestRock anchors its competitive stance through integrated corrugated and consumer packaging operations spanning multiple continents. Smurfit K specializes in high-performance recycled containerboard grades that compete on strength-to-weight metrics against plastic substitutes.
Fiber based packaging encompasses engineered paper and board structures formed from wood pulp, recycled fibers, or agricultural residues, typically ranging from 150 gsm to 600 gsm depending on load-bearing requirements, designed to protect, contain, and transport goods through distribution channels. Corrugated boxes dominate volume throughput due to e-commerce fulfillment infrastructure, while pulp molding exhibits the fastest structural expansion as electronics and food service buyers seek plastic replacement for protective and tray applications. Folding cartons retain concentrated margin pools in pharmaceutical and personal care segments where print quality and barrier coatings command specification premiums.
EPA guidelines on recycled content thresholds and the EU F-Gas Regulation's indirect pressure on plastic production economics shape material sourcing decisions and capital allocation across the industry. FDA food contact substance notifications and EFSA compliance requirements determine which barrier coatings and additives gain commercial traction in food packaging applications. Stakeholders must monitor how diverging national recycling infrastructure investments affect recovered fiber availability and pricing dynamics across major manufacturing regions.
Market Dynamics
Plastic reduction mandates from major retailers are compressing substitution timelines across food and electronics supply chains, converting fiber from alternative material to specification baseline faster than capital cycles can match.
Growth Catalysts
- EU Green Deal packaging requirements:Extended producer responsibility frameworks now assign full lifecycle costs to brand owners, accelerating material transition decisions in German and French retail supply chains.
- E-commerce fulfillment infrastructure expansion:Corrugated box demand concentrates in automated distribution centers serving same-day delivery networks across China and the United States.
- Barrier coating chemistry advances:Water-based and bio-derived coatings achieve grease and moisture resistance thresholds previously requiring plastic lamination, unlocking hot-fill and frozen food applications.
Market Restraints
- Recovered fiber supply concentration:Chinese import restrictions on waste paper have redirected recovered fiber flows, creating price volatility in North American and European pulp markets.
- Capital intensity of molded pulp tooling:Thermoformed fiber tray production requires aluminum tooling investments that amortize poorly below million-unit annual volumes.
- Performance gaps in high-barrier applications:Oxygen transmission rates in uncoated fiber remain orders of magnitude above multilayer plastic films, limiting meat and cheese packaging substitution.
Strategic Opportunities
- Indian food service disposables:FSSAI single-use plastic bans in tier-one cities create immediate demand for molded fiber plates and clamshells in QSR and institutional catering.
- Pharmaceutical cold chain expansion:Insulated fiber shippers with phase-change materials capture share from expanded polystyrene in temperature-sensitive biologics distribution.
- Digital printing integration:Inkjet and electrophotographic presses enable lot-specific coding and variable graphics on corrugated, collapsing minimum order quantities for regional brands.
Industry Challenges
- Barrier coating food contact certification:FDA notification and EFSA compliance timelines for novel chemistries extend 18-24 months, delaying product launches against plastic competitors.
- Recycling stream contamination controls:Sorting infrastructure struggles to separate fiber with incompatible coatings, creating quality downgrades that depress recovered fiber pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Based Packaging Market |
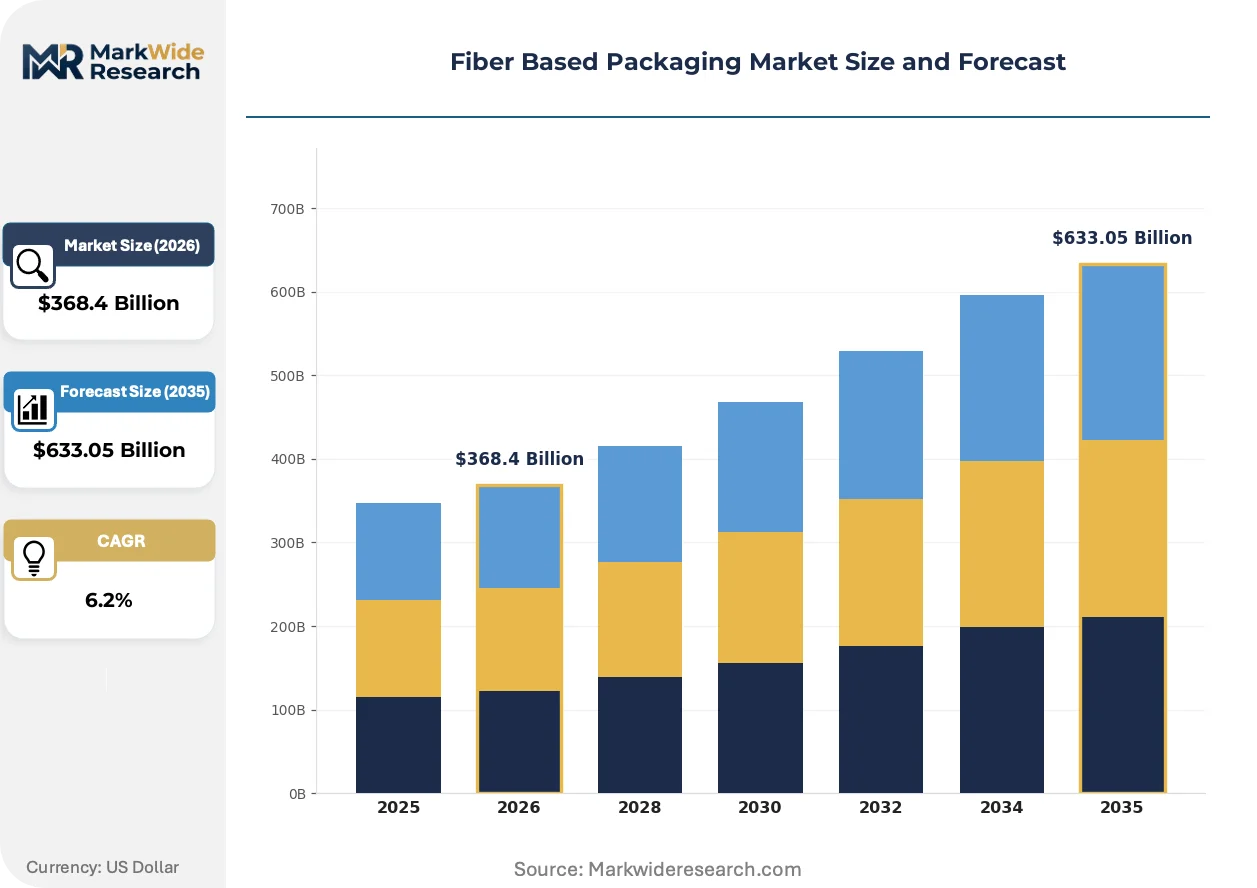
| Market Size in 2026 | $368.4 Billion |
| Market Size in 2035 | $633.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Folding Cartons, Paper Bags, Pulp Molding, Paperboard Containers, Tubes Material Grade: Kraft Paper, Virgin Pulp, Recycled Pulp, Coated Paperboard, Bleached Paperboard Application: Food Packaging, Pharmaceutical Packaging, Personal Care Packaging, Electronics Packaging, Textile Packaging End User Industry: Fast Moving Consumer Goods, Consumer Electronics, Cosmetics Manufacturers, Textile Producers, Pharmaceutical Companies |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Mondi Group, Stora Enso, Graphic Packaging, Mayr-Melnhof Karton, Rengo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Based Packaging Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pressure are converging to redefine performance specifications across protective, food contact, and display packaging applications simultaneously.
Nanocellulose reinforcement is rewriting strength-to-weight benchmarks in containerboard grades. Packaging engineers at appliance and electronics manufacturers specify 15-20% lighter basis weights without stacking performance degradation. This compression is forcing legacy integrated mills to retest furnish formulations and calender settings.
REACH restrictions on per- and polyfluoroalkyl substances eliminate oil-and-grease-resistant chemistries from European food packaging by 2026. Bakery and fast-food chains accelerate testing of silicone and clay-based alternatives. German and Dutch coating suppliers capture specification authority previously held by multinational chemical firms.
Direct-to-store replenishment models bypass regional distribution centers for ambient grocery categories. Retailers in the United Kingdom and Scandinavia compress order cycles to 48-hour windows. Corrugated suppliers respond with digital print capabilities and micro-fulfillment co-location strategies.
Fiber Based Packaging Market Segmentation
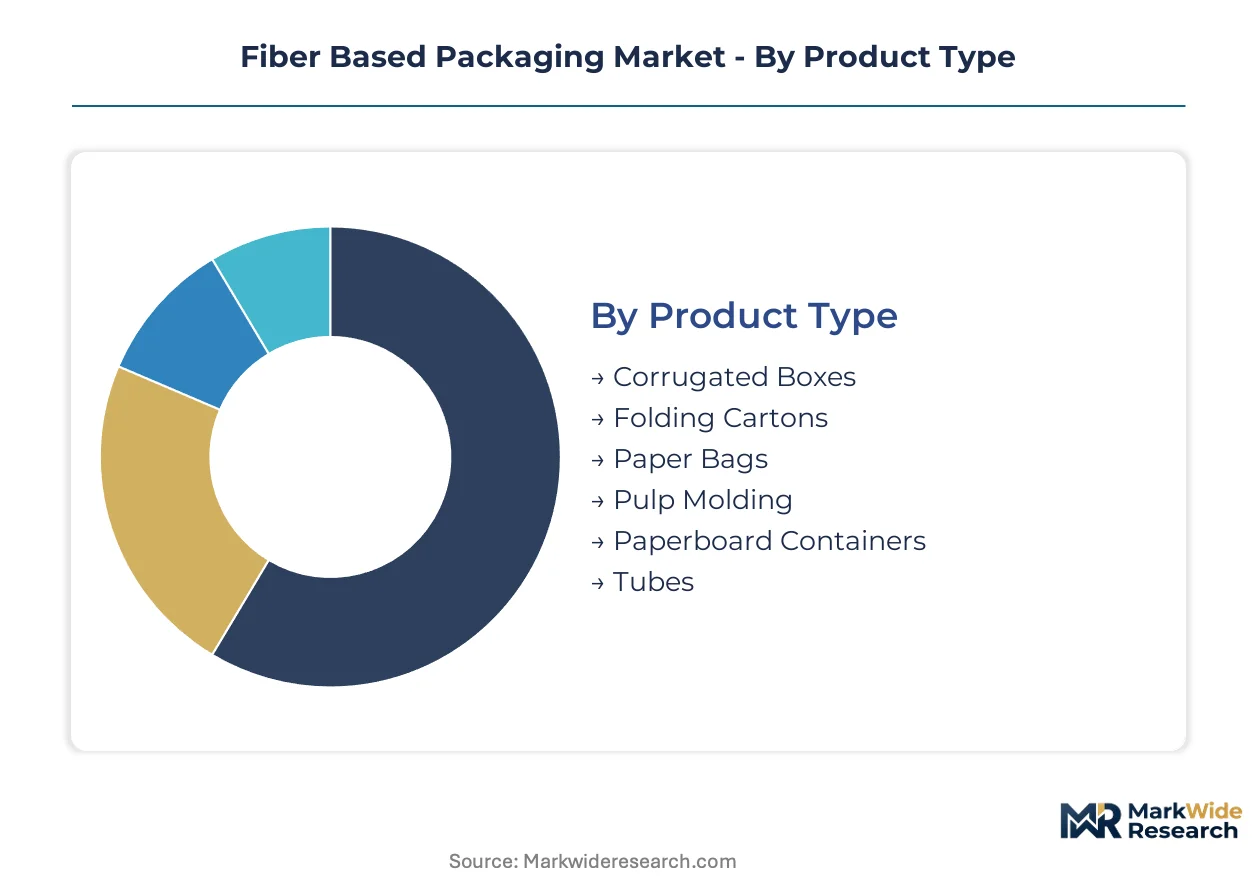
Fiber based packaging segments diverge sharply on load-bearing requirements, barrier specifications, and print complexity. Procurement teams select grades based on distribution channel stresses and regulatory compliance thresholds rather than unit cost alone.
Product Type:
Structural performance and automation compatibility separate commodity grades from specification-driven segments.
- Corrugated Boxes:Fluted medium sandwiched between linerboard faces delivers compressive strength for palletized distribution. Demand concentrates in automated e-commerce fulfillment centers across Germany and the United States where box-erecting robotics require dimensional precision.
- Pulp Molding:Wet-formed fibers from recycled newspaper and OCC create conformal protective structures through vacuum deposition. Electronics manufacturers in Shenzhen and Guadalajara specify molded pulp for smartphone and laptop shipment inserts as plastic buffer bans tighten.
- Folding Cartons:Solid bleached sulfate board with clay coatings supports high-fidelity lithographic printing for shelf presentation.
- Paper Bags:Twisted-handle and flat-handle constructions serve retail carryout and grocery applications with grammages from 80 to 150 gsm.
- Paperboard Containers:Rigid set-up boxes and composite cans protect premium cosmetics and confectionery through multi-layer laminated structures.
- Tubes:Spiral-wound or convolute constructions deliver cylindrical protection for posters, textiles, and industrial components.
Mature deployment sits with corrugated boxes. Newer deployment is concentrated in pulp molding.
Material Grade:
Cost position and sustainability credentials trade off across virgin and recycled fiber sourcing strategies.
- Recycled Pulp:Post-consumer OCC and mixed paper furnish processed through deinking and screening stages achieves lower carbon intensity than virgin alternatives. German and French packaging directives mandate minimum recycled content thresholds in shipping boxes, concentrating procurement authority with integrated mills possessing captive recovery infrastructure.
- Kraft Paper:Unbleached softwood pulp retains lignin content for tear resistance and tensile strength in sack and wrapping applications. Agricultural chemical and cement producers in India and Brazil specify multiwall kraft constructions for moisture-critical bulk shipment.
- Virgin Pulp:Northern bleached softwood kraft delivers superior brightness and cleanliness for food contact and pharmaceutical specifications.
- Coated Paperboard:Polyethylene or bio-based extrusion layers provide moisture and grease barriers for chilled food applications.
- Bleached Paperboard:Chlorine-free bleaching sequences achieve FDA and EFSA compliance thresholds for direct food contact in folding carton formats.
Volume leadership belongs to recycled pulp. Specification premiums concentrate in kraft paper.
Application:
Barrier requirements and contact safety standards segment demand by product protection intensity.
- Food Packaging:Grease-resistant and moisture-barrier coatings enable hot-fill, frozen, and fresh produce containment. Quick-service restaurant chains in the United Kingdom and Australia phase out plastic clamshells for fiber alternatives under retailer plastic reduction mandates.
- Electronics Packaging:Electrostatic discharge control and shock absorption specifications drive molded pulp and corrugated composite designs. Smartphone manufacturers in South Korea and Vietnam require fiber-based protective structures that meet drop-test protocols without polyethylene foam.
- Pharmaceutical Packaging:Serialization compliance and child-resistant closure integration govern folding carton specifications for prescription drug blister packs.
- Personal Care Packaging:Premium print quality and structural rigidity support cosmetic brand differentiation in retail environments.
- Textile Packaging:Breathable fiber constructions prevent moisture accumulation in garment shipment and storage.
Food packaging commands the largest addressable base. Electronics packaging is gaining share fastest.
End User Industry:
Order scale and specification stability separate long-contract industrial buyers from fragmented consumer-facing procurement.
- Fast Moving Consumer Goods:High-velocity replenishment cycles and SKU proliferation demand corrugated formats with digital print compatibility. Procter & Gamble and Unilever procurement teams in the United States and Netherlands specify lightweight containerboard grades that maintain stacking strength through automated warehouse handling.
- Consumer Electronics:Seasonal volume spikes and protective performance requirements concentrate molded pulp and corrugated specification authority with Apple, Samsung, and Dell supply chain engineers in Cupertino, Suwon, and Austin.
- Pharmaceutical Companies:Batch-specific serialization and temperature excursion documentation govern insulated shipper selection for biologics distribution.
- Cosmetics Manufacturers:Premium unboxing experiences and sustainability messaging drive rigid box and folding carton specifications.
- Textile Producers:Export shipment volumes and customs documentation requirements shape tube and corrugated selections for fabric rolls.
Fast moving consumer goods anchors volume procurement. Consumer electronics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European corrugated demand through its dense concentration of retail distribution centers and automated fulfillment infrastructure serving the Rhine-Ruhr manufacturing corridor.
Germany
Automotive parts suppliers in Stuttgart and Munich specify lightweight containerboard for just-in-time delivery sequences. The EU Green Deal packaging requirements mandate extended producer responsibility for brand owners. Bavarian integrated mills invest in captive recovered fiber sorting to secure OCC supply against Chinese import diversion.
United States
E-commerce fulfillment centers in Memphis and Louisville drive corrugated box specifications for same-day delivery networks. EPA recycled content guidelines shape procurement thresholds for federal supply contracts. Pacific Northwest containerboard producers leverage proximity to Asian export markets through Seattle-Tacoma port infrastructure.
China
Electronics manufacturers in Shenzhen and Dongguan specify molded pulp protective structures under domestic plastic reduction mandates. MIIT dual carbon goals accelerate material substitution in consumer goods packaging. Yangtze River Delta integrated mills expand high-performance recycled containerboard capacity for domestic e-commerce demand.
India
Quick-service restaurant chains in Mumbai and Bangalore phase out plastic clamshells for molded fiber alternatives. FSSAI single-use plastic bans in tier-one cities create immediate demand for food service disposables. Gujarat packaging converters expand thermoformed fiber tray production for institutional catering contracts.
United Kingdom
Grocery retailers in London and Manchester compress replenishment cycles to 48-hour windows for ambient categories. REACH restrictions on per- and polyfluoroalkyl substances eliminate oil-resistant chemistries from food packaging by 2026. Midlands corrugated suppliers deploy digital print capabilities for lot-specific coding in micro-fulfillment networks.
Fiber Based Packaging Market Key Industry Players
The competitive structure tilts toward integrated containerboard producers with captive fiber recovery networks. Scale advantages concentrate in North American and European players possessing multi-continent converting footprints. Three archetypes dominate: vertically integrated pulp-to-box operators, specialty coating technology licensors, and regional corrugated converters with digital print integration. Capacity expansion and barrier coating chemistry partnerships constitute the primary competitive moves as substitution timelines compress.
Among North American integrated producers, International Paper and WestRock occupy positions exemplifying scale-driven containerboard supply to automated fulfillment networks. Smurfit Kappa represents the European archetype of recycled fiber specialization with strength-to-weight optimization against plastic substitutes. These three entities anchor competitive dynamics through their respective continental infrastructure footprints and recovered fiber sourcing strategies.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| DS Smith |
| Mondi Group |
| Stora Enso |
| Graphic Packaging |
| Mayr-Melnhof Karton |
| Rengo |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-compliant barrier coatings and commodity kraft liners splits both pricing power and supply chain sourcing across German automotive suppliers and US e-commerce fulfillment networks. Premium grades command specification premiums through EFSA compliance timelines while commodity corrugated tracks OCC spot markets and Chinese import policy volatility.
Pricing Analysis
Throughput-based pricing anchors containerboard contracts to pallet-stacking performance metrics rather than basis weight alone. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cold-chain specifications from retail carryout bags. Cost compression in recycled pulp grades is intensifying because Yangtze River Delta mills expand high-performance capacity. Quick-service restaurant chains in India exhibit highest price sensitivity; pharmaceutical biologics distributors show least.
Supply Chain Analysis
Regional distribution centers in Memphis, Louisville, and Düsseldorf anchor hub-and-spoke fulfillment patterns for same-day delivery networks. Supply concentrates in Germany, China, and the United States where integrated mills control captive recovered fiber infrastructure. Raw material flows draw from OCC streams, northern bleached softwood kraft, and agricultural residue pulps. Single-source vulnerability sits with Chinese waste paper import restrictions redirecting global fiber flows. Distribution runs through automated box-erecting facilities co-located with e-commerce fulfillment campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber based packaging sector sits in a material-transition phase as water-based barrier coatings displace plastic lamination in food contact applications. This chemistry shift rewrites specification authority and procurement timelines simultaneously.
For Market Incumbents: To counter molded pulp tooling cost barriers that delay plastic substitution, International Paper and WestRock should deepen backward integration into captive OCC sorting infrastructure and accelerate FDA notification pipelines for novel grease-resistant chemistries. For New Entrants and Emerging Players: Enter via thermoformed fiber tray production for Indian QSR institutional catering where FSSAI enforcement creates immediate demand and million-unit volumes amortize aluminum tooling investments within eighteen months. For Investors and Strategic Acquirers: Re-rating potential sits with specialty coating technology licensors given REACH PFAS phase-out deadlines and EFSA compliance bottlenecks that extend commercialization timelines for multinational chemical firms. Long-term viability favors five-to-ten year positions in barrier chemistry platforms rather than commodity containerboard. Acquisition targets should possess validated food contact notifications and pilot-scale production capacity. The signal to watch is FDA notification backlog clearance rates as inflection indicator for substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Chemistry Partnership | Water-based formulations unlock hot-fill applications previously requiring plastic lamination under EU Green Deal timelines. |
| Captive Recovered Fiber Infrastructure | Bavarian integrated mills secure OCC supply against Chinese import diversion through in-house sorting investments. |
| Digital Print Capability Expansion | Inkjet integration at Midlands corrugated suppliers enables 48-hour replenishment cycles for UK grocery retailers. |
| Thermoformed Fiber Tooling Scale-Up | Gujarat converters capture institutional catering contracts as FSSAI bans drive molded pulp tray demand. |
| Pharmaceutical Cold Chain Certification | Insulated fiber shipper validation with phase-change materials displaces expanded polystyrene in biologics distribution. |
Research Approach
Trade association filings, customs export records, and regulatory submission databases formed the secondary backbone for demand quantification and material flow mapping. Primary interviews with containerboard procurement directors, coating R&D leads, corrugated plant managers, and quick-service restaurant supply chain executives validated secondary estimates and identified substitution timeline compression. Bottom-up and top-down triangulation reconciled mill capacity announcements with end-use consumption patterns across food, electronics, and pharmaceutical packaging segments.
Bottom-up modeling built demand from SKU-level consumption rates while top-down analysis anchored totals to macro trade flows. Segmentation dimensions included product type, material grade, application, and end-user industry across the analysis window. CAGRs derived from logistic curve fitting to substitution adoption patterns, with specific inputs from e-commerce fulfillment center expansion pipelines and retailer plastic reduction mandate enforcement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese waste paper import policy shifts and REACH restriction acceleration timelines. Outputs reflect documented assumptions on barrier coating certification timelines and recovered fiber availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market