
 Fiber Bale Packaging Market | 2026-2036
Fiber Bale Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Bale Packaging Market Foresight
ISO 9001 quality management certification is unwinding competitive access across the fiber bale packaging supply base, favoring producers with audited manufacturing systems. Sonoco Products Company leverages its North American mill network to sustain just-in-time delivery for cotton gins. Lenzing Plastics GmbH & Co KG anchors European demand through specialized cellulose-based bale wrap formulations. Bischof + Klein SE & Co. KG competes on multi-layer coextrusion capacity for moisture-sensitive textile fibers.
Fiber bale packaging denotes engineered flexible containers—typically woven polypropylene, cotton canvas, or kraft-laminated paper constructions rated for 50–2,000 kg payloads—designed to compress, shield, and transport loose fibrous materials during storage and transit. Woven polypropylene dominates material consumption due to its tensile strength exceeding 500 N/5cm and UV stabilization for outdoor agricultural staging. Non-woven bags represent the fastest-expanding product category, capturing margin pools in premium textile export channels where lint contamination controls command price premiums. Cotton and hemp materials retain niche positions in organic certification supply chains where synthetic polymer restrictions apply.
REACH chemical compliance in Europe and FDA indirect food contact standards in the United States govern resin formulations and migratory substance limits for bale packaging entering food-adjacent cottonseed and flax streams. India's BIS certification for woven sacks mandates dimensional stability under monsoon humidity cycles, shaping domestic procurement specifications for jute substitution programs. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional compliance investments versus standardized global product platforms.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a wholesale recalibration of material specifications across fiber bale packaging supply chains, compressing lead times for recyclability certification and privileging producers with existing polymer recovery infrastructure.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for flexible packaging by 2030, accelerating demand for post-consumer polypropylene feedstock in bale wrap production.
- Bangladesh textile mill expansion:Woven polypropylene consumption is accelerating in Dhaka and Chittagong as cotton ginning capacity scales to serve garment export quotas.
- India jute substitution programs:Ginning cooperatives in Maharashtra and Gujarat are retiring jute bale covers in favor of synthetic alternatives that withstand monsoon humidity cycles under BIS certification requirements.
Market Restraints
- Propylene feedstock volatility:Woven polypropylene margins compress when naphtha-cracker output tightens, exposing converters to Asian petrochemical pricing swings.
- Chinese supply concentration:Tape extrusion and circular loom capacity clusters in Zhejiang and Jiangsu provinces, creating single-source dependency risks for European distributors.
- Cellulose barrier limitations:Paper-laminated bale wraps fail moisture-vapor transmission rate thresholds for tropical cotton storage, restricting organic certification supply chains to synthetic alternatives.
Strategic Opportunities
- Vietnam ginning infrastructure:The Mekong Delta cotton belt remains underpenetrated by ISO 9001-certified converters, creating first-mover positioning for audited suppliers.
- Extended producer responsibility frameworks:France's AGEC law and Germany's VerpackG impose take-back obligations that favor domestic reprocessing partnerships over import-dependent models.
- RFID-embedded traceability:Convergence of woven substrate manufacturing with NFC tag integration enables lot-level provenance tracking for luxury textile spinners.
Industry Challenges
- REACH SVHC compliance timelines:Substances of very high concern screening delays batch releases by 8-12 weeks, disrupting just-in-time contracts with ginning cooperatives.
- UV stabilization formulation IP:Hindered amine light stabilizer patents held by Basel-area chemical specialists create licensing friction for mid-tier Asian converters.
- Legacy ERP integration:Agricultural procurement cooperatives in India operate on state-mandated accounting software that resists API connectivity with supplier quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Bale Packaging Market |
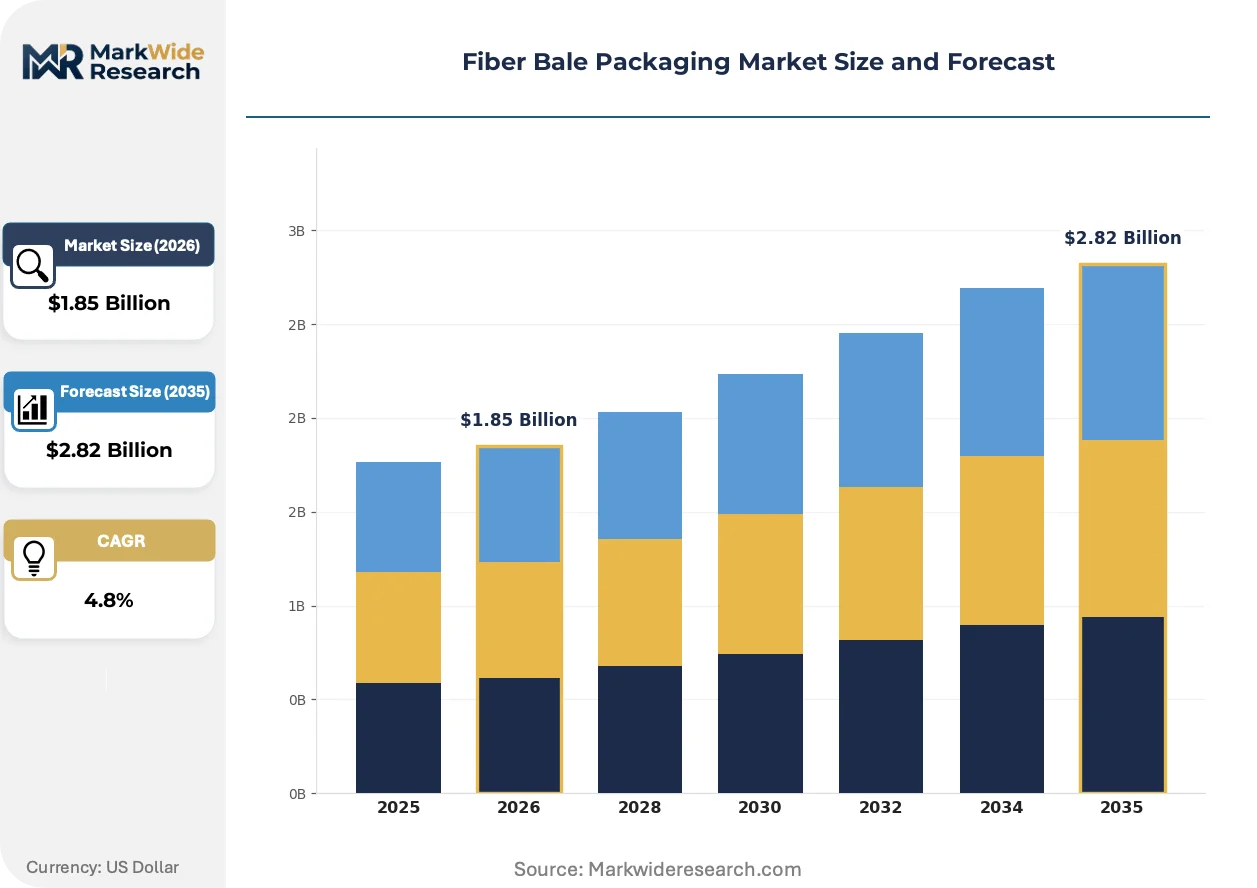
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, Non-Woven Bags, Paper Bags, Specialty Bags Material: Polypropylene, Cotton, Hemp, Recycled Fiber End User: Agriculture, Textile, Food Processing, Construction Application: Baling, Packaging, Storage, Shipping |
| Companies Covered | Sonoco Products Company, Lenzing Plastics GmbH & Co KG, ITW Signode India Limited, Bischof + Klein SE & Co. KG, Stein Fibers, Ltd., Proag Products Ltd., Balemaster, Berry Global, RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Bale Packaging Market Shifts & Advancements
Material science advances and regulatory stringency are bifurcating the fiber bale packaging landscape into commodity polypropylene volumes and certified specialty grades, with traceability technologies emerging as the decisive competitive wedge.
Biodegradable polymer formulations are fragmenting the traditional woven polypropylene dominance in premium textile channels. Italian and Portuguese spinners serving luxury apparel brands are piloting PLA-PHA blended bale wraps that decompose in industrial composting facilities. The structural consequence is fragmenting the addressable market into three distinct procurement tiers: undifferentiated agricultural volume, certified organic fiber, and closed-loop industrial textile streams.
REACH Annex XVII restrictions on microplastic shedding are compelling reformulation of non-woven bale cover surface treatments. The European Chemicals Agency's 2023 guidance on synthetic fiber fragmentation rates has triggered substitution of conventional spin-bonded polypropylene with mechanically bonded cellulose alternatives in flax and hemp transport applications. German and Dutch linen cooperatives are now specifying DIN-certified biodegradability testing as a mandatory tender precondition.
Direct mill procurement is displacing distributor intermediaries in North American cotton logistics. Texas and Mississippi gins are negotiating frame contracts with packaging converters that bypass traditional agricultural supply houses, compressing margin pools and transferring inventory carrying costs upstream. This disintermediation is most visible in the Mid-South region, where cooperative ginning associations have consolidated purchasing power across 40-plus facilities.
Fiber Bale Packaging Market Segmentation
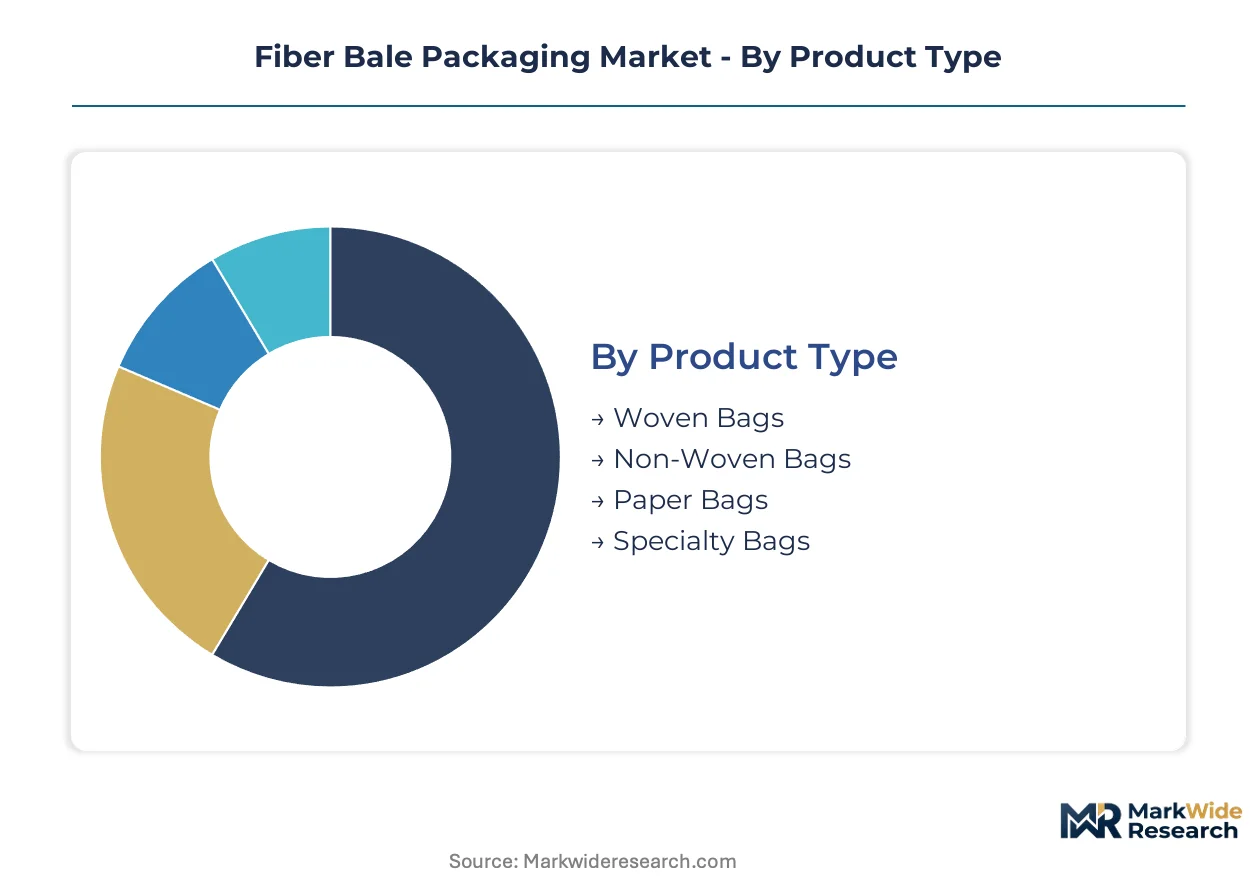
Fiber bale packaging demand fragments across material specifications, end-use durability requirements, and geographic regulatory thresholds. Procurement patterns diverge sharply between agricultural commodity flows and premium textile export channels.
Product Type:
Domestic procurement concentrates on woven and non-woven constructions for agricultural staging, while specialty and paper grades serve export-led textile certification chains.
- Woven Bags:Circular loom constructions of polypropylene tape yarn deliver tensile strength exceeding 500 N/5cm with UV stabilization for outdoor cotton storage. Bangladeshi textile mills in Dhaka and Chittagong are scaling woven polypropylene consumption as ginning capacity expands to serve garment export quotas.
- Non-Woven Bags:Spin-bonded or melt-blown polypropylene layers create lint-contamination barriers for premium cotton lint protection. Italian and Portuguese spinners serving luxury apparel brands are piloting these constructions for closed-loop industrial textile streams where price premiums apply.
- Paper Bags:Kraft-laminated constructions rated for 50–200 kg payloads serve organic certification supply chains with synthetic polymer restrictions.
- Specialty Bags:Multi-layer coextrusion formats with moisture-vapor barriers address tropical humidity cycles in Indian and Southeast Asian cotton belts.
Woven bags hold the largest share; momentum sits with non-woven bags.
Material:
Cost tiers separate commodity petrochemical feedstocks from certified organic alternatives, with recycled fiber emerging as a compliance-driven middle tier.
- Polypropylene:Homopolymer and copolymer resins dominate volume through tape extrusion and flat yarn production. REACH Annex XVII restrictions on microplastic shedding are compelling reformulation of surface treatments in European flax and hemp transport applications.
- Cotton:Natural fiber canvas retains position in organic certification supply chains where synthetic restrictions apply. German and Dutch linen cooperatives now specify DIN-certified biodegradability testing as mandatory tender preconditions.
- Hemp:Bast fiber constructions serve niche organic textile channels with compostable end-of-life requirements.
- Recycled Fiber:Post-consumer polypropylene feedstock is accelerating under EU Packaging and Packaging Waste Regulation minimum recycled content thresholds for flexible packaging.
Polypropylene commands volume leadership; recycled fiber is climbing the fastest.
End User:
Application maturity varies from standardized agricultural procurement to specification-intensive textile and food-adjacent channels.
- Agriculture:Cotton ginning cooperatives in Maharashtra and Gujarat are retiring jute bale covers for synthetic alternatives under BIS certification requirements for monsoon humidity resistance.
- Textile:Mill-direct procurement is displacing distributor intermediaries in Texas and Mississippi, where cooperative ginning associations have consolidated purchasing power across 40-plus facilities.
- Food Processing:FDA indirect food contact standards govern resin formulations for bale packaging entering cottonseed and flax streams.
- Construction:Insulation fiber and geotextile applications require heavier-duty 1,000–2,000 kg payload ratings with reinforced lifting loops.
Agriculture holds the largest share; textile channels show the steepest expansion trajectory.
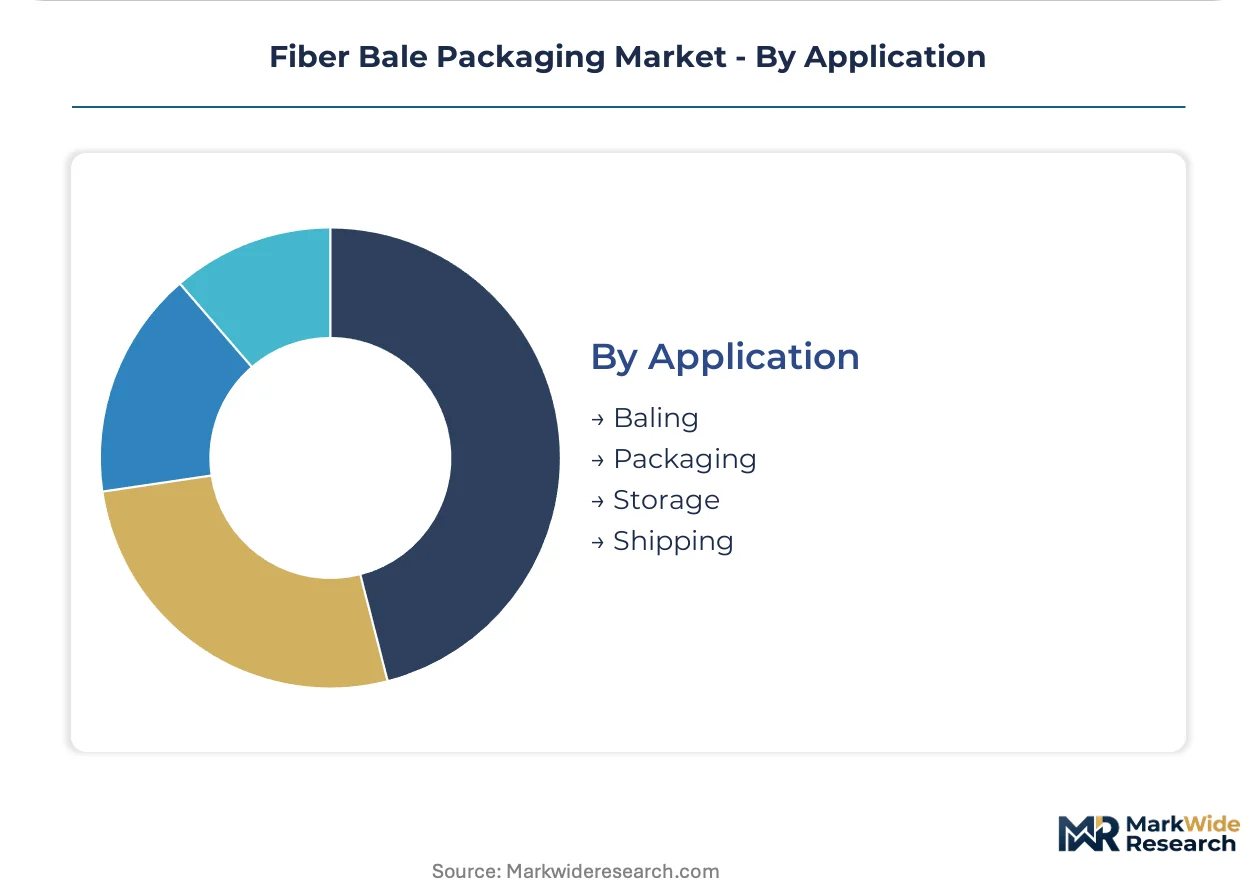
Application:
Customer workflows separate field-level baling and storage from downstream packaging and shipping specifications with traceability requirements.
- Baling:In-field compression and wrapping at ginning sites demands UV-stabilized constructions for 3–6 month outdoor staging cycles.
- Packaging:Mill-ready presentation formats with printed lot codes and RFID-embedded traceability enable provenance tracking for luxury textile spinners.
- Storage:Warehouse racking compatibility and stack stability specifications vary by fiber density and moisture content.
- Shipping:Containerized ocean freight requires ISPM-15 compliant wood pallet alternatives or slip-sheet formats for export documentation.
Baling holds the largest share; packaging applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates are recalibrating procurement specifications across major cotton-producing and textile-processing economies, compressing lead times for recyclability certification while privileging producers with polymer recovery infrastructure.
United States
Texas and Mississippi cotton cooperatives are consolidating purchasing power across 40-plus ginning facilities, displacing traditional agricultural supply houses through direct mill procurement. FDA indirect food contact standards govern resin formulations for cottonseed and flax streams entering food-adjacent channels. The Mid-South region anchors North American demand as cooperative associations negotiate frame contracts with packaging converters.
Germany
VerpackG extended producer responsibility obligations impose take-back obligations that favor domestic reprocessing partnerships over import-dependent supply models. DIN-certified biodegradability testing has become mandatory for linen cooperatives sourcing flax and hemp transport packaging. The North Rhine-Westphalia industrial corridor hosts specialized converters serving Dutch and Belgian textile spinners with REACH-compliant formulations.
India
Ginning cooperatives in Maharashtra and Gujarat are retiring jute bale covers for synthetic alternatives that withstand monsoon humidity cycles under BIS certification requirements. The country's national textile regulator mandates dimensional stability testing for woven sacks exposed to seasonal moisture extremes. Ahmedabad and Surat industrial clusters concentrate tape extrusion capacity serving domestic cotton belt upgrading programs.
Bangladesh
Dhaka and Chittagong textile mills are scaling woven polypropylene consumption as ginning capacity expands to serve garment export quotas. The central bank's export facilitation schemes channel working capital toward packaging procurement for vertically integrated spinning operations. The Chittagong port corridor concentrates import-dependent resin supply chains serving delta-region cotton processing infrastructure.
Vietnam
The Mekong Delta cotton belt remains underpenetrated by ISO 9001-certified converters, creating positioning opportunities for audited suppliers with quality management systems. The Ministry of Industry and Trade's technical regulations for packaging materials are converging with EU import standards for textile export channels. Ho Chi Minh City logistics hubs are emerging as consolidation points for regional ginning infrastructure investment.
Fiber Bale Packaging Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage, producing a bifurcated structure where scale-driven multinationals and regional fabricators split volume and margin pools. Publicly traded packaging conglomerates leverage North American and European mill networks for just-in-time delivery contracts, while private specialists anchor regional procurement through BIS or DIN certification advantages. Two strategic archetypes dominate: integrated resin-to-film converters controlling polymer feedstock access, and loom-focused specialists competing on circular weaving capacity and UV stabilization formulation expertise. Competitive moves concentrate on backward integration into tape extrusion and regional capacity expansion to bypass Chinese supply concentration risks.
Within the integrated converter tier, Sonoco Products Company and Berry Global exemplify scale-driven positions with mill network coverage spanning multiple continents. Lenzing Plastics GmbH & Co KG anchors European demand through cellulose-based specialization, occupying a position that bridges petrochemical and bio-based material streams. Bischof + Klein SE & Co. KG represents the multi-layer coextrusion specialist archetype, with SE & Co. KG structure indicating German partnership-based governance suited to family-controlled industrial packaging segments. RKW Group and ITW Signode India Limited sit within regional leadership positions—RKW with German origins and Signode with India-based operations reflecting subcontinent manufacturing scale.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Lenzing Plastics GmbH & Co KG |
| ITW Signode India Limited |
| Bischof + Klein SE & Co. KG |
| Stein Fibers, Ltd. |
| Proag Products Ltd. |
| Balemaster |
| Berry Global |
| RKW Group |
| Others |
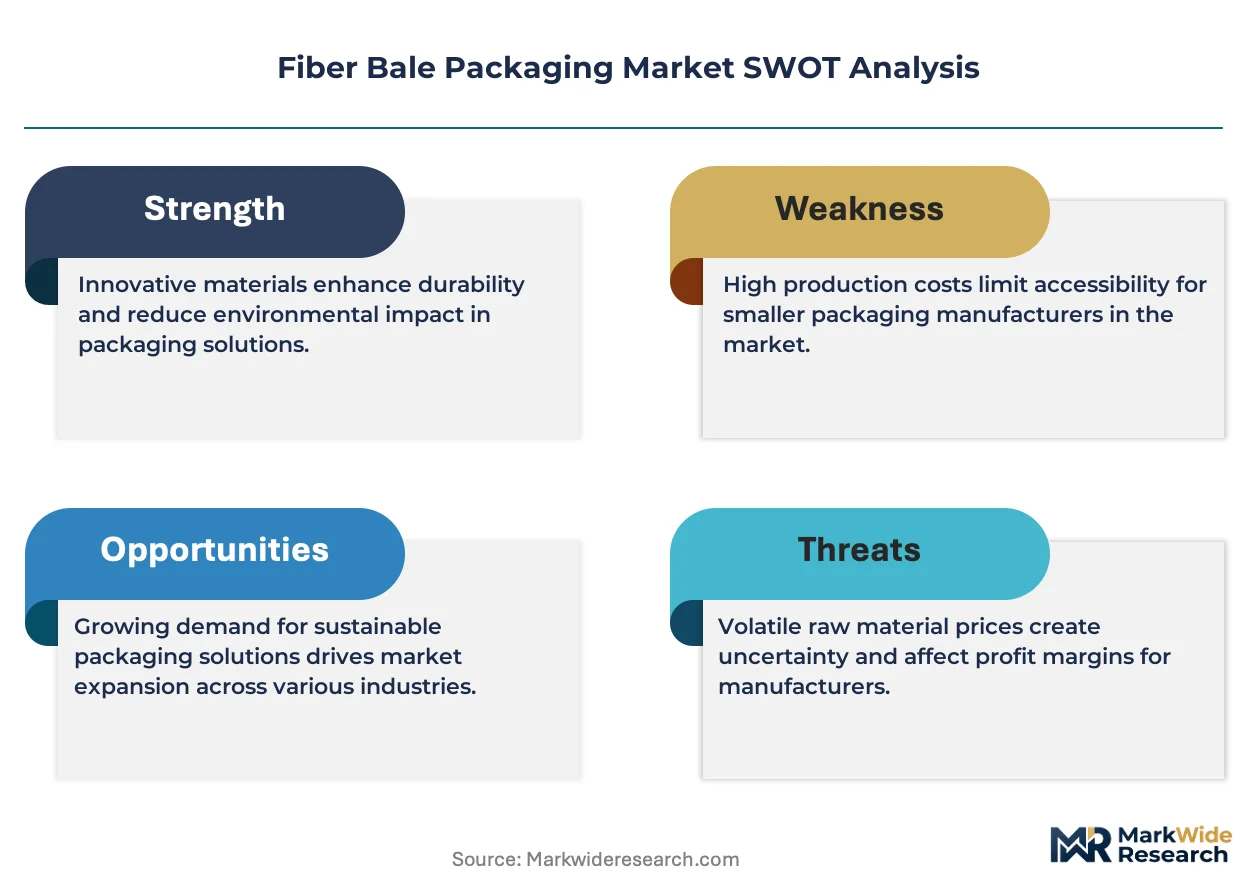
Supply & Pricing Matrix
Frame contracts with take-or-pay clauses lock in polypropylene resin access for Bangladeshi and Vietnamese ginning cooperatives, binding price visibility to monsoon-season delivery windows under BIS and EU Packaging and Packaging Waste Regulation compliance timelines.
Pricing Analysis
Certification level (ISO 9001/REACH/BIS-grade) creates the primary spread between commodity woven polypropylene and premium non-woven lint-barrier constructions. Three-tier pricing structure across certified specialty, standard industrial, and ungraded agricultural tiers reflects UV stabilization formulation costs and audit maintenance overhead. Pricing pressure stems from naphtha-cracker output volatility in Zhejiang and Jiangsu provinces, compressing converter margins when Asian petrochemical feedstock tightens. Agricultural cooperatives in Maharashtra and Gujarat exhibit the highest price sensitivity, while Italian and Portuguese luxury textile spinners accept premiums for DIN-certified biodegradability and RFID-embedded traceability.
Supply Chain Analysis
Inventory cycles compress to 6–8 weeks for EU-compliant bale wraps as REACH SVHC screening delays batch releases, forcing ginning cooperatives to stage buffer stock ahead of harvest windows. Tape extrusion and circular loom capacity concentrates in China, India, and Germany, with Zhejiang province hosting the dominant share of woven polypropylene substrate production. Raw material flows draw from Saudi and Qatari propylene feedstock, South Korean UV stabilizer additives, and Basel-area hindered amine light stabilizer patents. Single-source dependency on Chinese tape extrusion creates vulnerability to export licensing friction. Distribution runs through agricultural supply houses in the Mid-South region and direct mill procurement channels in Texas and Mississippi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where REACH and BIS certification timelines create switching costs that lock ginning cooperatives into audited supplier relationships.
For Market Incumbents: Compound certification advantages by deepening backward integration into tape extrusion capacity in Gujarat and North Rhine-Westphalia, insulating margin pools from Zhejiang supply concentration. Extend ISO 9001 audit coverage to Vietnam's Mekong Delta before first-mover positioning solidifies. Counter PLA-PHA biodegradable substitution threats by piloting cellulose-based barrier formulations with German and Dutch linen cooperatives.
For New Entrants and Emerging Players: Lead with RFID-embedded traceability bundles targeting Italian luxury textile spinners, where lot-level provenance tracking commands price premiums in closed-loop industrial streams. Exploit underpenetrated Vietnam ginning infrastructure by anchoring Ho Chi Minh City logistics hubs with EU-convergent technical regulations. Position through biodegradable polymer formulations certified under DIN industrial composting standards.
For Investors and Strategic Acquirers: Capital is best deployed toward loom-focused specialists with circular weaving capacity and captive UV stabilization formulation expertise, positioned for medium-term viability as extended producer responsibility frameworks reshape competitive access. Watch France's AGEC law and Germany's VerpackG enforcement intensity as the inflection signal for domestic reprocessing partnership valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tape Extrusion | Captures margin pools threatened by Zhejiang supply concentration and naphtha volatility. |
| REACH-Compliant Formulation Investment | Locks in European textile spinner contracts ahead of Annex XVII microplastic restrictions. |
| RFID-NFC Tag Integration | Enables lot-level provenance tracking for Italian and Portuguese luxury apparel channels. |
| Vietnam Capacity Expansion | Secures first-mover positioning in Mekong Delta ginning infrastructure before ISO 9001 saturation. |
| Domestic Reprocessing Partnership | Satisfies France's AGEC law and Germany's VerpackG take-back obligations with localized recovery. |
Research Methodology
A standing panel of cotton ginning cooperative procurement managers, woven polypropylene plant engineers, REACH regulatory compliance officers, and Italian textile spinner technical directors provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation guidance, BIS woven sack dimensional stability standards, FDA indirect food contact resin filings, and customs trade data tracking polypropylene tape yarn flows. Bottom-up demand modeling from ginning capacity expansions in Bangladesh, Vietnam, and India triangulated against top-down petrochemical feedstock allocation analysis.
Consistency checks validated volume and value outputs against EIA naphtha-cracker utilization trends, ACC flexible packaging demand indices, and SEC 10-K disclosures from North American packaging conglomerates. Segmentation modeling spanned material grade tiers, end-use durability requirements, certification compliance levels, and regional regulatory clusters. CAGRs derived from iterative convergence between historical shipment data and forward-looking capacity investment announcements, with monsoon humidity cycle severity and EU Green Deal recycled content thresholds as fiber bale packaging-specific forecast inputs.
Underlying assumptions cover sustained polypropylene resin availability, REACH SVHC screening timeline stability, and cooperative ginning association purchasing consolidation, with deviation risk concentrated in Chinese export licensing friction and biodegradable polymer substitution acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market