
 North America Molded Pulp Packaging Market | 2026-2036
North America Molded Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molded Pulp Packaging Market Intelligence
The US EPA's emerging extended producer responsibility framework is realigning the cost-of-entry calculus for single-use packaging converters. Huhtamaki Oyj leverages its integrated fiber sourcing network to sustain margin stability across volatile pulp cycles. Sonoco Products Company anchors its position through dedicated molded fiber R&D facilities in the US Southeast. Genpak, LLC differentiates via specialized foodservice tray geometries that navigate tight dimensional tolerances for automated filling lines.
North America molded pulp packaging comprises formed fiber articles manufactured through vacuum-assisted water-fiber slurry molding, typically achieving wall thicknesses of 1.5–4.0 mm and densities of 0.6–1.2 g/cm³ for protective cushioning and containment applications. The material dimension tilts toward recycled pulp grades as post-consumer fiber collection infrastructure matures, though kraft paper retains premium positioning in electronics cushioning where surface smoothness commands price premiums. Trays dominate foodservice applications with established tooling amortization, while clamshells capture faster expansion as quick-service chains eliminate polystyrene.
The US EPA, state-level extended producer responsibility boards, and FDA food-contact substance regulations collectively shape product standards and market access thresholds for molded pulp food packaging. California's SB 54 implementation timeline and Canada's pending single-use plastics prohibition are forcing cross-border supply chain recertification investments. Stakeholders must monitor evolving state-by-state labeling mandates and fiber sourcing disclosure requirements that will determine which production assets retain competitive validity.
Market Dynamics
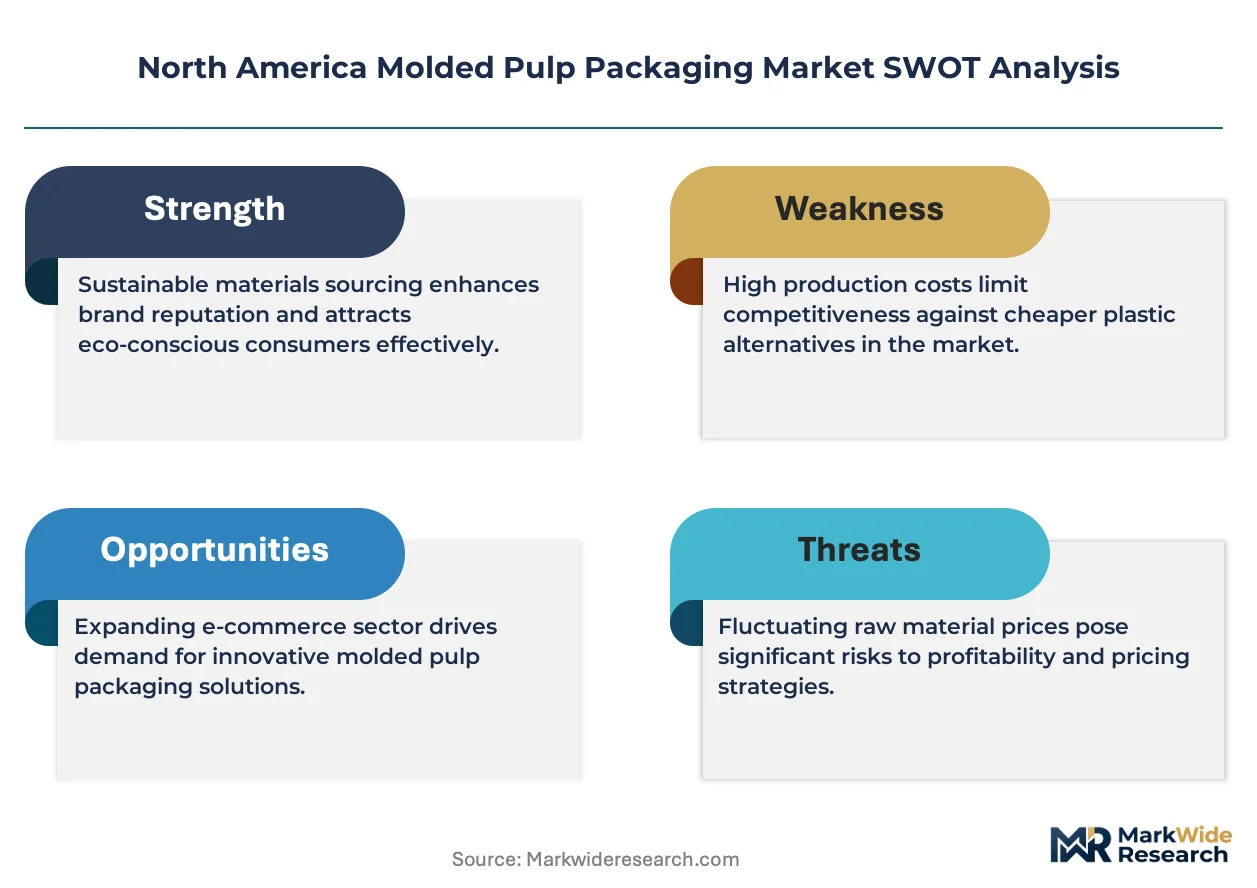
The US EPA's extended producer responsibility framework is compressing the economics of single-use plastics, forcing foodservice operators to absorb fiber-based packaging premiums while suppliers race to scale thermoformed pulp capacity ahead of state-level enforcement timelines.
Growth Catalysts
- California SB 54 mandates:The state's plastic packaging reduction targets are compelling quick-service restaurant chains to convert clamshell and tray specifications to molded fiber, creating immediate offtake visibility for Georgia and North Carolina production facilities.
- Post-consumer fiber collection maturation:MRF upgrades across the US Southeast are delivering cleaner OCC streams, enabling higher recycled content ratios in food-contact molded pulp without sacrificing structural integrity.
- Quick-service automation compatibility:Fiber tray geometries achieving dimensional tolerances within 0.5 mm are securing placement on high-speed filling lines previously locked to polystyrene dimensions.
Market Restraints
- Recycled pulp price volatility:OCC bale costs fluctuate with Chinese import policy shifts, compressing converter margins when fiber feedstocks spike without corresponding pass-through mechanisms in foodservice contracts.
- Tooling amortization burdens:Thermoformed pulp molds requiring 6-8 week lead times and $150,000+ capital deployment per SKU deter mid-volume foodservice operators from portfolio-wide conversion.
- Moisture barrier limitations:Current PLA and bio-wax coatings fail to match polyethylene's grease resistance beyond 30 minutes, restricting molded pulp penetration in hot-held protein applications.
Strategic Opportunities
- Canadian single-use plastics prohibition:Federal regulations banning polystyrene food containers are opening cross-border supply chain integration for US Southeast producers with SQF-certified facilities.
- Electronics cushioning premiumization:Kraft fiber smoothness grades achieving surface roughness below 50 microns are capturing price premiums in smartphone and laptop protective packaging.
- Direct-store-delivery channel expansion:Regional bakery and produce distributors are bypassing centralized distribution to specify custom molded pulp trays with localized graphics and reduced case counts.
Industry Challenges
- FDA food-contact notification timelines:Novel barrier coatings face 180-day review cycles that stall product launches ahead of seasonal menu transitions at major restaurant chains.
- Thermoforming technician scarcity:Vacuum-forming process optimization expertise concentrates with legacy packaging engineers approaching retirement, constraining capacity ramp rates at greenfield facilities.
- Legacy warehouse automation incompatibility:Existing case erectors and palletizers calibrated to polystyrene coefficient of friction require mechanical retrofitting to handle fiber packaging stack heights without line stoppage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molded Pulp Packaging Market |
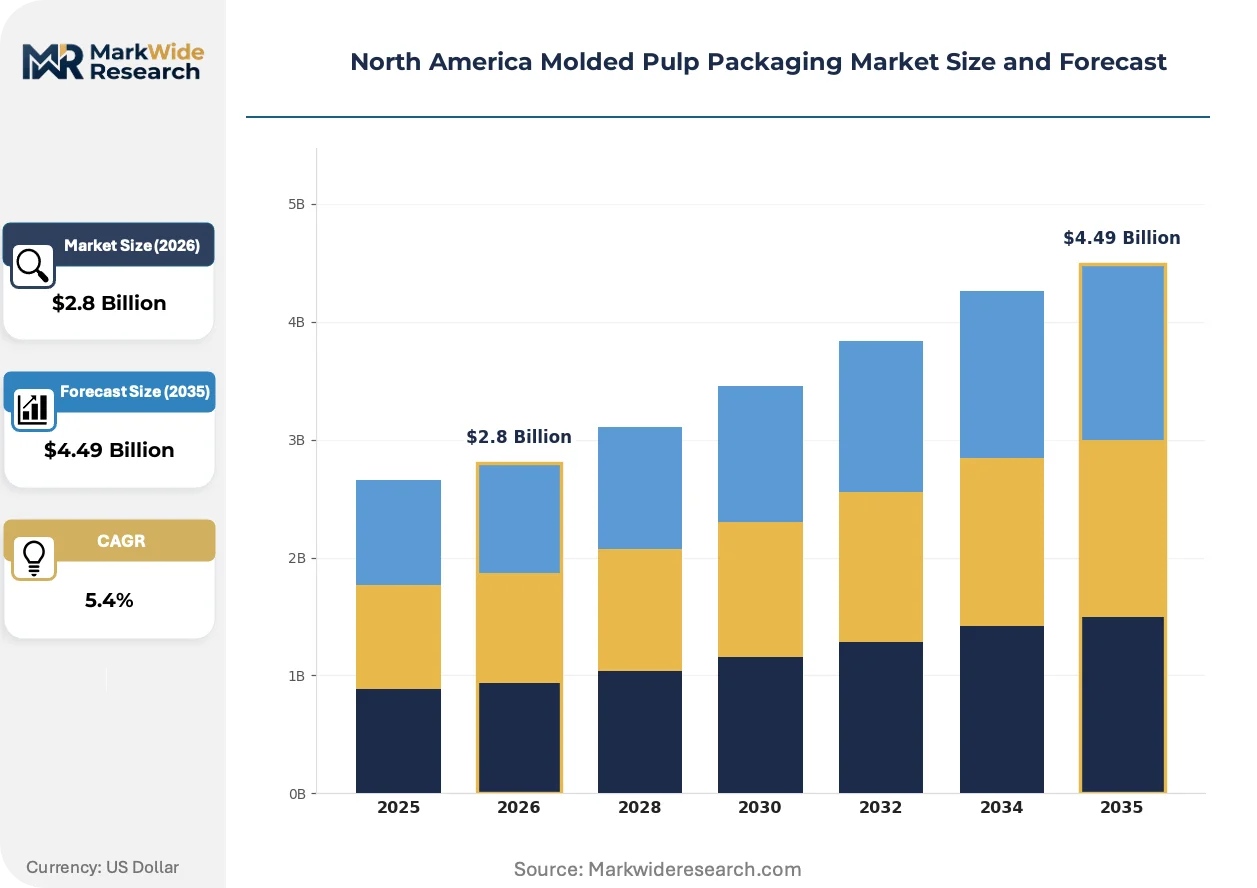
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Boxes, Containers End User: Food Industry, Electronics, Cosmetics, Pharmaceuticals Material: Kraft Paper, Recycled Pulp, Sustainable Fiber, Biodegradable Materials Form: Rigid Packaging, Flexible Packaging, Custom Designs, Standard Shapes |
| Companies Covered | Huhtamaki Oyj, Sonoco Products Company, WestRock Company, Genpak, LLC, Sabert Corporation, UFP Technologies, Pactiv Evergreen Inc., Henry Molded Products, Inc., EnviroPAK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molded Pulp Packaging Market Strategic Shifts & Innovations
Active R&D pipelines across the US Southeast are converging on barrier technology breakthroughs and precision molding advances that resolve fiber packaging's historical performance gaps against plastic incumbent.
Advanced thermoforming with in-mold labeling is electrifying the competitive calculus for branded foodservice applications. Quick-service chains in Texas and Florida are specifying full-color fiber trays with embedded logos at volumes exceeding 50 million units annually. The technology is electrifying margin expansion opportunities for converters who integrate printing and forming operations, compressing the traditional plastics-to-fiber cost gap by eliminating secondary labeling steps.
The US EPA's draft national recycling strategy is mandating post-consumer content minimums for federal foodservice contracts. This regulatory pressure is accelerating investment in de-inking and fiber recovery systems at Georgia and Alabama mills. Food-contact molded pulp destined for military and institutional channels faces the most stringent compliance timelines, with producers front-loading certification investments to secure multi-year supply agreements.
Buyer consolidation among the top ten quick-service restaurant holding companies is compressing supplier qualification cycles and favoring molders with multi-site manufacturing footprints. Regional operators in the Carolinas and Tennessee are responding by forming cooperative purchasing alliances to achieve volume thresholds for custom tooling access. This concentration dynamic is most visible in poultry and breakfast sandwich categories, where fiber tray standardization across franchise systems is displacing fragmented polystyrene specifications within 18-month procurement windows.
North America Molded Pulp Packaging Market Segmentation
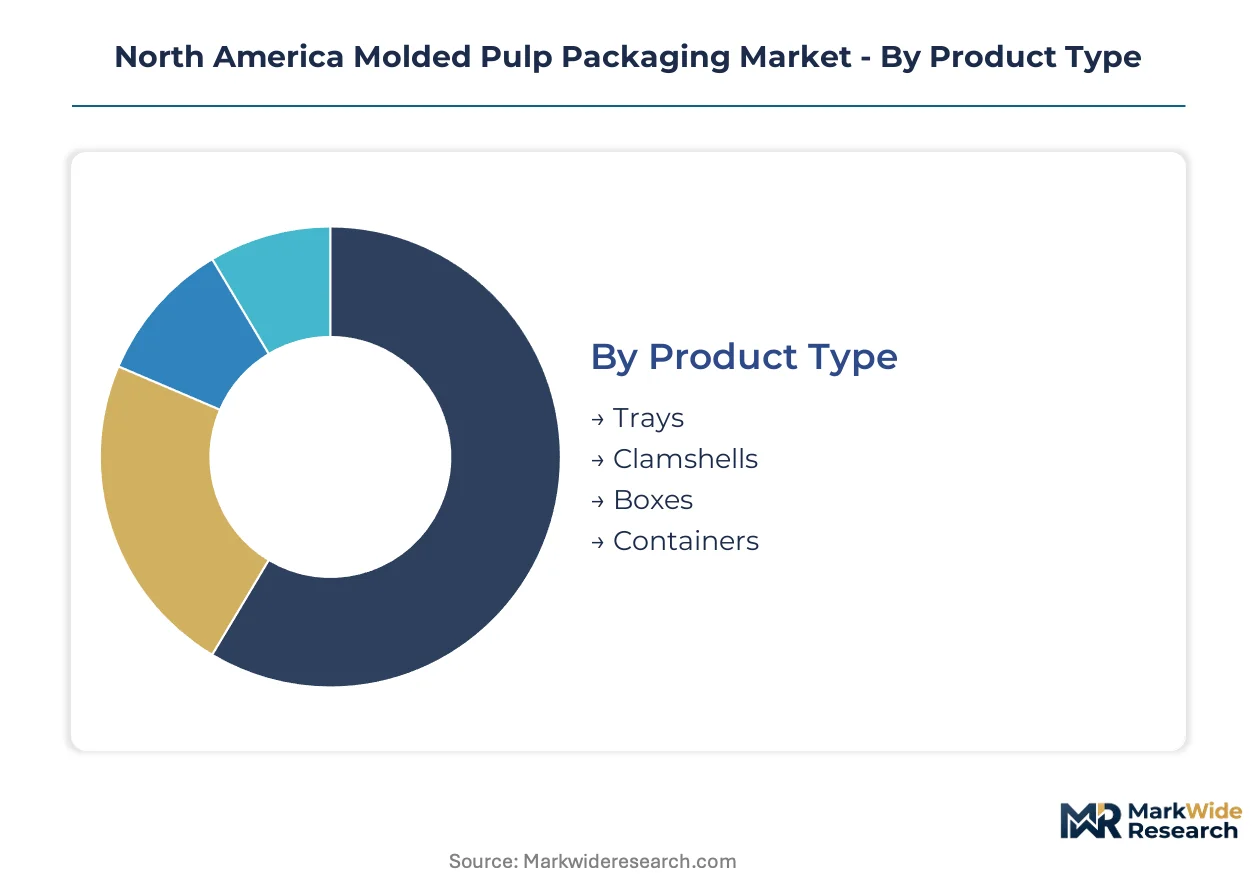
Molded pulp packaging segments diverge sharply in certification intensity. Food-contact applications demand FDA food-contact substance notifications and SQF facility certifications, while electronics cushioning navigates surface roughness specifications without regulatory filing burdens. Understanding these compliance boundaries determines which production assets can pivot across customer segments.
Product Type:
FDA food-contact notifications and state-level extended producer responsibility compliance requirements vary dramatically across tray, clamshell, and container geometries, with thermoformed fiber molds requiring distinct tooling validation protocols for each shape category.
- Trays:Vacuum-formed fiber articles with 1.5–4.0 mm wall thickness dominate quick-service restaurant automation lines. Georgia and North Carolina facilities supply standardized geometries to poultry and breakfast sandwich chains converting from polystyrene. Tooling amortization across 50-million-unit annual offtake agreements compresses per-unit premiums versus clamshell alternatives.
- Clamshells:Hinged fiber structures with integrated locking tabs are displacing plastic incumbents in California quick-service chains under SB 54 mandates. Dimensional tolerances within 0.5 mm secure placement on high-speed filling lines, though moisture barrier coatings face 180-day FDA review cycles that stall seasonal menu launches.
- Boxes:Deep-drawn fiber containers for produce and bakery distribution achieve stack heights compatible with existing warehouse automation in Texas and Florida direct-store-delivery networks.
- Containers:Custom-molded fiber vessels with in-mold labeling accommodate branded graphics for regional bakery specifications bypassing centralized distribution.
Leading the category by volume: Trays. Expanding most quickly: Clamshells.
End User:
Customer procurement patterns stratify by contract structure, with food industry buyers consolidating supplier qualification cycles across multi-site footprints while electronics and pharmaceutical segments negotiate specification-grade premiums.
- Food Industry:Quick-service restaurant holding companies demand SQF-certified facilities with multi-state manufacturing footprints. US Southeast producers leverage Georgia and Alabama mill integration to meet federal foodservice contract post-consumer content minimums.
- Electronics:Kraft fiber smoothness grades below 50 microns surface roughness capture price premiums in smartphone and laptop protective packaging. California and Texas distribution channels specify precision-molded cushioning for high-value device shipments.
- Cosmetics:Molded pulp inserts and secondary packaging for premium beauty brands emphasize tactile surface quality and custom coloration through in-mold labeling integration.
- Pharmaceuticals:Cold-chain fiber packaging with bio-wax moisture barriers serves temperature-sensitive drug distribution, though coating validation extends FDA notification timelines.
Dominating procurement volume: Food Industry. Steepest expansion trajectory: Electronics.
Material:
Feedstock selection determines margin volatility exposure, with recycled pulp grades tethered to OCC bale price swings while kraft paper commands stability through integrated sourcing networks.
- Kraft Paper:Virgin fiber grades deliver surface smoothness critical for electronics cushioning applications. Georgia mills with captive pulp supply sustain margin stability across volatile cycles.
- Recycled Pulp:Post-consumer fiber streams from upgraded MRFs across the US Southeast enable higher content ratios without structural compromise. OCC cost spikes compress converter margins absent pass-through mechanisms.
- Sustainable Fiber:Agricultural residue and bamboo fiber blends target brand sustainability commitments in cosmetics and premium food packaging segments.
- Biodegradable Materials:PLA and bio-wax barrier coatings address moisture resistance limitations, though 30-minute grease resistance thresholds restrict hot-held protein applications.
Highest volume throughput: Recycled Pulp. Gaining share fastest: Sustainable Fiber.
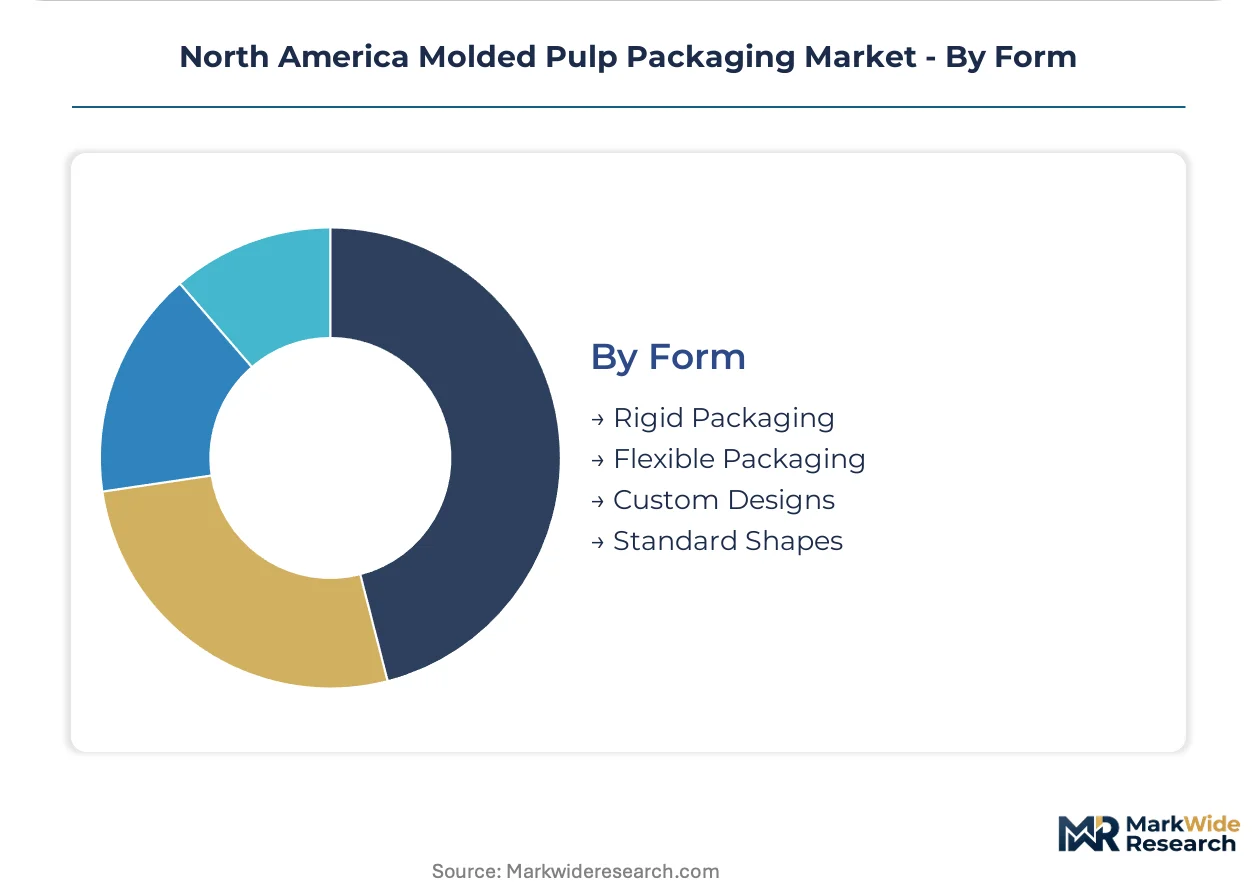
Form:
Structural rigidity requirements segment tooling capital deployment, with custom designs demanding 6-8 week lead times and $150,000-plus per-SKU investment that excludes mid-volume operators.
- Rigid Packaging:Thermoformed fiber with 0.6–1.2 g/cm³ density provides protective cushioning for electronics and automated foodservice filling lines. Standardized geometries achieve tooling amortization efficiency.
- Flexible Packaging:Pressed fiber wraps and sleeves serve produce bundling and secondary containment applications with lower capital barriers to entry.
- Custom Designs:Proprietary molds for regional bakery and produce distributors incorporate localized graphics and reduced case counts. Cooperative purchasing alliances among Tennessee and Carolina operators achieve volume thresholds for tooling access.
- Standard Shapes:Catalog geometries for quick-service chains accelerate procurement cycles, with buyer consolidation favoring molders with multi-site footprints.
Commanding production volume: Rigid Packaging. Climbing the fastest: Custom Designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern US opportunity zones and Canadian federal plastics prohibitions are concentrating investment flows across North American molded pulp capacity. Georgia and North Carolina mill clusters anchor fiber supply integration for food-contact applications. Cross-border regulatory misalignment between US state-level EPR frameworks and Canadian federal mandates is forcing dual-certification strategies.
United States
Georgia and North Carolina manufacturing clusters leverage proximity to recycled paper mills and quick-service restaurant distribution networks. The EPA's emerging extended producer responsibility framework is accelerating capital deployment in thermoformed fiber capacity ahead of state enforcement timelines. Atlanta and Charlotte metro areas host expanding production facilities serving poultry and breakfast sandwich chains converting from polystyrene.
Canada
Federal regulations banning polystyrene food containers are opening cross-border supply chain integration for US Southeast producers. Health Canada's food-contact substance notification requirements run parallel to FDA timelines, creating dual-review complexity for barrier coating approvals. Ontario and Quebec distribution channels are specifying SQF-certified fiber packaging for institutional foodservice contracts.
Mexico
Nearshoring trends in electronics assembly are generating demand for kraft fiber cushioning in smartphone and laptop protective packaging. Mexico's federal environmental standards for packaging waste lack the enforcement rigor of US state-level EPR frameworks, creating regulatory arbitrage opportunities. Baja California and Chihuahua industrial corridors are emerging as secondary sourcing options for US border-state distributors.
North America Molded Pulp Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated paperboard producers with captive pulp supply and independent molders reliant on spot OCC markets. Three archetypes dominate: multinational packaging conglomerates with multi-site footprints, regional specialists in foodservice automation compatibility, and captive molders serving single-category electronics demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with tooling co-investment agreements accelerating quick-service chain conversions.
Among Finland-based and US Southeast-anchored producers, Huhtamaki Oyj, Sonoco Products Company, and Genpak, LLC occupy positions across the specialization spectrum. Huhtamaki Oyj exemplifies integrated fiber sourcing networks that sustain margin stability across volatile pulp cycles. Sonoco Products Company represents the R&D facility concentration archetype with dedicated molded fiber operations in the US Southeast. Genpak, LLC anchors the foodservice automation specialist tier, with positioning tied to dimensional tolerance capabilities for high-speed filling lines.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Sonoco Products Company |
| WestRock Company |
| Genpak, LLC |
| Sabert Corporation |
| UFP Technologies |
| Pactiv Evergreen Inc. |
| Henry Molded Products, Inc. |
| EnviroPAK Corporation |
| Others |
Cost & Logistics Intelligence
Captive integration into Georgia and Alabama recycled paper mills anchors converter margin stability across OCC price cycles while compressing procurement premiums for quick-service restaurant chains. This upstream control over fiber feedstock sources simultaneously secures post-consumer content compliance for federal contracts and defends pricing power against spot-market-dependent competitors.
Pricing Analysis
Premium pricing for 6-8 week custom tooling lead times separates dedicated thermoformed fiber capacity from spot-market catalog geometries. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with FDA food-contact notification tiers commanding spreads over industrial cushioning grades. Cost compression in mid-volume contract tiers is intensifying because buyer consolidation among quick-service holding companies eliminates fragmented polystyrene replacement premiums. Regional cooperative purchasing alliances exhibit highest price sensitivity, while electronics OEMs tolerate specification-grade premiums for sub-50-micron surface roughness kraft fiber.
Supply Chain Analysis
Regional distribution centers in Atlanta and Charlotte metro areas anchor hub-and-spoke patterns serving poultry and breakfast sandwich chains. Supply concentrates in Georgia, North Carolina, and Alabama mill clusters drawing from upgraded MRFs across the US Southeast. Raw material dependencies rest on OCC bales, kraft pulp rolls, and bio-wax barrier coatings. Single-source vulnerability runs through Chinese import policy shifts affecting fiber feedstock costs. Distribution runs through direct-store-delivery channels in Texas and Florida bypassing centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into recycled paper capacity is reshaping competitive positioning as converters race to secure captive fiber supply ahead of EPA extended producer responsibility enforcement. Mill ownership represents the decisive upstream lever separating margin-stable incumbents from spot-market-exposed challengers.
For Market Incumbents: Anchor multi-site manufacturing footprints across Georgia and North Carolina to defend against buyer consolidation pressures from quick-service restaurant holding companies. Accelerate FDA food-contact notification pipelines for novel barrier coatings before seasonal menu transition windows close. Prioritize SQF certification maintenance for military and institutional contract eligibility.
For New Entrants and Emerging Players: Capture electronics cushioning premiums in Texas and California distribution channels where kraft fiber smoothness specifications remain underserved by incumbent foodservice-focused capacity. Target regional bakery and produce distributors bypassing centralized distribution for custom-molded tray specifications with localized graphics. Lead with in-mold labeling integration to compress secondary labeling cost disadvantages against plastic incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated fiber converters with captive Georgia mill supply and SQF-certified multi-site footprints. Long-term viability hinges on post-consumer content compliance infrastructure rather than speculative barrier technology bets. Monitor California SB 54 enforcement timelines as inflection indicator for cross-border Canadian supply chain integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Paper Mills | Captive OCC supply from Georgia mills insulates margins from Chinese import policy volatility. |
| FDA Food-Contact Notification Pipeline Expansion | Accelerated coating approvals unlock seasonal menu transitions at major quick-service chains. |
| SQF Certification Investment | Facility accreditation secures military and institutional procurement eligibility ahead of compliance deadlines. |
| In-Mold Labeling Technology Integration | Embedded full-color graphics eliminate secondary labeling steps and compress fiber-to-plastic cost gaps. |
| Cross-Border Canadian Supply Chain Certification | Dual FDA-Health Canada notification positions US Southeast capacity for federal plastics prohibition demand. |
Research Approach
Multi-period observation of OCC bale pricing, thermoformed pulp tooling lead times, and quick-service restaurant procurement cycles anchored the trend analysis, supplemented by interviews with converter operations directors, quick-service supply chain managers, MRF upgrade program officers, and FDA regulatory consultants. Secondary validation drew from EPA extended producer responsibility framework documents, FDA food-contact substance notification databases, California SB 54 implementation guidance, and customs trade data on fiber packaging imports. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Input-output matrices mapped fiber feedstock costs, tooling amortization schedules, and barrier coating R&D expenditure against quick-service automation compatibility specifications and electronics surface roughness requirements across the projection horizon. Segmentation dimensions modeled included product type, end-user industry vertical, material grade tier, and geographic production cluster. CAGRs were derived from regression analysis of historical capacity deployment against regulatory enforcement timeline assumptions, with specific weighting for state-level EPR adoption patterns and federal foodservice contract post-consumer content minimums.
The model holds under stable OCC supply from domestic MRF upgrades and consistent FDA review cycle timelines; deviation in Chinese recovered paper import restrictions or accelerated state EPR enforcement would shift capacity deployment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market