
 Global Molded Fiber Bowls Market | 2026-2036
Global Molded Fiber Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Fiber Bowls Market Intelligence
A capital-intensity divergence between automated thermoforming specialists and labor-dependent regional producers is bifurcating competitive dynamics in molded fiber bowls. Huhtamaki Oyj leverages integrated pulp molding and printing capabilities across multiple continents to sustain cost leadership in high-volume quick service restaurant contracts. Pactiv Evergreen anchors North American supply through captive fiber sourcing and extensive dairy and food service distribution networks. Brødrene Hartmann A/S specializes in recycled paper-based molded fiber for European retail and egg packaging extensions, competing on circular material credentials rather than scale.
Molded fiber bowls are rigid containers formed from slurried plant fibers—typically sugarcane bagasse, wheat straw, or recycled paper pulp—pressed and dried into shape, with wall thickness ranging from single-ply lightweight designs to double-wall insulated structures rated for hot foods above eighty-five degrees Celsius. Their primary purpose is to replace petroleum-based plastic and foam food containers in commercial and institutional food service settings where leak resistance, stackability, and compostability are required. Single-wall bowls dominate commodity quick service applications where cost minimization overrides thermal performance, while double-wall and lidded configurations capture premium positioning in catering and delivery channels where temperature retention and spill prevention command higher unit economics. Sugarcane bagasse and wheat straw materials lead growth trajectories as agricultural residue streams expand and pulping technologies improve fiber yield and whiteness without bleaching.
The U.S. Food and Drug Administration governs food contact substance compliance for molded fiber bowls, while the EU F-Gas Regulation and REACH frameworks indirectly shape fiber processing chemistry and additive restrictions. China's SAMR enforces national food safety standards on imported and domestically produced fiber foodware, creating divergent testing and certification pathways for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility schemes and compostability certification requirements, as fragmented municipal composting infrastructure threatens to outpace product innovation and create compliance gaps between material claims and end-of-life reality.
Market Dynamics
EU Single-Use Plastics Directive enforcement and state-level bans across California and New York are forcing quick service restaurant chains to accelerate molded fiber bowl procurement timelines, compressing supplier qualification windows and reshaping competitive positioning among thermoforming specialists.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated processing chemicals are pushing food service operators toward PFAS-free molded fiber alternatives, expanding addressable demand for compostable bowl suppliers.
- Sugarcane bagasse pulping:Agricultural residue fiber yield improvements are lowering unit material costs and enabling thicker-wall bowl production without virgin wood pulp dependence.
- Quick service restaurant chains:System-wide plastic elimination commitments across North American and European food service networks are creating multi-year procurement contracts for molded fiber bowl volumes.
Market Restraints
- Bleached pulp cost volatility:Recycled paper fiber input prices fluctuate with OCC (old corrugated containers) commodity markets, squeezing margin stability for mid-scale producers.
- China SAMR certification:Divergent national food safety testing requirements for imported fiber foodware create compliance friction for manufacturers serving multiple jurisdictions.
- Expanded polystyrene foam:Residual low-cost foam container availability in unregulated markets continues to undercut molded fiber pricing in price-sensitive institutional channels.
Strategic Opportunities
- India food service:Underpenetrated quick service and street food vendor segments present volume expansion potential as urban waste management regulations tighten.
- Extended producer responsibility schemes:Emerging packaging waste fee structures in Germany and France reward compostable material selection with reduced compliance levies.
- Digital food delivery platforms:Premium double-wall insulated bowl configurations are capturing higher unit economics through direct-to-consumer meal kit and ghost kitchen channels.
Industry Challenges
- Compostability certification timelines:TUV Austria OK Compost and BPI certification processes require six-to-twelve-month validation cycles, delaying product launches and contract awards.
- Thermoforming equipment capex:Automated pulp molding line investments exceed fifteen million dollars per installation, concentrating capacity expansion among capital-rich producers.
- Legacy ERP integration:Food service distributor procurement systems require EDI connectivity and lot-level traceability that smaller molded fiber suppliers struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Fiber Bowls Market |
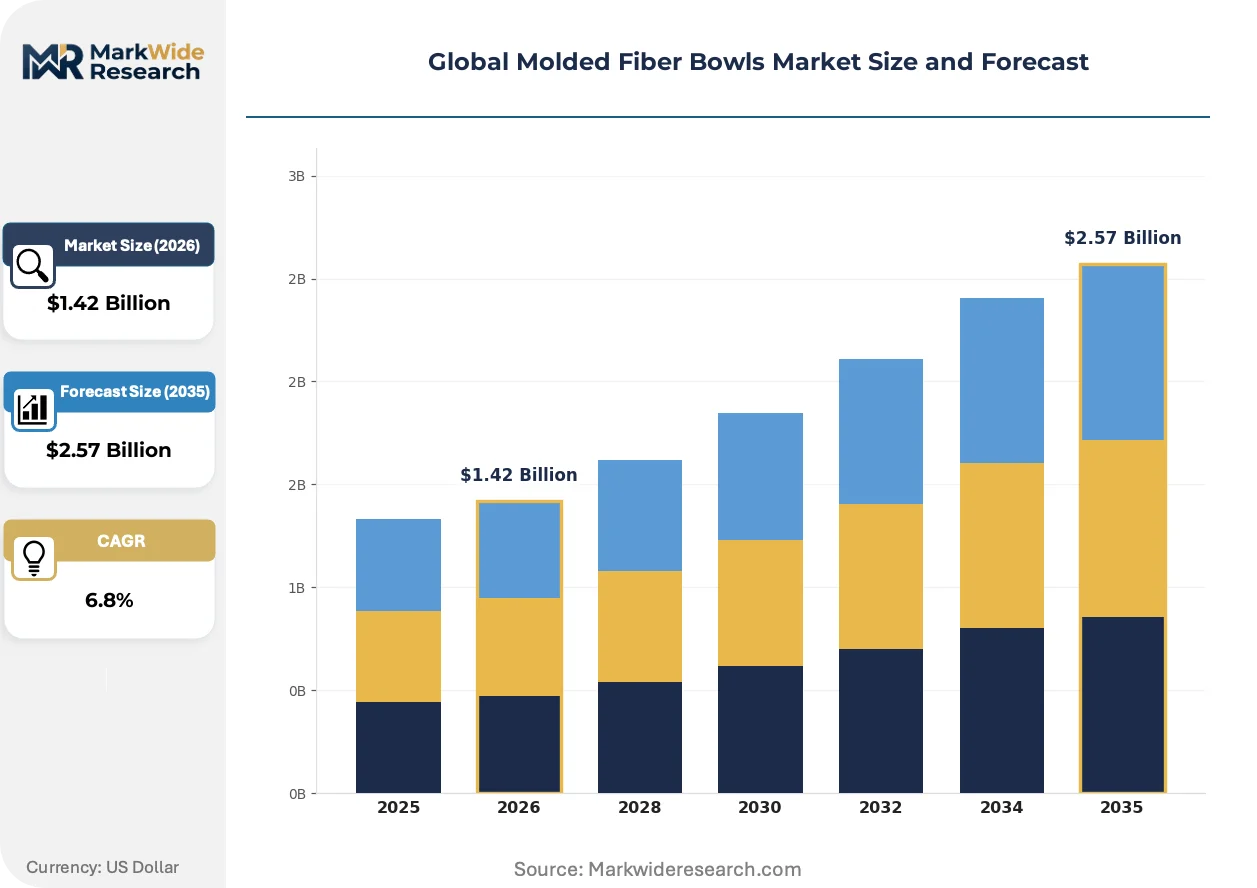
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall Bowls, Double-wall Bowls, Lidded Bowls, Compartment Bowls Material: Bamboo Fiber, Wheat Straw, Sugarcane Bagasse, Recycled Paper, Cornstarch Application: Food Service, Catering, Quick Service Restaurants, Household Use, Events & Catering End User: Restaurants, Cafeterias, Food Trucks, Institutional Canteens |
| Companies Covered | Huhtamaki Oyj, Pactiv Evergreen, Sonoco Products Company, Brødrene Hartmann A/S, CKF Inc., Genpak, Sabert Corporation, UFP Technologies Inc., Dart Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Fiber Bowls Market Strategic Shifts & Innovations
Active fiber processing and forming technologies are compressing production cycle times while regulatory chemistry restrictions are forcing additive reformulation across the supply base.
Advanced microwave-drying systems are replacing conventional thermal ovens in molded fiber bowl manufacturing, cutting energy consumption and enabling thinner-wall precision forming. Quick service restaurant suppliers in Germany and the United States are retrofitting existing thermoforming lines with this technology to meet sustainability disclosure requirements. The shift is decomposing the historical trade-off between production speed and wall thickness consistency that constrained single-ply bowl adoption in hot-food applications.
REACH framework restrictions on per- and polyfluoroalkyl substances are eliminating oil and grease resistant coatings previously standard in molded fiber food contact materials. European manufacturers are accelerating plasma treatment and natural wax barrier alternatives to maintain leak resistance without fluorinated chemistry. Caterers and delivery-focused operators across France and the Netherlands face the steepest reformulation deadlines, driving accelerated supplier qualification for compliant bowl configurations.
Direct supplier relationships between molded fiber producers and quick service restaurant corporate procurement teams are displacing traditional food service distributor intermediaries. Chains are consolidating bowl specifications across thousands of franchise locations to capture volume pricing and ensure brand-consistent sustainability messaging. This pattern is most visible in the United States, where Chipotle, Sweetgreen, and similar fast-casual networks have established dedicated molded fiber procurement categories with multi-year supply agreements.
Global Molded Fiber Bowls Market Segmentation
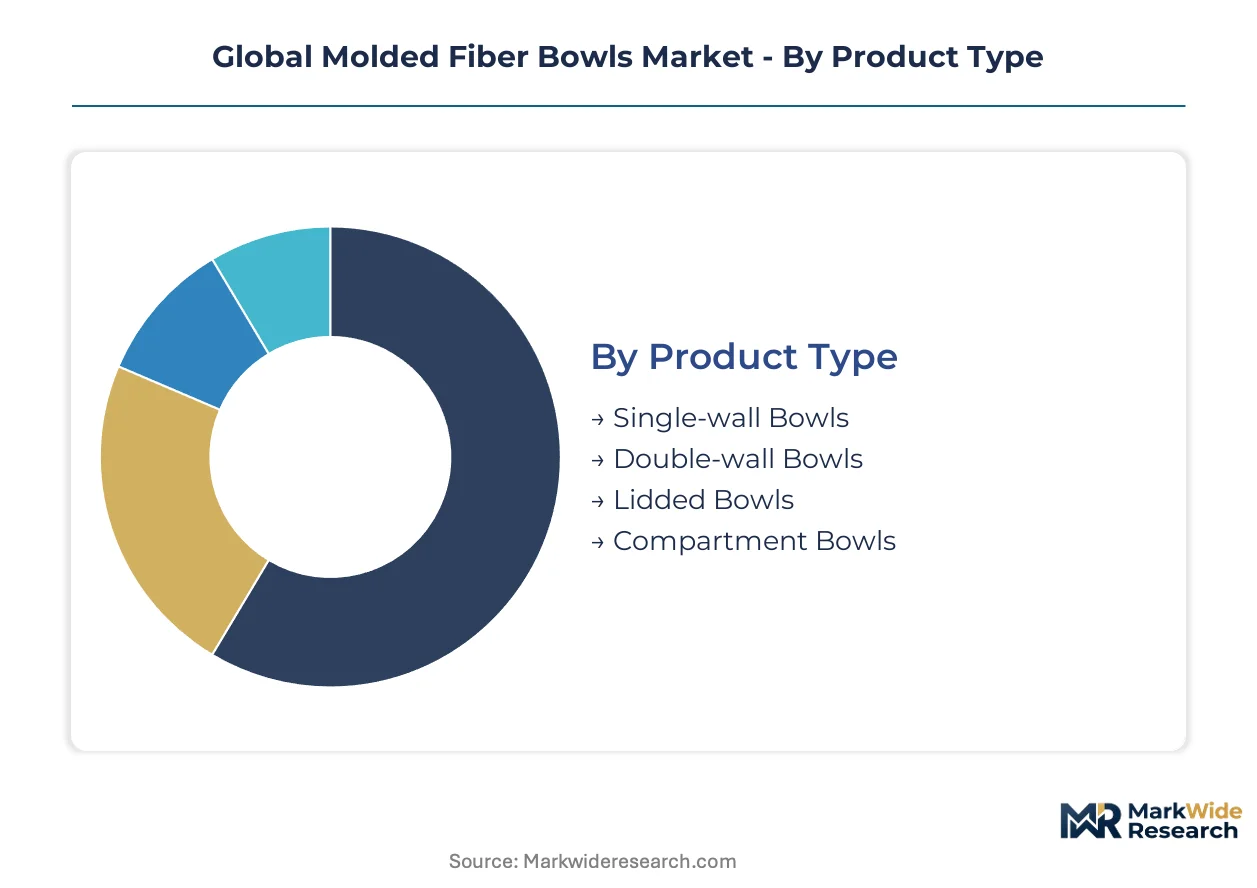
Molded fiber bowl segmentation reveals divergent margin structures across wall configurations, agricultural fiber inputs, and food service channel tiers. Understanding these divisions exposes where capital deployment and procurement consolidation concentrate competitive advantage.
Product Type:
Margin pools concentrate in insulated configurations where thermal performance commands premium positioning against commodity single-wall alternatives.
- Single-wall Bowls:Lightweight single-ply construction minimizes material input for high-volume quick service applications where cost floors determine supplier selection. Chipotle and Sweetgreen procurement teams specify these for cold salad and room-temperature bowl formats across thousands of U.S. locations, though their thin walls disqualify them from hot soup and noodle applications above sixty degrees Celsius.
- Double-wall Bowls:Insulated dual-layer structures with trapped air pockets maintain food temperatures above eighty-five degrees Celsius for extended holding periods. Ghost kitchen operators and catering specialists in Germany and France pay unit economics premiums for these configurations, as EU F-Gas Regulation compliance deadlines eliminate PFAS-coated foam alternatives.
- Lidded Bowls:Integrated or mating lid systems prevent spillage in delivery channels where transport vibration and tilt threaten food integrity.
- Compartment Bowls:Divided sections separate proteins from carbohydrates and sauces, serving institutional canteens and meal-kit providers requiring portion control without additional packaging components.
The dominant share belongs to Single-wall Bowls, while Double-wall Bowls is closing the gap fastest.
Material:
Cost tier stratification separates agricultural residue fibers with captive raw material access from recycled paper pulps exposed to OCC commodity volatility.
- Sugarcane Bagasse:Fibrous residue from sugar extraction delivers high cellulose content and natural whiteness without chlorine bleaching. Brazilian and Indian sugar mill proximity to pulping operations is lowering unit costs for bowl producers serving European quick service chains with strict compostability certification requirements.
- Wheat Straw:Agricultural byproduct from grain harvesting offers similar fiber yield to bagasse with broader geographic availability across North American and European farming regions. Pactiv Evergreen anchors North American supply through captive straw sourcing agreements with Midwest grain cooperatives, insulating margin stability from recycled paper price swings.
- Bamboo Fiber:Rapid-growth grass species provides dense fiber structure suitable for thin-wall precision forming.
- Recycled Paper:Post-consumer corrugated container pulp remains cost-competitive but faces whiteness and strength limitations without virgin fiber blending.
- Cornstarch:Biopolymer blends with molded fiber create hybrid structures with modified barrier properties.
Sugarcane Bagasse holds the volume lead, though Wheat Straw is expanding most quickly as North American supply chains mature.
Application:
Customer type concentration drives specification divergence between procurement-led corporate chains and fragmented independent operators.
- Quick Service Restaurants:System-wide plastic elimination commitments across corporate procurement functions generate multi-year volume contracts with stringent sustainability disclosure requirements. U.S. fast-casual networks consolidate bowl specifications across franchise networks to capture scale pricing and ensure brand-consistent compostability messaging.
- Catering:Event and corporate food service operators prioritize double-wall insulated configurations and lidded systems where temperature retention and presentation quality support premium pricing to end clients.
- Food Service:Broad category encompassing distributor-served independent restaurants with heterogeneous specification demands.
- Household Use:Retail-packaged consumer sales through grocery and club channels for home entertaining and meal preparation.
- Events & Catering:Large-scale temporary food service for festivals, weddings, and corporate gatherings requiring disposable solutions with visible sustainability credentials.
Quick Service Restaurants commands the largest application share, while Catering is gaining share fastest as corporate event budgets recover.
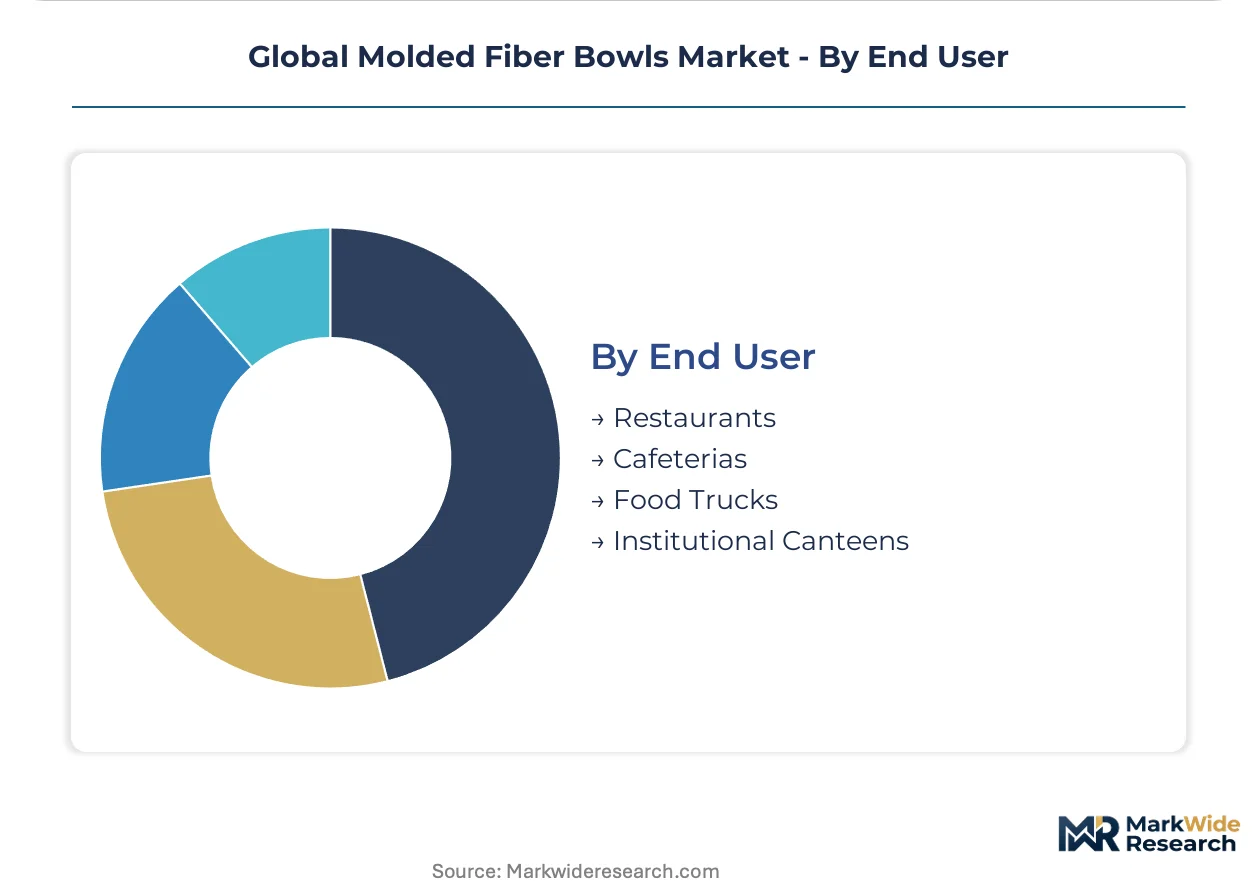
End User:
Volume scale separates institutional canteens with centralized procurement from fragmented food truck operators purchasing through distributor intermediaries.
- Restaurants:Full-service and fast-casual establishments with diverse menu formats driving specification variety across bowl sizes and wall thicknesses.
- Cafeterias:Corporate and educational dining facilities with standardized meal programs and sustainability procurement mandates.
- Food Trucks:Mobile operators prioritizing stackability and lid compatibility for confined storage spaces and transit vibration conditions.
- Institutional Canteens:Military, hospital, and prison feeding operations with massive volume requirements and extended producer responsibility compliance obligations in Germany and France.
Restaurants maintains the dominant end user position, while Institutional Canteens is climbing the fastest as extended producer responsibility schemes expand across Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Quick service restaurant chains in the United States and Germany absorb premium pricing for certified compostable bowls, while price-sensitive institutional buyers in India and Mexico continue sourcing residual foam alternatives where regulations permit.
United States
California and New York state-level plastic bans are compressing supplier qualification timelines for national quick service chains. The FDA governs food contact substance compliance, creating testing bottlenecks for imported fiber foodware. Chicago and Dallas distribution hubs are consolidating procurement volumes for Chipotle and Sweetgreen franchise networks.
Germany
Extended producer responsibility schemes reward compostable material selection with reduced compliance levies for institutional canteens. The EU F-Gas Regulation eliminates PFAS-coated alternatives, accelerating plasma treatment adoption among local manufacturers. Bavarian pulping operations are expanding wheat straw fiber capacity to serve pan-European catering demand.
China
SAMR enforces divergent national food safety standards on imported fiber foodware, creating certification friction for multinational suppliers. Urban waste management regulations in Shanghai and Beijing are tightening street food vendor compliance deadlines. Yangtze River Delta manufacturing clusters are retrofitting thermoforming lines with microwave-drying systems.
India
Underpenetrated quick service segments present volume expansion potential as municipal waste regulations tighten in Mumbai and Delhi. FSSAI food contact material standards are evolving toward compostability certification alignment with European norms. Sugarcane bagasse pulping operations in Uttar Pradesh are lowering unit costs for export-oriented bowl producers.
Brazil
Sugarcane mill proximity to pulping infrastructure creates captive raw material advantages for regional bowl manufacturers. ANVISA pharmaceutical and food safety frameworks are extending to fiber foodware import testing protocols. São Paulo state industrial parks are attracting thermoforming equipment investments from European capital equipment suppliers.
Global Molded Fiber Bowls Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Automated thermoforming specialists with integrated pulp molding capabilities command premium positioning in multi-year quick service contracts, while labor-dependent regional producers compete on price in fragmented institutional channels. Three archetypes dominate: integrated multinational suppliers with captive fiber sourcing, specialized agricultural residue processors with circular material credentials, and regional converters serving distributor-served independent restaurants. Competitive moves concentrate on capacity expansion through automated line installation and strategic partnerships with food service distributors requiring EDI connectivity and lot-level traceability.
Among Nordic-based circular material specialists, Brødrene Hartmann A/S exemplifies the recycled paper-based archetype competing on sustainability credentials rather than scale. At the integrated multinational tier, Huhtamaki Oyj and Pactiv Evergreen occupy positions sustained by captive fiber sourcing and extensive distribution network access. These three companies represent the dominant competitive configurations: agricultural residue integration, recycled fiber circularity, and continental-scale thermoforming automation.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Pactiv Evergreen |
| Sonoco Products Company |
| Brødrene Hartmann A/S |
| CKF Inc. |
| Genpak |
| Sabert Corporation |
| UFP Technologies Inc. |
| Dart Container Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day certification lead times for TUV Austria OK Compost and BPI standards compress supplier qualification windows and concentrate pricing power among thermoforming specialists with pre-certified capacity. This temporal bottleneck favors automated producers in Germany and the United States over regional converters in India and Brazil, who absorb margin compression while awaiting validation cycles.
Pricing Analysis
After-sales service contracts for lot-level traceability and EDI integration drive lifetime value for quick service restaurant procurement teams. Three-tier pricing structure across premium double-wall insulated, standard single-wall certified, and economy unbleached configurations stratifies the market. Price differentiation rests on compostability certification grade and captive fiber sourcing. Cost compression in the economy tier intensifies because recycled paper pulp fluctuates with OCC commodity markets. Institutional canteens in Germany exhibit highest price sensitivity due to extended producer responsibility compliance levies, while ghost kitchen operators in France absorb premiums for thermal performance.
Supply Chain Analysis
Strategic stockpiling of sugarcane bagasse and wheat straw pulp insulates automated thermoforming specialists from agricultural residue harvest volatility. Geographic supply concentration centers on Brazil, India, and the United States for agricultural fiber pulping, with Germany and China hosting downstream thermoforming capacity. Raw material dependencies draw from sugar mill residue streams, Midwest grain cooperatives, and recycled corrugated container networks. Single-source vulnerability concentrates in Brazilian bagasse supply during sugar harvest cycles. Distribution runs through food service distributor intermediaries requiring EDI connectivity, though direct supplier relationships with corporate procurement teams are displacing this channel in North American quick service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded fiber bowls sit in early-cycle expansion as EU F-Gas Regulation enforcement eliminates PFAS-coated foam alternatives and quick service chains systematize plastic elimination commitments. Regulatory chemistry restrictions are accelerating adoption beyond the sustainability-conscious early adopter base into mainstream food service procurement.
For Market Incumbents: Secure captive fiber sourcing agreements with Brazilian sugar mills and Midwest grain cooperatives to defend margin stability against OCC commodity volatility. Expand automated thermoforming capacity in Germany and the United States to capture compressed supplier qualification windows from California and New York state-level plastic bans. Certification investment in TUV Austria OK Compost and BPI standards anchors multi-year quick service contracts against emerging regional converters. For New Entrants and Emerging Players: BPI certification fast-track programs open white-space penetration in Indian quick service and street food vendor segments as Mumbai and Delhi municipal waste regulations tighten. Target ghost kitchen and meal-kit delivery channels in France and the Netherlands where premium double-wall configurations command unit economics premiums. Go-to-market angle emphasizes plasma treatment barrier technology to meet REACH framework PFAS restrictions without fluorinated chemistry. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because extended producer responsibility schemes across Germany and France structurally reward compostable material selection with reduced compliance levies. Acquisition target archetype: agricultural residue processors with circular material credentials and captive pulping infrastructure in Brazil or India. Signal to watch is microwave-drying equipment retrofit announcements from Yangtze River Delta manufacturing clusters, indicating capacity expansion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Supply | Captive bagasse and wheat straw sourcing insulates margin stability from OCC commodity volatility. |
| Microwave-Drying Equipment Retrofit | Yangtze River Delta and Bavarian thermoforming lines cut energy consumption for sustainability disclosure compliance. |
| Direct Procurement Relationship Establishment | Chipotle and Sweetgreen corporate teams displace distributor intermediaries for volume pricing capture. |
| Plasma Treatment Barrier Development | REACH framework PFAS elimination deadlines in France and Netherlands accelerate compliant bowl qualification. |
| Extended Producer Responsibility Compliance Positioning | German and French institutional canteens reduce packaging waste levies through compostable material selection. |
Research Approach
Cross-validation between primary interviews with quick service restaurant procurement directors, thermoforming plant managers, and agricultural residue supply coordinators anchors the qualitative findings against secondary validation from FDA food contact substance filings, EU F-Gas Regulation enforcement documentation, SAMR national food safety standards, and OCC commodity price indices. Bottom-up capacity assessments from Brazilian sugar mill pulping operations and top-down demand modeling from quick service chain plastic elimination commitments triangulate volume estimates.
Sensitivity analysis around compostability certification timeline assumptions and agricultural fiber yield improvements shapes the projection framework across the analysis window. Segmentation dimensions modeled include wall configuration tier, agricultural fiber input type, food service channel tier, and regional regulatory cluster. CAGRs derive from installed thermoforming capacity expansion announcements and quick service contract award velocity. Industry-specific forecast inputs incorporate microwave-drying technology adoption rates and plasma treatment barrier commercialization timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Single-Use Plastics Directive enforcement and stable sugarcane harvest yields; material deviation would warrant model refresh. Revision becomes warranted when China SAMR certification pathway harmonization with European compostability standards crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market