
 Fiberboard Packaging Market | 2026-2036
Fiberboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberboard Packaging Market Foresight
E-commerce distribution is fragmenting as parcel volumes surge and last-mile networks multiply. WestRock Company leverages its North American mill network to sustain containerboard supply for regional box plants. Smurfit Kappa Group plc anchors European corrugated demand through integrated recycling and paperboard operations. DS Smith plc specializes in retail-ready packaging formats that compete for shelf-facing applications in grocery chains.
Fiberboard packaging comprises paper-based engineered materials formed from wood fibers, recycled paper pulp, or agricultural residues, typically manufactured through wet-laid processes and pressed into sheets with densities ranging from 150 to 800 kg per cubic meter for load-bearing protection. Its primary commercial purpose centers on unitizing, cushioning, and transporting goods across supply chains while offering printable surfaces for branding and handling instructions. Corrugated boxes occupy the dominant volume position due to universal adoption in shipping applications, while structural fiberboard commands higher margins in industrial crating and automotive component protection where rigidity specifications exceed standard board grades. Fiberboard containers represent the fastest-growing product category as brands replace single-use plastic tubs and trays with molded pulp alternatives for food service and electronics.
The EPA governs recycled content claims and fiber sourcing under comprehensive procurement guidelines in the United States, while the EU Green Deal drives extended producer responsibility schemes that mandate recyclability and minimum recycled thresholds for fiberboard placed on European markets. China's MEE enforces dual carbon goals that restrict virgin pulp imports and incentivize domestic closed-loop fiber recovery systems. Stakeholders must monitor how divergent national recycling infrastructure investments reshape raw material availability and compliance costs across their manufacturing footprints.
Market Dynamics
E-commerce parcel volumes are fragmenting distribution networks and compressing order-to-delivery windows, forcing fiberboard manufacturers to co-locate converting capacity near metropolitan fulfillment clusters rather than traditional mill-adjacent sites.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in Germany and France now require minimum recycled fiber thresholds, pulling molded pulp demand into food service and electronics replacement applications.
- Automotive electrification logistics:Battery cell and module shipments demand high-strength structural fiberboard crating with precise vibration-dampening specifications that exceed standard corrugated capabilities.
- China's MEE dual carbon enforcement:Import restrictions on virgin pulp are accelerating domestic closed-loop recovery investments, tightening regional fiber supply and elevating recycled-content board premiums.
Market Restraints
- Recovered paper price volatility:Old corrugated container (OCC) feedstock costs swing with Chinese import quota fluctuations, compressing converter margins during supply crunches.
- Scandinavian pulp mill concentration:Four integrated producers control two-thirds of European kraftliner supply, creating bottleneck risk during maintenance cycles or energy price spikes.
- Plastic film substitution persistence:Stretch wrap and polyethylene foam retain cost advantages for moisture-sensitive shipments in humid climates, limiting fiberboard penetration in Southeast Asian export corridors.
Strategic Opportunities
- India's FSSAI food-contact approvals:Regulatory clearance for agricultural residue fiberboard is opening molded pulp tray markets for ready-meal and dairy brands previously locked into plastic.
- Retail-ready display packaging convergence:Shelf-facing fiberboard formats combining structural integrity with high-resolution print surfaces are capturing incremental value from corrugated shippers in grocery reset cycles.
- Last-mile micro-fulfillment densification:Urban dark stores and automated pickup lockers require customized box sizes in sub-batch quantities, favoring regional converting partnerships over national supply contracts.
Industry Challenges
- Digital print technician scarcity:High-speed inkjet integration for short-run customization demands operators with combined mechanical and color-management competencies that legacy workforces lack.
- FEFCO code harmonization delays:Inconsistent international box-style classifications complicate cross-border specification transfers and delay new product qualification timelines.
- Legacy ERP-to-IoT integration friction:Real-time moisture and grammage sensors on corrugators require middleware investments that smaller independent converters defer, widening productivity gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberboard Packaging Market |
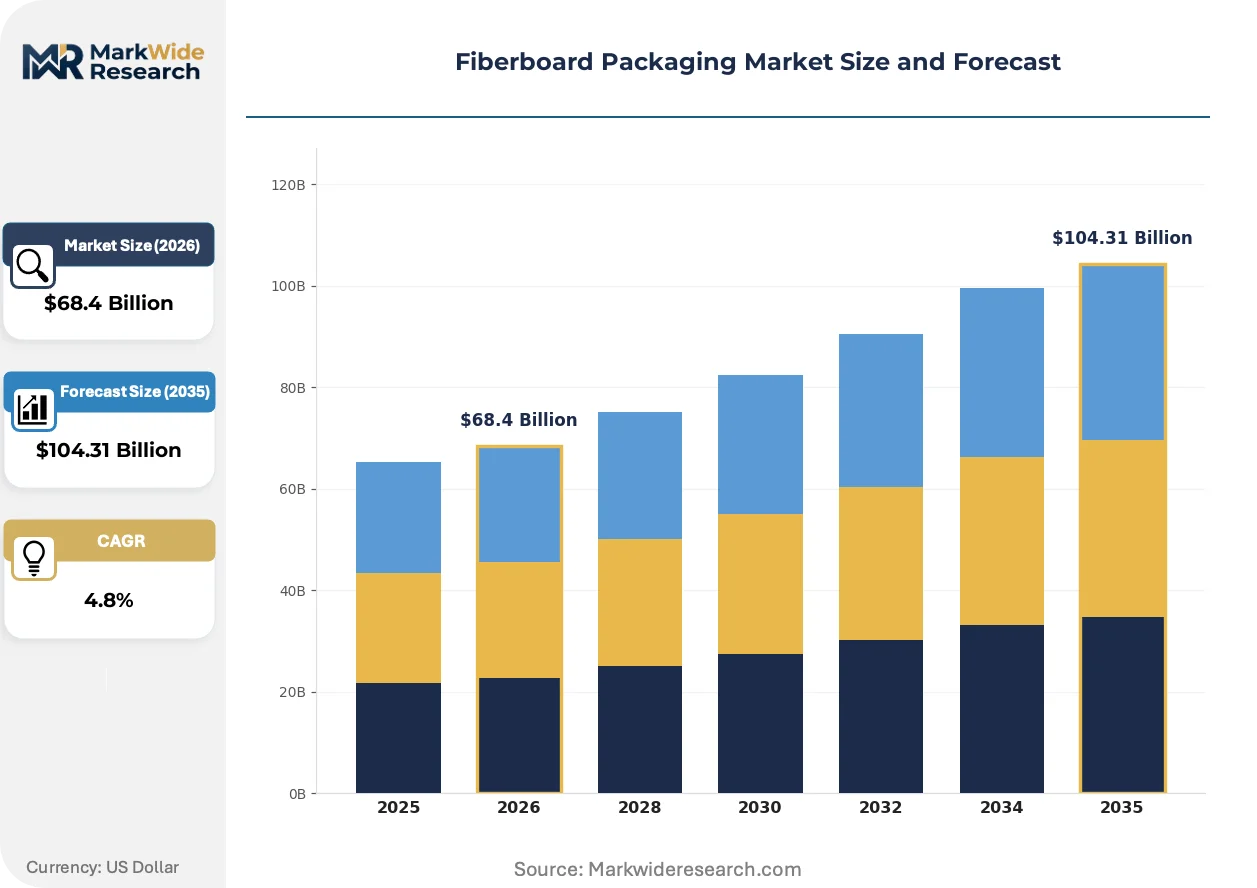
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Fiberboard Sheets, Structural Fiberboard, Fiberboard Containers End Use Industry: Food & Beverage, Consumer Goods, Electronics, Healthcare Packaging Type: Retail Packaging, Industrial Packaging, Bulk Packaging, Specialty Packaging Delivery Mode: Direct Shipping, Third-Party Logistics, E-commerce Distribution, B2B Supply |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group plc, DS Smith plc, Mondi Group, Graphic Packaging International, Stora Enso, Packaging Corporation of America, Nine Dragons Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberboard Packaging Market Shifts & Advancements
Active experimentation with fiber formulations and converting geometries is compressing lead times and expanding the performance envelope of paper-based protection beyond traditional corrugated boundaries.
Barrier-coated molded pulp is collapsing the functional gap between fiberboard and plastic tubs for refrigerated protein and prepared meals. European dairy cooperatives and North American meal-kit assemblers are qualifying agricultural-fiber trays with spray-applied bio-based moisture barriers at pilot scale. This convergence is collapsing the addressable market for expanded polystyrene in cold-chain applications previously considered unreachable for cellulose.
The EU Green Deal's packaging and packaging waste regulation revision is mandating recyclability-by-design assessments and minimum recycled content thresholds for all fiberboard placed on European markets. German and French authorities are deploying enhanced enforcement protocols against greenwashing claims, compelling converters to substantiate chain-of-custody documentation. Retail-facing brands in Benelux and Nordic markets are responding by accelerating FSC and PEFC certification renewals ahead of compliance deadlines.
Direct-to-consumer brands are compressing packaging specification cycles from annual to quarterly reviews, driven by unboxing experience metrics and social media amplification. Subscription beauty and electronics verticals in the United States and United Kingdom are displacing standard RSC boxes with die-cut presentation formats that eliminate void fill. This specification velocity is concentrating procurement influence with design-forward independent converters capable of rapid prototyping turnaround.
Fiberboard Packaging Market Segmentation
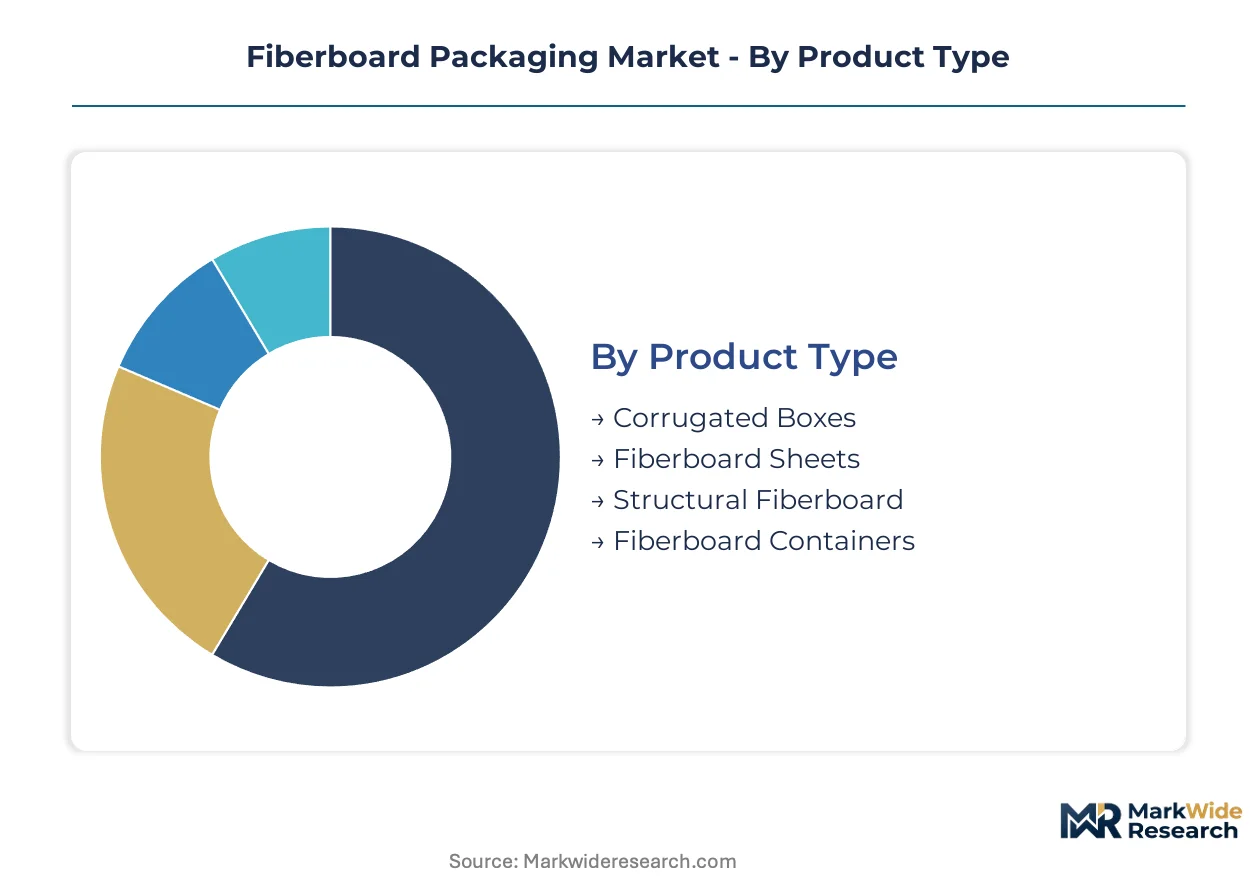
Fiberboard packaging segmentation reveals how material specifications, end-use durability requirements, and distribution velocity create distinct margin pools. Manufacturers configure mill assets and converting lines around these divides rather than pursuing universal coverage.
Product Type:
Cost tier differentiation separates commodity-grade shipping solutions from engineered structural protection demanding premium fiber formulations and precision calendering.
- Corrugated Boxes:Fluted medium sandwiched between linerboard faces provides compressive strength for parcel shipments. E-commerce fulfillment centers in Germany and the United States consume C-flute and B-flute grades in continuous pallet quantities, with specifications tightening around edge crush test thresholds for automated sortation compatibility.
- Structural Fiberboard:High-density pressed fiber panels exceeding 600 kg per cubic meter deliver rigidity for automotive battery modules and industrial machinery crating. China's NEV logistics corridors are qualifying vibration-dampening fiberboard cradles that displace plywood and expanded polystyrene for lithium-ion cell shipments.
- Fiberboard Sheets:Flat-pressed panels serve as pallet slip sheets and temporary surface protection in manufacturing environments.
- Fiberboard Containers:Molded pulp tubs and trays with barrier coatings are penetrating food service and electronics replacement applications under EU Green Deal mandates.
Corrugated boxes hold installed capacity. Fiberboard containers are rotating up the share rankings.
End Use Industry:
Application-specific performance requirements dictate grammage, moisture resistance, and print surface specifications across customer verticals.
- Food & Beverage:Chilled dairy and prepared meal brands require fiberboard with grease-resistant barriers and freezer-grade adhesive bonds. India's FSSAI approvals for agricultural residue fiberboard are unlocking molded pulp tray adoption in ready-meal segments previously committed to polypropylene.
- Electronics:Smartphone and laptop shipments demand electrostatic-dissipative fiberboard with controlled surface resistivity. Contract manufacturers in Vietnam and Mexico are specifying conductive-coated corrugated for high-value component protection against humidity and static discharge.
- Consumer Goods:Cosmetics and apparel brands prioritize unboxing aesthetics and print fidelity over structural margins.
- Healthcare:Medical device sterilization cycles require fiberboard with validated bioburden limits and seal integrity for pouch and tray applications.
Food & Beverage commands volume concentration. Electronics is climbing the fastest on specification value.
Packaging Type:
Customer type and order velocity determine whether fiberboard serves as a disposable shipping shell or a reusable display asset.
- Industrial Packaging:Heavy-duty triple-wall corrugated and structural fiberboard crating protect capital equipment and automotive components through extended supply chain transits. German automotive suppliers are specifying FEFCO 0927-style telescopic boxes with integrated dunnage for powertrain module exports.
- Retail Packaging:Shelf-ready fiberboard formats combine structural integrity with high-resolution print surfaces for grocery reset cycles. Benelux supermarket chains are accelerating adoption of retail-ready cases that eliminate secondary shelf stocking labor.
- Bulk Packaging:Gaylord containers and slip sheets unitize raw material shipments for manufacturing inputs.
- Specialty Packaging:Custom die-cut formats serve exhibition, gift, and promotional applications with short lead times.
Industrial Packaging anchors mill throughput. Retail Packaging is gaining share fastest on margin expansion.
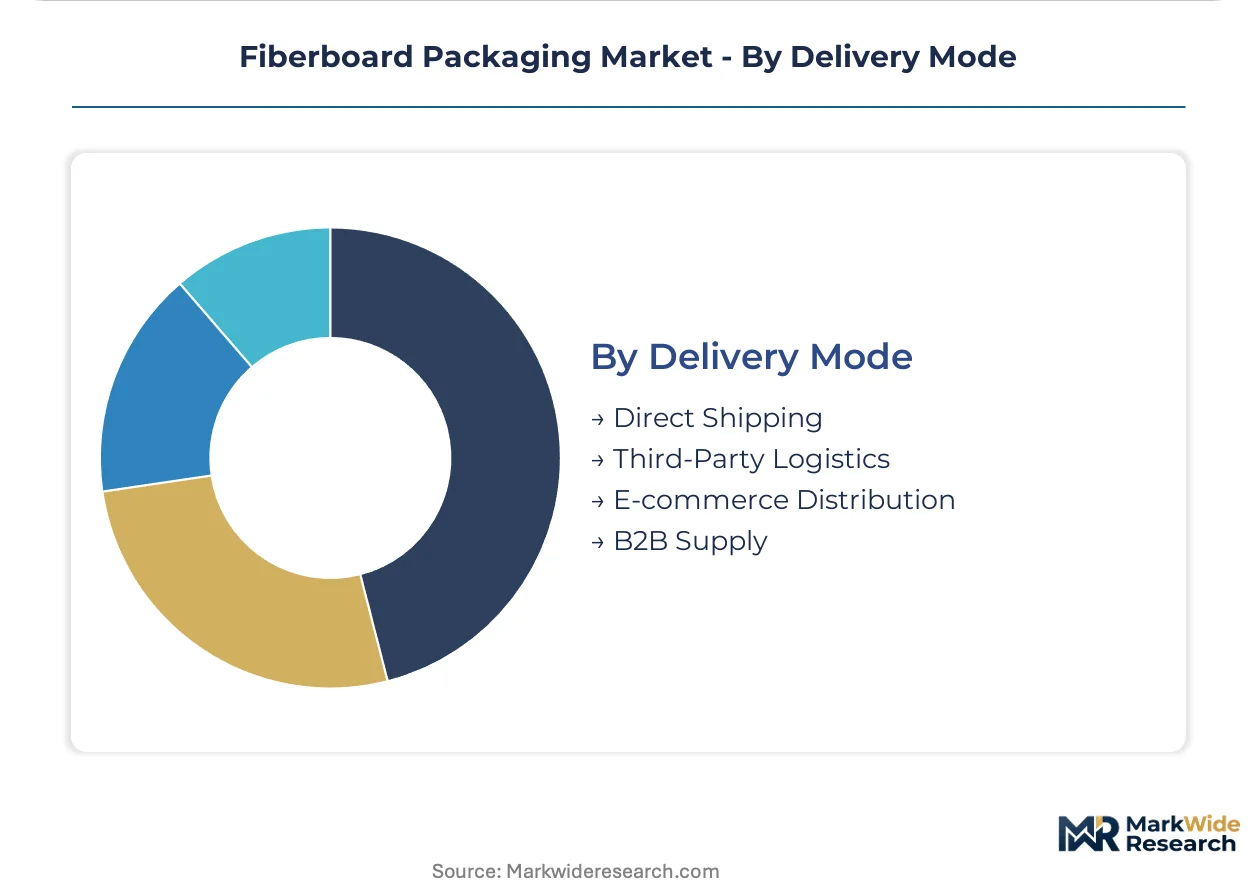
Delivery Mode:
Volume concentration and shipment frequency determine whether fiberboard supply contracts favor national scale or regional micro-fulfillment partnerships.
- E-commerce Distribution:Parcel-scale corrugated boxes in variable dimensions support direct-to-consumer fulfillment with minimal void fill. United Kingdom beauty subscription services are displacing standard RSC boxes with die-cut presentation formats designed for social media unboxing amplification.
- Third-Party Logistics:3PL providers aggregate demand across multiple shippers to justify dedicated box specifications and inventory positions. Regional logistics hubs in France and Poland are consolidating fiberboard procurement to secure volume discounts and specification consistency.
- Direct Shipping:Manufacturer-controlled fleets optimize packaging around pallet cube efficiency and freight density.
- B2B Supply:Contractual supply agreements with industrial customers emphasize forecast stability and just-in-time replenishment.
E-commerce Distribution holds throughput concentration. Third-Party Logistics is rotating up the share rankings on consolidation effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA governs recycled content claims and fiber sourcing under comprehensive procurement guidelines in the United States, while divergent national recycling infrastructure investments reshape raw material availability across manufacturing footprints worldwide.
Germany
Automotive electrification logistics and battery cell shipments drive demand for high-strength structural fiberboard crating with vibration-dampening specifications. The EU Green Deal's extended producer responsibility schemes mandate minimum recycled fiber thresholds. The Rhine-Ruhr industrial corridor hosts specialized converters supplying FEFCO 0927-style telescopic boxes for powertrain module exports.
China
New energy vehicle logistics corridors and lithium-ion cell shipments are qualifying fiberboard cradles that displace plywood and expanded polystyrene. The MEE enforces dual carbon goals that restrict virgin pulp imports and incentivize domestic closed-loop fiber recovery systems. The Yangtze River Delta concentrates molded pulp tray production for electronics replacement applications.
United States
E-commerce fulfillment centers consume C-flute and B-flute grades in continuous pallet quantities with specifications tightening around edge crush test thresholds. EPA procurement guidelines govern recycled content claims for federal supply contracts. The Great Lakes region anchors containerboard mill networks feeding regional box plants near metropolitan fulfillment clusters.
India
Ready-meal and dairy brands are adopting molded pulp trays as FSSAI approvals unlock agricultural residue fiberboard markets previously committed to polypropylene. The FSSAI regulatory clearance for food-contact fiberboard is accelerating domestic closed-loop recovery investments. Maharashtra's manufacturing belt hosts emerging converters qualifying barrier-coated trays for chilled dairy applications.
France
Retail-ready packaging formats compete for shelf-facing applications in grocery chains undergoing reset cycles. Enhanced enforcement protocols against greenwashing claims compel converters to substantiate chain-of-custody documentation. The Île-de-France region concentrates design-forward independent converters capable of rapid prototyping turnaround for subscription beauty verticals.
Fiberboard Packaging Market Competitive Landscape
Vertically integrated multinationals and regional design specialists split the market between scale-driven containerboard supply and customization-capable converting services. Mill-owning conglomerates anchor supply security through captive pulp and paperboard production. Strategic archetypes include integrated paperboard producers, independent specialty converters, and recycled fiber recovery operators. Competitive moves concentrate on co-locating converting capacity near metropolitan fulfillment clusters and qualifying barrier-coated molded pulp for cold-chain protein applications.
Among North American integrated producers, WestRock Company exemplifies the mill-network archetype with regional containerboard supply positioning. International Paper Company occupies a comparable scale-driven position in the United States market. Smurfit Kappa Group plc represents the European integrated model combining recycling operations with corrugated converting capabilities.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group plc |
| DS Smith plc |
| Mondi Group |
| Graphic Packaging International |
| Stora Enso |
| Packaging Corporation of America |
| Nine Dragons Paper |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial corridor concentrates European containerboard capacity, and this geographic clustering translates directly into pricing leverage for integrated producers supplying German automotive exporters and Benelux retail chains.
Pricing Analysis
Regional price spreads between Scandinavian kraftliner and recycled-content testliner have widened as OCC feedstock costs swing with Chinese import quota fluctuations. Three-tier pricing structure across premium structural fiberboard, standard corrugated grades, and economy molded pulp separates battery crating specifications from commodity shipping boxes. Cost compression in standard corrugated runs through converter margin pressure during recovered paper supply crunches. Contract manufacturers in Vietnam exhibit the highest price sensitivity, while German automotive suppliers prioritize vibration-dampening performance over unit cost.
Supply Chain Analysis
Export-control regimes on advanced pulp processing equipment limit technology transfer to emerging fiberboard markets, constraining capacity buildout in India and Southeast Asia. Supply concentrates in Germany, China, and the United States, where integrated mill networks draw from regional recovered paper collection systems. Raw material dependencies center on old corrugated containers, virgin kraft pulp, and agricultural residues such as bagasse and wheat straw. Single-source vulnerability in Scandinavian kraftliner supply creates bottleneck risk during maintenance cycles. Distribution runs through regional converting partnerships co-located near metropolitan fulfillment clusters rather than traditional mill-adjacent sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's packaging mandates constitute a regulatory inflection accelerating fiberboard displacement of plastic alternatives across food service and electronics logistics.
For Market Incumbents: Entrench mill-network advantages by securing long-term OCC supply contracts with municipal recovery operators in Germany and France. Expand barrier-coated molded pulp capacity to capture dairy and meal-kit substitution demand before independent converters qualify alternative suppliers. Backward integration into agricultural residue pulping hedges against virgin fiber import restrictions under China's MEE enforcement. For New Entrants and Emerging Players: India's Maharashtra manufacturing belt offers underpenetrated molded pulp tray capacity as FSSAI approvals unlock ready-meal and chilled dairy applications previously committed to polypropylene. Target design-forward independent converters in France's Île-de-France region capable of rapid prototyping turnaround for subscription beauty verticals. Partner with last-mile micro-fulfillment operators in urban dark store networks requiring customized box sizes in sub-batch quantities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty converters with digital print integration and barrier-coating capabilities over commodity containerboard producers. The five-to-ten-year viability window rewards acquisition targets possessing FSC chain-of-custody certification and food-contact regulatory clearances. Monitor China's dual carbon enforcement intensity as the signal indicating whether domestic closed-loop fiber recovery investments tighten regional supply sufficiently to sustain recycled-content board premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coated Molded Pulp Capacity Expansion | Captures cold-chain protein applications from expanded polystyrene under EU Green Deal mandates. |
| Backward Integration into Agricultural Residue Pulping | Secures feedstock independence from virgin pulp import restrictions enforced by China's MEE. |
| Digital Print Technology Partnership | Enables short-run customization for direct-to-consumer brands compressing specification cycles. |
| Regional Converting Joint Venture | Positions capacity adjacent to metropolitan fulfillment clusters serving e-commerce parcel growth. |
| FSC Chain-of-Custody Certification Program | Substantiates greenwashing-resistant documentation required by German and French enforcement protocols. |
Research Methodology
Desk research of trade association publications, customs records, and mill capacity databases preceded structured interviews with corrugated plant managers, retail packaging procurement leads, automotive logistics engineers, and sustainability compliance officers. Primary fieldwork captured specification velocity trends and barrier-coating qualification timelines. Secondary validation drew from FEFCO technical bulletins, EPA procurement guidelines, and EU Green Deal regulatory filings. Bottom-up volume estimates triangulated against top-down spending projections across end-use verticals.
Assumptions held fixed include EU packaging waste regulation enforcement intensity, Chinese OCC import quota trajectories, and e-commerce parcel growth rates. The analytical framework modeled product type, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs incorporated automotive electrification logistics demand curves and FSSAI regulatory approval timelines for food-contact fiberboard.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, industrial production indices, or energy price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and substitution elasticity between fiberboard and plastic alternatives. Material shifts in EU Green Deal enforcement protocols or Chinese dual carbon policy intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market