
 Composite Cardboard Tubes Market | 2026-2036
Composite Cardboard Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Cardboard Tubes Market Analysis
Multi-source procurement among corrugated packaging buyers is expanding as converters seek supply resilience against pulp price volatility. Sonoco leverages its North American mill network to sustain captive linerboard supply. Smurfit Kappa anchors European volume through integrated recycling and papermaking operations. Mondi Group competes on kraftliner specialization for heavy-duty tube grades.
Composite cardboard tubes consist of multiple plies of adhesively bonded paperboard wound in spiral or convolute formation around a mandrel, typically achieving burst strengths from 50 to 200 psi depending on ply count and adhesive formulation. These structures serve primarily as protective cores, shipping containers, and structural columns across industrial and consumer supply chains. Spiral-wound tubes dominate volume due to cost-efficient continuous production, while convolute constructions command premium positioning in textile and film winding applications where dimensional tolerance is critical. Custom-size configurations capture disproportionate margin pools by locking in long-term converter relationships and reducing customer switching.
EPA recycled-content guidelines and the EU Packaging and Packaging Waste Regulation shape material sourcing decisions and recyclability claims across the value chain. FDA indirect food-contact rules govern barrier-coated tubes destined for dry-food packaging, creating compliance thresholds that filter smaller converters. ISO 9001 and FSC chain-of-custody certifications increasingly function as gatekeeping requirements for multinational brand procurement. Stakeholders must weigh capital deployment between automation for standard spirals and flexible tooling for custom convolute orders as demand bifurcation hardens.
Market Dynamics
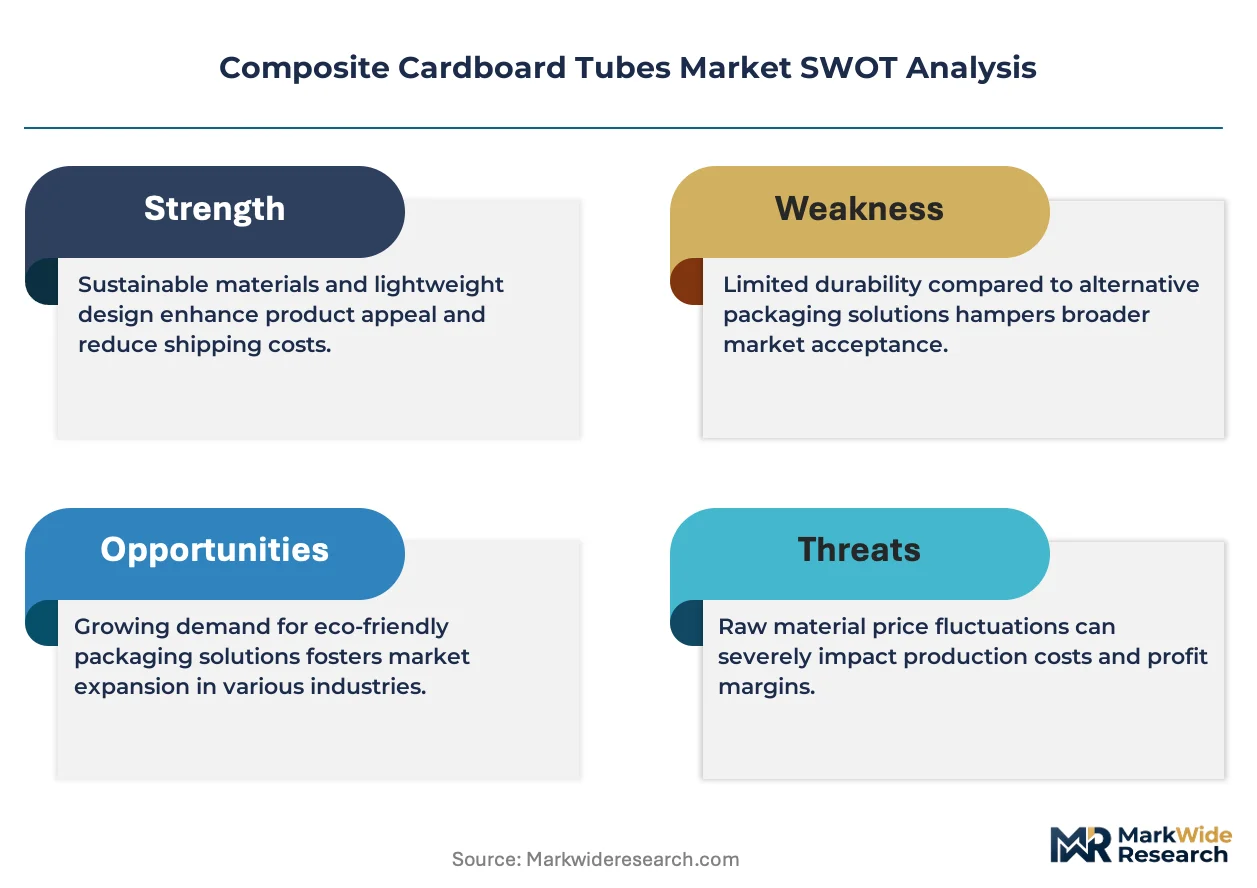
The EU Packaging and Packaging Waste Regulation is compressing demand toward recyclable fiber-based alternatives, forcing converters to requalify adhesive systems and barrier coatings for circularity compliance. This regulatory pressure intersects with pulp price volatility to reshape sourcing strategies across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclability thresholds are redirecting food and beverage brands toward paper-based secondary packaging, expanding order volumes for compliant tube grades.
- Spiral-winding automation:Continuous production technology is lowering unit economics for standard-diameter cores, enabling converters to capture volume in industrial winding applications.
- German manufacturing clusters:Deep penetration of paper-based industrial packaging in Baden-Württemberg and Bavaria creates anchored demand for heavy-duty structural tubes.
Market Restraints
- Kraftliner price volatility:Pulp futures fluctuation transmits directly to tube converter margins, squeezing profitability during raw material inflation cycles.
- Adhesive formulation constraints:FDA indirect food-contact rules limit permissible chemistries for dry-food packaging tubes, filtering smaller converters from certified supply pools.
- Plastic film cores:Polypropylene and polyethylene winding cores retain cost advantages in moisture-critical textile and film applications, constraining paper tube substitution.
Strategic Opportunities
- India packaging modernization:FSSAI food safety standards and BIS quality mandates are creating compliance-driven upgrade cycles for domestic tube converters serving FMCG brands.
- Barrier coating convergence:Water-based polymer and bio-wax technologies are enabling fiber tubes to compete in grease-resistant food packaging previously reserved for plastic.
- E-commerce shipping columns:Protective packaging demand from direct-to-consumer fulfillment networks is opening new volume channels for custom-diameter structural tubes.
Industry Challenges
- Mandrel tooling flexibility:Capital equipment for convolute production requires changeover expertise that sits with aging technician cohorts, constraining custom order responsiveness.
- FSC chain-of-custody audits:Multinational brand procurement mandates are extending certification timelines for mid-tier converters lacking dedicated compliance staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Cardboard Tubes Market |
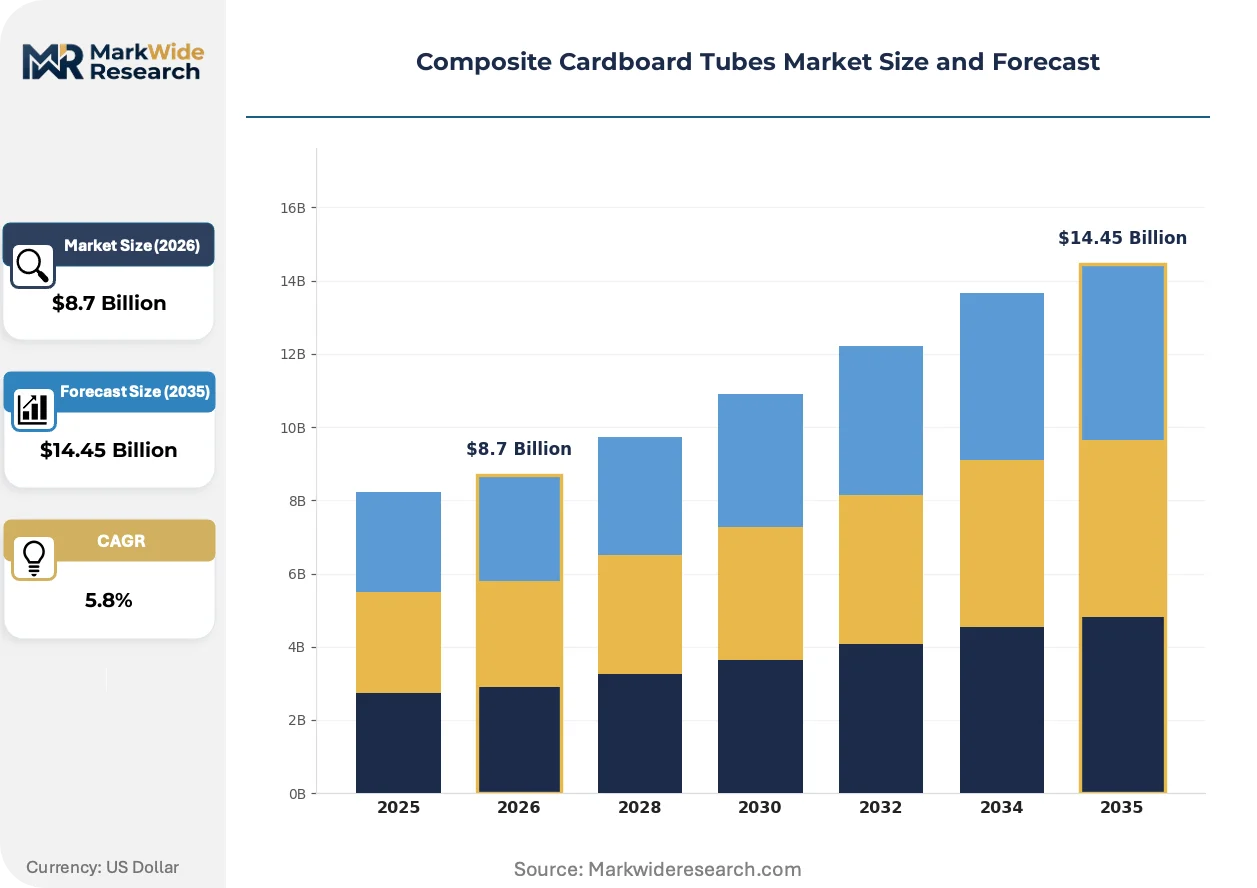
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral, Convolute, DWC, Round End User: Packaging, Textile, Construction, Automotive Size: Small, Medium, Large, Custom Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | Sonoco, Smurfit Kappa, Ace Paper Tube, Mondi Group, CBT Packaging, Visican, Marshall Paper Tube, Chicago Mailing Tube, Valk Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Cardboard Tubes Market Emerging Trajectories
Digital print integration and water-based barrier chemistry are converging to transform tube functionality from commodity protection to brand communication surface. These shifts are compressing traditional decoration lead times while expanding addressable end-use markets.
Water-based barrier coatings are decentralizing the geographic distribution of food-contact tube production. European converters adopting these chemistries are qualifying for EU Green Deal circularity credits. This technology is enabling regional production for perishable-goods brands that previously sourced moisture-resistant tubes from specialized Asian suppliers.
REACH chemical restrictions are forcing adhesive reformulation across European converter operations. Manufacturers are substituting conventional solvent-based bonding systems with bio-derived alternatives to maintain market access. German tube producers are absorbing the highest compliance costs, passing through price adjustments to industrial winding customers in textile and film sectors.
Direct-to-brand specification is displacing distributor-mediated tube procurement in North American consumer goods sectors. Large CPG buyers are consolidating supplier panels and mandating ISO 9001 certification as a baseline qualification. This pattern is most visible in California and Texas, where sustainability procurement teams are embedding recycled-content thresholds into vendor scorecards.
Composite Cardboard Tubes Market Segmentation
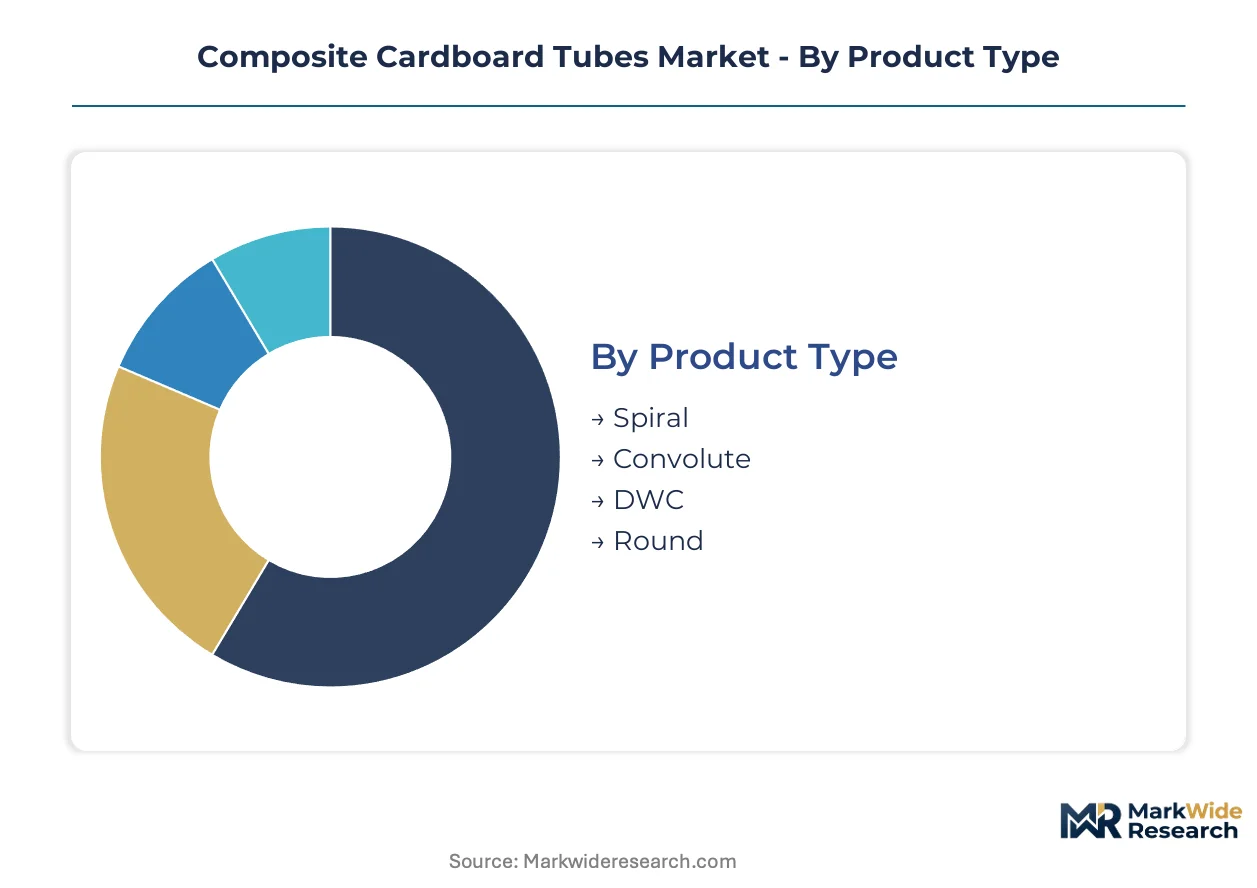
Tube converters configure production assets around diameter ranges and winding geometries that lock in margin profiles. Segment selection determines capital deployment between continuous spiral lines and flexible convolute mandrels.
Product Type:
Capital intensity peaks with convolute mandrel systems requiring precision tooling and changeover expertise.
- Spiral:Continuous paperboard plies wind helically around a stationary mandrel, achieving burst strengths from 50 to 200 psi through adhesive bonding. German textile and film winding clusters in Baden-Württemberg anchor volume demand for standard-diameter industrial cores.
- Convolute:Parallel paperboard layers wrap lengthwise around a rotating mandrel, delivering tighter dimensional tolerances critical for premium textile and film applications. REACH chemical restrictions are forcing adhesive reformulation that filters smaller European converters from certified supply pools.
- DWC:Double-wall constructions stack concentric tube layers for heavy-duty structural columns in construction and shipping applications.
- Round:Circular cross-section tubes serve as the default geometry for protective packaging and consumer goods cores.
Most installed capacity flows through Spiral. Expansion is steepest in Convolute.
End User:
Application-driven cost tiers separate commodity packaging from specification-critical industrial winding.
- Packaging:Food and beverage brands are scaling orders for sustainable secondary packaging as EU Packaging and Packaging Waste Regulation tightens recyclability thresholds. Water-based barrier coatings are enabling fiber tubes to compete in grease-resistant food applications previously reserved for plastic.
- Textile:Film and yarn winding operations demand dimensional precision that convolute constructions command at premium positioning. Polypropylene cores retain cost advantages in moisture-critical applications, constraining paper tube substitution.
- Construction:Structural columns and forming tubes require heavy-duty burst specifications.
- Automotive:Protective shipping cores and parts containers serve just-in-time assembly networks.
Volume concentrates in Packaging. Value capture is climbing fastest in Textile.
Size:
Customer type stratification separates high-volume standard diameters from relationship-locked custom configurations.
- Small:Narrow-diameter cores serve consumer tape, label, and narrow-film winding. California sustainability procurement teams are embedding recycled-content thresholds into vendor scorecards for small-tube suppliers.
- Medium:Mid-range diameters capture industrial winding volume across textile and paper converters.
- Large:Wide-diameter tubes function as structural shipping containers and construction forming.
- Custom:Bespoke diameter and length specifications lock in long-term converter relationships and reduce customer switching. E-commerce fulfillment networks are opening new volume channels for custom-diameter protective tubes.
Custom configurations capture disproportionate margin pools. Standard sizes dominate unit economics.
Distribution Channel:
Supply concentration varies from distributor-mediated procurement to direct-to-brand specification.
- Wholesale:Distributor networks aggregate fragmented converter supply for mid-tier industrial buyers.
- Retail:Hardware and packaging supply stores serve small-scale end-users with limited volume.
- Direct Sales:Large CPG buyers in Texas and California are consolidating supplier panels and mandating ISO 9001 certification as baseline qualification. Direct-to-brand specification is displacing distributor-mediated procurement in North American consumer goods sectors.
- Online:Digital platforms enable spot purchasing for non-critical applications and prototype quantities.
Direct Sales channels are gaining procurement share fastest. Wholesale retains the deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns trace regulatory-arbitrage gaps between jurisdictions with divergent compliance costs. Converters are relocating capacity toward regions where EU Packaging and Packaging Waste Regulation enforcement remains less stringent while maintaining market access through distribution partnerships.
Germany
Industrial winding demand from textile and film sectors anchors volume in Baden-Württemberg and Bavaria manufacturing clusters. REACH chemical restrictions from ECHA force adhesive reformulation investments that filter smaller converters from certified supply pools. Stuttgart-area tube producers absorb the highest compliance costs and pass through price adjustments to automotive and industrial customers.
United States
California sustainability procurement teams embed recycled-content thresholds into vendor scorecards for CPG suppliers. EPA recycled-content guidelines shape material sourcing decisions across the value chain. Texas-based fulfillment networks generate protective packaging demand for custom-diameter structural tubes serving direct-to-consumer channels.
India
FSSAI food safety standards and BIS quality mandates drive compliance-driven upgrade cycles for domestic converters serving FMCG brands. Maharashtra and Gujarat packaging modernization programs accelerate capital deployment toward automated spiral-winding lines. Mumbai-Pune industrial corridor attracts multinational brand sourcing teams seeking regional production alternatives.
United Kingdom
Post-Brexit regulatory divergence creates uncertainty around packaging waste compliance timelines for tube exporters. London and Midlands converters face dual certification burdens for EU and domestic markets. Birmingham-area industrial packaging specialists maintain textile winding relationships while navigating FSC chain-of-custody audit requirements from multinational buyers.
China
Dual carbon goals from MIIT accelerate fiber-based packaging substitution in coastal manufacturing zones. Yangtze River Delta converters supply e-commerce fulfillment networks with protective shipping columns. Zhejiang and Jiangsu provinces concentrate spiral-winding capacity for export-oriented consumer goods packaging.
Composite Cardboard Tubes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue barrier-coated food-contact specializations and e-commerce protective formats. The vendor base stratifies across integrated paperboard manufacturers, independent converter specialists, and regional fabrication shops serving local industrial accounts. Three archetypes dominate: mill-integrated players with captive linerboard supply, custom-diameter specialists locking in long-term relationships, and automation-focused volume producers. Capacity expansion and certification acquisition constitute the dominant competitive moves as procurement panels consolidate.
Among North American mill-integrated players, Sonoco exemplifies backward integration into captive linerboard networks that buffer pulp price volatility. Smurfit Kappa anchors European volume through integrated recycling and papermaking operations spanning multiple member states. Mondi Group occupies a position within kraftliner specialization for heavy-duty tube grades serving industrial winding applications. These three represent distinct strategic postures: captive raw material security, continental scale with circular infrastructure, and premium-grade technical specialization.
| Leading Market Players |
|---|
| Sonoco |
| Smurfit Kappa |
| Ace Paper Tube |
| Mondi Group |
| CBT Packaging |
| Visican |
| Marshall Paper Tube |
| Chicago Mailing Tube |
| Valk Industries |
| Others |
Supply Flow & Price Mechanics
Backward integration into captive linerboard networks anchors both supply security and pricing power for mill-integrated converters facing kraftliner futures volatility. Sonoco's North American mill footprint and Smurfit Kappa's European recycling-papermaking operations demonstrate how upstream control insulates margin structures from pulp price transmission.
Pricing Analysis
Distributor markups compress as direct-to-brand procurement displaces wholesale channels in North American CPG sectors. Three-tier pricing structure across FSC-certified premium, ISO-baseline standard, and unbranded economy levels separates multinational brand panels from mid-tier industrial accounts. Cost compression in standard spiral grades is intensifying because REACH adhesive reformulation expenses concentrate in German manufacturing clusters. Mid-range industrial buyers exhibit highest price sensitivity; custom-diameter specialists serving e-commerce fulfillment networks show lowest.
Supply Chain Analysis
Freight cost differentials between German industrial clusters and Asian barrier-coating specialists are reshaping regional production footprints for moisture-resistant food-contact tubes. Raw material sourcing draws from Swedish kraftliner mills, Brazilian pulp plantations, and recycled fiber collection networks across EU member states. Single-source vulnerability sits with specialized bio-wax coating suppliers qualifying for EU Green Deal circularity credits. Distribution runs through converter-direct relationships for large CPG accounts and wholesale aggregators for fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from the compliance cost gap between REACH-regulated German producers and FSSAI-governed Indian converters serving equivalent FMCG specifications.
For Market Incumbents: Anchor market position through FSC chain-of-custody certification acquisition and automated spiral-line capacity expansion in Texas fulfillment corridors. Plastic film core substitution in moisture-critical textile applications threatens paper tube volume; defend through water-based barrier coating R&D investment qualifying for EU circularity credits. For New Entrants and Emerging Players: Launch via direct-to-brand specification channels targeting California sustainability procurement teams embedding recycled-content thresholds into vendor scorecards. White-space concentrates in custom-diameter protective tubes for e-commerce shipping columns and grease-resistant food packaging previously reserved for plastic barriers. Penetrate through ISO 9001 certification as baseline qualification for CPG supplier panels. For Investors and Strategic Acquirers: Roll-up economics work for custom-diameter specialists with aging technician cohorts because mandrel tooling expertise scarcity constrains responsive capacity expansion. Five-to-ten-year viability hinges on barrier-coating technology transitions displacing solvent-based systems. Target mid-tier European converters facing REACH compliance filtering. Signal to watch: FSSAI enforcement intensity accelerating Maharashtra and Gujarat packaging modernization programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Linerboard | Sonoco's mill network buffers pulp price volatility transmission to converter margins. |
| Water-Based Barrier Coating Adoption | EU Green Deal circularity credits enable regional production for moisture-resistant food tubes. |
| Automated Spiral-Winding Capacity Expansion | Texas fulfillment networks generate protective packaging demand for custom-diameter structural columns. |
| FSC Chain-of-Custody Certification Investment | Multinational brand procurement mandates extend certification timelines for mid-tier converters. |
| Direct-to-Brand Distribution Channel Development | California CPG buyers consolidate supplier panels and mandate ISO 9001 baseline qualification. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tube converter operations managers, CPG packaging procurement leads, FSC certification auditors, and adhesive formulation chemists with secondary validation against customs trade data, SEC 10-K filings from publicly listed packaging groups, EPA recycled-content guideline documentation, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up capacity surveys across German Baden-Württemberg clusters and Indian Maharashtra-Gujarat corridors triangulated against top-down demand modeling from textile winding and food packaging end-use sectors.
Historical reference periods anchored volume and value trajectories across the analysis window, with projection horizons extending through the forecast period. Segmentation dimensions modeled include winding geometry (spiral versus convolute), end-use application (packaging, textile, construction), diameter configuration (standard versus custom), and regional regulatory cluster (REACH-governed EU, FSSAI-governed India, EPA-guided US). CAGRs derived from installed capacity utilization rates, pulp futures correlation analysis, and brand procurement panel consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH chemical restriction acceleration or kraftliner supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Fiberboard Packaging Market