
 Molded Fiber Trays Market | 2026-2036
Molded Fiber Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Trays Market Outlook
Modular tray configurations that separate compartments for hot and cold items is pivoting buyer specifications across food service and electronics sectors. Huhtamaki Oyj leverages its European manufacturing footprint to supply standardized modular formats to pan-regional quick-service chains. Brødrene Hartmann A/S anchors its position through captive pulp sourcing and thermoforming expertise in molded fiber. Sonoco Products Company differentiates by extending protective tray designs into automotive component shipping, where vibration resistance commands premium positioning.
Molded fiber trays are formed from slurried cellulose fibers—typically recycled paper, bagasse, or bamboo—that are vacuum-molded into precise geometries and dried under heat and pressure, yielding rigid, shock-absorbent structures designed primarily for protective packaging and food contact applications. Trays and clamshells capture the dominant volume share, driven by food service demand for stackable, grease-resistant serving vessels that replace expanded polystyrene. Inserts represent the fastest-expanding configuration, as electronics manufacturers specify custom-fit fiber cushioning for smartphones and laptops to satisfy retailer sustainability scorecards.
The EU F-Gas Regulation and REACH compliance frameworks restrict fluorinated treatments historically applied to fiber trays, compelling suppliers to certify compostable barrier coatings through EFSA-reviewed pathways. The US FDA maintains food contact notification requirements for post-consumer recycled fiber content, while China's GB standards mandate heavy metal thresholds in imported molded fiber food packaging. Stakeholders must monitor evolving compostability certification timelines across jurisdictions, as misaligned regional standards threaten to fragment product specifications and complicate cross-border sourcing strategies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing food service operators to abandon single-use plastics, redirecting procurement volumes toward fiber-based alternatives with certified recycled content thresholds.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recycled content thresholds favor fiber-based solutions over petroleum-derived alternatives in food contact applications across Germany, France, and Italy.
- Quick-service restaurant adoption:North American chains are replacing expanded polystyrene with molded fiber trays for takeout and delivery, driven by corporate sustainability commitments and consumer preference shifts.
- Bagasse and bamboo fiber processing:Agricultural residue pulp technologies reduce dependence on virgin wood fiber while improving grease resistance in hot-food applications.
Market Restraints
- Fluorinated barrier chemistry restrictions:The EU F-Gas Regulation and REACH compliance frameworks prohibit per- and polyfluoroalkyl substances historically used for oil and moisture resistance, forcing costly reformulation.
- Pulp supply concentration:Captive pulp sourcing dominates among Scandinavian manufacturers, limiting independent tray producers' access to cost-competitive raw material inputs.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse in Eastern European markets, undermining end-of-life claims for certified fiber trays.
Strategic Opportunities
- Electronics protective packaging:Smartphone and laptop manufacturers specify custom-fit fiber cushioning to satisfy retailer sustainability scorecards, opening premium positioning beyond food service.
- Automotive component shipping:Vibration-resistant tray designs for precision parts command price premiums in just-in-time supply chains serving German and Japanese vehicle assembly plants.
- US FDA food contact notification pathways:Streamlined approval processes for post-consumer recycled fiber content enable faster market entry for circular material innovators.
Industry Challenges
- Thermoforming equipment specialization:Precision mold engineering for complex geometries requires rare combinations of pulp processing and heat-pressure control expertise.
- Cross-border certification fragmentation:Misaligned compostability standards between EU EN 13432, US ASTM D6400, and China's GB/T 20197 complicate product specifications for multinational customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Trays Market |
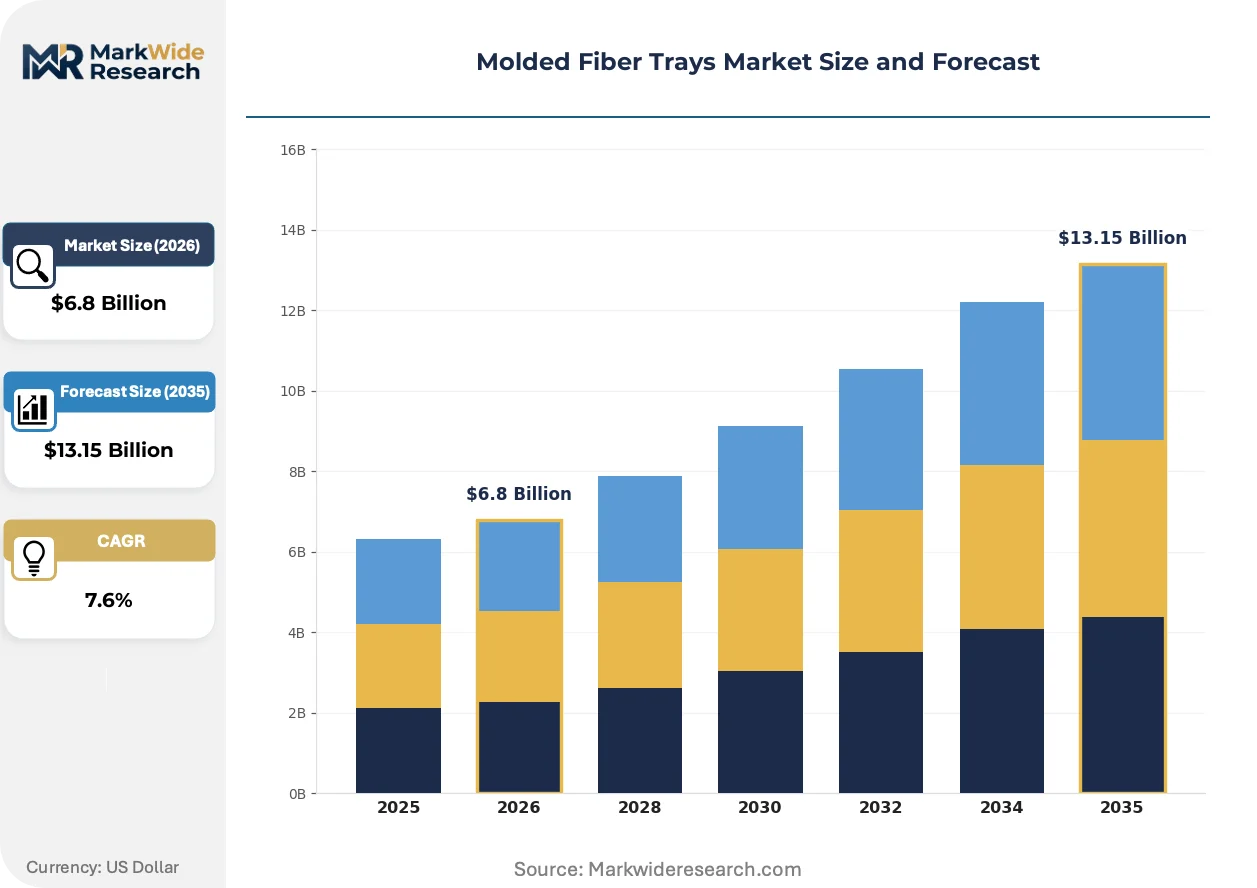
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshells, Inserts, Trays, Containers Material: Recycled Paper, Virgin Fiber, Bagasse, Bamboo End User: Food Service, Retail, Electronics, Automotive Packaging Type: Biodegradable, Compostable, Recyclable, Non-Recyclable |
| Companies Covered | Huhtamaki Oyj, Brødrene Hartmann A/S, Sonoco Products Company, UFP Technologies Inc., Pactiv Evergreen, Genpak LLC, Sabert Corporation, Keiding, Inc., ESCO Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Trays Market Strategic Shifts
Barrier coating technologies and modular tray architectures are redefining performance specifications across food service and industrial protective applications, compressing development cycles for incumbent suppliers.
Dry-molded fiber processing is decentralizing production economics by eliminating water-intensive slurry systems and enabling smaller-scale regional manufacturing. Food service distributors in the United Kingdom and Netherlands are piloting localized tray production to reduce transport emissions and inventory carrying costs. This distributed model compresses lead times from weeks to days while challenging centralized Scandinavian pulp-to-tray supply chains.
The EU F-Gas Regulation restricts hydrofluorocarbon treatments for grease resistance, compelling suppliers to certify compostable barrier coatings through EFSA-reviewed pathways. Industrial consequence includes accelerated R&D spending on polysaccharide and lipid-based alternatives. German supermarket chains and quick-service restaurants are most affected, demanding third-party verification ahead of neighboring markets to preempt compliance risk.
Retailer sustainability scorecards now dictate supplier selection in electronics protective packaging, displacing traditional procurement criteria centered on unit cost. Amazon and Apple specify molded fiber cushioning percentages in vendor qualification documents. This certification-driven preference shift is most visible in China and Vietnam, where contract manufacturers reconfigure component packaging to maintain tier-one supplier status.
Molded Fiber Trays Market Segmentation
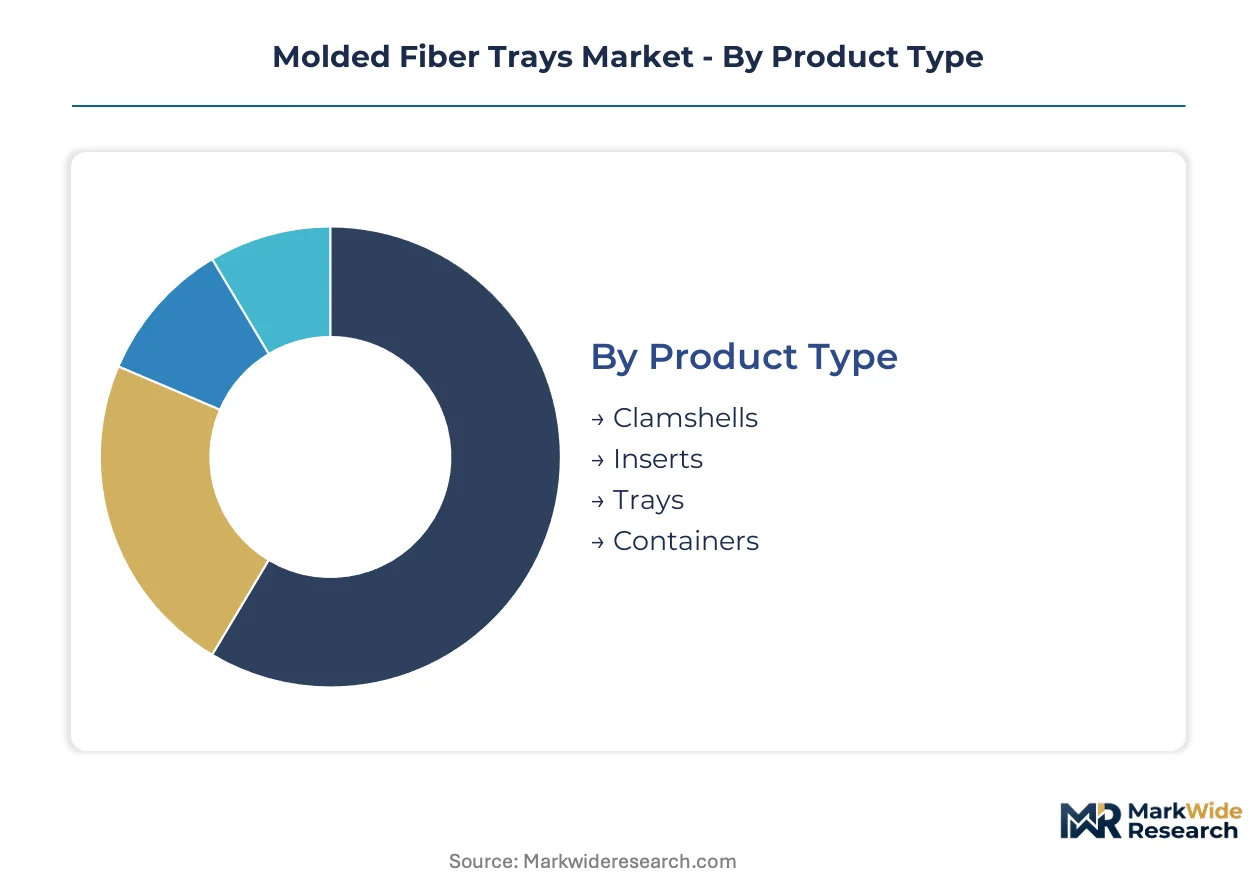
Segmentation in molded fiber trays reveals how material specifications and end-use requirements create divergent performance thresholds. Buyers in food service, electronics, and automotive sectors impose incompatible demands on moisture resistance, dimensional precision, and vibration damping that shape supplier specialization.
Product Type:
Replacement cycles vary sharply across product configurations, with food service operators refreshing stock quarterly while electronics manufacturers redesign cushioning annually for new device form factors.
- Trays:Standardized rectangular and round formats dominate quick-service restaurant takeout applications, formed from vacuum-molded slurries with heat-pressed edges for stackability. Demand concentrates in Germany and France where supermarket chains specify grease-resistant grades ahead of EU Packaging and Packaging Waste Regulation deadlines.
- Clamshells:Hinged-lid configurations integrate locking tabs and venting channels for hot-food retention, requiring precise fiber density calibration to prevent hinge cracking during repeated flexing. North American chains are replacing expanded polystyrene clamshells with these fiber alternatives to meet corporate sustainability commitments.
- Inserts:Custom-fit cushioning for smartphones and laptops commands premium positioning as electronics manufacturers satisfy retailer sustainability scorecards.
- Containers:Deep-drawn formats with reinforced corners serve meal-kit and prepared food segments requiring liquid containment without secondary wrapping.
Volume placements concentrate in Trays; the faster expansion belongs to Inserts.
Material:
Cost tiers separate commodity pulp from agricultural residue fibers, with bagasse and bamboo commanding 15-40% premiums over recycled paper in food contact applications.
- Recycled Paper:Post-consumer fiber content dominates mass-market food service trays, with US FDA food contact notification requirements governing heavy metal thresholds and contaminant screening. Supply concentrates in Scandinavian captive pulp operations that limit independent producer access.
- Bagasse:Sugarcane residue pulp delivers superior grease resistance in hot-food applications through inherent wax content, reducing dependence on fluorinated barrier treatments restricted under EU F-Gas Regulation. German quick-service restaurants specify bagasse grades ahead of neighboring markets.
- Bamboo:Rapid-renewable fiber source with high tensile strength suits electronics protective packaging requiring precise dimensional stability.
- Virgin Fiber:Uncontaminated cellulose from managed forestry serves pharmaceutical and premium food segments where optical brightness and odor neutrality justify cost premiums.
Recycled Paper captures the highest shipment volumes; bamboo fiber is climbing the fastest as Asian electronics manufacturers reconfigure supply chains.
End User:
Customer type determines specification rigor, with automotive and electronics buyers imposing vibration resistance and cleanliness protocols that food service operators rarely match.
- Food Service:Quick-service restaurants and supermarket chains specify stackable, grease-resistant serving vessels that replace expanded polystyrene, with procurement volumes redirected by EU Packaging and Packaging Waste Regulation mandates across Germany, France, and Italy.
- Electronics:Smartphone and laptop manufacturers demand custom-fit fiber cushioning with anti-static properties to satisfy Amazon and Apple sustainability scorecards, displacing traditional foam procurement criteria centered on unit cost.
- Automotive:Vibration-resistant tray designs for precision components command price premiums in just-in-time supply chains serving German and Japanese vehicle assembly plants.
- Retail:Private-label and branded goods distributors specify molded fiber for produce and prepared meal presentation, with compostability certification timelines varying across jurisdictions.
Food Service maintains the largest installed base; Electronics is gaining share fastest on certification-driven preference shifts.
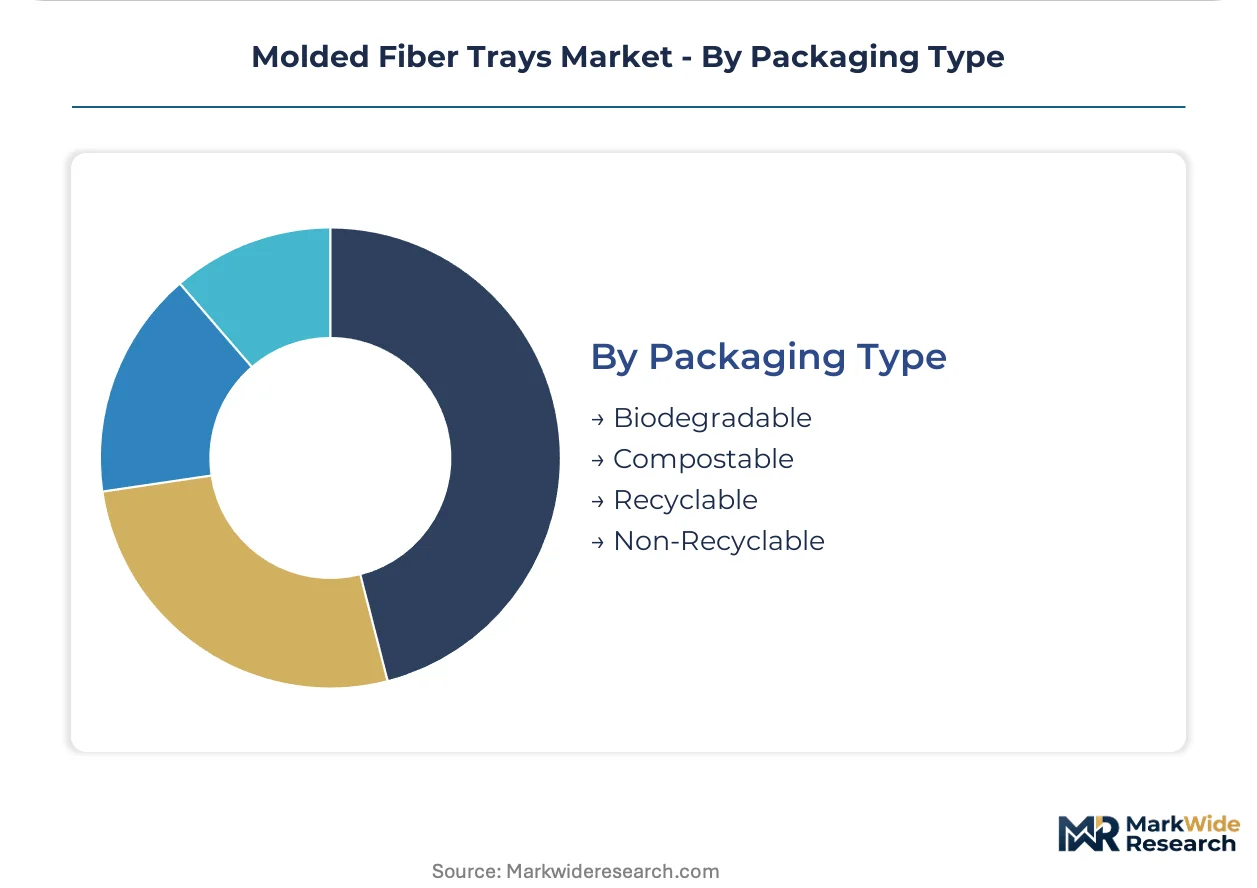
Packaging Type:
Margin structures diverge across certification tiers, with industrial compostable grades capturing premiums over backyard-degradable alternatives that lack third-party verification.
- Compostable:EN 13432 and ASTM D6400 certified products require polysaccharide or lipid-based barrier coatings as EU F-Gas Regulation restricts fluorinated treatments, with EFSA-reviewed pathways mandatory for food contact approval.
- Biodegradable:Unspecified degradation timelines without certification face skepticism from German supermarket chains demanding third-party verification ahead of neighboring markets.
- Recyclable:Paper stream compatibility allows post-consumer collection through existing municipal systems, though food contamination limits actual recovery rates.
- Non-Recyclable:Laminated or heavily contaminated fiber grades relegated to energy recovery or landfill, with volumes shrinking under regulatory pressure.
Compostable formats command the steepest pricing; Recyclable retains the broadest infrastructure compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian manufacturers control captive pulp supply chains while consumption concentrates in German quick-service restaurants and North American food service chains. This production-consumption split shapes cross-border trade flows and regional pricing tiers.
Germany
Quick-service restaurant chains and supermarket operators specify grease-resistant molded fiber grades ahead of EU Packaging and Packaging Waste Regulation deadlines. The country's national packaging regulator enforces recycled content thresholds that favor fiber-based solutions over petroleum-derived alternatives. Industrial demand clusters around the Rhine-Ruhr metropolitan region, where food distributors coordinate pan-European procurement volumes.
United States
North American chains are replacing expanded polystyrene with molded fiber trays for takeout and delivery applications. The FDA maintains food contact notification requirements for post-consumer recycled fiber content that enable faster market entry for circular material innovators. California and New York Metro area operators lead procurement shifts driven by municipal plastic restrictions and corporate sustainability commitments.
China
Electronics contract manufacturers reconfigure component packaging to satisfy Amazon and Apple sustainability scorecards. GB standards mandate heavy metal thresholds in imported molded fiber food packaging. Manufacturing concentrates in the Yangtze River Delta, where smartphone and laptop assembly plants specify custom-fit fiber cushioning for retailer qualification.
United Kingdom
Food service distributors pilot localized tray production using dry-molded fiber processing to reduce transport emissions and inventory carrying costs. The country's national environmental regulator monitors compostability certification timelines that threaten to fragment product specifications. London and Southeast England logistics hubs coordinate distributed manufacturing models that compress lead times from weeks to days.
India
Agricultural residue pulp technologies reduce dependence on virgin wood fiber while improving grease resistance in hot-food applications. BIS standards govern food contact safety for molded fiber packaging in domestic and export markets. Manufacturing activity concentrates in Maharashtra and Gujarat, where bagasse processing facilities supply quick-service restaurant chains expanding across South Asian markets.
Molded Fiber Trays Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-tray specialists with captive fiber supply. Scandinavian and North American manufacturers dominate volume positions through backward integration into recycled paper and agricultural residue processing. Two strategic archetypes define the field: pan-regional quick-service suppliers leveraging standardized modular formats, and protective packaging specialists serving electronics and automotive tier-one vendors. Dominant competitive moves include geographic expansion through regional manufacturing partnerships and portfolio diversification into vibration-resistant industrial grades.
Among Nordic integrated manufacturers, Huhtamaki Oyj and Brødrene Hartmann A/S exemplify the captive pulp archetype with European manufacturing footprints. Sonoco Products Company anchors the protective packaging vector, extending tray designs into automotive component shipping where vibration resistance commands premium positioning. These three occupy positions across the food service and industrial protective segments without overlapping core customer bases.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Brødrene Hartmann A/S |
| Sonoco Products Company |
| UFP Technologies Inc. |
| Pactiv Evergreen |
| Genpak LLC |
| Sabert Corporation |
| Keiding, Inc. |
| ESCO Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Scandinavian pulp producers anchor supply discipline through captive fiber operations, translating upstream control into pricing power that independent tray converters cannot match. This ownership pattern tightens margin structures for non-integrated competitors while reinforcing premium positioning for backward-linked specialists serving German quick-service chains.
Pricing Analysis
Cost compression in standard-grade food service trays accelerates as bagasse pulp availability expands beyond traditional sugarcane regions. Three-tier pricing structure across premium compostable, standard recyclable, and economy non-certified levels separates buyers by certification tier and volume commitment. Pricing pressure stems from EU F-Gas Regulation compliance costs that force barrier coating reformulation. Quick-service restaurant chains exhibit highest price sensitivity, while electronics manufacturers prioritize sustainability scorecard compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in the Netherlands and United Kingdom compress lead times for dry-molded fiber pilot programs. Manufacturing concentrates in Sweden, Finland, and Germany where captive pulp operations feed thermoforming facilities. Raw material inputs draw from post-consumer recycled paper, bagasse agricultural residue, and bamboo fiber streams. Single-source vulnerability runs through Scandinavian pulp supply concentration. Distribution runs through pan-European food service distributors and direct automotive tier-one contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation constructs a cost-of-compliance moat that favors incumbents with certified recycled content pathways and EFSA-reviewed barrier coating investments.
For Market Incumbents: Lock in captive pulp supply through long-term offtake agreements with Scandinavian fiber producers before independent competitors secure equivalent access. Deepen thermoforming expertise in vibration-resistant grades to defend automotive positioning against polymer foam substitutes. Prioritize EN 13432 certification investment as German supermarket chains demand third-party verification ahead of neighboring markets. For New Entrants and Emerging Players: Launch via dry-molded fiber processing partnerships with United Kingdom food service distributors seeking localized production to reduce transport emissions. Target electronics protective packaging in China and Vietnam where retailer sustainability scorecards displace traditional procurement criteria. Penetrate through custom-fit insert designs for smartphone and laptop manufacturers reconfiguring supply chains for Amazon and Apple qualification. For Investors and Strategic Acquirers: Accelerated R&D spending on polysaccharide barrier coatings is the leading indicator that compostable-grade specialists will capture premium positioning as fluorinated treatments phase out. Five-to-ten year viability favors integrated pulp-to-tray manufacturers with European manufacturing footprints. Acquisition target archetype: mid-cap thermoforming specialists with automotive vibration-resistant expertise and pending EFSA food contact approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Supply | Scandinavian fiber control secures cost-competitive raw material access against independent converters. |
| EFSA-Reviewed Barrier Coating Certification | Compostable grease resistance approvals unlock German quick-service restaurant procurement volumes. |
| Automotive Vibration-Resistant Grade Development | Premium positioning in German and Japanese just-in-time supply chains commands price premiums. |
| Dry-Molded Fiber Regional Manufacturing | United Kingdom and Netherlands pilots reduce transport emissions and inventory carrying costs. |
| Electronics Sustainability Scorecard Alignment | Amazon and Apple vendor qualification requirements displace foam procurement in China and Vietnam. |
Study Parameters
Multi-period observation of EU regulatory compliance timelines, quick-service restaurant procurement shifts, and electronics manufacturer packaging reconfigurations anchored the trend analysis, supplemented by interviews with plant managers at thermoforming facilities, procurement leads at German supermarket chains, sustainability officers at North American food service operators, and technical R&D directors at barrier coating suppliers. Secondary validation drew from EFSA food contact notifications, EU Packaging and Packaging Waste Regulation implementation documents, FDA food contact substance inventories, and customs trade data on molded fiber imports. Bottom-up shipment data triangulated against top-down market sizing across material, product type, and end-use dimensions.
Segment-weighting approaches distributed volume and value across recycled paper, bagasse, bamboo, and virgin fiber material tiers, combined with trays, clamshells, inserts, and containers product configurations, and food service, electronics, automotive, and retail end-use sectors. CAGRs were derived from regression analysis of historical shipment patterns and forward projection of regulatory mandate compliance curves. Forecast inputs included EU F-Gas Regulation phase-out schedules for fluorinated treatments and retailer sustainability scorecard adoption timelines across the projection horizon.
Regulatory delay, composting infrastructure buildout failure, and barrier coating performance shortfalls are the dominant revision risks that could compress or extend modeled adoption curves. Forecasts reflect documented assumptions regarding compliance timelines and substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Fibreglass Trays Market