
 Europe Molded Pulp Packaging Market | 2026-2036
Europe Molded Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molded Pulp Packaging Market Intelligence
Supermarket private-label supply chains are reshaping how molded pulp packaging reaches European consumers. Huhtamaki Oyj leverages its broad converting footprint to supply major retail banners across Nordic and Central European markets. Stora Enso anchors demand through its integrated pulp-to-package model, controlling fiber sourcing from Nordic forests. Brodrene Hartmann differentiates via specialized egg and fruit tray production that dominates Northern European agricultural logistics.
Molded pulp packaging consists of pressed cellulose fibers formed into rigid, three-dimensional shapes through vacuum thermoforming or press-molding processes, typically achieving wall thicknesses of 0.8 to 3.0 millimeters for structural protection. The material serves primarily as a shock-absorbing, compostable alternative to expanded polystyrene and plastic trays in food transit and consumer goods distribution. Trays command the largest product volume given their ubiquity in protein, produce, and dairy retailing, while clamshells represent the fastest-expanding category as berry and organic snack brands abandon plastic hinged containers. Recycled fiber formulations lead material usage due to cost parity with virgin alternatives and alignment with retailer sustainability commitments, though plant-based fiber blends are gaining traction in premium cosmetic and electronics applications where surface smoothness matters.
EMA, ECHA, and the EU Green Deal collectively determine what materials enter European packaging streams, with REACH restricting certain chemical additives and the Packaging and Packaging Waste Regulation mandating recyclability thresholds that molded pulp satisfies inherently. The F-Gas Regulation indirectly supports fiber-based thermal insulation alternatives in cold-chain shipping. Stakeholders must monitor how the EU AI Act and impending digital product passport requirements reshape traceability obligations across multi-tier supply chains.
Market Dynamics
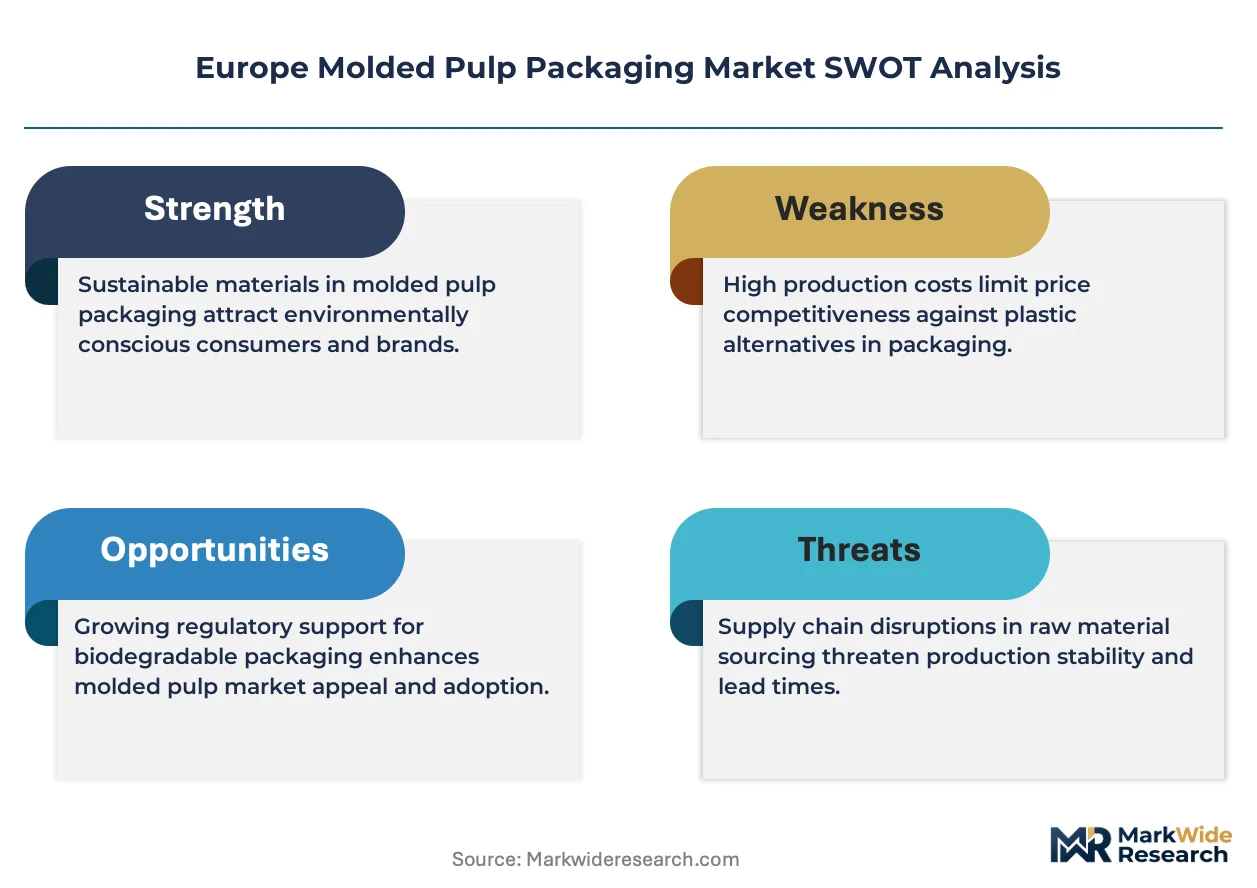
The EU Green Deal and Packaging and Packaging Waste Regulation are forcing food and beverage manufacturers to eliminate single-use plastics, creating immediate substitution demand for molded pulp trays and clamshells across European supermarket supply chains.
Growth Catalysts
- REACH compliance pressure:Chemical restrictions on plastic additives accelerate brand migration to fiber-based alternatives in fresh produce retailing.
- German supermarket chains:Aldi, Lidl, and Rewe have mandated plastic reduction timelines that directly convert shelf space to molded pulp egg and fruit trays.
- Thermoforming automation:Advanced vacuum-forming equipment cuts cycle times and enables thinner-wall designs that reduce fiber input costs.
Market Restraints
- Nordic pulp concentration:Stora Enso and limited Nordic suppliers control virgin fiber supply, creating price volatility risk during harvest disruptions.
- Barrier coating limitations:Current water-resistant coatings fail hot-fill liquid applications above 85 degrees Celsius, excluding soups and sauces.
- Expanded polystyrene residual demand:Cold-chain logistics providers in Eastern Europe still specify EPS for thermal performance in frozen meat distribution.
Strategic Opportunities
- Polish and Romanian retail modernization:Discount chains are expanding molded pulp adoption as they align with Western European sustainability standards.
- Cosmetic premium packaging:Plant-based fiber blends with smoothed surfaces capture gift-set and skincare markets abandoning plastic inserts.
- EU AI Act traceability:Digital product passport requirements favor molded pulp's inherent recyclability and fiber-source transparency.
Industry Challenges
- Mold design engineering shortage:European converters lack sufficient tool-and-die specialists capable of rapid prototype-to-production cycles for custom clamshell geometries.
- Composting infrastructure fragmentation:Industrial composting facility availability varies dramatically between Netherlands density and Southern European gaps, complicating end-of-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molded Pulp Packaging Market |
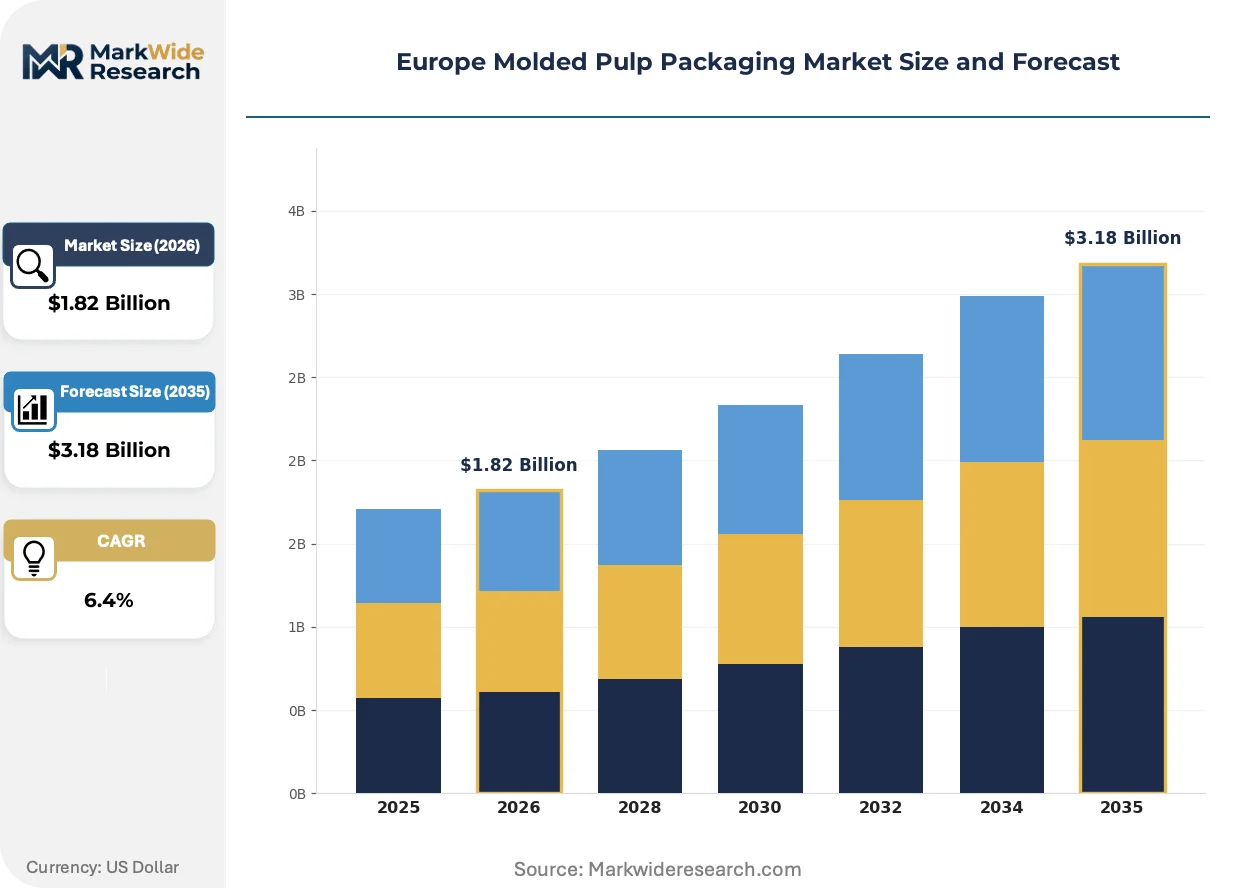
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Containers, Inserts End User: Food & Beverage, Electronics, Healthcare, Cosmetics Application: Packaging, Shipping, Display, Storage Material Type: Recycled Fiber, Virgin Fiber, Biodegradable Additives, Plant-Based Fibers |
| Companies Covered | PAPACKS Sales GmbH, International Paper Company, Huhtamaki Oyj, KIEFEL GmbH, Pulp-Tec Limited, Brodrene Hartmann, Stora Enso, buhl-paperform GmbH, Omnipac Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molded Pulp Packaging Market Strategic Shifts & Innovations
Sensor-integrated quality control and barrier chemistry breakthroughs are compressing production cycles while expanding molded pulp into temperature-sensitive and premium cosmetic applications previously reserved for plastics.
Inline near-infrared spectroscopy is digitizing fiber consistency monitoring across thermoforming lines, enabling real-time moisture and density adjustments that cut defect rates. Dutch tray converters deploy these systems to meet supermarket tolerance specifications for automated packaging machinery. The technology is digitizing quality assurance labor out of mid-scale production facilities.
The EU F-Gas Regulation restricts hydrofluorocarbon use in cold-chain insulation, indirectly accelerating fiber-based thermal packaging development for pharmaceutical and fresh food distribution. Manufacturers reformulate molded pulp with bio-based aerogel interlayers to match EPS thermal performance. Northern European logistics corridors between Rotterdam and Hamburg show fastest adoption of these hybrid insulated shippers.
Supermarket private-label procurement teams now mandate mold-in barcode and RFID integration for supply chain traceability, displacing secondary labeling operations. Berry and organic snack brands specify these features for inventory accuracy in automated warehouse environments. French and German retail banners lead this specification shift, pressuring converters to retool for direct-part-marking capability.
Europe Molded Pulp Packaging Market Segmentation
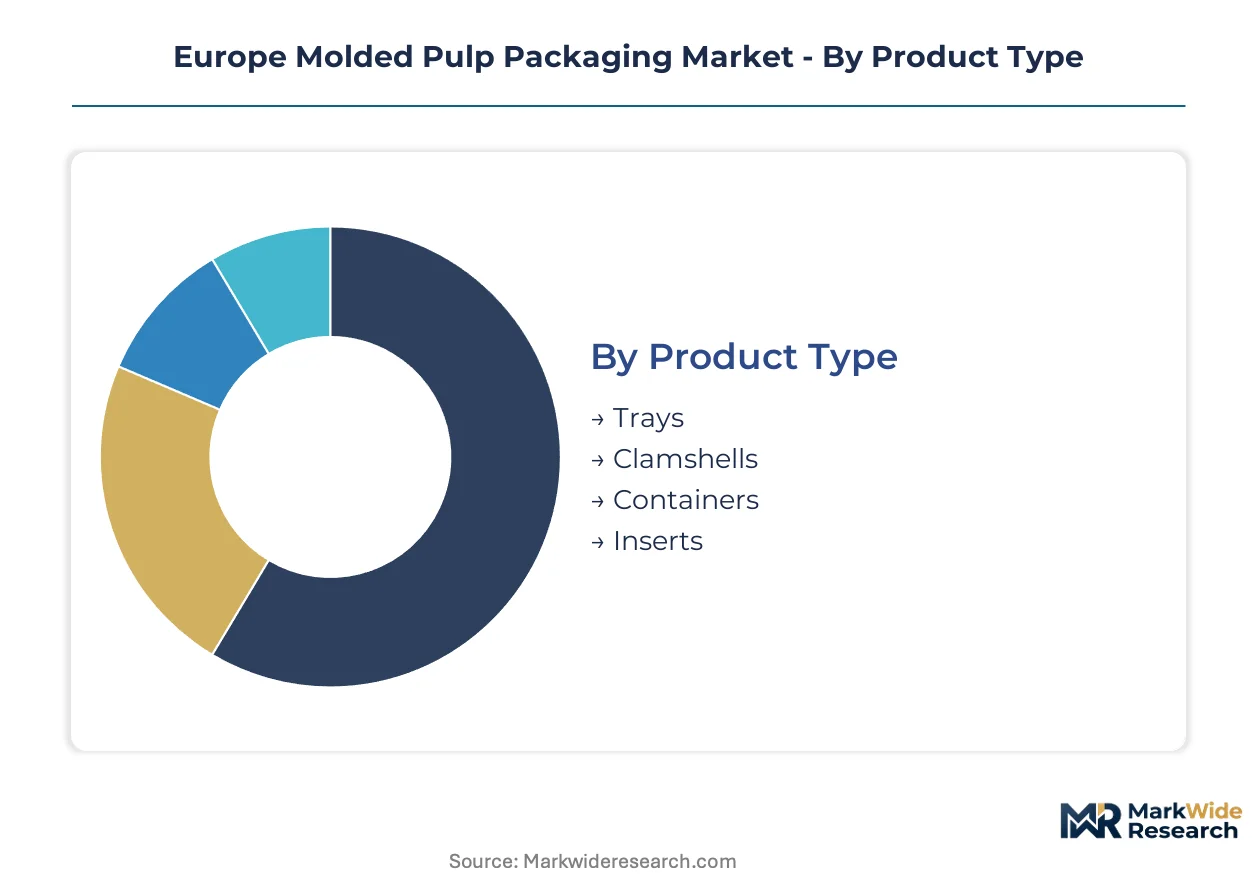
Segmentation in molded pulp packaging reveals how fiber-based solutions penetrate distinct value chains with varying technical requirements. Product geometry, end-use specifications, and material formulations each create separate competitive arenas with unique margin profiles and regulatory exposures.
Product Type:
Mature formats dominate current volume while emerging geometries reshape growth trajectories across European retail channels.
- Trays:Pressed cellulose structures with 0.8 to 3.0 millimeter wall thickness provide structural protection for protein, produce, and dairy retailing. German supermarket chains Aldi, Lidl, and Rewe mandate these for egg and fruit categories under plastic reduction timelines. Trays retain volume leadership; clamshells hold the steepest expansion curve.
- Clamshells:Hinged fiber containers with integrated locking mechanisms serve berry and organic snack brands abandoning plastic hinged containers. Berry producers in Netherlands and France specify these for automated warehouse compatibility with mold-in barcode integration.
- Containers:Deep-drawn fiber vessels with reinforced corners handle liquid and semi-liquid foodservice applications. Limited hot-fill capability above 85 degrees Celsius constrains soup and sauce adoption.
- Inserts:Custom-molded protective shapes nest inside outer boxes for electronics and cosmetic gift sets. Plant-based fiber blends with smoothed surfaces capture premium skincare markets.
Trays anchor current production volumes across Northern European agricultural logistics; clamshells are gaining share fastest as fresh produce retailers eliminate plastic hinged containers.
End User:
Customer-type concentration varies sharply by sustainability mandate intensity and supply chain automation level.
- Food & Beverage:Protein, produce, dairy, and ready-to-eat meal manufacturers drive absolute demand under EU Green Deal and Packaging and Packaging Waste Regulation compliance pressure. REACH restrictions on plastic additives accelerate brand migration to fiber-based alternatives.
- Electronics:Device manufacturers specify molded pulp for shock absorption and ESD protection in distribution. Premium unboxing experiences favor plant-based fiber blends with surface smoothness.
- Healthcare:Pharmaceutical distributors adopt fiber-based thermal packaging under F-Gas Regulation restrictions on hydrofluorocarbon insulation. Bio-based aerogel interlayers match EPS thermal performance for cold-chain shipping.
- Cosmetics:Skincare and gift-set brands abandon plastic inserts for compostable molded pulp with premium surface finishes. French and German retail banners lead specification shifts toward direct-part-marking capability.
Food and beverage commands absolute volume; cosmetics demonstrates the steepest margin expansion as premium positioning justifies higher fiber input costs.
Application:
Functional use cases span protective logistics through retail presentation with divergent performance requirements.
- Packaging:Primary and secondary containment for consumer goods at point of sale. Supermarket private-label procurement teams mandate RFID integration for supply chain traceability.
- Shipping:Protective dunnage and thermal insulation for distribution networks. Rotterdam-Hamburg logistics corridors show fastest adoption of hybrid insulated shippers.
- Display:Shelf-ready presentation units with printed branding surfaces. Automated packaging machinery tolerances drive quality specifications.
- Storage:Reusable or long-duration containment for agricultural and industrial goods. Composting infrastructure fragmentation complicates end-of-life claims in Southern Europe.
Packaging absorbs the dominant share of fiber throughput; shipping applications are climbing the fastest as cold-chain pharmaceutical distribution expands.
Material Type:
Cost-positioning and sustainability certification create tiered supply strategies across virgin, recycled, and bio-based inputs.
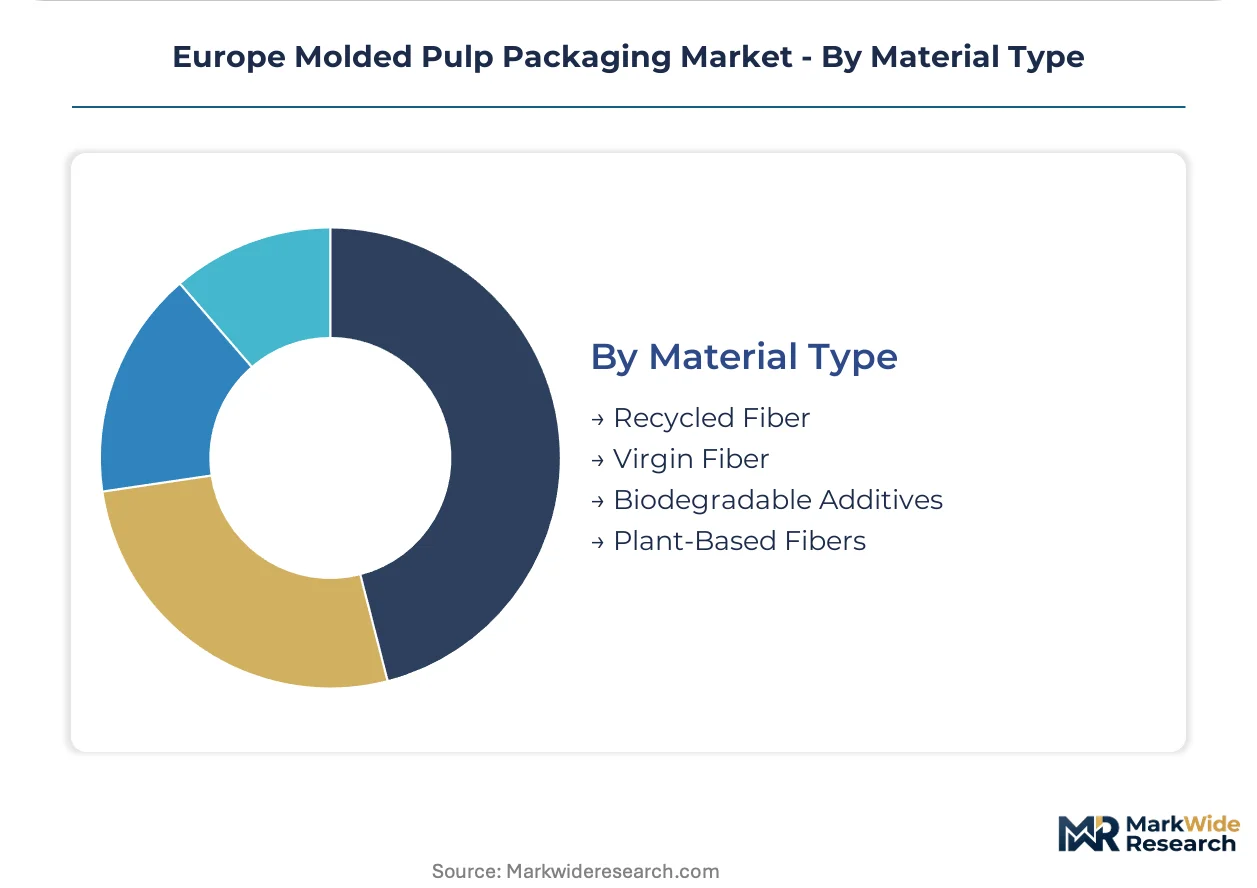
- Recycled Fiber:Post-consumer and post-industrial cellulose pulp achieves cost parity with virgin alternatives. Alignment with retailer sustainability commitments drives specification dominance.
- Virgin Fiber:Nordic softwood pulp delivers consistent fiber length and strength for thin-wall structural applications. Stora Enso and limited Nordic suppliers control supply, creating harvest-disruption price volatility.
- Biodegradable Additives:Compostability-enhancing compounds integrated during pulp slurry preparation. ECHA evaluation of additive safety profiles influences formulation choices.
- Plant-Based Fibers:Agricultural residues and non-wood cellulose sources for premium surface smoothness. Cosmetic and electronics applications favor these for tactile and visual properties.
Recycled fiber retains volume leadership due to cost structure and retailer commitments; plant-based fibers demonstrate the steepest expansion curve as premium positioning justifies input premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors regulatory momentum across the continent, with ECHA compliance requirements and national plastic reduction mandates creating differentiated adoption curves among member states.
Germany
Aldi, Lidl, and Rewe have mandated aggressive plastic reduction timelines that convert shelf space to molded pulp egg and fruit trays. The Packaging and Packaging Waste Regulation enforcement pressures converters to meet recyclability thresholds. Bavarian agricultural logistics clusters around Nuremberg and Munich show dense tray converter concentration serving Central European distribution networks.
France
French retail banners lead specification shifts toward mold-in barcode and RFID integration for automated warehouse compatibility. ANSM and CNIL guidance on digital product passports shapes traceability requirements for cosmetic and food applications. The Île-de-France region concentrates demand from Paris-based supermarket headquarters and luxury skincare brands abandoning plastic inserts.
Netherlands
Rotterdam-Hamburg logistics corridors demonstrate fastest adoption of hybrid insulated shippers as F-Gas Regulation restrictions displace hydrofluorocarbon thermal packaging. Dutch tray converters deploy inline near-infrared spectroscopy to meet supermarket tolerance specifications. Randstad industrial zones anchor thermoforming automation investment for thinner-wall designs.
Poland
Discount chain expansion drives molded pulp adoption as Polish retail modernizes toward Western European sustainability standards. EU cohesion funding supports packaging sector investment in compliance infrastructure. Warsaw and Łódź manufacturing zones attract converter capacity expansion serving Eastern European markets.
Sweden
Nordic forest fiber supply concentration creates harvest-disruption price volatility that shapes continental material sourcing strategies. Stora Enso's integrated pulp-to-package model controls fiber flow from Swedish and Finnish timberlands. Stockholm-based sustainability certification bodies influence retailer fiber-source transparency requirements across Northern Europe.
Europe Molded Pulp Packaging Market Key Industry Players
Integrated pulp producers and specialized converters split the market between captive fiber supply and agile customization capabilities. The vendor base concentrates around Nordic fiber control points and Central European converting clusters, with limited mid-scale independent players. Two archetypes dominate: forest-integrated multinationals with backward fiber control, and regional specialists with rapid prototyping expertise. Competitive moves center on thermoforming automation deployment and mold design engineering capacity acquisition.
Among Nordic forest-integrated players, Stora Enso and Huhtamaki Oyj exemplify the captive fiber archetype, while Brodrene Hartmann occupies a position within specialized agricultural packaging. German fabricators including PAPACKS Sales GmbH and buhl-paperform GmbH represent the precision-converting tier serving supermarket private-label procurement. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| PAPACKS Sales GmbH |
| International Paper Company |
| Huhtamaki Oyj |
| KIEFEL GmbH |
| Pulp-Tec Limited |
| Brodrene Hartmann |
| Stora Enso |
| buhl-paperform GmbH |
| Omnipac Group |
| Others |
Cost & Logistics Intelligence
Rotterdam thermoforming clusters anchor European molded pulp capacity, with converter density in Randstad industrial zones feeding downstream pricing leverage to German supermarket procurement teams at Aldi, Lidl, and Rewe. REACH compliance costs and Nordic pulp supply concentration create asymmetric cost structures that tier pricing across virgin fiber, recycled pulp, and premium plant-based formulations.
Pricing Analysis
Price spreads widen between Nordic virgin fiber and recycled pulp formulations as Stora Enso harvest disruptions trigger spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates plant-based cosmetic grades from agricultural trays and commodity egg packaging. Cost compression in standard-grade recycled pulp is intensifying because German discount chains mandate volume offtake at fixed contract rates. Private-label supermarket buyers exhibit highest price sensitivity; premium skincare brands tolerate input premiums for surface-finish specifications.
Supply Chain Analysis
EU F-Gas Regulation restrictions on hydrofluorocarbon thermal packaging limit cold-chain insulation alternatives, indirectly constraining molded pulp aerogel interlayer flows into pharmaceutical distribution. Fiber supply concentrates in Sweden, Finland, and Poland, with Nordic softwood pulp and Polish recycled paper streams feeding Central European converting clusters. Raw material dependencies rest on post-consumer cardboard collections, agricultural residue streams, and bio-based coating chemistries. Single-source vulnerability concentrates in Stora Enso's integrated pulp-to-package model controlling Nordic timberland access. Distribution runs through Rotterdam-Hamburg logistics corridors serving supermarket distribution centers and automated warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Packaging and Packaging Waste Regulation mandates recyclability thresholds that fiber-based packaging satisfies inherently, positioning molded pulp as the default substitution technology for banned single-use plastics across European food retail.
For Market Incumbents: Harden backward integration into Nordic pulp supply through long-term fiber offtake agreements with Stora Enso and Finnish timberland cooperatives. Acquire thermoforming automation capabilities in Randstad and Bavarian clusters to defend margin position against Polish cost competition. Prioritize mold design engineering talent retention as custom clamshell prototyping becomes the bottleneck capability. For New Entrants and Emerging Players: Build out barrier coating R&D partnerships with Dutch chemical specialists to unlock hot-fill liquid applications above 85 degrees Celsius, the largest unserved segment in European foodservice. Target Romanian and Bulgarian discount chain expansion as these markets modernize toward Western European sustainability standards. Pursue private-label supply contracts with supermarket procurement teams mandating mold-in RFID traceability as the go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized converters with rapid prototyping expertise over capital-intensive integrated pulp producers. Five-to-ten year viability hinges on composting infrastructure buildout across Southern Europe and barrier chemistry breakthroughs. Acquisition targets should demonstrate supermarket private-label relationships and thermoforming automation deployment. Watch EU AI Act digital product passport implementation timelines as the signal for traceability-driven specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoforming Automation Deployment | Rotterdam and Bavarian converters cut cycle times to meet Aldi and Lidl tolerance specifications. |
| Backward Integration into Nordic Fiber Supply | Long-term pulp offtake with Stora Enso hedges harvest-disruption price volatility risk. |
| Barrier Coating R&D Partnership | Dutch chemical collaboration unlocks hot-fill soup and sauce applications above 85 degrees Celsius. |
| RFID-Integrated Mold Design Capability | French and German retail banners mandate direct-part-marking for automated warehouse compatibility. |
| Eastern European Converter Capacity Expansion | Polish and Romanian manufacturing zones capture discount chain modernization toward EU Green Deal compliance. |
Research Approach
Operator-level perspectives from thermoforming plant managers, supermarket private-label procurement directors, barrier coating R&D specialists, and Nordic pulp supply planners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EU regulatory filings, ECHA additive safety evaluations, and trade data tracking fiber pulp flows through Rotterdam and Hamburg ports. Bottom-up capacity modeling across German, French, and Dutch converting clusters triangulated against top-down demand estimates from supermarket plastic reduction timeline disclosures.
Scenario-bracketing around EU Green Deal implementation pace, REACH enforcement intensity, and F-Gas Regulation displacement timelines framed the projection horizon. Segmentation dimensions modeled include product geometry, end-use industry, material formulation tier, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, supermarket mandate conversion rates, and cold-chain pharmaceutical distribution growth patterns.
Stress conditions across Nordic harvest yields, recycled pulp collection rates, and barrier coating approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about composting infrastructure rollout and digital product passport technical standards. Material shifts in EU AI Act traceability requirements or ECHA restrictions on biodegradable additives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Molded Fiber Trays Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market