
 Twin Neck Bottles Market | 2026-2036
Twin Neck Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Twin Neck Bottles Market Analytics
Pharmaceutical packaging is expanding as the dominant end-use vertical for twin neck bottles, displacing traditional single-neck formats in liquid medication dispensing. Berlin Packaging leverages its North American distribution network to sustain volume leadership in contract pharma packaging. Ancy Polymers anchors regional supply through specialized polyethylene compounding capabilities for dual-chamber designs. The Cary Company competes via extensive catalog breadth across closure configurations and fill volumes.
Twin neck bottles are dual-compartment containers featuring two separate neck openings with independent closure systems, typically molded from high-density polyethylene or polyethylene terephthalate to enable sequential or proportional dispensing of distinct liquid components. Blow molding with in-mold labeling achieves the precise chamber wall thickness required for chemical stability and leak resistance across pharmaceutical and agrochemical applications. Plastic material variants lead unit volume due to cost efficiency and shatter resistance, though glass maintains premium positioning in light-sensitive pharmaceutical formulations. Screw cap closures dominate installed base compatibility, while pump dispenser configurations represent the fastest-growing segment driven by measured-dose requirements in topical drug delivery.
FDA 21 CFR Part 211 cGMP regulations govern container closure integrity for pharmaceutical twin neck applications, while EMA Annex 1 sterile manufacturing guidelines influence barrier property specifications for multi-chamber designs. EPA FIFRA container regulations shape chemical-resistant material selection for agricultural twin neck packaging in the United States. Stakeholders must monitor evolving pharmacopeial extractables testing standards and state-level extended producer responsibility mandates to determine material and design investments.
Market Dynamics
Unit-dose pharmaceutical dispensing is compressing fill-volume requirements and forcing chamber miniaturization across twin neck bottle specifications. FDA extractables testing protocols and EMA Annex 1 sterile manufacturing guidelines are tightening material qualification timelines, extending new product introduction cycles by 8-14 months for multi-compartment formats.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Barrier property specifications for multi-chamber designs are accelerating adoption of high-performance polyethylene terephthalate in ophthalmic drug packaging across European formulation facilities.
- Ophthalmic therapy precision dosing:German procurement patterns for nasal and eye-drop applications are standardizing dual-chamber formats to eliminate dosing error liability in pediatric and geriatric patient populations.
- Blow molding with in-mold labeling:Chamber wall thickness precision below 0.3mm variation is enabling chemical stability claims that satisfy EPA FIFRA agricultural chemical resistance requirements.
Market Restraints
- High-density polyethylene resin volatility:Feedstock price swings tied to naphtha cracking economics compress margin predictability for converters serving agrochemical end-uses.
- Mold fabrication concentration:Precision dual-cavity blow mold production clusters in southern Germany and northern Italy, creating 14-18 week lead time exposure for North American bottle manufacturers.
- Glass substitution in light-sensitive segments:Amber borosilicate vials retain premium positioning for photostable biologics, capping polyethylene penetration in high-value pharmaceutical tiers.
Strategic Opportunities
- India CDSCO unit-dose registration pathway:Streamlined approval timelines for pre-filled dual-chamber containers are opening generic ophthalmic markets previously dominated by single-neck ampoules.
- Connected pump dispenser integration:Bluetooth-enabled dose-capture modules converging with twin neck chassis are creating adherence-data revenue streams in clinical trial supply chains.
- Direct-to-pharmacy distribution:Bypassing wholesale consolidation through hospital system captive procurement portals is capturing 12-15 point margin improvement for specialized bottle configurations.
Industry Challenges
- Extractables chemist scarcity:Qualified analytical personnel for FDA 21 CFR Part 211 container closure integrity validation are concentrated among three specialized contract laboratories, extending qualification timelines.
- Legacy ERP integration:Twin neck inventory tracking by chamber-specific lot codes requires reconfiguration of pharmaceutical manufacturer warehouse management systems, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twin Neck Bottles Market |
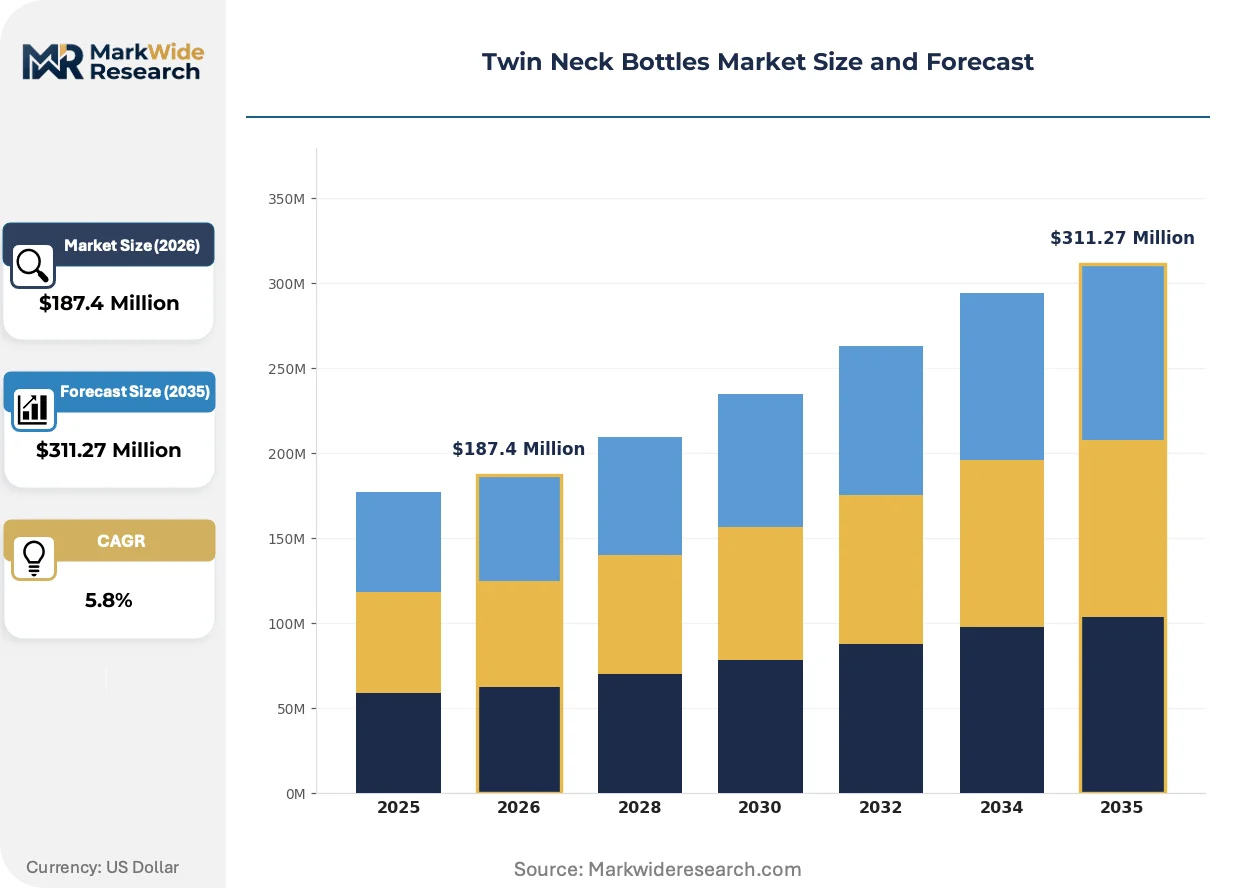
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Polyethylene, PET Closure Type: Screw Cap, Flip Top, Pump Dispenser, Cork Application: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Ancy Polymers, Pipeline Packaging, The Cary Company, U.S. Plastic Corp., O.Berk Company, Berlin Packaging, Illing Company, Tip-N-Measure, Container & Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twin Neck Bottles Market Evolving Landscape
Active pharmaceutical ingredient stability requirements are fragmenting chamber material specifications and accelerating multi-material co-injection development cycles. Sequential dispensing mechanisms are evolving from mechanical snap-separation to precision valve actuation, compressing user error rates in critical-dose therapies.
Digital printing with photoinitiator-free UV curing is decentralizing short-run label customization for clinical trial packaging. Contract research organizations in the United States and Switzerland are adopting digitally printed twin neck bottles with variable chamber volume markings to support adaptive trial designs. This capability is compressing minimum order quantities from 50,000 units to 2,500 units, enabling just-in-time supply for Phase II/III transitions.
REACH Annex XVII restrictions on certain phthalate plasticizers are forcing reformulation of flexible chamber seals in European pharmaceutical applications. ECHA substance evaluation workflows have classified three legacy seal compounds as Substances of Very High Concern, triggering substitution programs across German and French blow molding facilities. High-consistency silicone rubber compounds are capturing specification share in pediatric and parenteral-contact applications.
Hospital system consolidated procurement is compressing supplier rosters and elevating technical service requirements above unit pricing in vendor selection. Integrated delivery networks in the United States are mandating dedicated field engineering support for twin neck filling line integration, displacing catalog-based purchasing for volumes above 500,000 annual units. This behavioral shift is most visible in ophthalmic and respiratory therapy categories where line changeover complexity exceeds internal maintenance capabilities.
Twin Neck Bottles Market Segmentation
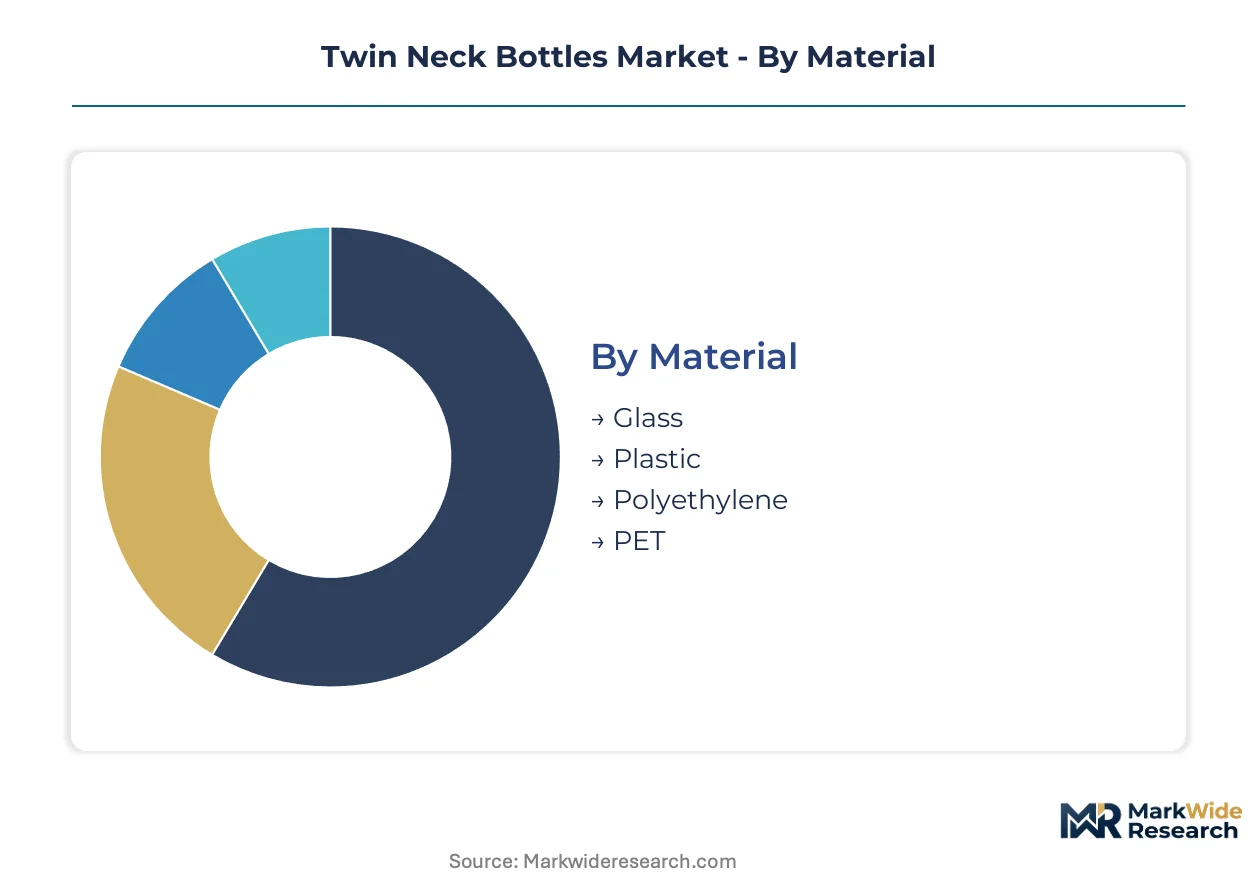
Twin neck bottle specifications fragment across material chemistry, closure mechanics, and end-use compliance requirements. Each segmentation axis carries distinct regulatory footprints and margin structures that determine converter investment priorities and customer procurement patterns.
Material:
Material selection governs barrier properties, chemical resistance, and sterilization compatibility across pharmaceutical and agrochemical applications.
- Plastic:High-density polyethylene dominates unit economics through blow-molding efficiency and shatter resistance. FDA 21 CFR Part 211 extractables testing requirements are compressing approved resin grades for ophthalmic drug contact applications.
- PET:Polyethylene terephthalate offers superior oxygen barrier performance and clarity for light-sensitive formulations. EMA Annex 1 sterile manufacturing guidelines are accelerating PET specification in European multi-chamber ophthalmic packaging.
- Glass:Amber borosilicate retains premium positioning for photostable biologics requiring inert contact surfaces and zero permeation.
- Polyethylene:Specialized HDPE and LDPE grades serve agrochemical resistance requirements under EPA FIFRA container regulations.
Plastic leads on scale; PET leads on momentum.
Closure Type:
Closure mechanisms determine dosing precision, user error rates, and line integration complexity for automated filling operations.
- Screw Cap:Threaded closure systems dominate installed base compatibility and retrofit economics across legacy pharmaceutical filling lines.
- Pump Dispenser:Metered-dose actuation mechanisms are expanding fastest in topical drug delivery. Bluetooth-enabled adherence tracking modules are converging with pump chassis in clinical trial supply chains.
- Flip Top:Hinged snap closures serve single-hand operation requirements in consumer health and veterinary applications.
- Cork:Natural and synthetic cork seals maintain niche positioning in premium beverage and specialty chemical segments.
Screw cap leads on scale; pump dispenser leads on momentum.
Application:
End-use verticals impose divergent stability, sterility, and labeling requirements that reshape chamber geometry and material stack specifications.
- Pharmaceuticals:Dual-chamber designs for sequential reconstitution of lyophilized drugs and diluents. Unit-dose precision requirements in Germany are standardizing twin neck formats for pediatric and geriatric ophthalmic therapies.
- Chemicals:Agricultural chemical resistance specifications under EPA FIFRA govern HDPE grade selection and wall thickness tolerances for pesticide and herbicide containment.
- Cosmetics:Premium skincare and haircare applications drive aesthetic surface finish requirements and custom color compounding.
- Food & Beverage:Dual-chamber packaging for oil-and-vinegar combinations and separated beverage components, constrained by FDA food contact notification timelines.
Pharmaceuticals leads on scale; chemicals leads on momentum.
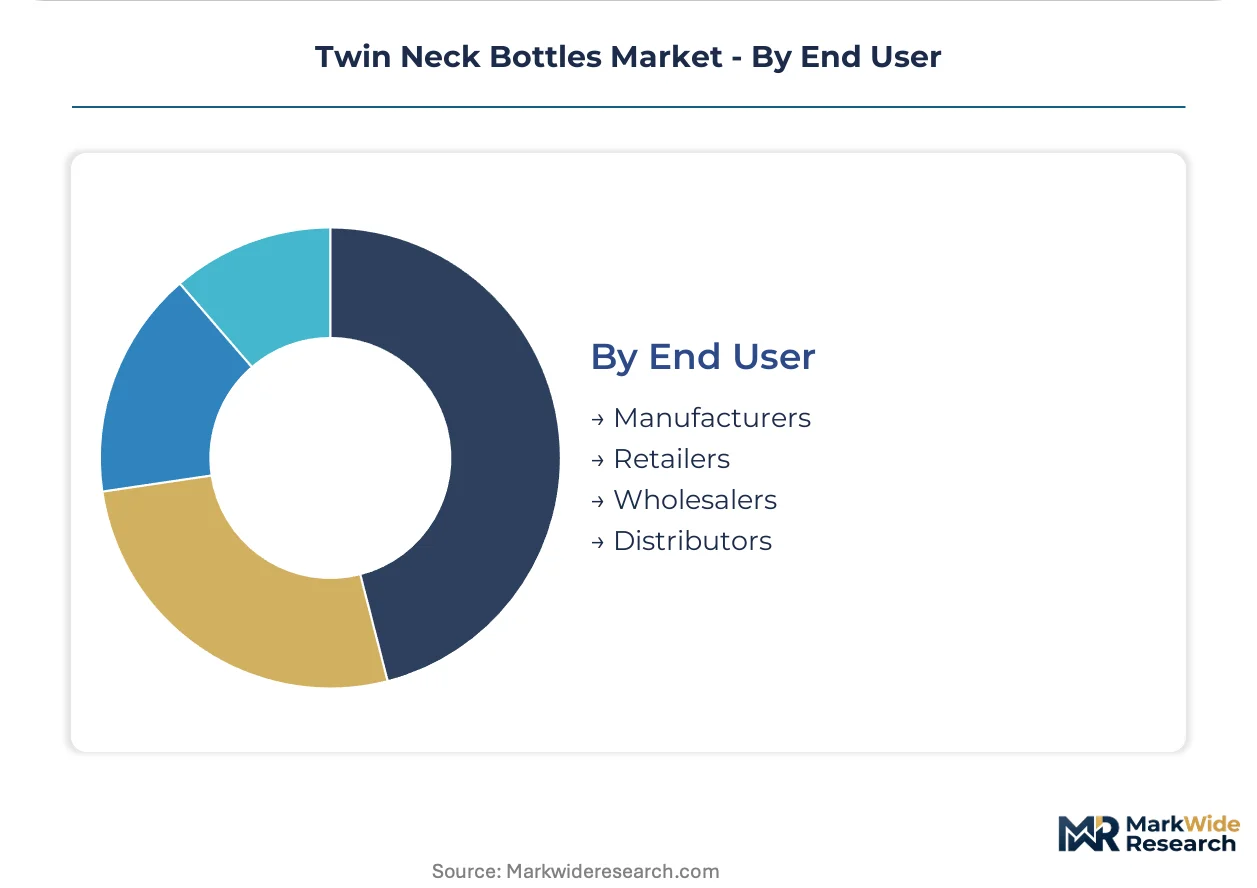
End User:
Channel position determines order scale, technical service intensity, and inventory management system integration requirements.
- Manufacturers:Pharmaceutical and agrochemical formulators drive specification authority through captive filling line investments and regulatory submission ownership.
- Distributors:Hospital system consolidated procurement portals are elevating technical service requirements above unit pricing for volumes above 500,000 annual units.
- Wholesalers:Inventory aggregation points face margin compression from direct-to-pharmacy distribution models bypassing traditional channel tiers.
- Retailers:Private label and store-brand cosmetics applications generate short-run, high-mix demand patterns served by digital printing capabilities.
Manufacturers leads on scale; distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision dosing applications in ophthalmic and nasal therapies anchor specialized twin neck bottle procurement patterns across the analysis window. Pharmaceutical packaging adoption concentrates in industrial clusters where unit-dose and dual-chamber dispensing formats satisfy tightening FDA and EMA stability-testing requirements.
United States
Contract pharma packaging volumes sustain North American demand leadership through Berlin Packaging's distribution network concentration. FDA 21 CFR Part 211 cGMP regulations govern container closure integrity validation timelines, compressing new product introduction cycles. Precision dual-cavity blow mold production lead times of 14-18 weeks create supply exposure for domestic bottle manufacturers serving agrochemical end-uses under EPA FIFRA container regulations.
Germany
Pediatric and geriatric ophthalmic therapy precision dosing standardizes dual-chamber formats to eliminate liability exposure. EMA Annex 1 sterile manufacturing guidelines accelerate high-performance polyethylene terephthalate specification in European multi-chamber ophthalmic packaging. Southern German mold fabrication clusters concentrate precision dual-cavity blow mold production, creating continental supply leverage.
India
CDSCO unit-dose registration pathway streamlines approval timelines for pre-filled dual-chamber containers in generic ophthalmic markets. Domestic pharmaceutical formulators drive specification authority through captive filling line investments and regulatory submission ownership. Mumbai-Pune pharmaceutical manufacturing corridors anchor regional procurement for specialized polyethylene compounding capabilities.
Switzerland
Contract research organizations adopt digitally printed twin neck bottles with variable chamber volume markings to support adaptive trial designs. Swissmedic pharmacopeial extractables testing standards influence barrier property specifications for multi-chamber designs. Basel-Zurich clinical trial supply chains compress minimum order quantities from 50,000 units to 2,500 units through decentralized short-run label customization.
France
REACH Annex XVII restrictions on phthalate plasticizers force reformulation of flexible chamber seals across blow molding facilities. ECHA substance evaluation workflows classify legacy seal compounds as Substances of Very High Concern, triggering substitution programs. Lyon-Paris pharmaceutical packaging corridors concentrate high-consistency silicone rubber compound specification share in pediatric and parenteral-contact applications.
Twin Neck Bottles Market Competitive Landscape
Capacity expansion dominates the current landscape as converters respond to EMA Annex 1 barrier property specification tightening and FDA extractables testing protocol extensions. The vendor base stratifies across three tiers: integrated packaging distributors with captive mold fabrication relationships, specialized polyethylene compounders serving dual-chamber designs, and regional catalog suppliers competing on closure configuration breadth. Strategic archetypes include North American volume leaders leveraging distribution density, European precision specialists exploiting southern Germany mold cluster proximity, and agile digital printing adopters capturing clinical trial short-run demand. M&A activity and geographic expansion represent the dominant competitive moves, with hospital system consolidated procurement elevating technical service requirements above unit pricing.
Within the integrated distribution tier, Berlin Packaging and The Cary Company exemplify divergent scale-positioning strategies. Berlin Packaging anchors North American contract pharma packaging through extensive distribution network coverage, while The Cary Company occupies a catalog-breadth position across closure configurations and fill volumes. Ancy Polymers represents the specialized compounder archetype, with regional supply anchoring through polyethylene compounding capabilities purpose-built for dual-chamber pharmaceutical designs.
| Leading Market Players |
|---|
| Ancy Polymers |
| Pipeline Packaging |
| The Cary Company |
| U.S. Plastic Corp. |
| O.Berk Company |
| Berlin Packaging |
| Illing Company |
| Tip-N-Measure |
| Container & Packaging |
| Others |
Value Network & Pricing Analysis
Pharmaceutical certification-grade divergence between FDA 21 CFR Part 211 validated formats and commodity agrochemical specifications manifests in both pricing premiums and sourcing geography. High-performance polyethylene terephthalate commands material cost premiums that compress converter margins in ophthalmic applications, while standard high-density polyethylene serves EPA FIFRA agricultural markets through distributed compounding networks.
Pricing Analysis
High-density polyethylene resin volatility passes through directly to agrochemical bottle converters, compressing margin predictability for southern Germany mold-dependent manufacturers. Three-tier pricing structure across pharmaceutical-validated, industrial-grade, and commodity agrochemical levels differentiates on extractables testing documentation and chamber wall precision. Pricing pressure stems from REACH Annex XVII seal reformulation costs in European pediatric applications. Agrochemical end-users exhibit highest price sensitivity, while pharmaceutical formulators prioritize barrier performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in Indian CDSCO registration pathways are reshaping sourcing toward Mumbai-Pune pharmaceutical corridors for unit-dose dual-chamber formats. Precision dual-cavity blow mold production concentrates in southern Germany and northern Italy, creating single-source vulnerability for North American bottle manufacturers. Raw material dependencies span Saudi naphtha feedstocks, Belgian polyethylene terephthalate resin grades, and Swiss high-consistency silicone rubber compounds. Distribution runs through hospital system consolidated procurement portals and direct-to-pharmacy captive channels, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
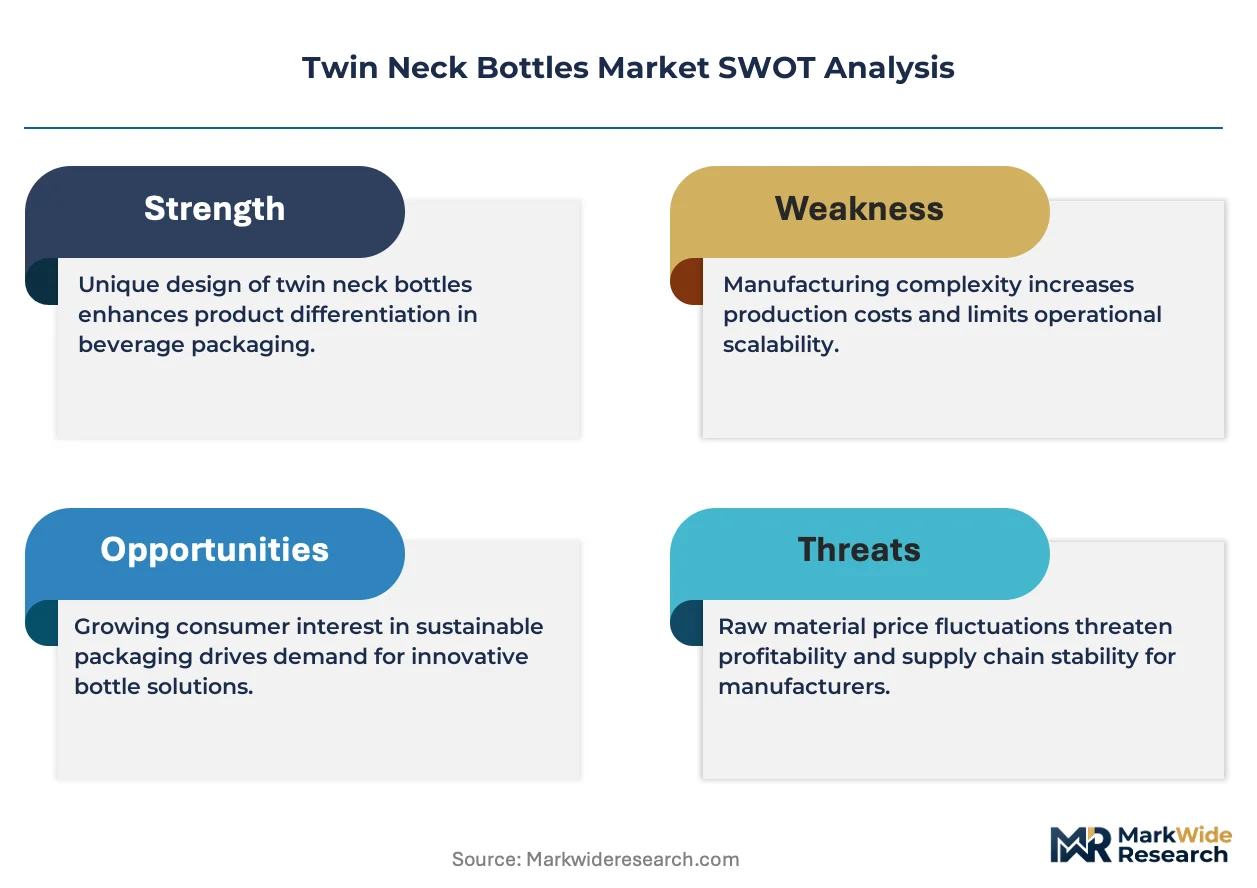
Twin neck bottles function as a stable compounder anchored by irreplaceable precision dosing requirements in pediatric and geriatric ophthalmic therapies, with regulatory validation timelines creating durable competitive moats.
For Market Incumbents: Anchor market position through backward integration into precision dual-cavity mold fabrication capabilities, reducing 14-18 week lead time exposure from southern German clusters. Defend against glass substitution in photostable biologics by investing in amber polyethylene terephthalate co-injection development. Prioritize certification maintenance for FDA 21 CFR Part 211 extractables testing protocols to sustain pharmaceutical pricing premiums.
For New Entrants and Emerging Players: Begin with digitally printed short-run clinical trial supply chains in Switzerland and the United States, where minimum order quantity compression from 50,000 to 2,500 units creates accessible entry points. Target generic ophthalmic markets in India through CDSCO streamlined registration pathways previously dominated by single-neck ampoules. Deploy connected pump dispenser integration with Bluetooth-enabled adherence modules as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where hospital system procurement portals elevate technical service requirements above unit pricing for volumes above 500,000 annual units. Long-term viability favors specialized polyethylene compounders with dual-chamber pharmaceutical design capabilities over catalog-based regional suppliers. Watch for EMA Annex 1 barrier specification tightening as inflection signal for high-performance polyethylene terephthalate capacity expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Mold Fabrication Integration | Captures southern Germany cluster proximity to compress pharmaceutical customer lead times. |
| Digital Printing Capability Deployment | Enables Swiss clinical trial adaptive designs through variable chamber volume markings. |
| High-Performance PET Capacity Expansion | Satisfies EMA Annex 1 sterile manufacturing barrier specifications in ophthalmic packaging. |
| Connected Pump Dispenser Development | Creates adherence-data revenue streams in Bluetooth-enabled clinical trial supply chains. |
| Direct-to-Pharmacy Distribution Buildout | Bypasses wholesale consolidation to capture margin improvement in specialized bottle configurations. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement managers, blow molding plant engineers, regulatory affairs specialists, and hospital system formulary directors grounded qualitative findings. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EMA Annex 1 sterile manufacturing guidelines, EPA FIFRA container regulations, REACH Annex XVII restriction databases, and customs trade data for polyethylene resin flows. Bottom-up volume modeling by material grade, closure type, and end-use application converged with top-down pharmaceutical packaging expenditure estimates.
Bottom-up modeling segmented twin neck bottle demand across plastic, polyethylene terephthalate, glass, and polyethylene material chemistry, with closure mechanics disaggregated by screw cap, pump dispenser, flip top, and cork configurations. Application-level granularity captured pharmaceutical, chemical, cosmetic, and food and beverage end-use verticals. CAGR derivation incorporated regulatory timeline impacts on new product introduction cycles, resin price volatility coefficients, and mold fabrication capacity constraints across the analysis window. Forecast inputs included CDSCO registration pathway throughput, ECHA substance evaluation workflows, and hospital system procurement portal adoption rates.
Several conditions sit outside the modeled scope, including unforeseen polymer science breakthroughs displacing multi-chamber mechanical designs, abrupt FDA extractables testing protocol revisions, and geopolitical disruptions to southern German mold fabrication clusters. Forecasts reflect documented assumptions regarding EMA Annex 1 implementation timelines and REACH substitution program completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
French Square Bottle Market