
 North America Molded Fiber Packaging Market | 2026-2036
North America Molded Fiber Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molded Fiber Packaging Market Analytics
Asset-light leasing arrangements for thermoforming equipment is narrowing the capital barrier for mid-tier converters entering molded fiber production. Sonoco Products Company leverages its integrated pulp-to-package infrastructure across multiple US states. Huhtamaki Oyj anchors its North American position through specialized foodservice tray capacity. Pactiv LLC competes via broad direct-sales relationships with institutional food buyers.
Molded fiber packaging consists of cellulose pulp slurry formed under heat and pressure into rigid, dimensionally stable containers, typically achieving wall thicknesses of 0.8–3.0 mm and moisture resistance through fluorochemical or PFAS-free barrier coatings; it serves primarily as a protective, nestable, and compostable alternative to expanded polystyrene and rigid plastics in food distribution and consumer goods logistics. Trays dominate volume in foodservice applications where stackability and grease resistance command premium positioning. Clamshells represent the fastest-expanding product category as quick-service chains adopt hinged-lid formats for delivery. Sustainable fiber materials capture widening margin pools as brand owners specify certified virgin and agricultural residue feedstocks for scope-three emissions reporting.
The EPA regulates pulp and paper mill effluent under Clean Water Act permits, while state-level extended producer responsibility frameworks in California and Oregon impose post-consumer recycled content thresholds on single-use food packaging. The US FDA maintains food-contact substance notification requirements for barrier coatings and additives in molded fiber articles. Stakeholders must monitor pending PFAS restrictions under state toxic substance laws and evaluate PFAS-free barrier chemistry investments before compliance deadlines tighten.
Market Dynamics
State-level PFAS prohibitions are compressing the timeline for barrier-coating substitution across US food packaging supply chains, forcing converters to accelerate capital deployment into fluorine-free chemistry platforms before enforcement windows close.
Growth Catalysts
- California SB 54 mandates:Extended producer responsibility thresholds for single-use foodware are compelling brand owners to specify molded fiber alternatives with certified recycled content.
- Quick-service delivery formats:Hinged-lid clamshell adoption by national restaurant chains is pulling demand for grease-resistant fiber structures with nested stackability.
- Agricultural residue feedstocks:Wheat straw and bagasse sourcing from the Central Valley is reducing scope-three emissions for processors reporting to California's climate disclosure frameworks.
Market Restraints
- Fluorochemical barrier dependency:Legacy PFAS-based grease resistance still dominates installed capacity, creating stranded asset risk as Maine and Washington enforcement dates approach.
- Pulp supply concentration:Virgin softwood kraft availability tightens around southeastern US mill corridors, exposing converters to input cost volatility from packaging-grade furnish competition.
- Performance gap in high-moisture applications:Current PFAS-free coatings exhibit shorter shelf stability for hot-filled liquid foods, limiting penetration into ready-meal segments.
Strategic Opportunities
- Texas and Florida foodservice growth corridors:Underpenetrated institutional catering markets in Sun Belt metro areas offer first-mover positioning for regional molded fiber tray capacity.
- Barrier-coating convergence:Integration of bio-based polymers with cellulosic substrates is enabling microwave-safe performance previously restricted to plastic alternatives.
- USDA BioPreferred procurement preference:Federal foodservice contract specifications are creating channel access for certified biobased packaging suppliers.
Industry Challenges
- PFAS-free formulation expertise:Shortage of polymer chemists with food-contact barrier development experience is extending R&D timelines for compliant coating systems.
- Thermoforming equipment reconfiguration:Legacy pulp molding lines require substantial capital modification to handle higher-density fiber slurries needed for premium structural performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molded Fiber Packaging Market |
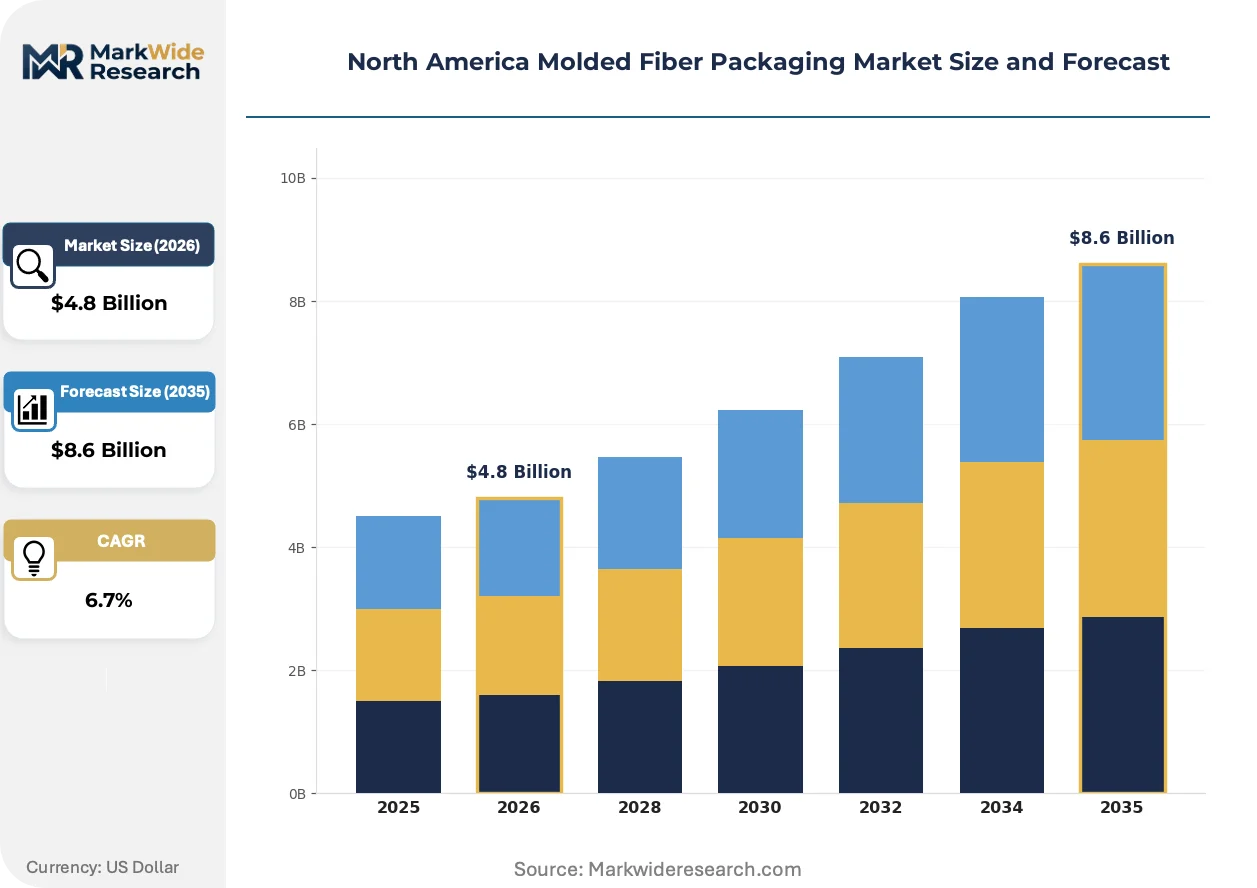
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Boxes, Clamshells, Inserts End User: Food Industry, Electronics, Consumer Goods, Healthcare Material: Sustainable Fiber, Recycled Paper, Natural Fibers, Biopolymers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Exporters |
| Companies Covered | Sonoco Products Company, UFP Technologies Inc., Brødrene Hartmann A/S, Pactiv LLC, Genpak LLC, Henry Molded Products Inc., Fabri-Kal, Huhtamaki Oyj, Keiding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molded Fiber Packaging Market Evolving Landscape
Barrier-coating chemistry is undergoing forced substitution as regulatory deadlines eliminate incumbent fluorochemical options, while equipment leasing models and agricultural residue processing reshape production economics.
PFAS-free barrier technologies are collapsing the performance-cost tradeoff that previously favored plastic alternatives in hot-food applications. Quick-service chains with delivery-centric menus are piloting these coatings at scale in California and Oregon markets. The transition is compressing margins for converters unable to secure qualified fluorine-free formulations before state enforcement phases begin.
EPA effluent guidelines under the Clean Water Act are tightening discharge limits for pulp and paper operations supplying molded fiber feedstock. Mills serving packaging-grade markets are investing in closed-loop water systems to maintain permit compliance. Southeastern US kraft pulp producers face the steepest capital burden from these revised standards.
Direct procurement relationships between institutional food buyers and molded fiber converters are displacing traditional distributor intermediaries in the K-12 and healthcare segments. Large district cooperatives in the Great Lakes region are consolidating purchasing through sole-source agreements with certified compostable suppliers. This channel compression rewards converters with integrated pulp-to-package capabilities and third-party compostability certification.
North America Molded Fiber Packaging Market Segmentation
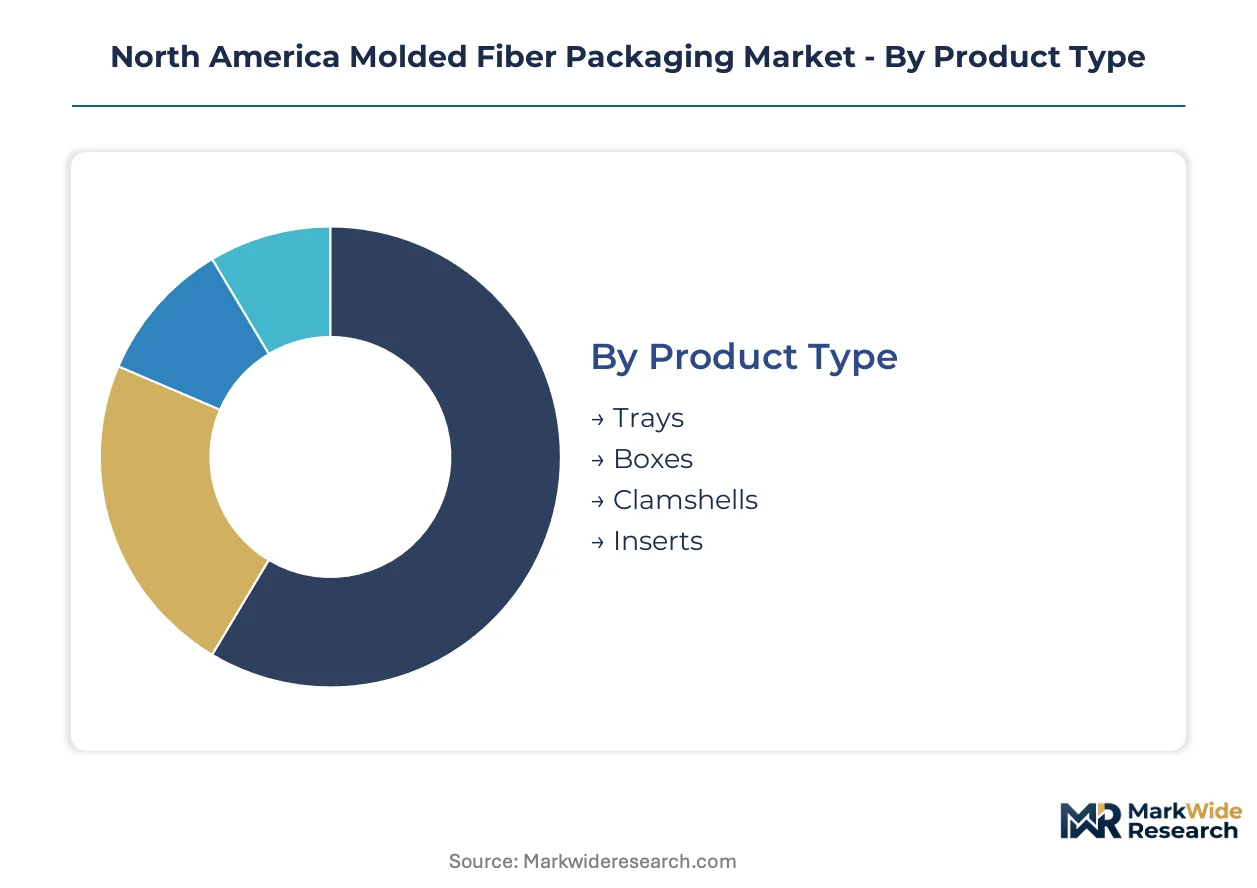
Segmentation in molded fiber packaging reveals how material specifications, end-use performance requirements, and channel economics create distinct competitive arenas. Each dimension shapes capital deployment decisions for converters navigating regulatory deadlines and customer certification demands.
Product Type:
Structural formats span protective cushioning through primary food-contact containers, with performance specifications tightening around grease resistance and nested density.
- Trays:Rectangular and round configurations with 0.8–2.5 mm wall thickness dominate institutional foodservice. California's agricultural processors specify these for produce distribution under compostability mandates.
- Clamshells:Hinged-lid designs with integral locking tabs serve quick-service delivery formats. National chains in Texas and Florida are standardizing these for hot-food transport, pulling investment into PFAS-free barrier coating lines.
- Boxes:Rigid corner-post structures protect electronics and consumer goods during e-commerce fulfillment. Demand concentrates around Great Lakes manufacturing corridors serving automotive parts distributors.
- Inserts:Custom-molded cavity designs nest products within outer corrugated shells. Electronics OEMs in Mexico's border maquiladoras specify these for device protection.
Established volume favors trays; emerging adoption favors clamshells.
End User:
Customer requirements diverge sharply between food-contact barrier specifications and industrial protective performance.
- Food Industry:Quick-service chains, institutional caterers, and agricultural processors require FDA-compliant food-contact substances with grease and moisture resistance. California SB 54 compliance is redirecting procurement toward certified recycled content.
- Electronics:OEMs and contract manufacturers demand electrostatic discharge protection and precision-fit cushioning. Mexican assembly plants near the US border drive cross-border supply chain integration.
- Consumer Goods:Cosmetics and personal care brands specify premium surface finishes for unboxing experiences. Direct-to-consumer brands are bypassing distributors for molded fiber primary packaging.
- Healthcare:Sterile barrier requirements and FDA device packaging regulations govern surgical kit trays and pharmaceutical distribution. Hospital consolidation in the Great Lakes region is compressing supplier bases.
Foodservice procurement commands the steepest compliance investment; electronics protective applications offer the most stable margin structure.
Material:
Feedstock selection determines scope-three emissions positioning and regulatory risk exposure across state toxic substance laws.
- Sustainable Fiber:Certified virgin softwood kraft and agricultural residues from California's Central Valley wheat straw operations. Brand owners reporting under California's climate disclosure frameworks specify these for emissions reduction.
- Recycled Paper:Post-consumer OCC and mixed paper furnish processed through deinking systems. Supply tightens around southeastern US mill corridors competing for packaging-grade recycled fiber.
- Natural Fibers:Bagasse from sugar processing and bamboo pulp alternatives. Mexican sugarcane operations supply North American converters seeking biogenic carbon credentials.
- Biopolymers:PLA and PHA blends integrated with cellulosic substrates for enhanced moisture barriers. USDA BioPreferred procurement preferences are opening federal foodservice contract channels.
Agricultural residue sourcing is climbing the fastest; recycled paper maintains cost-positioning dominance.
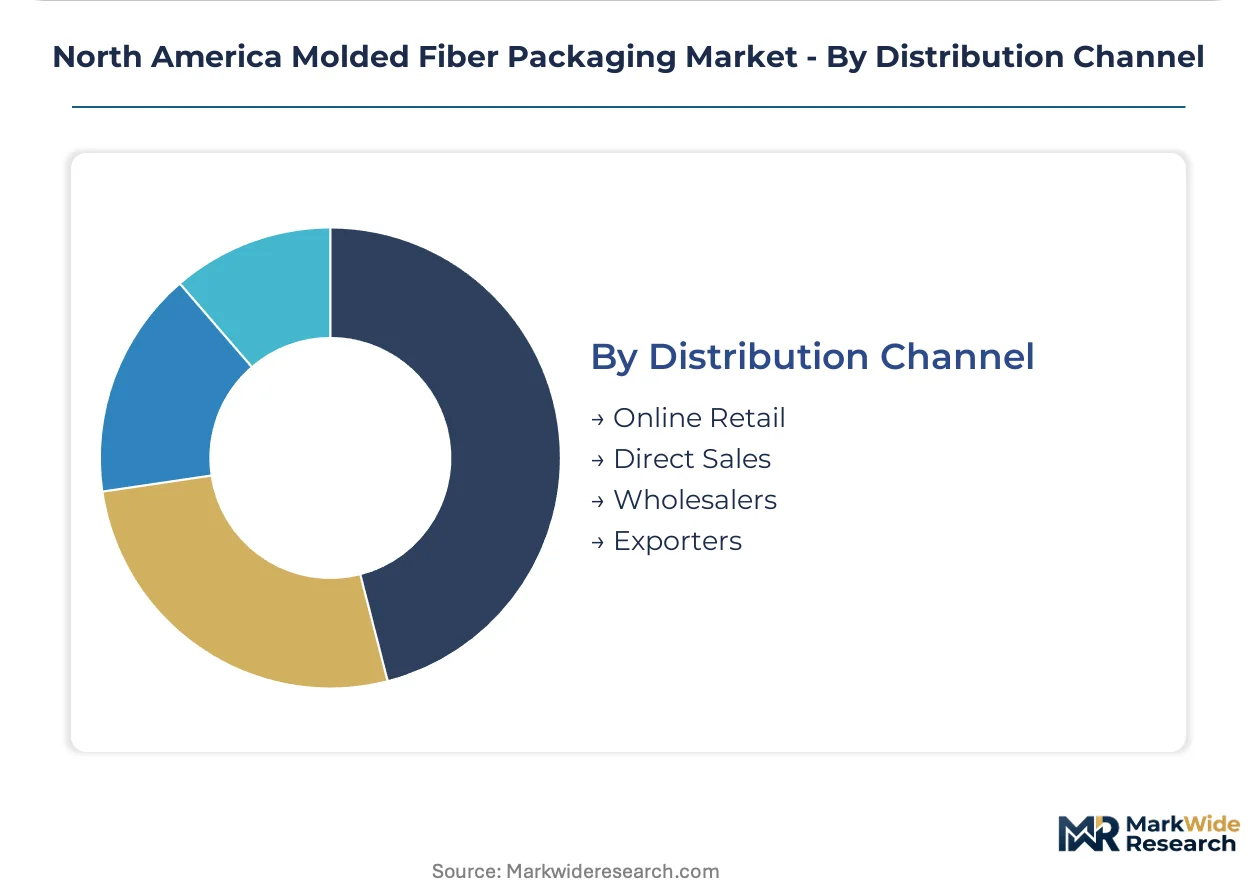
Distribution Channel:
Channel economics reflect customer scale, certification requirements, and geographic service intensity.
- Direct Sales:National account relationships with quick-service chains and institutional buyers. K-12 district cooperatives in the Great Lakes region are consolidating through sole-source agreements with certified compostable suppliers.
- Online Retail:E-commerce platforms serving small-batch food producers and specialty consumer brands. California-based sustainable packaging marketplaces are aggregating demand for certified products.
- Wholesalers:Distributor networks stocking standard tray and box dimensions for regional foodservice operators. Traditional intermediaries are losing share to direct procurement in healthcare and education segments.
- Exporters:Cross-border shipments to Canadian and Mexican manufacturing operations. USMCA trade compliance and harmonized food-contact regulations govern these flows.
Direct sales capture the highest margin accounts; online retail is expanding fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American molded fiber packaging trade flows reflect a net export position to Mexican manufacturing clusters and Canadian food processing operations, with US Gulf Coast ports handling rising containerized shipments of agricultural residue feedstocks.
United States
California's Central Valley agricultural processors drive residue-to-package demand under SB 54 mandates, while Texas quick-service chains expand clamshell procurement for Sun Belt delivery corridors. EPA Clean Water Act permits are tightening effluent limits on southeastern kraft pulp mills supplying packaging-grade furnish. Georgia and the Carolinas host concentrated thermoforming equipment lessors serving mid-tier converters.
Canada
Ontario's foodservice distributors are consolidating procurement through Health Canada-aligned compostability certifications for K-12 and healthcare segments. The country's national environmental regulator is harmonizing PFAS restrictions with US state timelines. Quebec pulp mills are retrofitting closed-loop water systems to maintain discharge permits under tightened federal standards.
Mexico
Border maquiladoras in Nuevo León and Tamaulipas specify molded fiber inserts for electronics OEMs under USMCA trade compliance. Mexico's federal consumer protection agency is aligning food-contact substance regulations with FDA notification requirements. Jalisco's sugarcane operations supply bagasse feedstock to North American converters seeking biogenic carbon credentials.
North America Molded Fiber Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pulp supply and barrier chemistry. The vendor base organizes around three strategic archetypes: integrated pulp-to-package operators with captive fiber supply, specialized foodservice converters with direct institutional relationships, and equipment-leasing platforms enabling mid-tier market entry. Dominant competitive moves include backward integration into agricultural residue processing and strategic partnerships with quick-service chains for co-developed delivery formats.
Among North American-based operators, Sonoco Products Company exemplifies the integrated archetype with multi-state pulp infrastructure, while Pactiv LLC occupies a position within the foodservice direct-sales tier. Huhtamaki Oyj anchors the specialized tray capacity segment. These three represent distinct competitive vectors: captive supply control, institutional channel density, and format-specific manufacturing scale.
| Leading Market Players |
|---|
| Sonoco Products Company |
| UFP Technologies Inc. |
| Brødrene Hartmann A/S |
| Pactiv LLC |
| Genpak LLC |
| Henry Molded Products Inc. |
| Fabri-Kal |
| Huhtamaki Oyj |
| Keiding Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in California's agricultural residue processing corridor is compelling converters to accept premium feedstock pricing while locking in multi-year supply contracts, tightening margins for non-integrated operators and accelerating consolidation among mid-tier thermoforming specialists.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifies across premium PFAS-free certified tiers, standard fluorochemical-coated formats, and economy-grade recycled fiber alternatives. Price differentiation rests on certification level under California SB 54 and USDA BioPreferred standards, plus volume scale for institutional foodservice accounts. Cost compression in standard tiers is intensifying because pulp furnish competition from packaging-grade markets has tightened southeastern US kraft supply. Quick-service chains with delivery-centric menus exhibit lowest price sensitivity; regional foodservice distributors face highest pressure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for agricultural residue processors supplying California Central Valley operations, squeezing working capital for independent converters. Geographic supply concentrates in the United States, Mexico, and Canada, with raw material dependencies on wheat straw, bagasse, and virgin softwood kraft pulp. Single-source vulnerability around PFAS-free barrier chemistry creates stranded asset risk as Maine and Washington enforcement deadlines approach. Distribution runs through direct sales relationships with national quick-service accounts and sole-source agreements with K-12 district cooperatives in the Great Lakes region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded fiber packaging sector is approaching a platform-economics inflection where PFAS-free barrier chemistry interoperability will determine which converters capture quick-service chain co-development relationships and which face exclusion from procurement shortlists.
For Market Incumbents: Build captive pulp supply moats through backward integration into Central Valley wheat straw processing and southeastern kraft mill partnerships. Incumbents must accelerate thermoforming equipment reconfiguration for higher-density fiber slurries before state PFAS enforcement windows close, defending against specialized foodservice converters with direct institutional relationships. For New Entrants and Emerging Players: Mid-market healthcare catering operations in Texas and Florida Sun Belt corridors represent the most penetrable entry point, with underdeveloped compostable packaging procurement and less consolidated supplier bases than California or Great Lakes markets. New entrants should pursue USDA BioPreferred certification as a go-to-market wedge for federal foodservice contract access. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pulp-to-package operators with multi-state fiber infrastructure and qualified PFAS-free coating partnerships, positioned for sustained viability as regulatory compliance costs reshape competitive economics. The signal to watch is quick-service chain pilot program announcements for hinged-lid clamshell formats in California and Oregon markets.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier Chemistry Scale-Up | Converters with qualified fluorine-free formulations capture quick-service chain procurement before state enforcement deadlines. |
| Agricultural Residue Processing Integration | Backward control over Central Valley wheat straw supply secures scope-three emissions positioning for brand owner reporting. |
| Thermoforming Equipment Leasing Platforms | Asset-light models narrow capital barriers for mid-tier converters entering molded fiber production in underpenetrated Sun Belt markets. |
| Direct Institutional Sales Consolidation | Sole-source agreements with K-12 district cooperatives displace traditional distributors and lock in volume commitments. |
| USDA BioPreferred Certification Investment | Federal foodservice contract specifications create channel access for certified biobased packaging suppliers. |
Research Methodology
A standing panel of pulp mill operations directors, thermoforming equipment lessors, quick-service chain procurement leads, and agricultural residue processors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against EPA Clean Water Act permit filings, FDA food-contact substance notifications, state toxic substance law registries, and SEC 10-K disclosures from packaging-grade pulp producers. Bottom-up volume modeling across product type, end user, material, and distribution channel dimensions triangulated with top-down macroeconomic sizing.
Scenario-bracketing around PFAS enforcement timelines, pulp furnish availability, and quick-service delivery format adoption shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format, end-use industry, feedstock type, and geographic procurement cluster. CAGRs were derived from regression analysis against historical substitution rates of plastic alternatives and projected regulatory compliance deadlines, with inputs from agricultural residue yield forecasts and thermoforming capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity pricing, freight logistics costs, or federal procurement policy would shift the trajectory. Forecasts reflect documented assumptions regarding state-level PFAS prohibition implementation schedules and brand owner scope-three emissions reporting adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Fiber Bale Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Molded Pulp Inserts Market