
 Garage Equipment Market | 2026-2036
Garage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Garage Equipment Market Analysis
Connected diagnostics and electrification-ready service tooling is fragmenting traditional garage equipment procurement patterns. Robert Bosch GmbH leverages its embedded sensor ecosystems to anchor premium diagnostic portfolios. Launch Tech Co., Ltd. competes aggressively on cost-optimized electric lift systems for emerging markets. Hunter Engineering Company specializes in precision alignment technology that sustains its position in high-throughput automotive workshops.
Garage equipment encompasses lifts, compressors, tools, and diagnostic apparatus engineered to rated load capacities, hydraulic pressure tolerances, and electromagnetic compatibility thresholds for commercial vehicle servicing. Lifts and diagnostic equipment command the deepest margin pools as fleet operators prioritize uptime-minimizing technologies; electric and hydraulic technologies diverge in growth trajectory, with electric systems gaining traction where energy efficiency regulations tighten. Automotive workshops and dealerships represent the most concentrated demand channel, while independent garages navigate compressed budgets across fragmented procurement patterns.
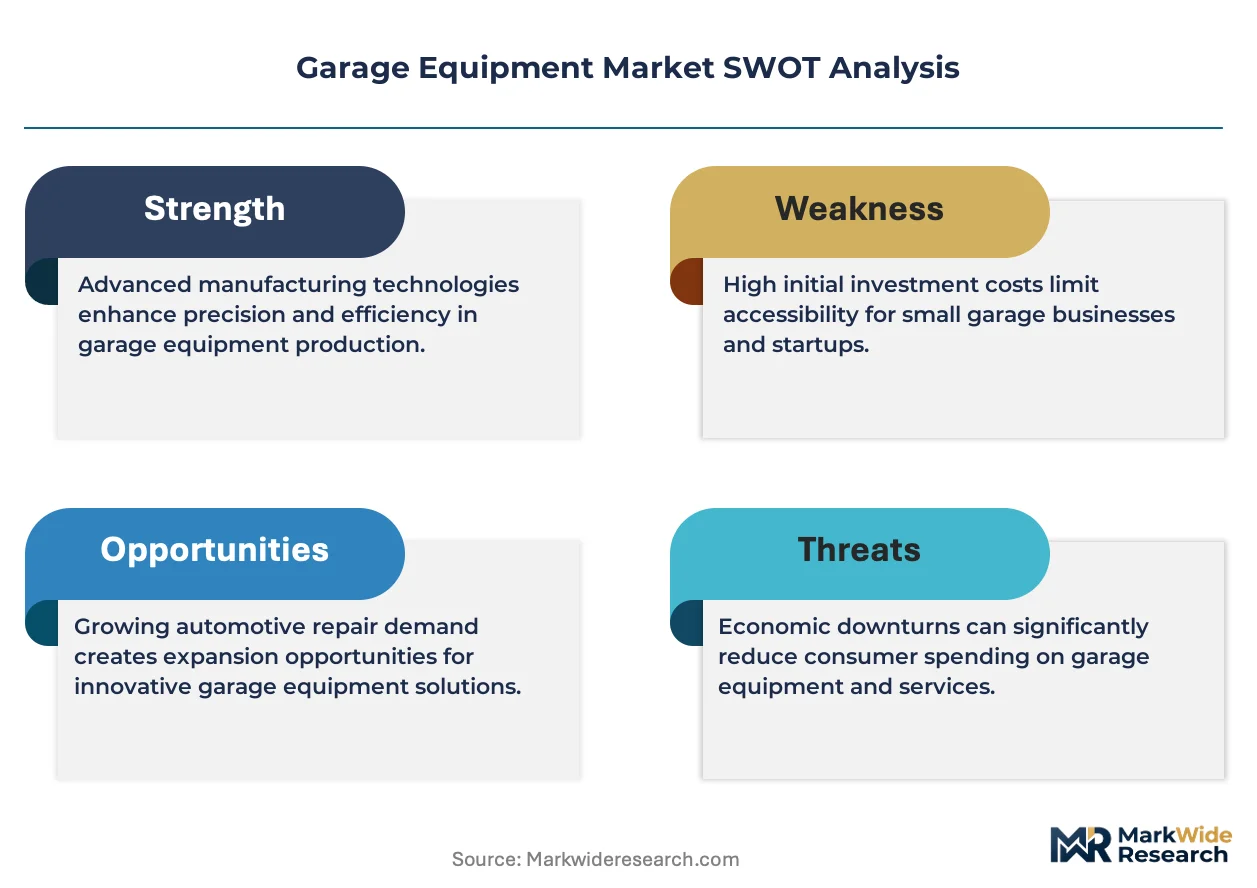
The US EPA enforces emissions compliance for equipment engines and refrigerant handling systems, while OSHA mandates workplace safety standards that directly influence lift design and shop layout requirements. The EU Machinery Directive and CE marking framework shape product access across European member states, compelling manufacturers to certify against harmonized health and safety benchmarks. Stakeholders must monitor how electrification servicing standards evolve across regulatory jurisdictions to anticipate tooling obsolescence cycles and capital replacement timelines.
Market Dynamics
Fleet electrification is compressing traditional equipment replacement cycles as commercial vehicle operators retrofit service bays for high-voltage battery servicing and thermal management diagnostics.
Growth Catalysts
- OSHA workplace safety mandates:Stricter lift certification requirements in the United States force garage operators toward premium hydraulic and electric lift replacements.
- Compressed natural gas and hydrogen fuel cell adoption:Alternative fuel infrastructure expansion across Texas and California creates specialized equipment demand for leak detection and high-pressure fuel system servicing.
- Embedded telematics integration:Real-time vehicle health monitoring systems now require compatible diagnostic benches that sync with OEM data protocols.
Market Restraints
- Steel and aluminum input volatility:Lift frame fabrication depends on commodity metal pricing that squeezes manufacturer margins unpredictably.
- Component supply concentration:Precision hydraulic pumps and certified load sensors concentrate among German and Japanese specialist suppliers.
- Refrigerant handling compliance friction:US EPA Section 608 technician certification requirements extend equipment procurement timelines for air conditioning service bays.
Strategic Opportunities
- India commercial vehicle aftermarket expansion:Rapid fleet growth in Maharashtra and Gujarat creates first-mover positioning for diagnostic equipment distributors establishing local service networks.
- EU Green Deal repairability mandates:Right-to-repair legislation accelerates demand for independent garage access to OEM-grade diagnostic tools previously restricted to dealerships.
- Mobile service unit convergence:Portable electric lifts and battery-powered compressors enable on-site fleet maintenance, collapsing the distinction between fixed and field service capabilities.
Industry Challenges
- High-voltage technician certification gaps:Electrified vehicle servicing requires specialized electrical safety training that outpaces vocational program output in most markets.
- Legacy diagnostic protocol fragmentation:Proprietary OEM software interfaces complicate universal scanner development and extend R&D cycles.
- CE marking documentation burdens:EU Machinery Directive compliance timelines delay product launches for mid-tier manufacturers lacking dedicated regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage Equipment Market |
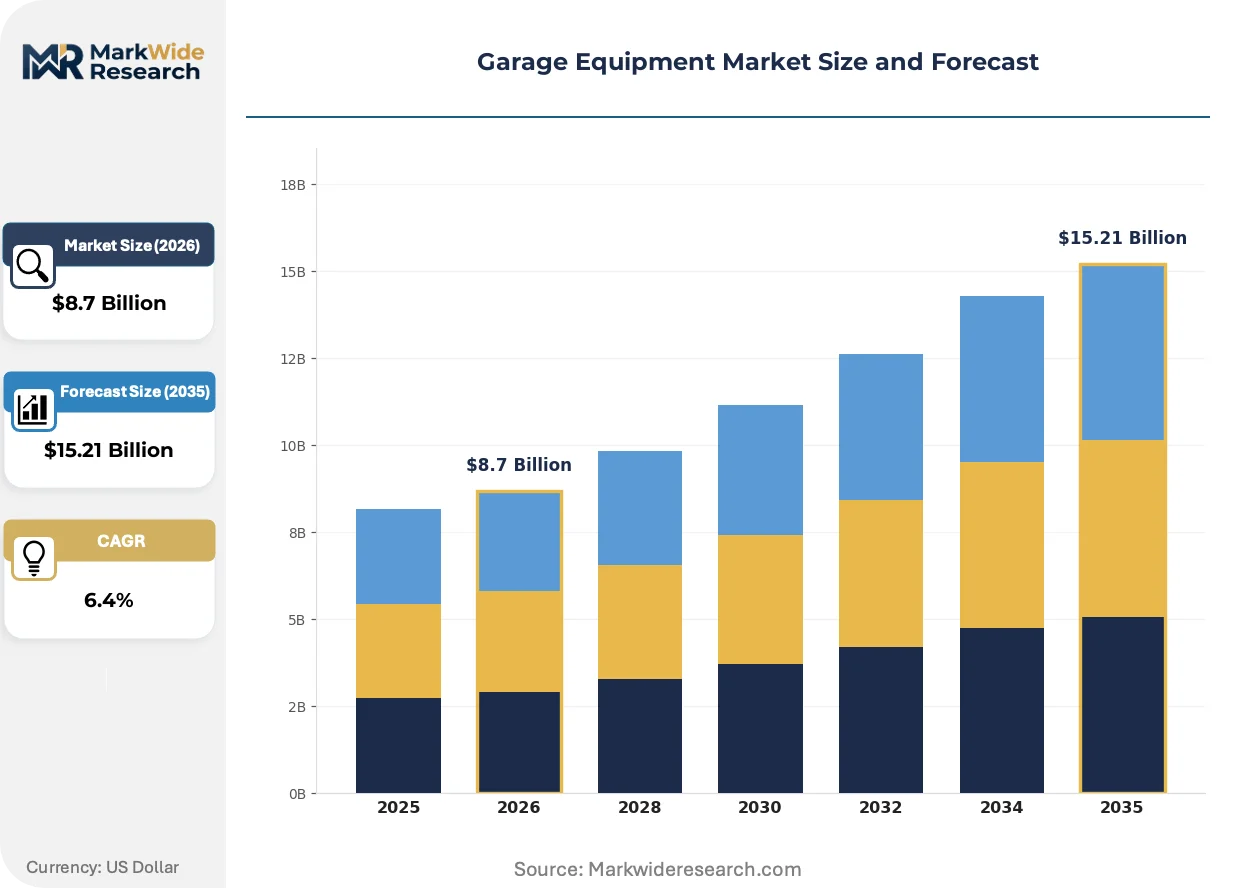
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lifts, Compressors, Tools, Diagnostic Equipment End User: Automotive Workshops, Fleet Maintenance, Independent Garages, Dealerships Technology: Hydraulic, Pneumatic, Electric, Mechanical Application: Repair, Maintenance, Inspection, Installation |
| Companies Covered | Hunter Engineering Company, MAHA Maschinenbau Haldenwang GmbH & Co. KG, Robert Bosch GmbH, Launch Tech Co., Ltd., Rotary Lift, Snap-on Incorporated, Vehicle Service Group, Nussbaum Automotive Solutions, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage Equipment Market Emerging Trajectories
Connected equipment architectures and predictive maintenance algorithms are redefining how garage operators justify capital expenditures and manage asset utilization.
Artificial intelligence-driven diagnostic inference is collapsing the expertise gap between veteran technicians and entry-level staff. Fleet maintenance departments in California now deploy machine learning-enabled fault code interpretation that reduces mean-time-to-repair by automating pattern recognition across historical service records. This compression of diagnostic labor requirements enables smaller garages to handle complex commercial vehicle repairs previously reserved for dealership service centers.
The US EPA's evolving refrigerant management rules under Section 608 now mandate leak detection rates below specific thresholds for systems handling hydrofluorocarbon alternatives. Equipment manufacturers must redesign recovery and recycling machines to meet these specifications, forcing R&D prioritization toward sensor miniaturization and real-time emissions quantification. Independent garages in Texas face the steepest compliance costs as they retrofit existing air conditioning service infrastructure.
Subscription-based tool access is displacing outright equipment ownership among fragmented independent garage networks. Tool distributors now offer diagnostic scanner leasing with bundled software update commitments, capturing recurring revenue from previously transactional relationships. This model penetrates fastest in metropolitan clusters where capital constraints and rapid technology obsolescence deter large upfront investments.
Garage Equipment Market Segmentation
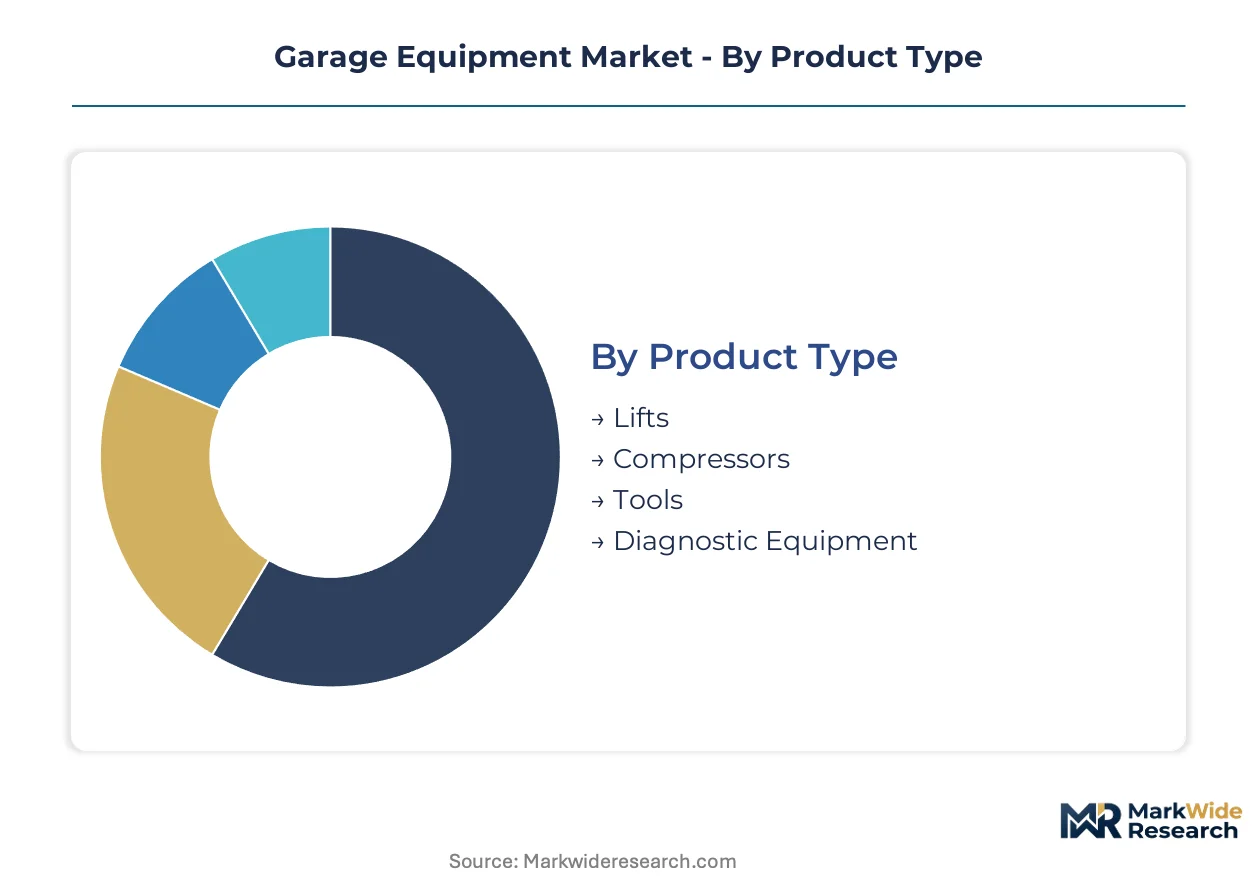
Garage equipment procurement patterns diverge sharply across product categories and end-use channels, with fleet operators prioritizing uptime-minimizing technologies while independent garages navigate capital constraints. Understanding these segment boundaries clarifies where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
After-sales-service intensity varies dramatically across equipment categories, with diagnostic systems requiring continuous software updates and calibration support while mechanical tools demand minimal post-sale engagement.
- Lifts:Two-post, four-post, and scissor configurations rated to specific load capacities anchor workshop infrastructure. Fleet maintenance operators in Texas and California prioritize electric lift systems where OSHA mandates and energy efficiency regulations tighten procurement specifications.
- Diagnostic Equipment:Embedded sensor arrays and protocol-compatible interfaces enable real-time fault interpretation. Demand concentrates among dealerships integrating OEM data streams, though EU Green Deal repairability mandates now expand independent garage access to previously restricted diagnostic capabilities.
- Compressors:Rotary screw and reciprocating units deliver compressed air for pneumatic tooling across service bays.
- Tools:Hand tools, power tools, and specialty servicing implements complete workshop equipment portfolios.
Lifts hold the largest share; momentum sits with diagnostic equipment.
End User:
Cost tier stratification separates capital-rich fleet operators from budget-constrained independents, with subscription-based tool access models penetrating fastest among fragmented garage networks.
- Fleet Maintenance:In-house service bay investments prioritize electrification-ready tooling and high-voltage battery servicing infrastructure. Commercial vehicle operators across California retrofit facilities for thermal management diagnostics as compressed natural gas and hydrogen fuel cell adoption accelerates.
- Dealerships:OEM-aligned service centers command proprietary diagnostic protocol access and manufacturer-certified training programs. Embedded telematics integration requirements now mandate compatible diagnostic benches that sync with factory data streams.
- Automotive Workshops:High-throughput independent facilities balance equipment capability against utilization rates.
- Independent Garages:Capital constraints and rapid technology obsolescence drive leasing preferences over outright ownership.
Fleet maintenance holds the largest share; independent garages are expanding most quickly through subscription-based equipment access.
Technology:
Volume distribution shifts as regulatory pressure and energy efficiency benchmarks displace legacy mechanical and pneumatic systems.
- Electric:Servo-motor and battery-powered systems deliver precision control with reduced energy consumption. Demand climbs where EPA emissions standards and state-level efficiency mandates constrain hydraulic equipment procurement.
- Hydraulic:Fluid-power systems maintain dominance in heavy-duty lifting applications despite electrification headwinds. German and Japanese precision pump suppliers concentrate critical component supply, creating procurement vulnerability for mid-tier lift manufacturers.
- Pneumatic:Compressed-air systems persist in high-torque fastening and surface preparation applications.
- Mechanical:Simple lever and screw mechanisms retain niche positioning in low-complexity service tasks.
Hydraulic technology holds the largest share; electric systems gain share fastest where regulatory pressure intensifies.
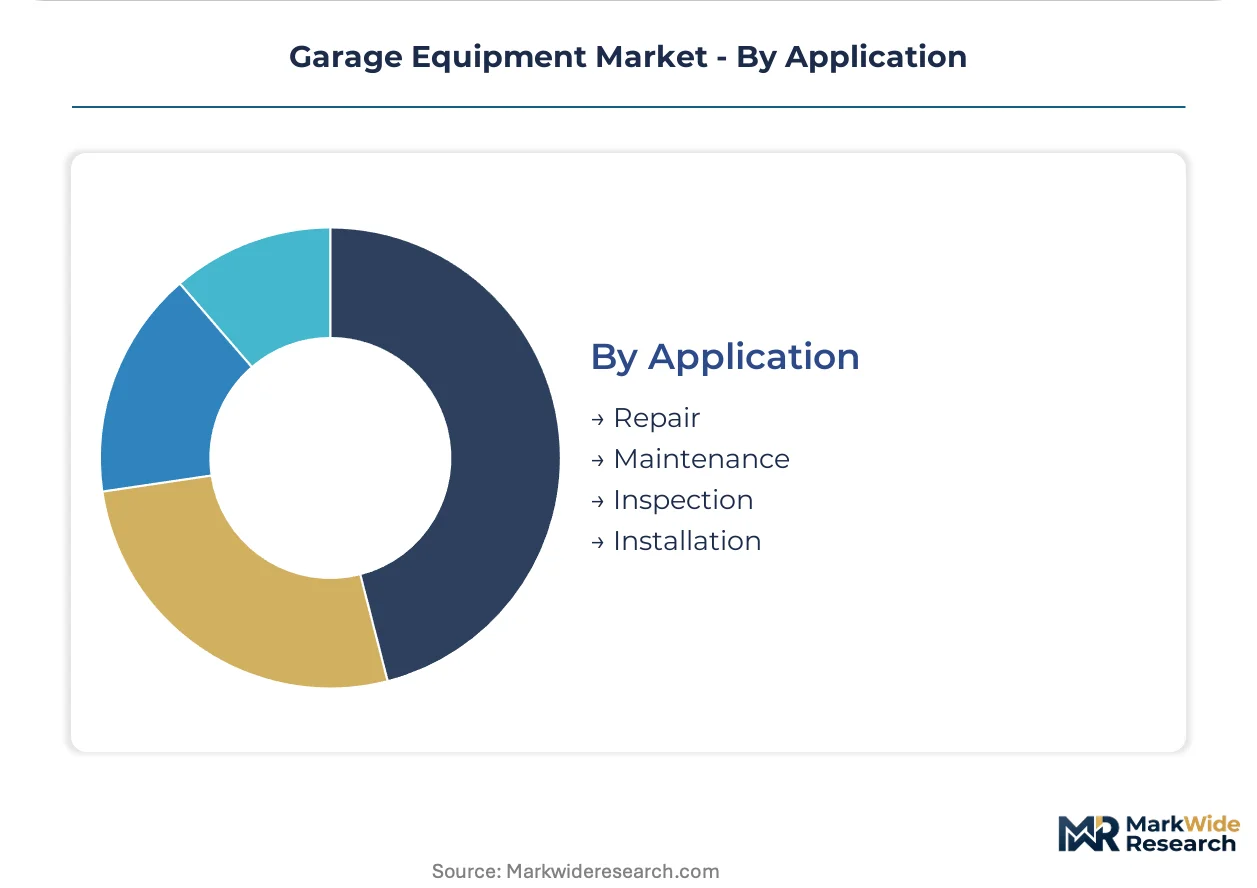
Application:
Customer type differentiation separates scheduled maintenance workflows from unscheduled repair events, with inspection applications gaining regulatory tailwinds.
- Repair:Corrective maintenance workflows address component failure and collision damage. AI-driven diagnostic inference now compresses mean-time-to-repair by automating pattern recognition across historical service records.
- Maintenance:Preventive servicing schedules prioritize uptime continuity for commercial vehicle operators. Predictive maintenance algorithms embedded in connected equipment architectures redefine capital justification and asset utilization management.
- Inspection:Regulatory compliance verification and safety certification procedures.
- Installation:Accessory fitment and system integration services.
Repair holds the largest share; inspection shows the steepest expansion trajectory as emissions and safety mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese precision component suppliers dominate upstream supply chains, while commercial vehicle fleet operators in the United States and emerging Asian markets drive equipment procurement volumes. Equipment flows concentrate from European and East Asian manufacturing centers toward North American and Indian aftermarket service networks.
United States
Commercial vehicle fleet operators in Texas and California retrofit service bays for compressed natural gas and hydrogen fuel cell infrastructure. OSHA workplace safety mandates tighten lift certification requirements, accelerating replacement cycles for hydraulic and electric systems. Houston and Los Angeles anchor the densest concentrations of fleet maintenance facilities.
Germany
Automotive OEM-aligned service centers demand diagnostic benches compatible with factory telematics protocols. CE marking requirements under the EU Machinery Directive shape product development timelines for equipment exports. Stuttgart and Munich host the highest densities of dealership service networks and precision component suppliers.
China
Domestic commercial vehicle production growth drives aftermarket equipment demand across provincial fleet operators. GB standards and MIIT regulations establish electromagnetic compatibility thresholds for diagnostic equipment manufacturing. The Yangtze River Delta cluster concentrates lift fabrication capacity serving both domestic and export markets.
India
Rapid commercial vehicle fleet expansion in Maharashtra and Gujarat creates first-mover opportunities for diagnostic equipment distributors. BIS certification requirements and state-level industrial policies influence import substitution strategies. Pune and Ahmedabad emerge as critical hubs for aftermarket service network development.
Japan
Precision hydraulic pump and certified load sensor suppliers concentrate among specialist manufacturers serving global lift OEMs. METI efficiency standards and JIS certification frameworks shape electric system development priorities. Nagoya and Osaka anchor the densest concentrations of component engineering expertise.
Garage Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement patterns. The vendor base separates into consolidated multinational equipment integrators and mid-tier regional fabricators serving price-sensitive independents. Three archetypes dominate: diagnostic protocol specialists anchoring OEM relationships, lift manufacturers competing on energy efficiency certifications, and tool distributors capturing recurring revenue through subscription access models. Capacity expansion and strategic partnerships represent the primary competitive moves as electrification servicing requirements reshape capability requirements.
Among German engineering-intensive players, Robert Bosch GmbH and MAHA Maschinenbau Haldenwang GmbH & Co. KG occupy positions emphasizing precision manufacturing and regulatory compliance integration. Launch Tech Co., Ltd. represents the cost-optimized systems archetype targeting emerging market fleet operators. Hunter Engineering Company anchors the alignment-technology specialist tier within North American high-throughput workshop networks.
| Leading Market Players |
|---|
| Hunter Engineering Company |
| MAHA Maschinenbau Haldenwang GmbH & Co. KG |
| Robert Bosch GmbH |
| Launch Tech Co., Ltd. |
| Rotary Lift |
| Snap-on Incorporated |
| Vehicle Service Group |
| Nussbaum Automotive Solutions |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster anchors global lift fabrication capacity, with its electric servo-motor foundries and hydraulic component workshops feeding downstream pricing power to OEMs serving California fleet operators and Texas commercial vehicle hubs. This geographic concentration enables tier-one manufacturers to enforce cost-plus contracts indexed to steel and aluminum commodity exchanges, while mid-tier fabricators absorb margin compression from German and Japanese precision pump suppliers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between lift OEMs and fleet maintenance operators across California and Texas. Three-tier pricing structure across premium, standard, and economy levels separates OSHA-certified electric systems from legacy hydraulic units and unbranded imports. Pricing pressure stems from steel input volatility and compressed budgets among independent garages in metropolitan clusters. Fleet operators show lowest price sensitivity due to uptime-minimization mandates, while fragmented independent garages drive fastest adoption of subscription-based diagnostic scanner leasing.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta lift fabricators, Stuttgart-area precision engineering workshops, and Nagoya hydraulic component specialists serving global OEM assembly. Critical inputs draw from German and Japanese certified load sensor suppliers, Chinese aluminum extrusion mills, and Taiwanese servo-drive controllers. Single-source vulnerability concentrates in precision hydraulic pump supply from German and Japanese specialist manufacturers. Distribution runs through authorized dealer networks for OEM-aligned service centers and independent tool distributors capturing recurring revenue from fragmented garage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Garage equipment procurement is shifting toward platform-economics dynamics as embedded telematics integration and OEM data protocol compatibility create winner-take-most ecosystem effects. Interoperability standards for high-voltage battery diagnostics and thermal management tooling now determine which equipment suppliers capture fleet maintenance spend.
For Market Incumbents: Pre-empt obsolescence by embedding predictive maintenance algorithms into connected lift architectures and securing backward integration into certified load sensor production currently concentrated among German and Japanese suppliers. Anchor OEM data protocol access through exclusive diagnostic bench partnerships with commercial vehicle manufacturers retrofitting California and Texas service bays for electrification. For New Entrants and Emerging Players: Establish a beachhead in mobile service unit convergence by developing portable electric lifts and battery-powered compressors for on-site fleet maintenance across Maharashtra and Gujarat. Target subscription-based tool access models penetrating fastest among capital-constrained independent garages in metropolitan clusters where rapid technology obsolescence deters large upfront investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic equipment distributors bundling software update commitments with scanner leasing contracts. Long-term viability favors acquiring mid-tier manufacturers with established CE marking documentation capabilities and existing channel relationships in EU member states facing Green Deal repairability mandate tailwinds. Monitor EPA Section 608 refrigerant handling compliance timeline extensions as inflection indicator for air conditioning service bay retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Battery Servicing Certification | OSHA and EPA alignment on technician training standards accelerates premium equipment procurement across Texas and California fleet hubs. |
| Embedded Telematics Protocol Integration | Diagnostic bench compatibility with OEM data streams locks in dealership service center loyalty and recurring software revenue. |
| Mobile Service Unit Development | Portable electric lifts collapse fixed-versus-field service distinctions for commercial vehicle operators prioritizing uptime. |
| Precision Component Backward Integration | In-house production of certified load sensors reduces dependency on German and Japanese specialist suppliers. |
| Subscription-Based Tool Access Expansion | Leasing models with bundled updates capture recurring revenue from fragmented independent garage networks in metropolitan clusters. |
Methodological Framework
Cross-validation between primary interviews with fleet maintenance directors, dealership operations managers, aftermarket service heads, and independent garage owners anchors the qualitative findings against secondary validation from EPA regulatory filings, OSHA safety standard updates, EU Machinery Directive documentation, and commercial vehicle production databases. Bottom-up equipment procurement modeling triangulates against top-down fleet operator capex surveys across the analysis window.
Calibration against historical replacement cycle data and electrification retrofit announcement tracking shapes the projection framework. Segmentation dimensions span product type, end-user channel, technology architecture, and application workflow across the modeling period. CAGRs derive from equipment unit demand curves, software attachment rate trajectories, and regional regulatory compliance timeline assumptions including EPA Section 608 evolution and EU Green Deal repairability mandate implementation.
Stress conditions across steel and aluminum commodity volatility, precision component supply disruption, and high-voltage technician certification program output gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification penetration and alternative fuel infrastructure buildout. Quarterly review of OSHA lift certification requirement updates, EPA refrigerant handling rule revisions, and OEM telematics protocol standardization announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Shot Peening Machine Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Hose End Sprayers Market