
 Case Erectors Market | 2026-2036
Case Erectors Market Size, Share, and Industry Trends Forecast 2026-2036
Case Erectors Market Analysis
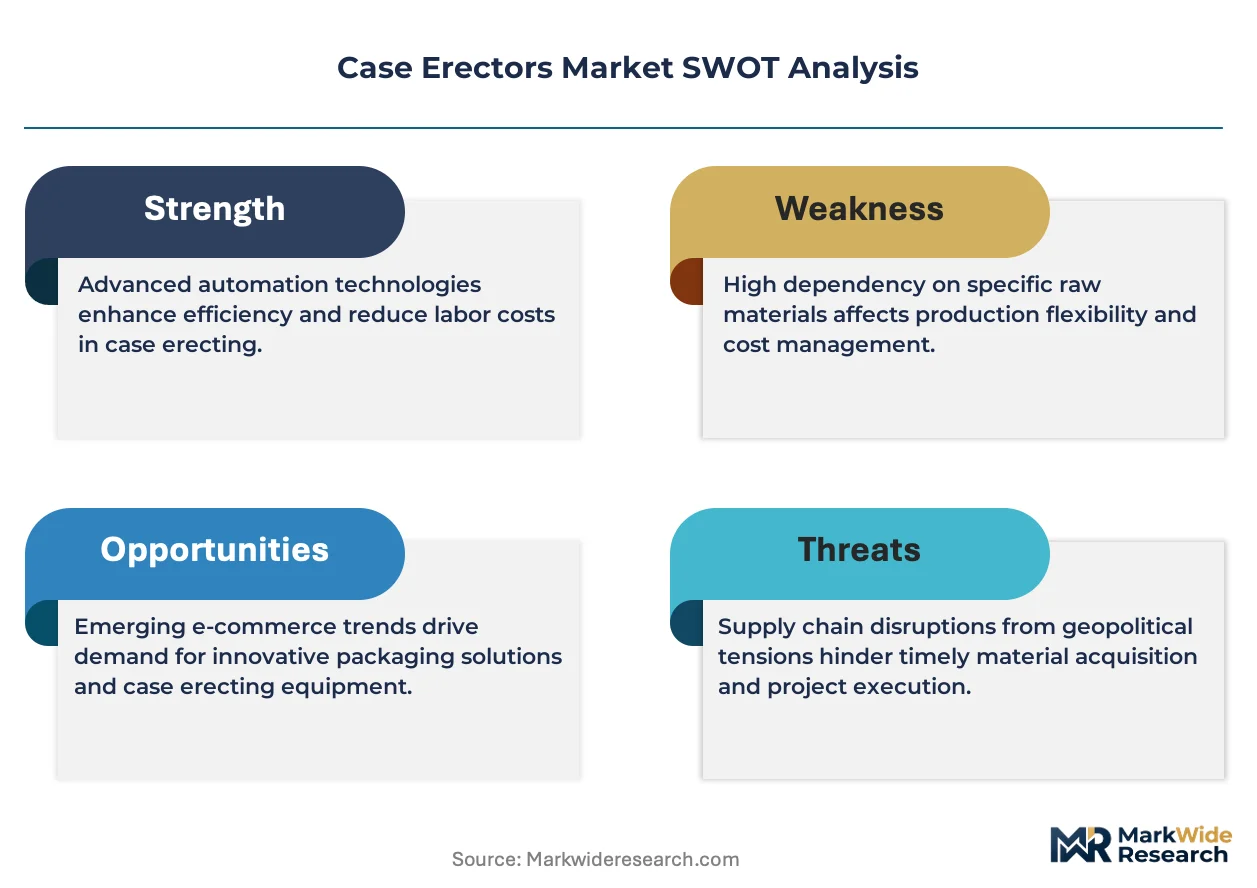
Small-batch craft producers is collapsing into large-scale beverage bottlers as the dominant buyer archetype for case erecting equipment. Wayne Automation leverages its vertical integration into control systems to capture recurring service revenue from high-volume installations. Lantech sustains geographic dominance across North American corrugated handling lines through dense distributor networks. Wexxar Bel differentiates via specialized tape-sealing technology for food-grade sanitary environments.
A case erector is an automated packaging machine that forms flat corrugated blanks into sealed bottom containers at speeds ranging from 10 to 50 cases per minute, serving as the critical first node in end-of-line packaging systems. Automatic case erectors anchor the product mix as throughput requirements tighten across beverage and prepared food operations. Electric drive technology is displacing pneumatic systems where energy efficiency targets and precise motion control justify higher capital outlay. Corrugated box handling occupies the dominant packaging type segment, though rigid container formats are gaining traction in pharmaceutical serialization lines.
FDA sanitary design standards and OSHA machine guarding regulations in the United States compel manufacturers to integrate interlocked access panels and washdown-rated construction. ISO packaging machinery safety standards shape export market access for European and Asian equipment builders. CE marking under the EU Machinery Directive creates compliance friction for non-European suppliers seeking placement with multinational CPG brands. Stakeholders must weigh total cost of ownership against throughput flexibility when specifying equipment for mixed-SKU fulfillment environments.
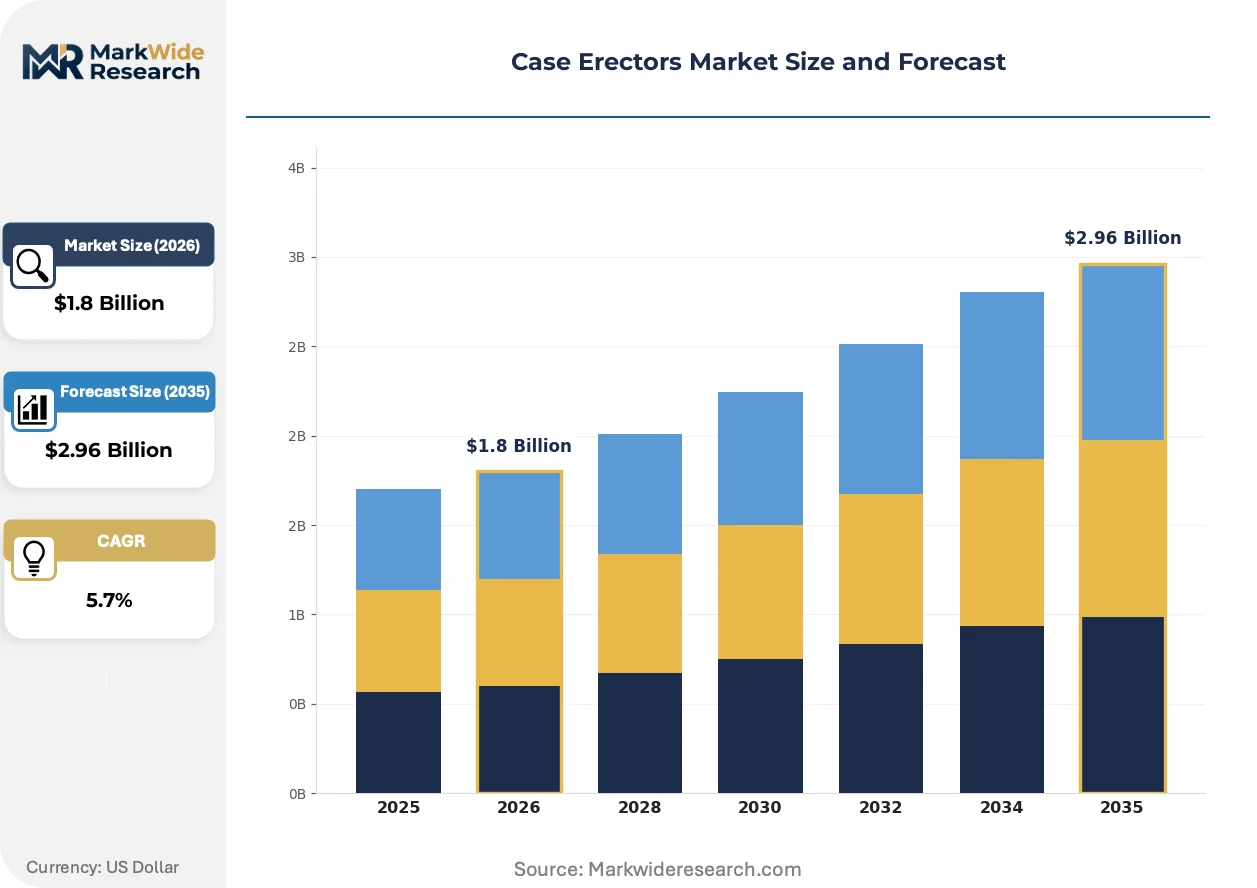
Market Dynamics
The case erectors market pivots on the tension between labor scarcity in developed economies and the capital intensity required to automate corrugated forming at mixed-SKU fulfillment centers. Electric drive architectures are compressing total cost of ownership curves while washdown-rated sanitary designs open food-grade applications previously served by manual labor.
Growth Catalysts
- OSHA machine guarding mandates:United States manufacturers face stepped-up enforcement of interlocked access panel requirements, accelerating replacement cycles for legacy pneumatic equipment lacking compliant safety architectures.
- E-commerce fulfillment throughput pressure:Third-party logistics operators in Germany and the Netherlands deploy automatic case erectors to sustain 40+ cases-per-minute velocities across highly variable order profiles.
- Corrugated substrate standardization:FEFCO box codes and automated blank feeding systems reduce changeover downtime, enabling beverage bottlers to run shorter production lots without manual adjustment.
Market Restraints
- Steel and servo motor input cost volatility:Electric drive case erectors carry 15-25% higher bill-of-material exposure to rare-earth magnet and precision gearbox supply chains concentrated in East Asian manufacturing clusters.
- CE marking friction for non-European builders:The EU Machinery Directive's conformity assessment requirements create 6-12 month approval timelines for North American and Asian equipment seeking placement with multinational CPG brands.
- Retrofit complexity with legacy conveyor infrastructure:Pneumatic-to-electric conversions often require complete control system replacement, not component swap, extending payback periods for mid-volume operations.
Strategic Opportunities
- Pharmaceutical serialization integration:Rigid container case erecting modules with integrated track-and-trace verification capture share in European and North American drug packaging lines facing DSCSA and Falsified Medicines Directive deadlines.
- India's PLI scheme for food processing:Central government production-linked incentives for cold chain infrastructure create first-mover advantages for sanitary-design equipment qualified to FSSAI hygiene standards.
- Servo-electric and vision system convergence:Real-time blank detection and adaptive forming pressure control enable zero-damage handling of lightweight recycled corrugated, expanding addressable substrate range.
Industry Challenges
- Controls engineering talent scarcity:Programming and commissioning of multi-axis servo systems requires specialized skill sets in short supply across Midwest US manufacturing corridors and Central European industrial regions.
- Sanitary welding certification timelines:FDA-compliant 3-A sanitary standards for dairy and ready-to-eat food applications demand 8-14 month validation cycles, compressing vendor margins on standardized platform designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Erectors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Pneumatic, Electric, Hydraulic, Mechanical Packaging Type: Corrugated Boxes, Rigid Containers, Flexible Packaging, Others |
| Companies Covered | Wexxar Bel, Lantech, Combi Packaging Systems, Wayne Automation, A-B-C Packaging, Pearson Packaging Systems, Hamrick Manufacturing & Services, WestRock Company, Arpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Erectors Market Emerging Trajectories
Packaging machinery architecture is pivoting from pneumatic to electric actuation, driven by energy accounting pressures and the precision requirements of lightweight recycled substrates. Three convergent developments are restructuring competitive positioning and buyer specifications.
Electric servo drives with integrated motion controllers are displacing pneumatic cylinder systems in mid-to-high speed applications. Beverage bottlers and prepared food processors adopt these platforms to cut compressed air consumption 30-40% and enable programmable forming pressure curves. The displacement compresses aftermarket revenue from pneumatic component replacement while shifting vendor economics toward software-enabled performance optimization.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of food-contact lubricants and anti-stick coatings used in case erector forming heads. European OEMs face 2025 sunset dates for legacy chemistries, requiring accelerated qualification of bio-based alternatives. German automotive parts packagers report 4-6 month validation delays as they retest forming surface compatibility with new lubricant portfolios.
Contract packaging procurement patterns are fragmenting equipment specification authority away from central engineering teams toward site-level operations managers. Third-party logistics providers in the Netherlands and Belgium now source case erectors through rental and short-term lease channels rather than capital purchase, compressing manufacturer margins and forcing unbundling of installation and training services from base equipment pricing.
Case Erectors Market Segmentation
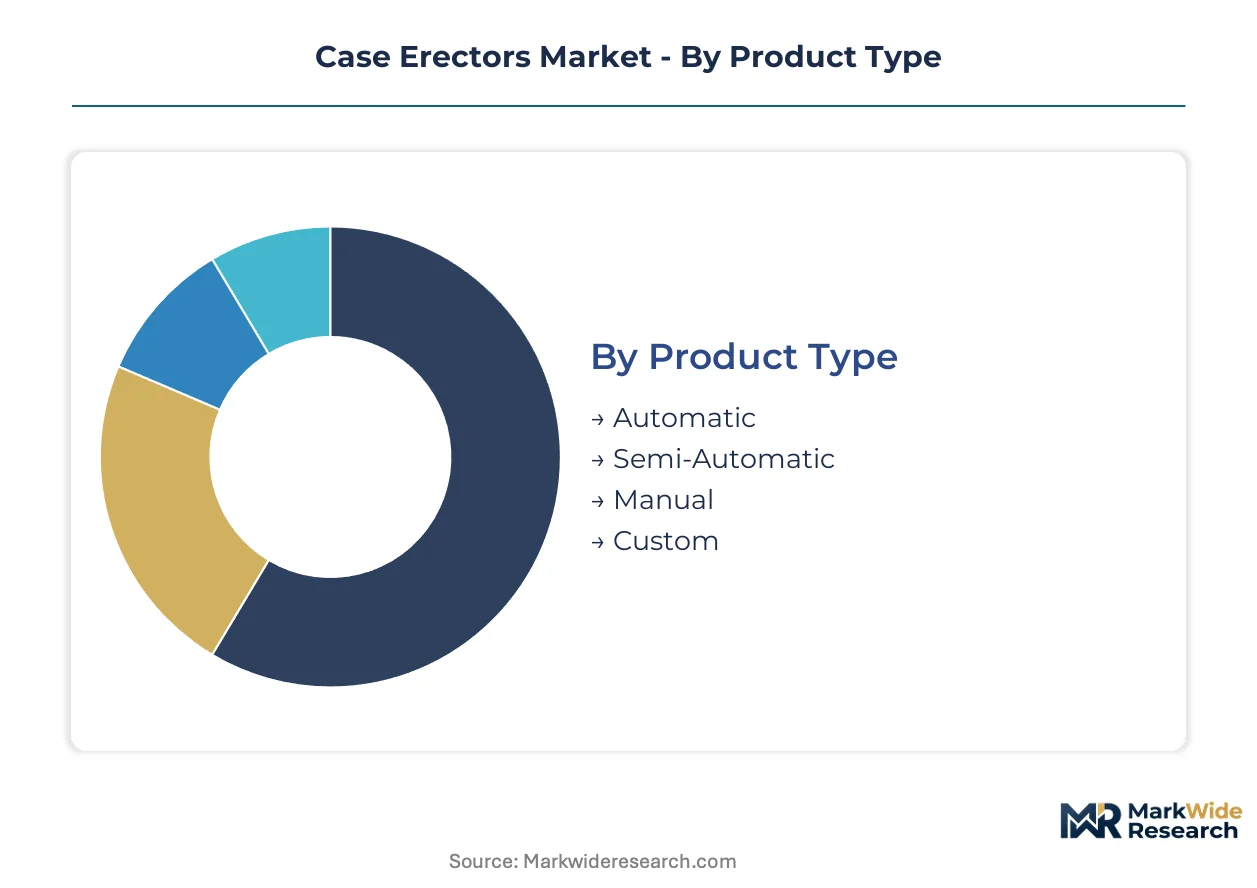
Case erector procurement varies sharply by operational scale and regulatory exposure, with automatic systems commanding capital budgets at multinational beverage bottlers while semi-automatic units serve mid-volume regional packers. Technology choices and packaging formats further stratify the addressable market, creating distinct competitive arenas with divergent margin profiles and service intensity requirements.
Product Type:
Automatic case erectors anchor export-led demand from German and Dutch fulfillment centers, while semi-automatic and manual variants concentrate in domestic North American operations serving craft producers and contract packagers.
- Automatic:These systems integrate servo-electric drives and programmable logic controllers to achieve 40+ cases per minute across variable SKU profiles. Demand concentrates in Netherlands third-party logistics hubs where CE-marked equipment faces stepped-up throughput mandates from pan-European e-commerce clients.
- Semi-Automatic:Hybrid designs blend powered blank feeding with operator-assisted case closing, occupying the cost-performance midpoint for mid-volume food processors. Domestic US adoption is accelerating among regional dairy cooperatives upgrading from manual stations to meet OSHA interlock requirements without full automation capital outlay.
- Manual:Hand-operated forming stations serve low-volume specialty operations and startup craft beverage producers with batch sizes below 500 units daily.
- Custom:Engineered-to-order systems accommodate non-standard corrugated formats or integration with legacy conveyor architectures prevalent in acquired facility footprints.
Automatic holds the largest share; momentum sits with semi-automatic as mid-tier operators bridge compliance gaps.
End User:
Cost tier stratification separates pharmaceutical serialization investments from food-grade sanitary specifications, with electronics and cosmetics occupying intermediate price-performance bands.
- Food & Beverage:Beverage bottlers and prepared food processors drive specification authority for washdown-rated stainless construction and 3-A sanitary welding certification. German automotive parts packagers are retooling forming surface compatibility with bio-based lubricant portfolios under REACH sunset deadlines.
- Pharmaceuticals:Rigid container case erecting modules with integrated track-and-trace verification capture priority capital allocation. European drug packaging lines facing DSCSA and Falsified Medicines Directive deadlines are expanding the addressable substrate range through servo-electric and vision system convergence.
- Cosmetics:Fragile product handling requirements favor gentle forming pressure curves and cosmetic-grade surface finishes, typically sourcing from Italian and French equipment specialists.
- Electronics:ESD-rated construction and precision dimensional tolerance control serve high-value consumer device protection in Shenzhen and Taipei manufacturing corridors.
Food & Beverage commands the dominant revenue pool; Pharmaceuticals is expanding most quickly on regulatory deadline compression.
Technology:
Volume concentration favors electric architectures in high-throughput applications, while pneumatic legacy installed base creates retrofit complexity extending payback periods for mid-volume operators.
- Electric:Servo motor systems with integrated motion controllers enable programmable forming pressure curves and 30-40% compressed air consumption reduction. Netherlands and Belgium contract packagers specify these platforms for rental and short-term lease channels.
- Pneumatic:Cylinder-based actuation retains installed base dominance in legacy beverage operations, though aftermarket component replacement revenue is compressing as electric displacement accelerates.
- Hydraulic:High-force applications for heavy-duty rigid container forming occupy niche positions in industrial chemical packaging.
- Mechanical:Cam-driven simplicity serves developing market entry-level installations with limited maintenance technical capacity.
Electric claims the steepest expansion trajectory; Pneumatic retains the largest installed base.
Packaging Type:
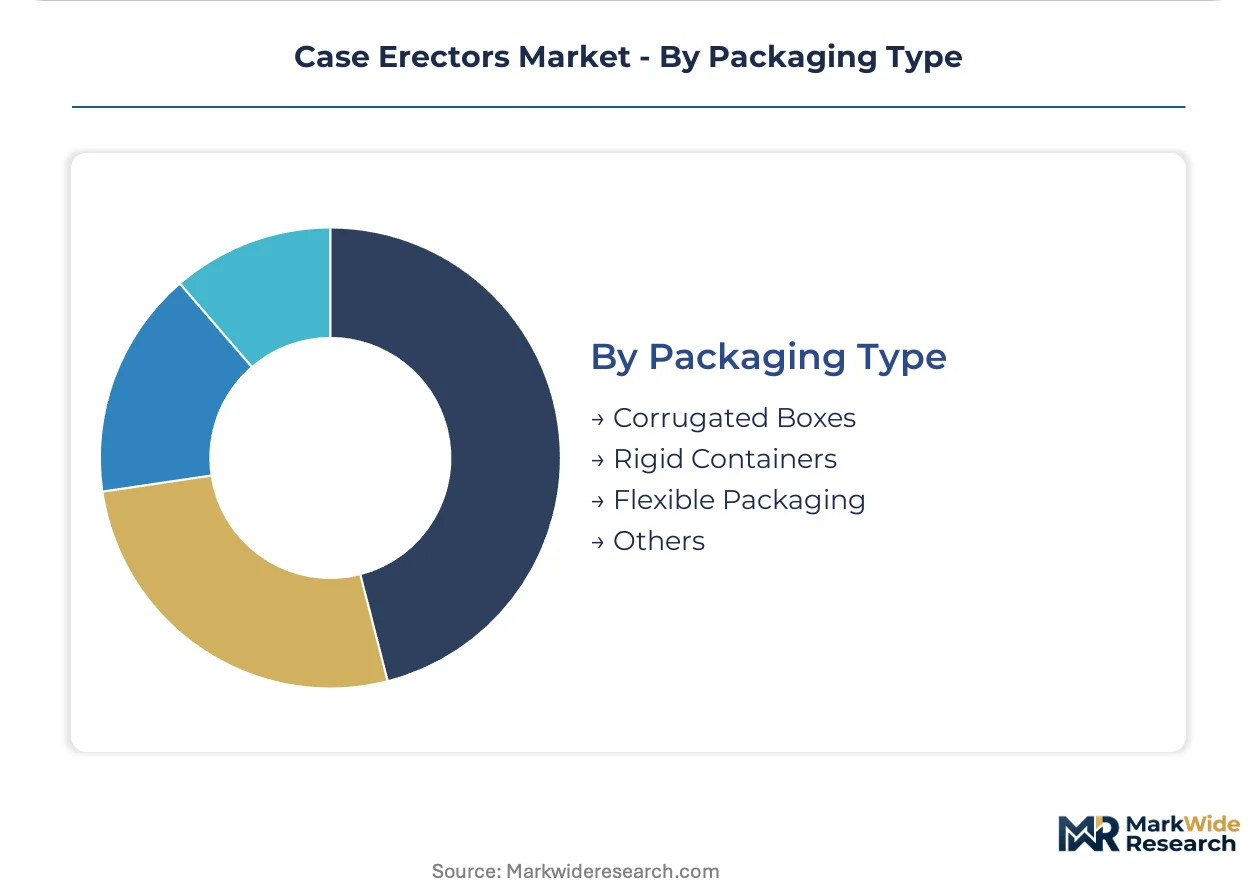
Customer type fragmentation separates corrugated standardization from rigid container specialization, with flexible packaging emerging at the periphery of traditional case erector applicability.
- Corrugated Boxes:FEFCO code standardization and automated blank feeding systems reduce changeover downtime for beverage bottlers running shorter production lots. German demand concentrates in automotive parts precision erecting equipment.
- Rigid Containers:Pharmaceutical serialization integration with track-and-trace verification modules is gaining traction in European and North American drug packaging lines facing regulatory compliance deadlines.
- Flexible Packaging:Modified-atmosphere pouch handling adaptations extend case erector applicability into prepared meal and snack food segments.
- Others:Composite and fiber-based sustainable substrates require adaptive forming pressure control for zero-damage handling of lightweight recycled materials.
Corrugated Boxes maintains volume leadership; Rigid Containers is gaining share fastest on pharmaceutical line investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' position as Europe's primary fulfillment automation hub, with adjacent German industrial corridors feeding precision packaging demand.
United States
E-commerce fulfillment centers in Illinois and Ohio drive electric drive adoption as OSHA machine guarding mandates accelerate replacement of legacy pneumatic systems. FDA sanitary design standards compel washdown-rated construction in dairy operations across Wisconsin and New York. Chicago-area third-party logistics operators deploy 40+ cases-per-minute automatic systems to meet throughput pressure from pan-American retail clients.
Germany
Automotive parts packaging in Baden-Württemberg and Bavaria demands precision erecting equipment for variable corrugated formats. REACH restrictions on per- and polyfluoroalkyl substances force 4-6 month validation delays as manufacturers retest forming surface compatibility with bio-based lubricant portfolios. Stuttgart industrial clusters concentrate specification authority for CE-marked equipment serving multinational CPG brands.
Netherlands
Third-party logistics hubs around Rotterdam and Eindhoven specify automatic case erectors through rental and short-term lease channels rather than capital purchase. EU Machinery Directive conformity assessment requirements shape procurement patterns for equipment serving pan-European e-commerce clients. Venlo's warehousing corridor anchors deployment of servo-electric systems with integrated vision control.
India
Central government production-linked incentives for food processing cold chain infrastructure create first-mover advantages for sanitary-design equipment qualified to FSSAI hygiene standards. Maharashtra and Gujarat dairy cooperatives bridge compliance gaps with semi-automatic systems avoiding full automation capital outlay. Mumbai-Pune industrial belt concentrates regional packaging machinery procurement authority.
China
Shenzhen and Taipei manufacturing corridors drive ESD-rated construction for high-value consumer device protection in electronics packaging lines. GB standards and MIIT regulations shape domestic equipment specifications while dual carbon goals accelerate electric displacement of pneumatic legacy systems. Yangtze River Delta beverage bottlers adopt programmable forming pressure curves for lightweight recycled corrugated substrates.
Case Erectors Market Vendor Landscape
Concentration sits with mid-scale specialists commanding narrow technology segments rather than diversified machinery conglomerates. The vendor base spans three tiers: integrated packaging line builders, standalone equipment specialists, and regional fabricators serving domestic markets. Strategic differentiation runs through control system architecture, geographic density of service networks, and vertical integration into aftermarket parts. Competitive moves center on M&A to capture complementary sealing technologies and capacity expansion in CE-marked production for European market access.
Among North American equipment builders, Wayne Automation and Lantech occupy positions reflecting divergent scale strategies, while Wexxar Bel represents the specialist archetype anchored in application-specific technology domains. These companies exemplify competitive positioning through distinct channel structures and technology focal points rather than undifferentiated portfolio breadth.
| Leading Market Players |
|---|
| Wexxar Bel |
| Lantech |
| Combi Packaging Systems |
| Wayne Automation |
| A-B-C Packaging |
| Pearson Packaging Systems |
| Hamrick Manufacturing & Services |
| WestRock Company |
| Arpac LLC |
| Others |
Supply Flow & Price Mechanics
CE marking under the EU Machinery Directive gates both European market access and price stratification, forcing non-European builders into extended conformity timelines that compress margins while enabling certified incumbents to command service-bundled premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked servo-electric systems from pneumatic legacy platforms and entry-level mechanical units. Price differentiation rests on certification grade and after-sales service bundling, with FDA 3-A sanitary welding certification adding substantial validation cost recovery. Pricing pressure stems from Netherlands contract packagers shifting procurement toward rental and short-term lease channels. Mid-volume regional dairy cooperatives exhibit highest price sensitivity, while multinational beverage bottlers prioritize throughput reliability over capital outlay.
Supply Chain Analysis
Inbound logistics costs from East Asian manufacturing clusters fluctuate with container availability on transpacific trade lanes, exposing electric drive builders to rare-earth magnet supply volatility. Component sourcing draws from China, Japan, and Germany for precision gearboxes, servo motors, and control systems. Single-source vulnerability concentrates in rare-earth magnet supply chains. Distribution runs through dense North American distributor networks and direct OEM relationships in European industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The case erectors market sits in early-cycle expansion as e-commerce fulfillment throughput mandates accelerate electric displacement of pneumatic legacy systems across mixed-SKU operations.
For Market Incumbents: Compound service revenue attachment through predictive maintenance software and remote diagnostics platforms. Deepen backward integration into control system architecture to capture recurring revenue streams. Expand CE-marked production capacity in European manufacturing corridors to reduce conformity assessment friction. Defend against emerging servo-electric specialists by accelerating sanitary welding certification pipelines.
For New Entrants and Emerging Players: Differentiate on pharmaceutical serialization integration with track-and-trace verification modules. Target India's PLI-supported food processing cold chain infrastructure as the most penetrable geography. Pursue white-space opportunities in rigid container forming for European drug packaging lines facing DSCSA deadlines. Lead with rental-channel partnerships in Netherlands third-party logistics hubs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-electric platform development as multi-axis motion control engineering talent scarcity intensifies. Long-term viability favors vendors with captive software capabilities and geographic density of aftermarket service networks. Acquisition targets should display vertical integration into control systems or specialized sealing technologies. Watch for inflection when REACH bio-based lubricant qualification timelines compress vendor margins.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Shortens conformity timelines for non-European builders seeking multinational CPG brand placement. |
| Servo-Electric Platform Development | Captures energy efficiency mandates and precision requirements of lightweight recycled corrugated substrates. |
| Pharmaceutical Serialization Integration | Addresses DSCSA and Falsified Medicines Directive compliance deadlines in European and North American drug packaging. |
| Sanitary Welding Certification Investment | Opens FDA 3-A dairy and ready-to-eat food applications with extended validation cycles. |
| Software-Enabled Performance Optimization | Shifts vendor economics from pneumatic component replacement toward recurring service revenue streams. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs records, and equipment manufacturer technical documentation. Primary interviews engaged plant engineers, OEM procurement teams, aftermarket service heads, and packaging line integration specialists across beverage, pharmaceutical, and third-party logistics operations. Secondary validation drew from OSHA enforcement databases, FDA 510(k) equipment listings, EU Machinery Directive conformity assessments, and FEFCO corrugated standards documentation. Bottom-up equipment shipment analysis triangulates against top-down end-use industry capital expenditure tracking.
Segmentation dimensions modeled span product type, technology architecture, packaging format, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment replacement cycle analysis, regulatory deadline compression effects, and substrate standardization adoption curves. Industry-specific forecast inputs include e-commerce fulfillment throughput velocity requirements and pharmaceutical serialization compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth, stable rare-earth magnet supply chains, or unaltered REACH enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding labor cost trajectories and corrugated substrate standardization adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Smart Crane Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Collating Machinery Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Deep Hole Drilling Machines Market