
 Gantry Crane Market | 2026-2036
Gantry Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Gantry Crane Market Intelligence
Modular crane configurations is shifting procurement patterns across port and industrial terminals. Konecranes leverages its service network to bundle predictive maintenance with new equipment sales. Liebherr Group anchors its position through in-house manufacturing of drive systems and steel structures. Demag Cranes & Components GmbH differentiates via standardized modular kits that reduce on-site assembly time.
A gantry crane is a overhead lifting apparatus mounted on legs that travel on rails or wheels, typically spanning 10 to 50 meters with load capacities from 1 ton to over 1,000 tons, designed for horizontal movement of heavy loads across fixed work areas. Electric technology variants now dominate new orders as harbor operators phase out diesel-hydraulic systems to meet emission protocols. Portable gantry crane configurations represent the fastest-expanding product category, driven by maintenance departments seeking flexible deployment without permanent infrastructure. Heavy lifting applications command the largest revenue share within the application dimension, though material handling segments show stronger volume growth in manufacturing end-use settings.
ISO 4301-1 classification standards and FEM 1.001 design rules govern load ratings and safety margins for international crane procurement. OSHA workplace safety directives in the United States and CE marking requirements under the EU Machinery Directive shape regional compliance costs and product certification timelines. China GB/T standards and MEE emission guidelines add parallel certification layers for equipment deployed in domestic ports. Stakeholders must monitor how overlapping carbon accounting rules and local content requirements reshape supplier qualification criteria across major harbor expansion programs.
Market Dynamics
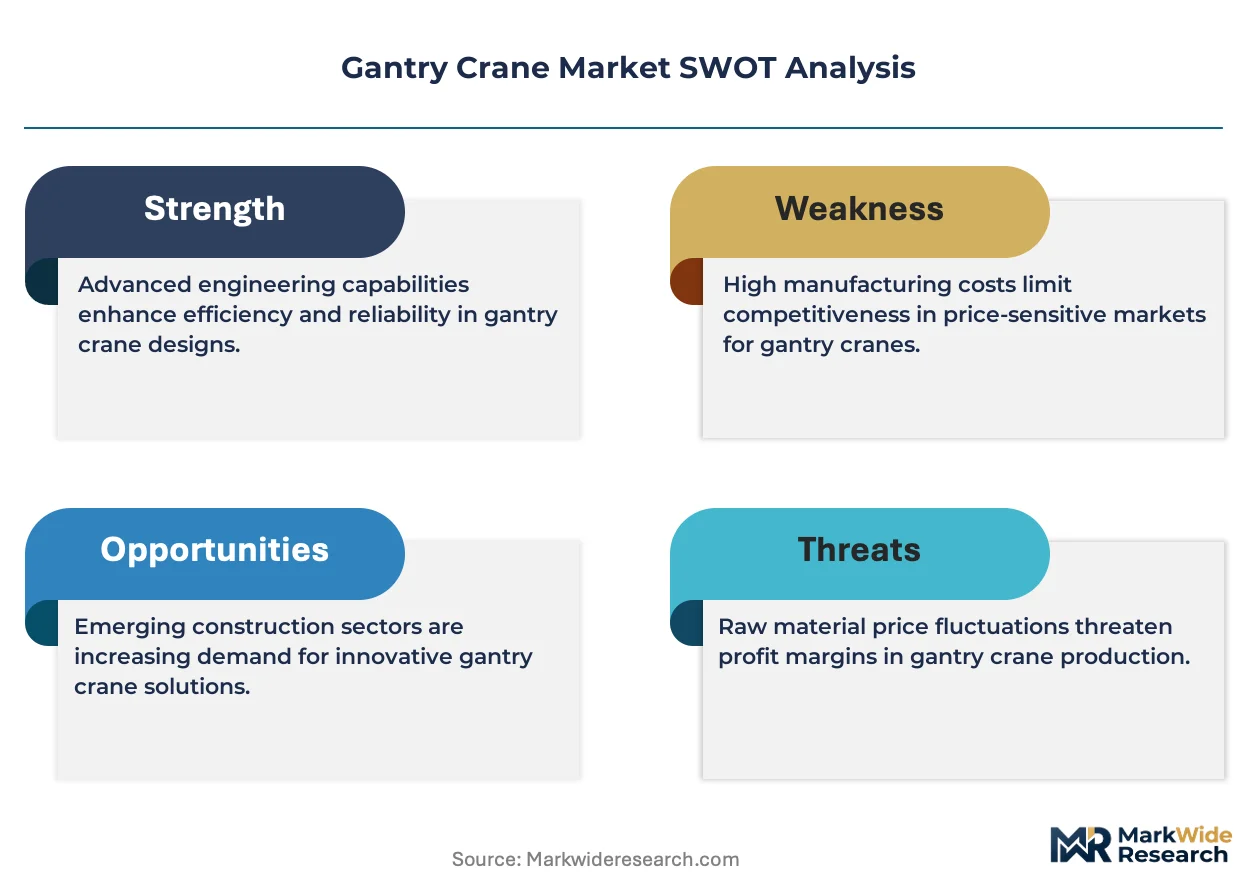
Electrification mandates from the EU F-Gas Regulation and IMO decarbonization protocols are forcing harbor operators to retire diesel-hydraulic fleets ahead of depreciation schedules, compressing replacement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- IMO 2023 Carbon Intensity Indicator:Shipping lines face penalties for vessel emissions, driving port authorities to install electric shore-power gantry systems that reduce auxiliary engine runtime during cargo operations.
- China shipyard expansion:Domestic vessel construction programs in Jiangsu and Guangdong provinces are generating concentrated demand for heavy-lift gantry installations with 1,000-ton plus capacity ratings.
- Modular assembly protocols:Standardized component kits are reducing on-site installation time by enabling pre-fabricated leg and beam sections to be containerized for remote deployment.
Market Restraints
- Steel price volatility:Structural beam fabrication depends on hot-rolled steel coil, where input cost swings of 20-40 percent within single quarters destabilize project budgeting for terminal operators.
- Drive system supply concentration:Permanent magnet motor and variable frequency drive production clusters in Germany and Japan create vulnerability for crane builders without captive manufacturing or dual-source agreements.
- Battery energy density limits:Lithium-ion cell chemistry constraints restrict all-electric gantry duty cycles in high-throughput container terminals, necessitating hybrid architectures that add capital cost and maintenance complexity.
Strategic Opportunities
- India port privatization:Adani Ports and JSW Infrastructure are expanding container terminal capacity under concession agreements, creating procurement windows for European and East Asian equipment suppliers.
- Predictive maintenance convergence:Integration of vibration sensors with cloud-based analytics platforms is enabling crane-as-a-service revenue models that capture lifetime value beyond initial equipment sales.
- EU Green Deal funding:Innovation and Modernisation Funds are subsidizing shore electrification infrastructure, lowering effective cost barriers for municipal port authorities in Italy, Spain, and Greece.
Industry Challenges
- Certification timeline compression:Parallel ISO 4301-1, FEM 1.001, and China GB/T approval processes extend delivery schedules by 8-14 months for equipment destined for multi-jurisdiction deployment.
- Electromechanical technician scarcity:Harbor maintenance departments lack personnel trained in high-voltage power electronics and PLC diagnostics, forcing reliance on OEM service contracts that erode operating margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gantry Crane Market |
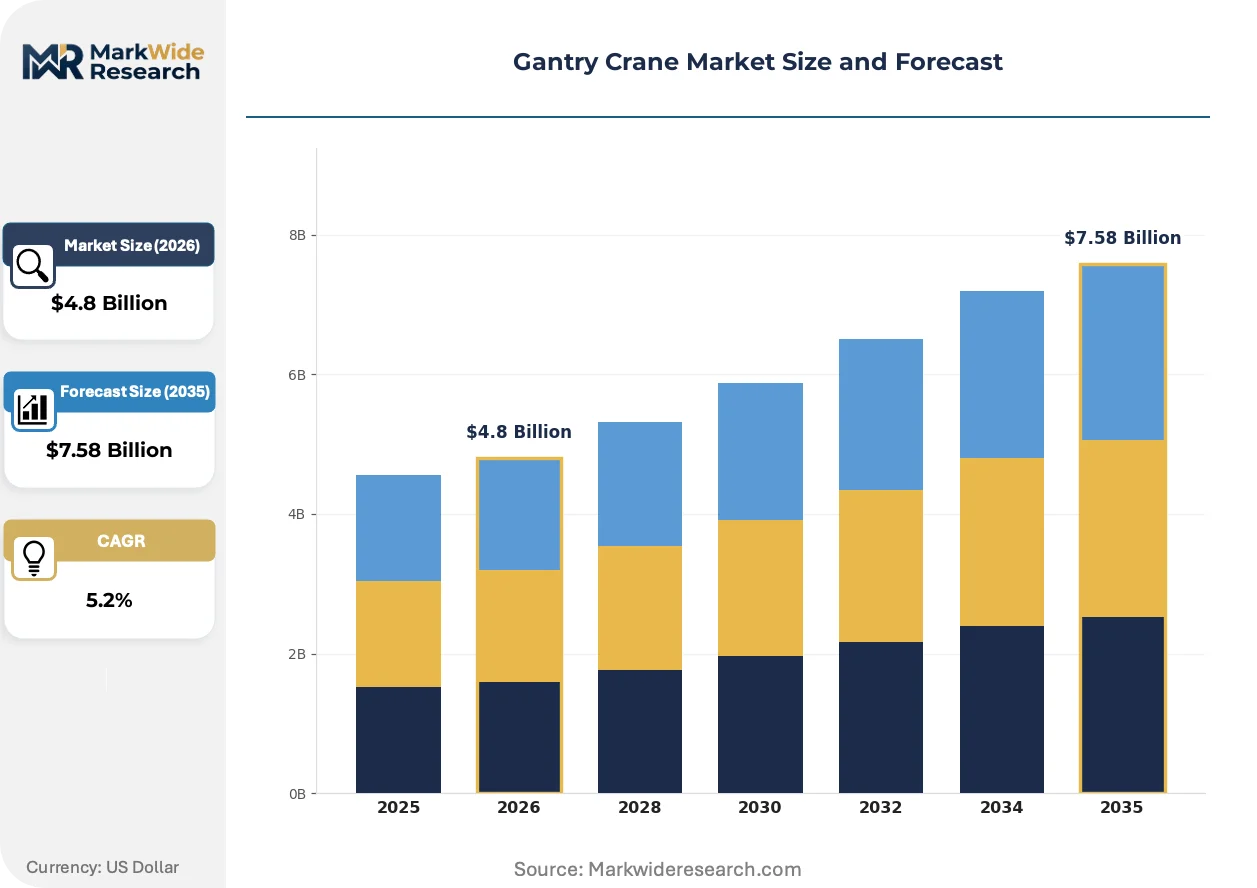
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Gantry Crane, Portable Gantry Crane, Adjustable Gantry Crane, Under-Hook Gantry Crane End User: Construction, Manufacturing, Transportation, Shipping Technology: Hydraulic, Electric, Manual, Pneumatic Application: Heavy Lifting, Material Handling, Assembly, Maintenance |
| Companies Covered | Konecranes, Demag Cranes & Components GmbH, Liebherr Group, JASO Industrial Cranes, SANY Group, Shanghai Zhenhua Heavy Industries Co., Ltd., Aicrane Machinery Group, Mi-Jack Products, Inc., Mammoet Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gantry Crane Market Strategic Shifts & Innovations
Digital twin architectures and autonomous positioning systems are converging with electrification platforms to redefine crane lifecycle economics. Equipment buyers now evaluate total cost of ownership across 15-20 year horizons rather than upfront capital expenditure alone.
Digital twin simulation software is unifying structural load modeling with real-time operational data streams. Port operators in Rotterdam and Singapore are deploying these systems to optimize maintenance intervals and predict component failures before downtime occurs. This technology is unifying design engineering with field performance, collapsing the feedback loop between crane manufacturers and terminal operators from years to weeks.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is accelerating adoption of air-cooled transformer and drive systems in electric gantry designs. Crane builders must redesign thermal management architectures to eliminate dependency on synthetic cooling fluids. Heavy-lift applications in Northern European ports face the steepest compliance cost increases, prompting accelerated R&D budgets for alternative cooling topologies.
Service contract unbundling is fragmenting traditional procurement relationships. Terminal operators in Brazil and the UAE are separating equipment purchase from maintenance obligations, soliciting third-party engineering firms for lifecycle support. This pattern is most visible in greenfield port developments where owners lack legacy vendor relationships and seek competitive tension across supply categories.
Gantry Crane Market Segmentation
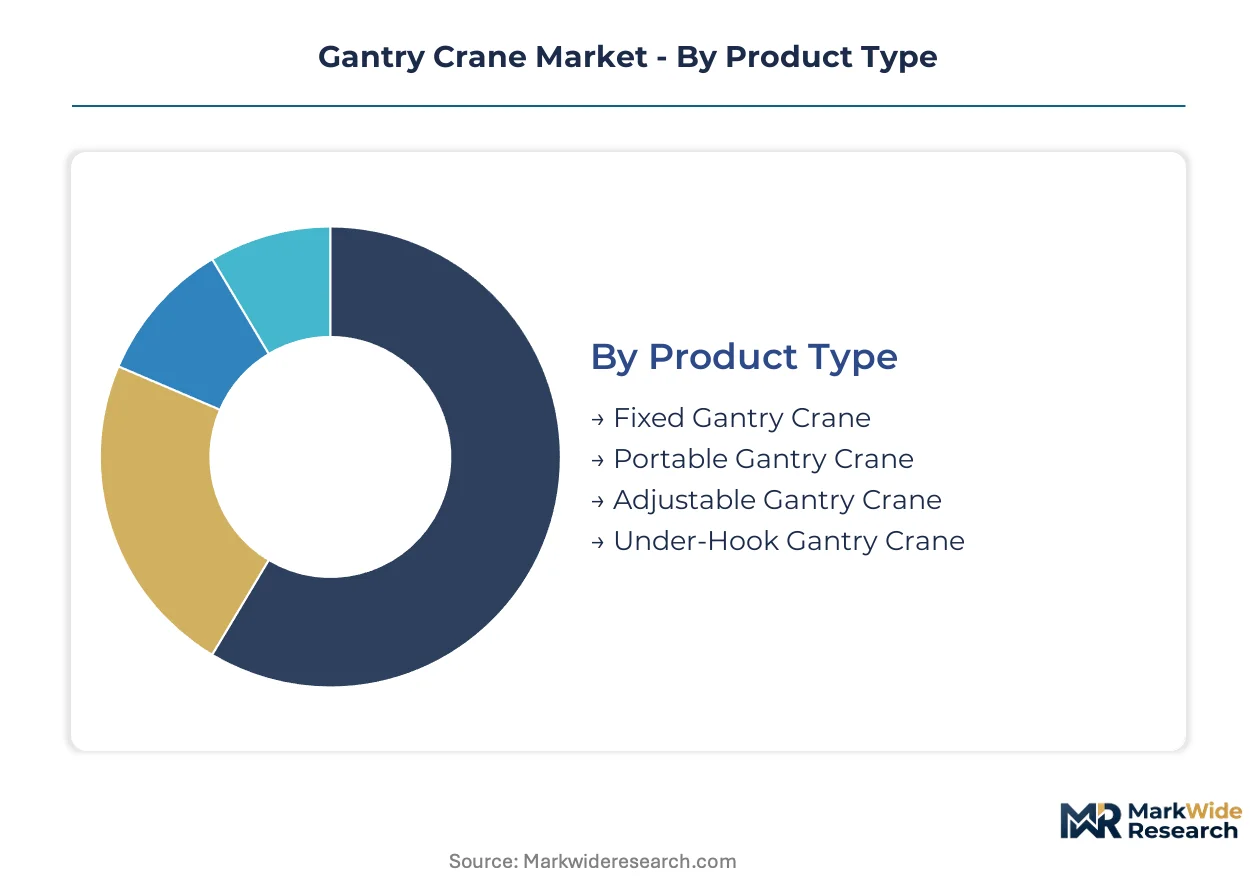
Gantry crane segmentation reveals how specification choices cascade through procurement economics and operational lifecycles. Equipment buyers weigh duty cycle demands against infrastructure constraints, creating distinct purchasing patterns across product configurations and technology platforms.
Product Type:
Structural mobility defines the capital-expense-to-operating-flexibility trade-off across gantry crane architectures.
- Fixed Gantry Crane:Permanent rail-mounted installations with welded steel superstructures spanning 30-50 meters dominate container terminal and shipyard applications. Demand concentrates in Chinese ports where Shanghai Zhenhua Heavy Industries anchors procurement for 1,000-ton capacity installations serving Jiangsu and Guangdong shipyard expansions.
- Portable Gantry Crane:Modular aluminum or steel assemblies with caster-mounted legs enable rapid redeployment without foundation work. Manufacturing maintenance departments in Germany and Japan are expanding orders for sub-10-ton units to support flexible production line reconfigurations driven by just-in-time assembly protocols.
- Adjustable Gantry Crane:Telescoping leg designs permit height and span modification for multi-purpose indoor facilities.
- Under-Hook Gantry Crane:Suspended configurations integrate with existing overhead structures for constrained headroom environments.
Fixed gantry crane installations lead on scale; portable gantry crane configurations are gaining share fastest among end-users prioritizing capital efficiency.
End User:
Operational intensity and load frequency shape technology selection across vertical demand clusters.
- Shipping:Container terminals and bulk cargo facilities require continuous-duty electric systems with 20+ lift cycles per hour. IMO decarbonization mandates are forcing port authorities in Rotterdam and Singapore to retire diesel-hydraulic fleets ahead of depreciation schedules, compressing replacement cycles for shore-power gantry infrastructure.
- Manufacturing:Automotive and heavy machinery plants deploy medium-capacity electric gantries for repetitive material flows. German OEMs are bundling predictive maintenance contracts with new equipment purchases to address electromechanical technician scarcity in PLC diagnostics and high-voltage power electronics.
- Construction:Infrastructure projects utilize rental fleets of portable and adjustable configurations for temporary heavy lifting.
- Transportation:Rail yards and intermodal terminals integrate gantry systems with automated guided vehicle networks.
Shipping commands the largest revenue concentration; manufacturing shows the steepest expansion trajectory as reshoring programs rebuild domestic industrial capacity.
Technology:
Power transmission architecture determines compliance cost exposure and lifecycle operating economics.
- Electric:Permanent magnet motor drives with variable frequency control deliver precision positioning and zero direct emissions. EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants is accelerating adoption of air-cooled transformer systems, prompting redesign of thermal management architectures in Northern European port installations.
- Hydraulic:Diesel-hydraulic systems face accelerated obsolescence as harbor operators phase out equipment to meet emission protocols, though remaining demand persists in remote construction sites lacking grid infrastructure.
- Manual:Chain-hoist configurations serve low-duty maintenance and small workshop applications with minimal capital outlay.
- Pneumatic:Compressed-air drives operate in explosive atmosphere environments where electrical ignition risks are prohibitive.
Electric systems lead on new order volume; hybrid architectures are climbing fastest as battery energy density constraints restrict pure-electric duty cycles in high-throughput terminals.
Application:
Load characteristics and movement patterns dictate structural engineering requirements and safety margin calculations.
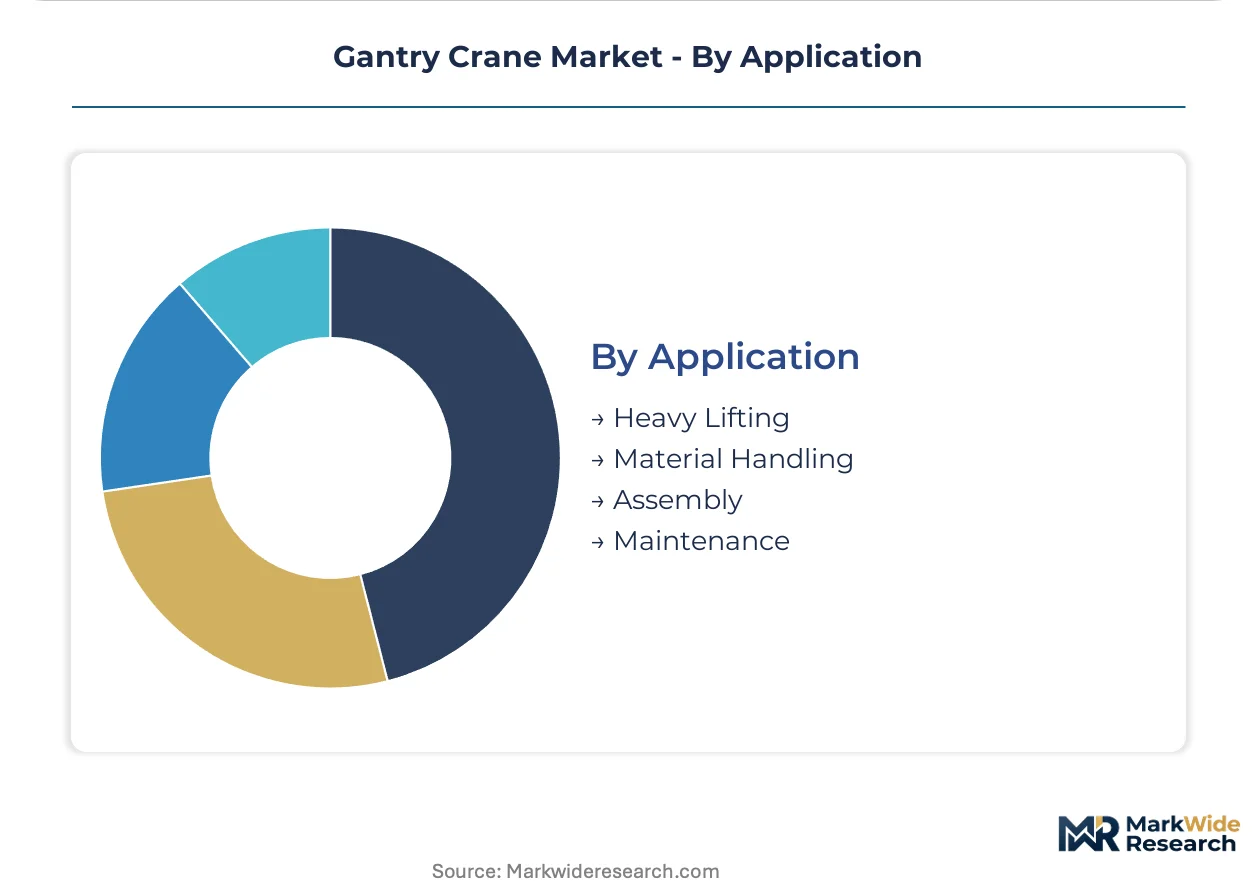
- Heavy Lifting:Shipyard and offshore fabrication applications require engineered solutions with 500-ton plus capacity ratings and redundant safety systems. China GB/T standards and FEM 1.001 design rules govern load ratings for equipment serving domestic vessel construction programs.
- Material Handling:Repetitive pallet and container movements in distribution centers prioritize speed over single-lift capacity. ISO 4301-1 classification standards shape procurement specifications for automated storage and retrieval integration.
- Assembly:Precision positioning for aerospace and automotive component mating demands fine control and minimal sway.
- Maintenance:Intermittent-use configurations emphasize rapid deployment and compact storage footprints for facility upkeep crews.
Heavy lifting anchors revenue concentration; material handling is expanding most quickly as e-commerce fulfillment networks densify automated warehouse infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gantry crane manufacturing originated in German heavy engineering workshops during the early industrial era, with port electrification programs in Rotterdam and Hamburg establishing the first large-scale container terminal installations that defined modern specifications.
China
Jiangsu and Guangdong shipyard expansions drive concentrated demand for 1,000-ton capacity heavy-lift installations. MEE emission guidelines and GB/T standards impose parallel certification requirements for domestic port deployments. Shanghai Zhenhua Heavy Industries anchors procurement volumes through integrated steel structure and drive system production serving Yangtze River Delta terminal operators.
Germany
Automotive OEM maintenance departments seek flexible sub-10-ton portable configurations for just-in-time assembly line reconfigurations. CE marking under the EU Machinery Directive shapes regional compliance timelines for equipment exports. Baden-Württemberg industrial clusters host predictive maintenance service bundling alongside new equipment sales.
United States
OSHA workplace safety directives govern load rating certifications for intermodal rail yard and container terminal procurement. Port authorities in Los Angeles and Long Beach face IMO 2023 Carbon Intensity Indicator pressure to install electric shore-power gantry systems. Southeast manufacturing reshoring programs expand medium-capacity electric gantry orders for repetitive material flows.
India
Adani Ports and JSW Infrastructure concession agreements create procurement windows for foreign equipment suppliers entering container terminal expansion programs. BIS standards and CEA electrical safety regulations add certification layers for imported installations. Gujarat and Maharashtra port privatization drives concentrate demand assessment among European and East Asian crane builders.
Singapore
Digital twin deployment for autonomous positioning and predictive maintenance optimization leads port technology adoption. Maritime and Port Authority regulations align with IMO decarbonization protocols to compress diesel-hydraulic fleet replacement cycles. Tuas Port development generates demand for continuous-duty electric systems with 20-plus lift cycles per hour.
Gantry Crane Market Key Industry Players
Premium-margin players sit above commodity-margin players across service bundling and captive manufacturing capabilities. The vendor base stratifies between integrated engineering groups with in-house drive system production and assembly-focused fabricators sourcing components externally. Three archetypes dominate: full-service providers combining equipment with lifetime maintenance contracts, modular kit specialists reducing on-site assembly duration, and heavy-lift engineers targeting shipyard and offshore fabrication niches. Competitive moves concentrate on predictive maintenance convergence and geographic expansion through port privatization windows.
Among European engineering groups, Konecranes and Demag Cranes & Components GmbH exemplify divergent strategic positions. Konecranes occupies a service-network tier bundling predictive maintenance with new equipment sales. Demag Cranes & Components GmbH represents the modular assembly archetype through standardized component kits. Shanghai Zhenhua Heavy Industries Co., Ltd. anchors the heavy-lift fabrication segment with integrated steel structure and drive system production.
| Leading Market Players |
|---|
| Konecranes |
| Demag Cranes & Components GmbH |
| Liebherr Group |
| JASO Industrial Cranes |
| SANY Group |
| Shanghai Zhenhua Heavy Industries Co., Ltd. |
| Aicrane Machinery Group |
| Mi-Jack Products, Inc. |
| Mammoet Holding B.V. |
| Others |
Cost & Logistics Intelligence
Hot-rolled steel coil costs cascade from Chinese and German mill complexes through three distinct pricing tiers, with structural beam fabrication consuming 35-45 percent of finished crane value and terminal operators facing quarterly budget destabilization from input volatility.
Pricing Analysis
Project-based contract pricing with indexed raw material adjustments dominates heavy-lift procurement, separating integrated full-service bundles from modular kit suppliers and spot-market rental fleets. Price differentiation rests on certification grade—ISO 4301-1 and FEM 1.001 compliance tiers command 15-25 percent premiums—and captive drive system manufacturing. Cost compression in standard-capacity electric gantries is intensifying because Shanghai Zhenhua Heavy Industries and SANY Group are expanding domestic Chinese production. Municipal port authorities in Southern Europe show highest price sensitivity due to constrained public budgets, while Singapore and Rotterdam terminal operators prioritize lifecycle cost over upfront capital.
Supply Chain Analysis
Regional distribution centers in Hamburg, Shanghai, and Houston orchestrate hub-and-spoke patterns for containerized leg and beam sections, with final assembly occurring at port sites or certified installer yards. Manufacturing gravity centers on China, Germany, and Finland for structural steel and drive system integration. Permanent magnet motors and variable frequency drives draw from Japanese and German component specialists, creating single-source vulnerability for crane builders lacking dual-source agreements. Tariff exposure on Chinese steel imports into the EU and USA adds compliance cost layers. Distribution runs through OEM-direct channels for large installations and specialized industrial distributors for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gantry crane market functions as a regulatory compounder, with the EU F-Gas Regulation and IMO 2023 Carbon Intensity Indicator forcing harbor operators into compressed replacement cycles that favor electrified equipment suppliers.
For Market Incumbents: Extend predictive maintenance service networks into India and Southeast Asia before Adani Ports and regional privatization programs lock in vendor relationships. Backward integration into permanent magnet motor production reduces exposure to Japanese supply concentration. Bundle vibration sensor analytics with new equipment sales to capture lifetime value beyond initial capital transactions and defend against third-party engineering firms unbundling maintenance obligations. For New Entrants and Emerging Players: Autonomous positioning software for container terminals offers entry leverage into Singapore and Rotterdam where digital twin deployment is accelerating. Target portable gantry crane configurations below 10-ton capacity for German and Japanese manufacturing maintenance departments seeking flexible deployment without permanent infrastructure. Pursue crane-as-a-service revenue models that separate equipment ownership from operational risk, appealing to greenfield port developments in Brazil and the UAE lacking legacy vendor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional service networks because electromechanical technician scarcity forces terminal operators toward OEM maintenance contracts that generate recurring revenue streams. Platform consolidation across predictive maintenance software and aftermarket parts distribution captures margin expansion as equipment fleets electrify. Monitor IMO carbon intensity penalty enforcement as the inflection signal for accelerated diesel-hydraulic fleet retirement and replacement demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Systems | Captive permanent magnet motor production insulates Konecranes and Liebherr from Japanese supply bottlenecks. |
| Predictive Maintenance Platform Launch | Vibration sensor integration with cloud analytics enables Demag Cranes to unbundle traditional procurement relationships. |
| India Port Privatization Partnership | Adani Ports concession agreements create procurement windows for European equipment suppliers entering container terminal expansion. |
| Air-Cooled Transformer Redesign | Elimination of hydrofluorocarbon refrigerants addresses EU F-Gas Regulation compliance for Northern European port installations. |
| Modular Kit Standardization | Containerized leg and beam sections reduce on-site assembly time for remote deployment in Jiangsu and Guangdong shipyards. |
Research Approach
Multiple input streams — structured interviews with port authority engineering directors, OEM procurement teams, and aftermarket service heads; customs and trade flow databases; SEC filings and EU Machinery Directive implementation records — were reconciled through bottom-up equipment shipment tracking and top-down terminal capacity expansion analysis.
Historical deployment patterns were cross-referenced against panel input from maintenance directors and plant engineers to model adoption curves across the projection horizon. Segmentation dimensions included product type mobility configuration, power transmission architecture, end-use operational intensity, and regional regulatory cluster. CAGRs were derived from equipment order backlogs and port infrastructure investment pipelines, with steel price volatility and battery energy density constraints incorporated as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO decarbonization enforcement timing and China shipyard expansion program continuity. Forecasts reflect documented assumptions around electrification technology cost curves and certification timeline standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Precision Gearbox Machinery Market