
 Welding Equipment Market | 2026-2036
Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Equipment Market Intelligence
Specialized equipment manufacturing in Europe is rebalancing the supply chain away from commoditized Asian production. Lincoln Electric sustains its market position through a vast distribution network and application support. ESAB competes by offering a broad portfolio covering multiple welding and cutting technologies. Fronius International differentiates itself with advanced solutions in robotic and automated welding systems.
Welding equipment comprises devices that use electrical current or gas flames to generate sufficient heat for joining materials, primarily metals. These systems include power sources, such as inverters with specific amperage ratings, and mechanisms for delivering filler material. Gas Metal Arc Welding technology dominates due to its versatility and speed in fabrication shops. Applications like pipeline construction and aerospace fabrication demand more specialized technologies such as Submerged Arc Welding for high deposition rates.
Regulatory frameworks, including OSHA standards in the United States and CE marking directives in Europe, mandate safety features and fume extraction capabilities. In China, compliance with GB standards for electrical safety and performance is essential for market access. Vendor selection will increasingly hinge on the ability to integrate equipment with automated and robotic manufacturing workflows.
Market Dynamics
The fundamental dynamic shaping the welding equipment market is the industrial transition toward automated and robotic systems. This shift is driven by demands for higher precision and productivity, particularly in sectors like aerospace and heavy machinery manufacturing, where joint integrity and production speed are critical competitive factors.
Growth Catalysts
- Robotic System Integration:The incorporation of advanced sensors and machine vision into robotic welding arms enhances quality assurance and throughput, meeting the stringent requirements of the automotive and electronics fabrication industries.
- Infrastructure Investment:Government-led infrastructure projects, especially in North America and India, stimulate demand for high-deposition welding technologies like Submerged Arc Welding for constructing bridges, pipelines, and public utilities.
- Shipbuilding Expansion:Concentrated industrial activity in China's coastal regions, specifically within its expanding shipbuilding sector, creates sustained demand for heavy-duty Gas Metal Arc Welding and Flux-Cored Arc Welding equipment.
Market Restraints
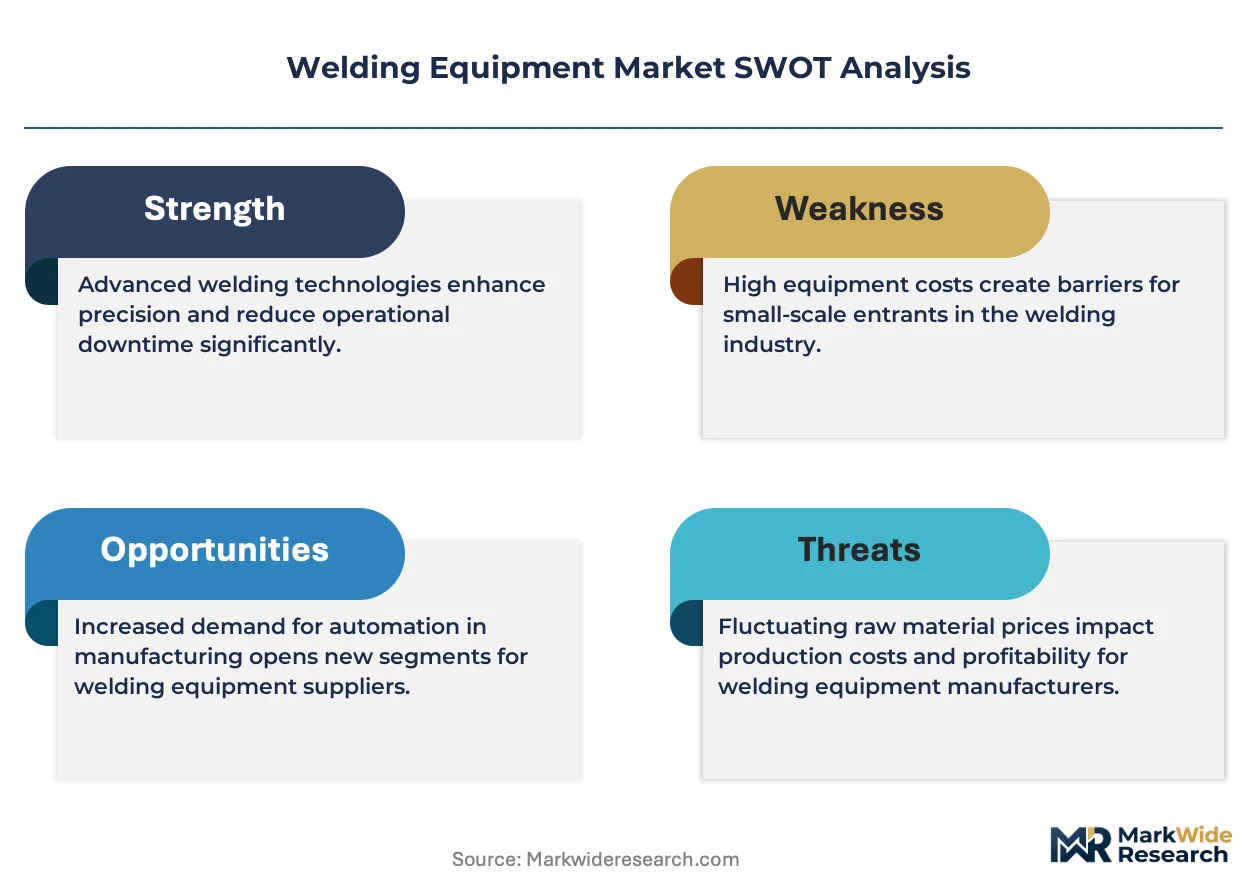
- Input Material Volatility:Price fluctuations in key commodities, including copper for cables and rare earth elements for inverter power sources, create margin pressure and unpredictable equipment costs for manufacturers and end-users.
- Advanced Alloy Complexity:The growing use of high-strength, lightweight alloys in aerospace and automotive applications presents a technical barrier, as these materials require specialized, often expensive, welding processes to avoid compromising structural integrity.
- Regulatory Compliance Costs:The need to meet divergent safety standards, such as OSHA requirements in the US and CE marking directives in Europe for fume extraction, increases design complexity and cost for global manufacturers.
Strategic Opportunities
- Additive Manufacturing:The emergence of Wire Arc Additive Manufacturing (WAAM) as a method for producing large metal parts creates a new application frontier for welding power sources and wire feed systems, moving beyond traditional joining.
- Service-Oriented Models:Developing equipment-as-a-service (EaaS) or lease-based models for automated welding cells can lower the barrier to entry for small and medium-sized enterprises hesitant about high upfront capital expenditure.
- AI-Powered Quality Control:Integrating artificial intelligence for real-time analysis of weld-pool data offers a significant opportunity to automate inspection, reduce defect rates, and provide auditable quality records for critical applications.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of certified welders and, more critically, technicians skilled in programming and maintaining robotic welding systems, limits the effective deployment and productivity of advanced automation.
- System Integration Complexity:Ensuring seamless interoperability between new, data-rich welding equipment and legacy factory management software or older production line machinery poses a significant technical and operational hurdle for many industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Equipment Market |
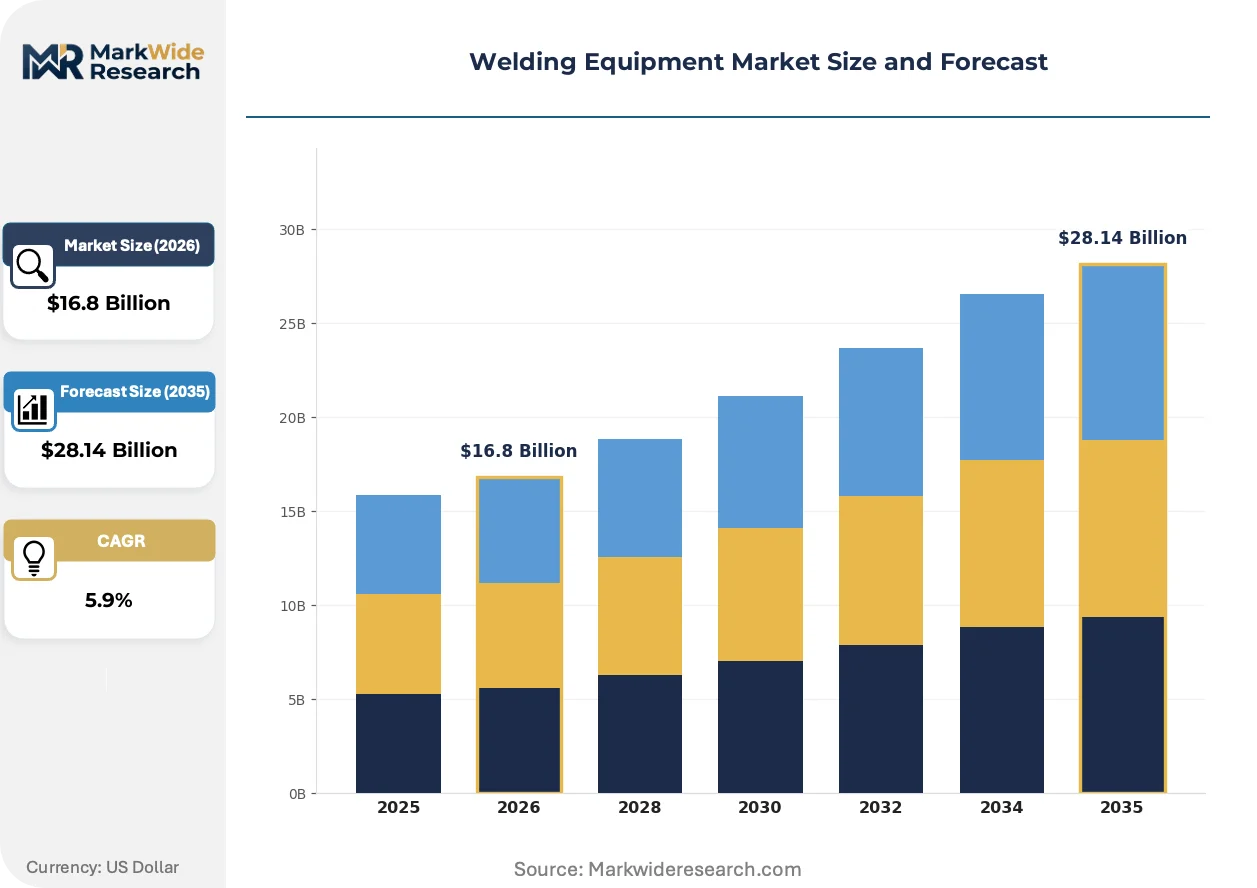
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $28.14 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Welders, MIG Welders, TIG Welders, Spot Welders, Plasma Cutters Technology: Gas Metal Arc Welding, Shielded Metal Arc Welding, Gas Tungsten Arc Welding, Submerged Arc Welding, Electron Beam Welding Application: Shipbuilding, Aerospace Fabrication, Pipeline Construction, Structural Steel, Heavy Machinery Manufacturing End User: Fabrication Shops, Construction Companies, Metal Processing Units, Energy Sector Providers, Defense Contractors |
| Companies Covered | Fronius International, Panasonic Welding Systems, Lincoln Electric, Hobart Welding Products, Kemppi, Miller Electric, Illinois Tool Works, Hypertherm, ESAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Equipment Market Strategic Shifts & Innovations
The convergence of digital technologies with traditional welding processes is defining the market's innovation trajectory. This evolution moves equipment from being a simple fabrication tool to becoming an intelligent node within a connected manufacturing ecosystem, prioritizing data generation and process control.
Inverter-based power sources provide a highly stable and controllable electrical current with significant energy efficiency. Fabrication shops and mobile repair services are rapidly adopting these compact systems due to their portability and superior arc characteristics. The lightweight and precise nature of inverter technology is overtaking older, heavier transformer-based machines across a majority of manual and semi-automated welding applications.
European Union directives, particularly CE marking requirements that mandate adherence to strict occupational safety standards for fume exposure, are driving equipment design. This forces manufacturers to engineer integrated fume extraction capabilities directly into welding guns or offer compatible high-efficiency ventilation units. The European heavy fabrication and manufacturing sectors are most affected, prompting an upgrade cycle away from non-compliant legacy equipment.
Buying decisions are increasingly based on an equipment's data connectivity and integration potential, rather than solely on its amperage or duty cycle. This shift disrupts traditional sales channels that focused on hardware, creating an advantage for vendors who provide comprehensive software and system integration support. This behavior is most pronounced in the global automotive sector, where process traceability for safety-critical components is a non-negotiable requirement.
Welding Equipment Market Segmentation
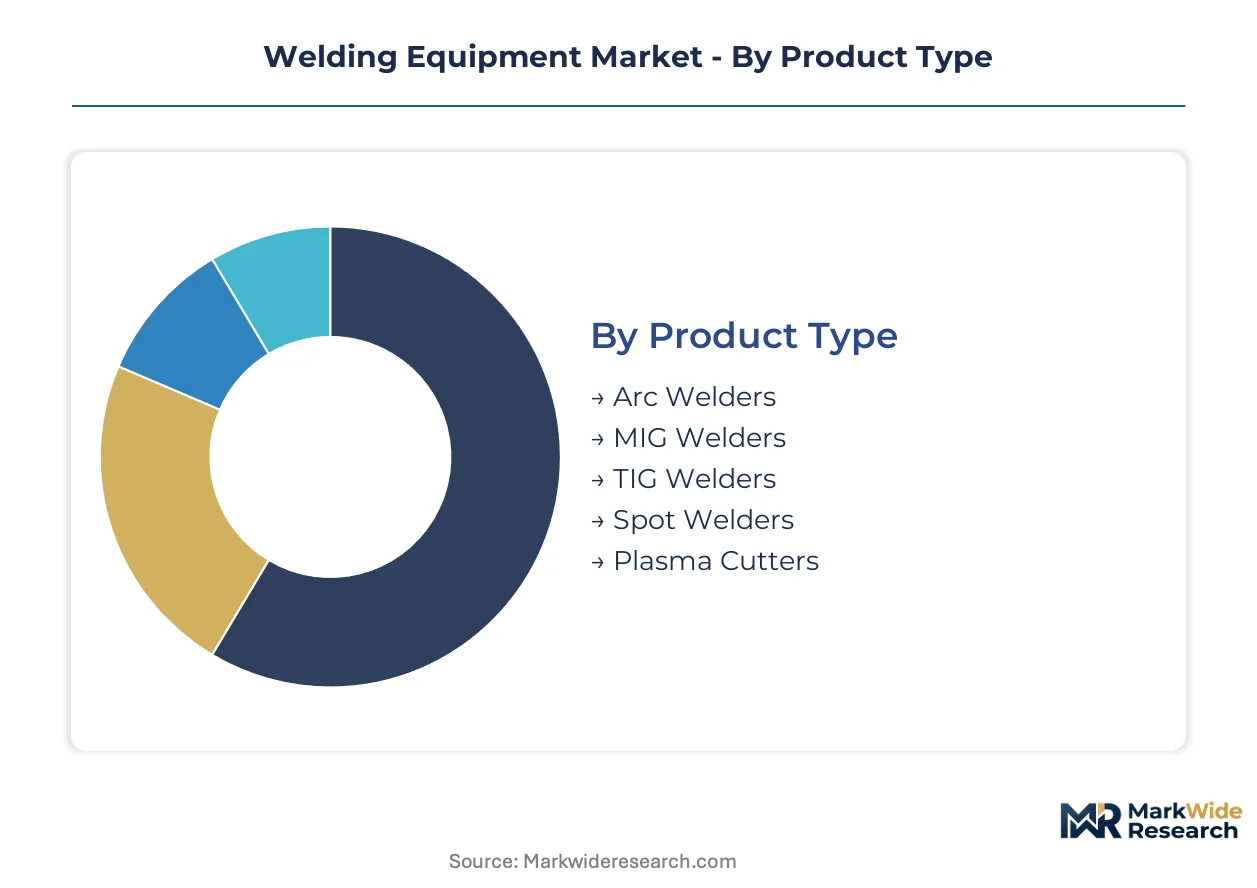
The Welding Equipment Market's diverse landscape necessitates a granular understanding of its components to effectively address evolving industrial demands. This segmentation analysis dissects the market by product, technology, application, and end-user, highlighting critical differentiators and areas of concentrated value. Precise market categorization aids strategic planning.
Product Type:
The upgrade and replacement cycle for welding equipment is significantly influenced by product types required for modern fabrication processes.
- Arc Welders:Arc Welders generate heat via an electric arc, melting and fusing metals for strong joints. Demand remains robust in general fabrication and construction due to versatility and cost.
- MIG Welders:MIG Welders continuously feed a consumable wire electrode, offering high deposition rates and speed. These systems are critical for automotive and heavy machinery production, where throughput and quality are essential.
- TIG Welders:TIG Welders use a non-consumable tungsten electrode and inert gas, providing precise welds for aerospace applications.
- Spot Welders:Spot Welders join overlapping metal sheets with pressure and electric current, crucial for automotive assembly.
- Plasma Cutters:Plasma Cutters utilize a high-velocity jet of ionized gas to cut conductive materials, used in metal fabrication.
Volume placements concentrate in Arc Welders; faster expansion belongs to MIG Welders.
Technology:
Each welding technology is selected based on specific material requirements, joint configurations, and desired production speeds across industrial applications.
- Gas Metal Arc Welding:Gas Metal Arc Welding (GMAW) employs a continuously fed wire electrode and shielding gas, renowned for speed and versatility. Its efficiency makes it a preferred choice for high-volume automotive and general manufacturing.
- Shielded Metal Arc Welding:Shielded Metal Arc Welding (SMAW) uses a flux-coated electrode, valued for simplicity and outdoor maintenance.
- Gas Tungsten Arc Welding:Gas Tungsten Arc Welding (GTAW) delivers precise, high-quality welds on thin materials, critical for aerospace fabrication.
- Submerged Arc Welding:Submerged Arc Welding (SAW) uses a continuously fed electrode under granular flux, delivering high deposition rates and deep penetration. This technology is indispensable for pipeline construction and shipbuilding, where structural integrity is paramount.
- Electron Beam Welding:Electron Beam Welding (EBW) uses a high-velocity electron beam in a vacuum, producing deep, narrow welds for high-precision aerospace parts.
Gas Metal Arc Welding maintains the largest installed base; Electron Beam Welding expands most quickly for highly specialized applications.
Application:
The volume and complexity of welding operations vary significantly across industrial applications, dictating the type and scale of equipment deployed.
- Shipbuilding:Shipbuilding requires robust, high-deposition welding equipment for large steel plates and complex structures, often demanding Flux-Cored Arc Welding and Submerged Arc Welding. China's coastal industrial zones represent significant demand concentration.
- Aerospace Fabrication:Aerospace Fabrication mandates high-precision welding for lightweight, high-strength alloys, often utilizing Gas Tungsten Arc Welding and electron beam technologies. Stringent quality control and traceability are non-negotiable for critical components.
- Pipeline Construction:Pipeline Construction relies on high-deposition, portable welding solutions for thick-walled pipes in challenging outdoor environments.
- Structural Steel:Structural Steel applications demand durable, efficient welding systems for fabricating beams and trusses in commercial buildings.
- Heavy Machinery Manufacturing:Heavy Machinery Manufacturing requires powerful welding equipment for robust joints in large components, driving demand for high-amperage MIG and Flux-Cored Arc Welding.
Shipbuilding accounts for substantial equipment volume; Aerospace Fabrication gains share fastest due to advanced material requirements.
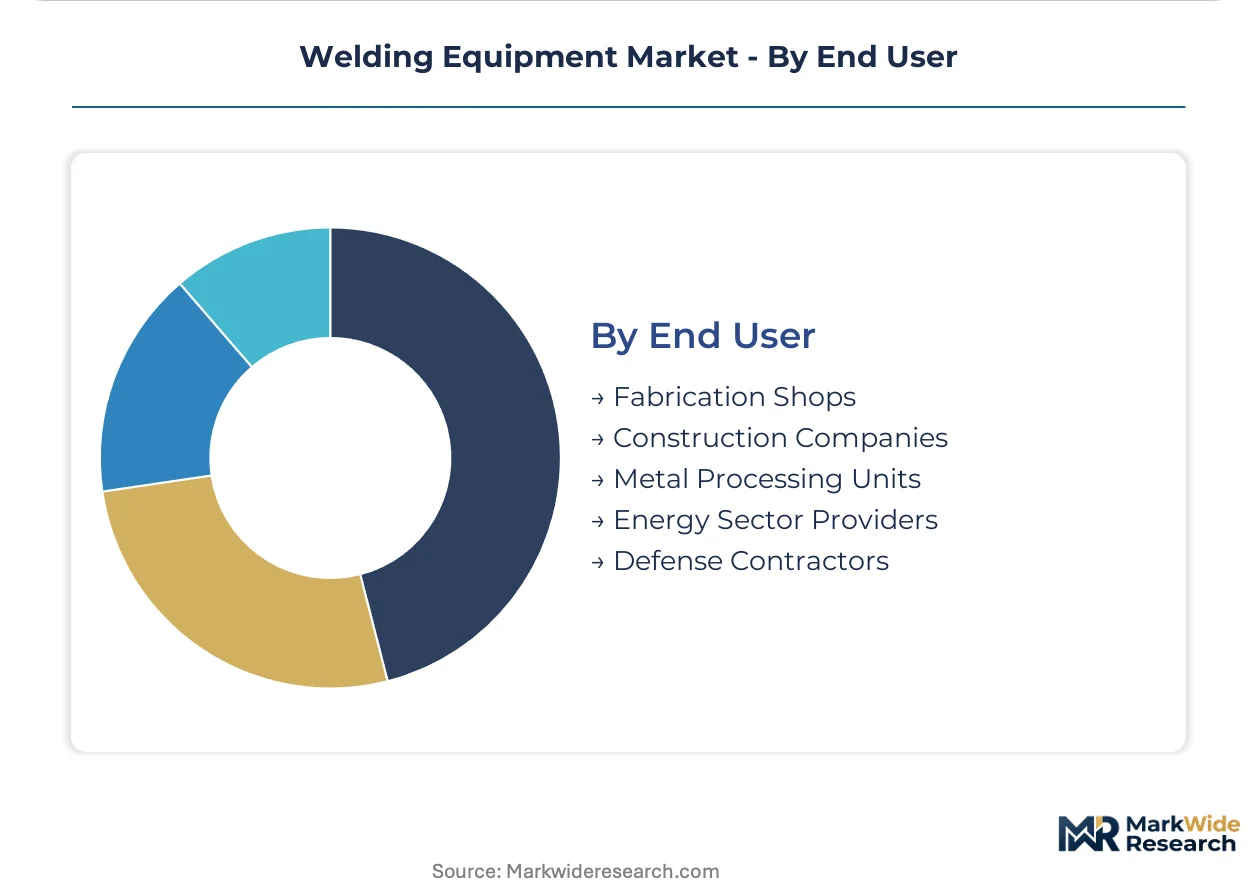
End User:
Different end-user segments exhibit distinct purchasing behaviors and equipment preferences, influenced by operational scale, regulatory environment, and project demands.
- Fabrication Shops:Fabrication Shops require versatile welding equipment for custom projects and short-run production, often prioritizing multi-process machines. Their demand is driven by flexibility across different materials and joint types.
- Construction Companies:Construction Companies utilize robust, portable welding equipment for on-site structural work and infrastructure projects, demanding durability and reliability. Government-led infrastructure investments in North America stimulate significant demand.
- Metal Processing Units:Metal Processing Units integrate welding equipment into automated production lines for high-volume manufacturing, focusing on efficiency.
- Energy Sector Providers:Energy Sector Providers require specialized welding for high-pressure vessels, pipelines, and infrastructure, emphasizing safety.
- Defense Contractors:Defense Contractors demand high-specification welding equipment for military vehicles and aerospace components, adhering to stringent quality standards.
Fabrication Shops consistently drive equipment sales; Energy Sector Providers show the steepest expansion trajectory for specialized high-reliability systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive metal production and processing capabilities, particularly within its coastal industrial zones, anchor substantial global demand for welding equipment. This region's expanding shipbuilding and heavy machinery sectors drive significant volume. Market dynamics are heavily influenced by this concentrated industrial activity.
China
China's shipbuilding expansion and heavy machinery manufacturing propel demand for robust welding solutions. Compliance with GB standards for electrical safety and performance is essential for market access. Coastal industrial zones, especially around Shanghai, represent a significant concentration for heavy-duty Gas Metal Arc Welding.
United States
United States infrastructure investment, alongside aerospace fabrication, stimulates demand for advanced welding technologies. OSHA standards mandate safety features and fume extraction capabilities across all industrial applications. The Gulf Coast region continues to drive demand for pipeline construction and energy sector projects.
Germany
German specialized equipment manufacturing and its automotive sector maintain strong demand for advanced welding systems. CE marking directives enforce strict occupational safety standards, particularly for fume exposure. Industrial hubs like Bavaria are central for the deployment of robotic and automated welding solutions.
India
India's government-led infrastructure projects and its growing manufacturing base increase demand for high-deposition welding equipment. BIS standards ensure product quality and safety for industrial machinery and construction. Manufacturing corridors in Maharashtra drive adoption of technologies like Submerged Arc Welding.
Japan
Japan's automotive manufacturing and high-precision electronics fabrication require specialized welding equipment. Adherence to JIS standards is critical for quality control in critical components. The Tokyo-Nagoya industrial belt sees significant investment in automated and robotic welding applications.
Welding Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced automation solutions and service-oriented models. The market structure exhibits a tiered landscape, with established generalists providing broad portfolios and specialized firms focusing on niche technologies. Competitive moves emphasize portfolio diversification and strategic technology integration to meet evolving industrial demands for precision and productivity.
On the premium-tier vector, Fronius International exemplifies differentiation through advanced solutions in robotic and automated welding systems, catering to high-precision applications. Lincoln Electric, a global player, anchors its market position through a vast distribution network and comprehensive application support, serving a wide customer base. ESAB competes effectively by offering a broad portfolio covering multiple welding and cutting technologies, addressing diverse end-user segments from heavy fabrication to general manufacturing.
| Leading Market Players |
|---|
| Fronius International |
| Panasonic Welding Systems |
| Lincoln Electric |
| Hobart Welding Products |
| Kemppi |
| Miller Electric |
| Illinois Tool Works |
| Hypertherm |
| ESAB |
| Others |
Cost & Logistics Intelligence
Skilled labor concentrations in key manufacturing hubs like Germany and China drive labor-cost differentials, which significantly impact pricing-tier spreads for advanced welding equipment. This dynamic connects directly to equipment manufacturing locations and their associated operational expenses.
Pricing Analysis
Warranty and service bundling often differentiates premium welding equipment offerings from basic models, influencing overall customer value propositions. The market largely operates on a value-based pricing model, where specialized features for aerospace or automated systems command higher prices. Price differentiation often stems from certification levels, such as CE marking compliance for European markets, and the brand premium associated with companies like Fronius International. Pricing softness stems from input material volatility, particularly for copper and rare earth elements. Fabrication shops typically exhibit the highest price sensitivity, while defense contractors prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by large end-users to mitigate supply chain risks within the welding equipment market. Geographic supply concentration for finished equipment is notable in China, Germany, and Japan, reflecting established manufacturing capabilities. Key raw material dependencies include copper for electrical components and rare earth elements for advanced inverter power sources. Commodity price volatility presents a structural risk, directly affecting manufacturing costs for equipment producers. Downstream distribution relies heavily on established networks of specialized industrial distributors and direct sales channels for complex automated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with automated and robotic welding systems rapidly displacing traditional manual processes for enhanced precision and productivity.
For Market Incumbents:Lock in existing customer relationships through superior application support and comprehensive service contracts, especially for complex automated installations. Invest heavily in research and development for AI-powered quality control systems to meet stringent traceability requirements in automotive and aerospace. Counter the threat from new entrants offering Equipment-as-a-Service models by developing competitive lease-based solutions. Expand distribution networks in high-growth regions like India to capture infrastructure investment opportunities.
For New Entrants and Emerging Players:Digital-channel routes, including online configurators and virtual product demonstrations, can effectively penetrate under-served small and medium-sized enterprise segments. Target the Wire Arc Additive Manufacturing application frontier by developing specialized power sources and wire feed systems for large-part metal printing. Focus on offering subscription-based or lease-to-own models for automated welding cells, lowering the barrier to entry for hesitant buyers. The most penetrable segment remains small fabrication shops seeking cost-effective automation upgrades.
For Investors and Strategic Acquirers:Re-rating potential sits with technology-centric firms given the industrial transition towards automated and data-driven welding solutions. Long-term viability is strong, driven by persistent infrastructure development and advanced manufacturing needs. Target acquisition candidates include specialized software providers for weld-pool data analysis and robotic integration specialists. A key signal to watch is the sustained increase in government-led infrastructure project spending in North America and India.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Weld Quality Systems | Automates inspection, reduces defect rates, and provides auditable records for critical applications like aerospace fabrication. |
| Expand Equipment-as-a-Service Offerings | Lowers upfront capital expenditure for SMEs, accelerating adoption of advanced automated welding solutions. |
| Invest in Wire Arc Additive Manufacturing Technology | Captures a new application frontier for large metal part production, moving beyond traditional joining processes. |
| Strengthen Global Distribution Networks | Ensures broad market reach and application support, critical for maintaining market position against specialized competitors. |
| Enhance Robotic System Integration Capabilities | Addresses the growing demand for higher precision and productivity in automotive and heavy machinery manufacturing. |
Research Approach
Multi-period observation of technology adoption rates and regional infrastructure spending anchored the trend analysis, supplemented by interviews with industry stakeholders. This approach combined extensive primary research with secondary validation to ensure robust data integrity. Stakeholders included welding engineers, procurement managers at heavy fabrication shops, R&D leads at equipment manufacturers, and regulatory compliance officers. Secondary data sources encompassed industry association reports, government manufacturing statistics, and relevant patent databases. Bottom-up and top-down triangulation refined all quantitative and qualitative insights.
Segment-weighting across product type, technology, application, end-user, and key geographic markets informed the analytical framework over the projection horizon. This granular approach allowed for precise modeling of demand drivers and competitive dynamics. Compound annual growth rates were derived from historical data analysis and future market projections, accounting for technological advancements and regulatory shifts. Industry-specific forecast inputs included global shipbuilding orders and aerospace production rates, reflecting critical demand sectors.
The model holds under current macroeconomic conditions and anticipated technological trajectories; deviation in raw material price stability or skilled labor availability would shift the outlook materially. Forecasts reflect assumptions regarding continued industrial automation and infrastructure investment. Deviation in global trade policy could also significantly impact supply chain dynamics and market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Australia Concrete Pump Market