
 Heavy Duty IBC Market | 2026-2036
Heavy Duty IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty IBC Market Foresight
Direct-to-manufacturer supply contracts is rewriting how heavy duty IBC volumes move across industrial regions. SCHÜTZ GmbH & Co. KGaA leverages its German manufacturing base to dominate European chemical sector replenishment cycles. Greif Inc. sustains broad geographic coverage through its North American steel drum and IBC parallel production network. Mauser Packaging Solutions anchors reusable container pooling services across multiple industrial corridors.
Heavy duty IBCs are rigid intermediate bulk containers engineered to withstand repeated filling, transport, and cleaning cycles under loads exceeding standard IBC ratings, typically constructed from high-density polyethylene, galvanized steel, or composite laminates with UN-certified stacking and drop-test performance. Their primary purpose is safe, efficient bulk handling of chemicals, food ingredients, and pharmaceutical intermediates across multi-modal logistics chains. Metal IBCs command premium positioning in flammable and corrosive chemical applications where UN certification and fire resistance justify higher unit economics. Plastic IBCs lead in food-grade and non-hazardous chemical segments where weight reduction and corrosion immunity drive procurement decisions. Folding IBCs represent the fastest-expanding structural category as collapsible designs cut return freight costs for distant supply loops.
EPA hazardous waste manifest rules, UN Model Regulations on dangerous goods transport, and FDA food contact material standards collectively determine which IBC constructions qualify for cross-border industrial use. REACH compliance in Europe and evolving state-level chemical disclosure laws in the US add parallel compliance layers that filter supplier eligibility. Stakeholders must monitor how pending revisions to UN performance testing protocols and emerging per- and polyfluoroalkyl substance restrictions reshape material specifications and manufacturing qualification timelines.
Market Dynamics
Closed-loop pooling systems are displacing single-use packaging across chemical corridors, forcing converters to engineer higher-cycle containers while logistics operators consolidate return infrastructure around dense industrial clusters.
Growth Catalysts
- UN Model Regulations:Stricter dangerous goods transport protocols mandate UN-certified composite and metal constructions for cross-border chemical shipments, disqualifying lower-performance alternatives from hazardous material routes.
- Food-grade HDPE formulations:Corrosion-immune plastic IBCs capture pharmaceutical intermediate handling where metal contamination risks exceed tolerance thresholds.
- Ludwigshafen-Leverkusen corridor:Dense BASF and Bayer facility networks demonstrate operational proof for multi-modal reusable container systems, creating reference architecture for replication.
Market Restraints
- Galvanized steel input volatility:Zinc price swings compress margin predictability for metal IBC fabricators serving flammable chemical segments.
- REACH compliance timelines:ECHA substance evaluation protocols extend material qualification cycles, delaying new composite laminate introductions by 18-24 months.
- Folding container durability skepticism:Collapsible designs face adoption friction in high-frequency cleaning environments where hinge fatigue concerns persist.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO-compliant container pooling remains underdeveloped around Mumbai and Hyderabad bulk drug production zones.
- RFID-embedded tracking convergence:Integration of passive sensor arrays with composite wall structures enables real-time location and condition monitoring for high-value chemical shipments.
- EU Green Deal circularity mandates:Packaging waste reduction targets create procurement preference for reusable IBCs in member state public chemical purchasing.
Industry Challenges
- Multi-material welding certification:Composite IBC fabricators face scarce technician pools qualified for HDPE-steel hybrid seam validation under UN pressure-test protocols.
- Legacy ERP integration:Pooling operators struggle to synchronize container tracking data with customer inventory management systems, delaying automated replenishment deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty IBC Market |
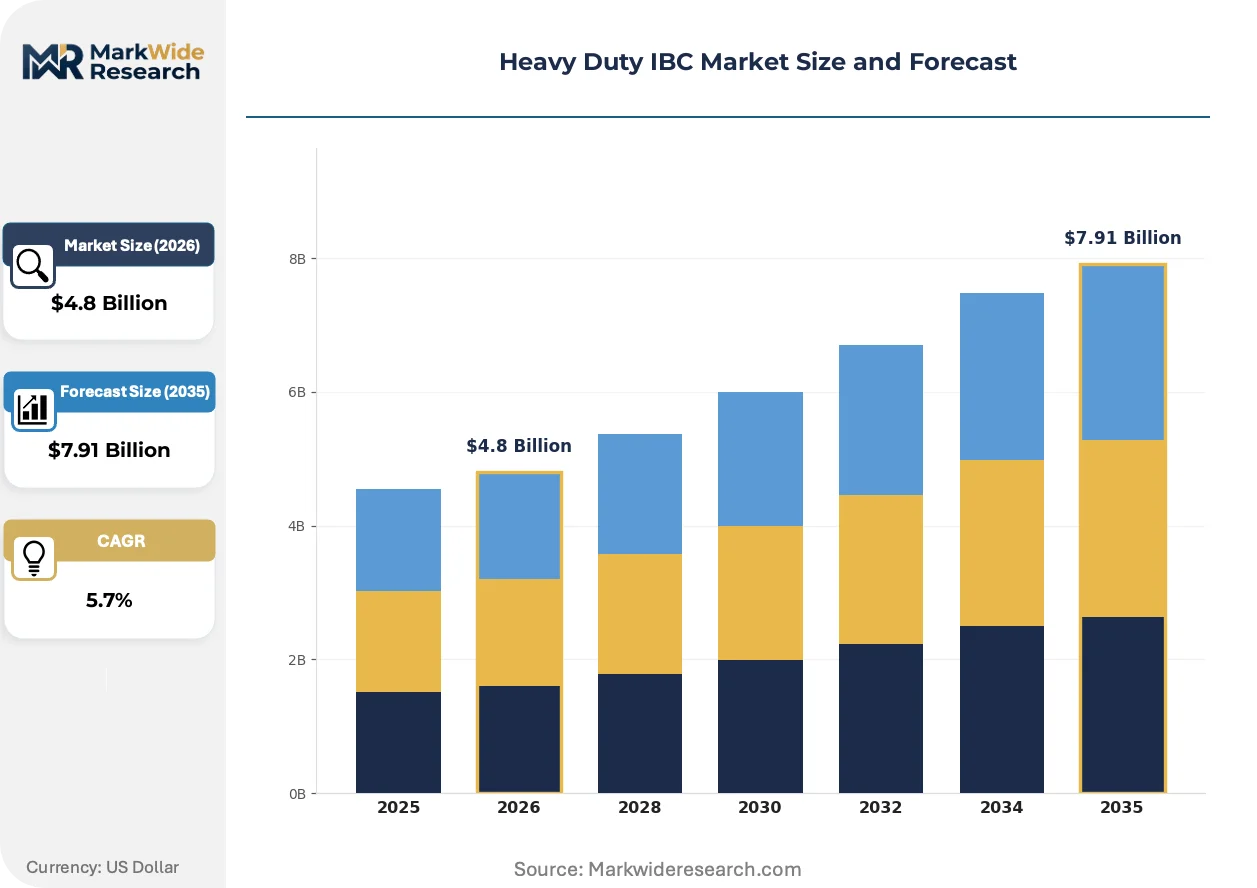
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic IBCs, Metal IBCs, Composite IBCs, Folding IBCs End Use: Food & Beverage, Chemicals, Pharmaceuticals, Oil & Gas Capacity: 1000 Liters, 1500 Liters, 2000 Liters, 2500 Liters Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | SCHÜTZ GmbH & Co. KGaA, Mauser Packaging Solutions, Greif Inc., Snyder Industries, Thielmann, SCHÄFER Container Systems, Precision IBC, RPP Containers, TPS Rental Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty IBC Market Shifts & Advancements
Material science advances and regulatory ratcheting are compressing product lifecycles while digital traceability requirements reshape competitive differentiation around data-rich container platforms rather than commodity fabrication alone.
Collapsible composite IBCs with integrated hinge mechanisms are collapsing return freight economics for transcontinental supply loops. Chemical distributors serving Southeast Asian manufacturing outposts from German production bases adopt folding designs to cut empty container repositioning costs by half. The technology is collapsing the traditional radius limitation on profitable pooling operations, extending viable service territories from 500 to 2,000 kilometer loops.
REACH authorization list expansion is forcing substitution of legacy plasticizers in HDPE liner formulations. ECHA SVHC candidate list updates trigger reformulation cycles every 24-36 months, compelling resin suppliers to maintain parallel certification tracks. European pharmaceutical intermediate handlers face the most acute compliance pressure, accelerating migration toward pre-certified food-grade material streams.
Leasing-based procurement models displace capital purchase for mid-volume chemical processors. Third-party pooling operators assume container asset ownership, charging per-trip fees that transfer utilization risk from chemical manufacturers to logistics providers. German Mittelstand chemical specialists exhibit the fastest adoption velocity, preferring operational expenditure treatment for packaging assets over balance-sheet burden.
Heavy Duty IBC Market Segmentation
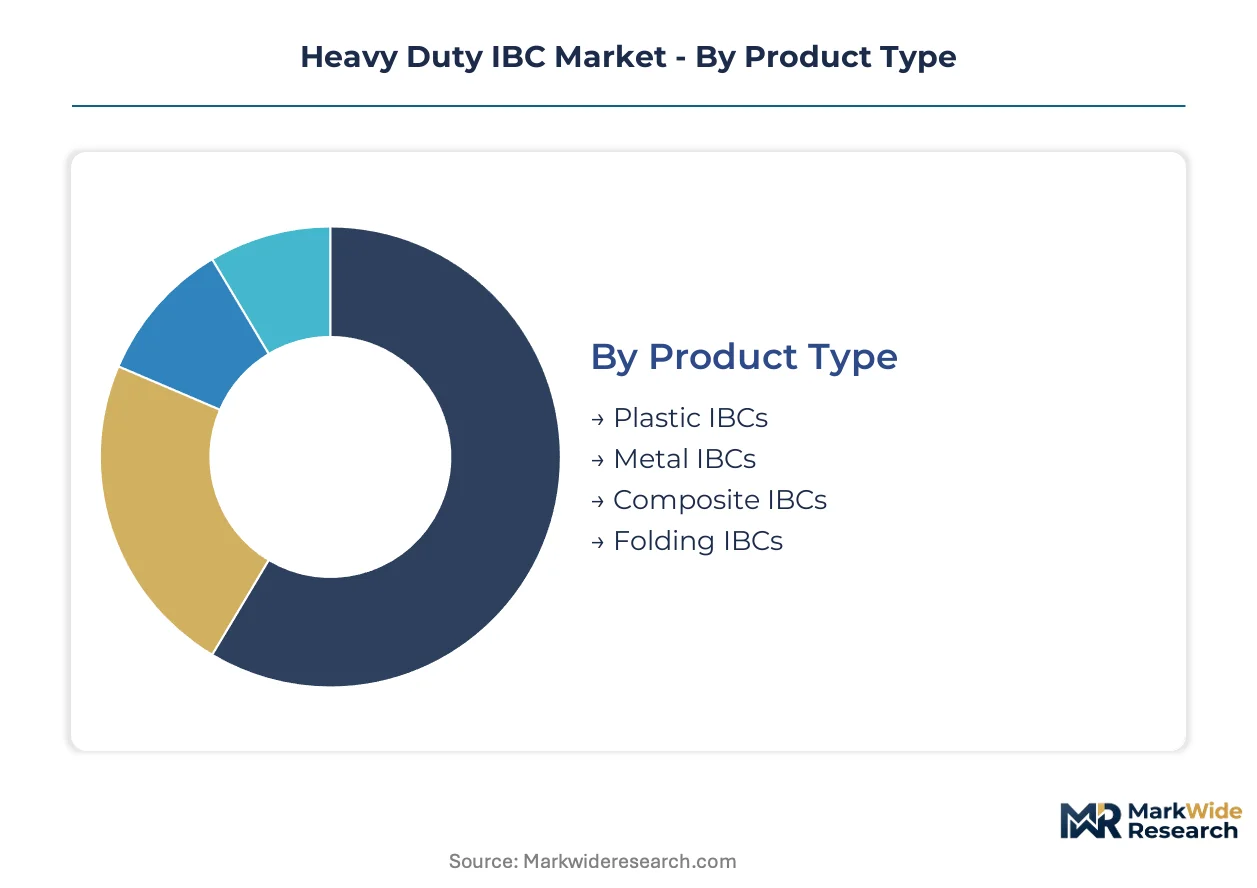
Heavy duty IBC segmentation reveals how material selection, application requirements, and procurement channels fragment demand across distinct technical and commercial profiles. Each dimension carries specific compliance burdens and operational constraints that shape supplier positioning.
Product Type:
Material composition defines performance thresholds across hazardous and non-hazardous handling environments, with cost tier and certification requirements driving procurement sorting.
- Plastic IBCs:High-density polyethylene constructions dominate food-grade and pharmaceutical intermediate applications where metal contamination risks exceed tolerance thresholds. FDA food contact material standards and EFSA compliance requirements filter supplier eligibility for European and US pharmaceutical corridors.
- Metal IBCs:Galvanized steel fabrications command premium positioning in flammable and corrosive chemical segments where UN certification and fire resistance justify elevated unit economics. German chemical manufacturers around Ludwigshafen and Leverkusen specify metal constructions for closed-loop pooling systems handling hazardous intermediates.
- Composite IBCs:HDPE-steel hybrid laminates balance weight reduction with structural integrity for multi-modal chemical transport.
- Folding IBCs:Collapsible hinge mechanisms cut return freight costs for transcontinental supply loops serving Southeast Asian manufacturing outposts.
Metal IBCs command the established base. The steepest expansion runs through Folding IBCs.
End Use:
Application-specific compliance layers sort demand across regulatory jurisdictions, with hazardous material handling imposing the most stringent construction requirements.
- Chemicals:UN Model Regulations on dangerous goods transport mandate certified composite and metal constructions for cross-border shipments, disqualifying lower-performance alternatives. EPA hazardous waste manifest rules and REACH compliance in Europe add parallel qualification layers that extend material certification timelines.
- Pharmaceuticals:EMA and FDA standards for sterile intermediate handling drive specification toward corrosion-immune plastic formulations with validated cleaning protocols. CDSCO requirements in India and PMDA standards in Japan create additional regional compliance filters for container suppliers.
- Food & Beverage:FDA and EFSA food contact material standards govern liner formulations, with REACH SVHC list updates triggering reformulation cycles.
- Oil & Gas:Flammable liquid handling specifications favor metal constructions with fire-resistant properties for upstream and midstream logistics.
Chemical applications anchor volume concentration. Pharmaceutical handling shows the sharpest specification escalation.
Capacity:
Volume scale determines modal compatibility and pooling economics, with standardization pressures strongest in chemical corridor operations.
- 1000 Liters:The modal standard for European and North American chemical logistics, optimized for truck and rail compatibility. BASF and Bayer facility networks in Germany standardize on this capacity for dense closed-loop replenishment cycles.
- 1500 Liters:Intermediate scale capturing pharmaceutical batch processing where production lot sizes exceed 1000-liter increments but fall short of full 2000-liter vessel utilization.
- 2000 Liters:Bulk chemical transport scale favored for ocean freight consolidation and large-volume food ingredient handling.
- 2500 Liters:Maximum single-unit capacity for specialized industrial chemical and oil and gas applications with dedicated handling equipment.
1000-liter units dominate installed base. 1500-liter configurations are climbing fastest in pharmaceutical adoption.
Distribution Channel:
Procurement pathway selection reflects customer scale, technical support requirements, and asset ownership preferences across leasing and purchase models.
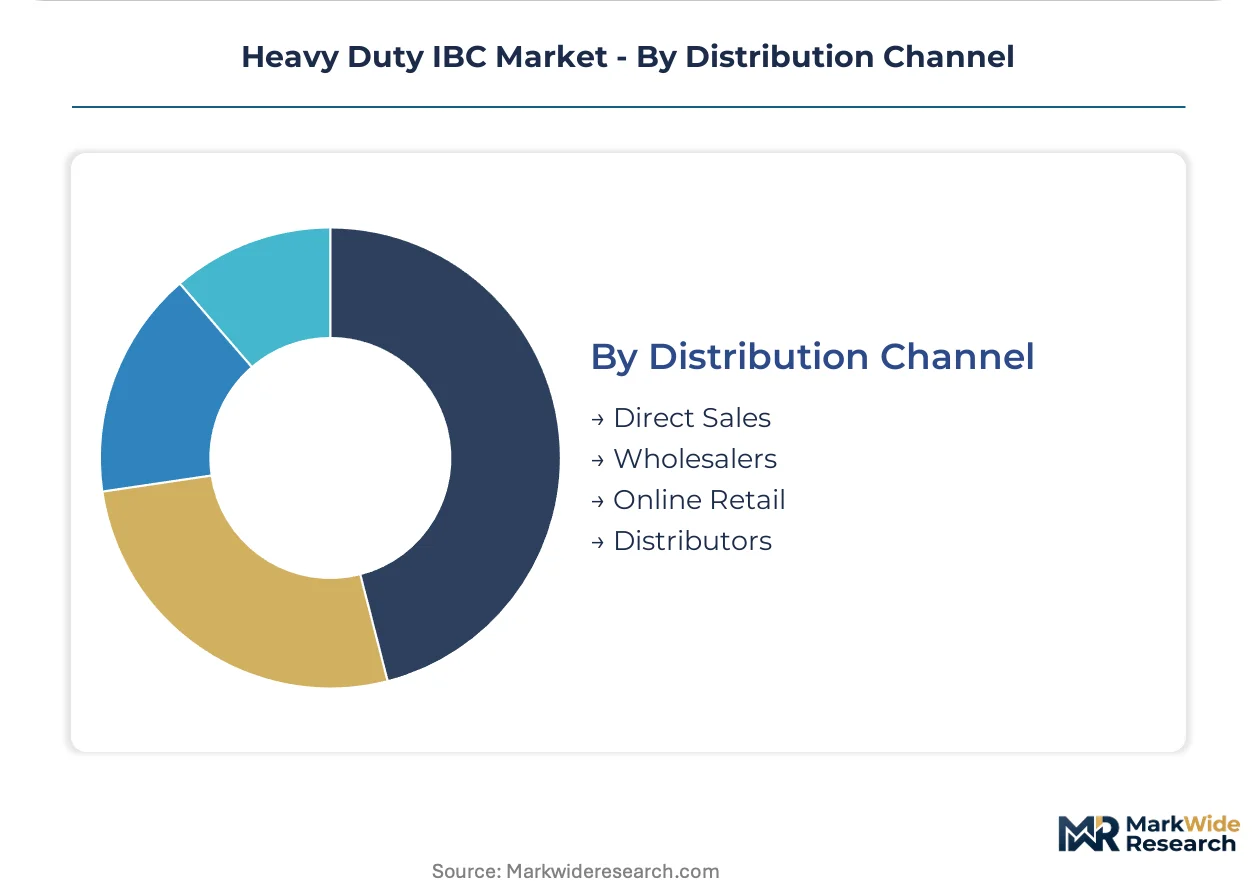
- Direct Sales:Manufacturer-to-processor contracts dominate large chemical and pharmaceutical operations requiring customized pooling arrangements and integrated tracking systems. SCHÜTZ GmbH and Greif Inc. leverage direct relationships for European and North American chemical corridor coverage.
- Distributors:Regional inventory positioning serves mid-volume processors with shorter lead time requirements and standardized specification needs.
- Wholesalers:Aggregated procurement channels capture smaller food and beverage processors with less specialized handling requirements.
- Online Retail:Digital procurement platforms emerge for standardized plastic IBC replacement and accessory purchases in non-hazardous segments.
Direct sales structures capture the premium tier. Distributor networks are gaining share fastest among mid-scale chemical processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites European heavy duty IBC circulation density, while the Houston Ship Channel and Yangtze River Delta port complexes anchor transatlantic and Asia-Pacific chemical logistics respectively.
Germany
BASF and Bayer facility networks around Ludwigshafen and Leverkusen operate dense closed-loop pooling systems with multi-modal rail-truck interchange. ECHA REACH authorization protocols extend material qualification timelines for composite laminate introductions. The North Rhine-Westphalia chemical corridor demonstrates operational proof for reusable container architectures replicable across industrial clusters.
United States
EPA hazardous waste manifest rules and OSHA process safety standards filter supplier eligibility for cross-border chemical shipments. Gulf Coast petrochemical complexes along the Houston Ship Channel drive demand for UN-certified metal constructions in flammable liquid handling. Texas and Louisiana facility networks favor direct-to-manufacturer supply contracts with integrated tracking systems.
China
NMPA pharmaceutical container standards and MIIT industrial packaging regulations shape procurement specifications for bulk drug intermediate handling. Yangtze River Delta chemical manufacturers around Shanghai and Ningbo expand reusable container fleets to reduce single-use packaging waste. SAMR quality certification requirements accelerate migration toward pre-certified material streams.
India
CDSCO-compliant container pooling remains underdeveloped around Mumbai and Hyderabad bulk drug production zones despite pharmaceutical export growth. FSSAI food contact material standards govern liner formulations for food-grade HDPE applications. Gujarat chemical processors show fastest adoption velocity for leasing-based procurement models transferring utilization risk to logistics providers.
Japan
METI circular economy guidelines and PMDA pharmaceutical intermediate handling standards drive specification toward corrosion-immune plastic formulations. Osaka-Kobe industrial corridor manufacturers prioritize validated cleaning protocols for sterile applications. JIS standards for dangerous goods transport containers mandate performance testing alignment with UN Model Regulations.
Heavy Duty IBC Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated multinational fabricators with captive pooling networks, regional specialists commanding dense corridor coverage, and technology-focused entrants embedding digital traceability. Strategic archetypes include vertically integrated packaging conglomerates, independent pooling operators, and composite material innovators. Dominant competitive moves encompass geographic expansion through distributor acquisition and backward integration into resin compounding.
Among German fabricators, SCHÜTZ GmbH & Co. KGaA occupies a position exemplifying integrated production-pooling capability, while Greif Inc. represents North American scale-driven coverage across steel drum and IBC parallel networks. Mauser Packaging Solutions anchors the independent pooling operator archetype with multi-corridor service infrastructure.
| Leading Market Players |
|---|
| SCHÜTZ GmbH & Co. KGaA |
| Mauser Packaging Solutions |
| Greif Inc. |
| Snyder Industries |
| Thielmann |
| SCHÄFER Container Systems |
| Precision IBC |
| RPP Containers |
| TPS Rental Systems |
| Others |
Supply & Pricing Matrix
Galvanized steel sheet mills in Germany and China concentrate feedstock supply for metal IBC fabricators, anchoring margin pools with converters serving UN-certified hazardous chemical segments while plastic resin compounding in the US Gulf Coast shapes HDPE container economics.
Pricing Analysis
Volume-discount tiering structures dominate procurement for chemical processors operating closed-loop pooling systems. Three-tier pricing separates UN-certified metal constructions from standard composite grades and economy plastic alternatives. Zinc price volatility compresses margin predictability for galvanized steel fabricators. Mid-volume pharmaceutical handlers exhibit highest price sensitivity due to leasing-model adoption.
Supply Chain Analysis
HDPE resin feedstock draws from petrochemical complexes in the United States, Saudi Arabia, and South Korea. Galvanized steel sheet and composite laminate adhesives constitute secondary material anchors. Single-source vulnerability concentrates around specialized hinge mechanisms for folding IBC designs. Distribution runs through direct manufacturer contracts integrated with pooling operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy duty IBC demand sits in early-cycle expansion as closed-loop pooling adoption accelerates across chemical corridors, with regulatory ratcheting on single-use packaging waste creating durable tailwinds for reusable container penetration.
For Market Incumbents: Entrench pooling infrastructure density around Ludwigshafen-Leverkusen and Houston Ship Channel corridors to defend against independent logistics operators capturing mid-volume chemical processors. Deepen backward integration into HDPE resin compounding to offset feedstock cost volatility. Prioritize RFID-embedded tracking certification to maintain differentiation from commodity fabricators.
For New Entrants and Emerging Players: Establish a beachhead in CDSCO-compliant pharmaceutical container pooling around Mumbai and Hyderabad production zones where incumbent coverage remains sparse. Target folding IBC designs for Southeast Asian manufacturing outposts served by European chemical distributors. Lead with per-trip leasing models that transfer utilization risk from processors to logistics providers.
For Investors and Strategic Acquirers: Capital is best deployed toward independent pooling operators with multi-corridor service infrastructure and established customer integration protocols. Long-term viability hinges on regulatory persistence for reusable packaging mandates. Watch for ECHA SVHC list expansion as an inflection signal accelerating food-grade material stream migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds fabrication lines near Rhine-Main-Danube waterway to serve BASF-Bayer corridor density. |
| Backward Integration | Captures HDPE resin compounding margins and insulates against Gulf Coast feedstock volatility. |
| Long-term Supply Agreement | Locks zinc sheet pricing for German metal IBC fabricators serving flammable chemical segments. |
| Joint Venture | Pairs European pooling operators with Indian logistics firms for CDSCO-compliant pharmaceutical coverage. |
| Green Manufacturing Transition | Aligns composite laminate production with EU Green Deal circularity mandates for public procurement preference. |
Research Methodology
A spread of perspectives from chemical plant managers, procurement leads at pharmaceutical manufacturers, distribution channel partners, and technical R&D directors at composite fabricators converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs/trade data, Cefic chemical industry reports, SEC 10-K filings, and UN dangerous goods transport documentation. Bottom-up unit economics and top-down sectoral sizing were triangulated to constrain estimate variance.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include material grade tier, end-use industry, capacity standard, and regional production hub. CAGRs were derived from slope analysis of historical penetration curves adjusted for regulatory inflection timing. Forecast inputs incorporated REACH authorization timeline risk and folding IBC adoption elasticity for transcontinental supply loops.
Sensitivities concentrate around ECHA SVHC list expansion pace and zinc price volatility assumptions. Forecasts reflect documented assumptions on pooling operator consolidation speed and pharmaceutical export growth from Indian bulk drug zones. Cross-checking against Cefic packaging flow statistics and UN dangerous goods shipment manifests is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Earthmover Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Press Brakes Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Scaffold Technology Market