
 Tunnels Design and Construction Market | 2026-2036
Tunnels Design and Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnels Design and Construction Market Insights
ISO 9001 and IRIS certification cycles are redrawing competitive access across the Tunnels Design and Construction Market. Strabag SE leverages its integrated tunneling division to dominate alpine and urban projects across Central Europe. Larsen & Toubro Limited anchors its position through captive manufacturing of tunnel segments and specialized formwork systems in South Asia. China Railway Construction Corporation Limited sustains massive throughput capacity via state-backed procurement pipelines and in-house boring machine fleets.
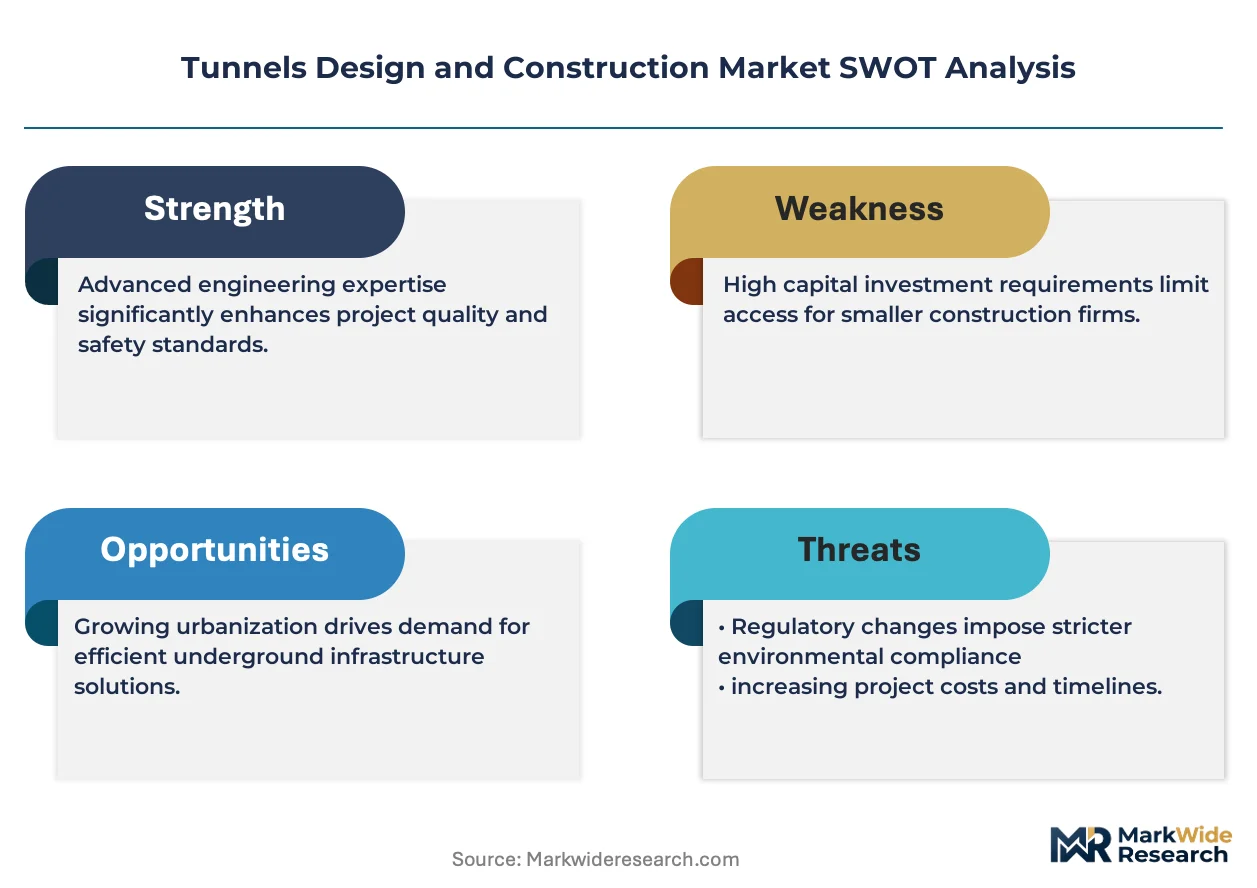
Tunnels Design and Construction encompasses the engineering, excavation, lining, and mechanical installation of subterranean passages designed to withstand hydrostatic pressure, seismic loads, and long-term ground movement, typically employing shotcrete initial support followed by cast-in-place or precast concrete final linings with specified permeability below 10^-12 m/s. Tunnel Boring Machine deployment now leads in urban settings where surface disruption must be minimized, while NATM retains margin advantages in variable geology where flexibility in support sequencing reduces overbreak. Cut-and-cover methods dominate shallow transit corridors but face compressed margins as municipal budgets tighten. Mega Projects concentrate the largest value pools though execution risk escalates with contract duration and geological uncertainty.
FERC guidelines in the United States govern hydroelectric tunnel safety inspections, while OSHA mandates confined-space protocols that directly shape crew sizing and equipment automation decisions. The EU's CSRD disclosure requirements are pushing contractors to quantify embodied carbon in concrete and steel linings, altering material sourcing and mix design specifications. Stakeholders must monitor how evolving geotechnical survey standards and climate-resilience codes reshape pre-qualification thresholds and long-term maintenance liability structures.
Market Dynamics
EU F-Gas Regulation enforcement is compressing contractor margins across long-distance tunnel ventilation contracts while simultaneously accelerating low-carbon cooling system adoption in alpine corridors. This regulatory pressure intersects with procurement concentration among state-backed rail authorities in Asia-Pacific, reshaping competitive access requirements.
Growth Catalysts
- Urban Rail Transit Expansion:Metro authorities in China, India, and Vietnam are tendering underground corridor packages exceeding 50 kilometers per project. These contracts specify NATM and TBM hybrid methodologies to minimize surface disruption in dense urban cores.
- EU CSRD Disclosure Mandate:Corporate Sustainability Reporting Directive requirements are forcing contractors to quantify embodied carbon in concrete and steel linings. This is redirecting material sourcing toward low-clinker cement blends and recycled aggregate suppliers.
- High-Speed Rail Geology:China's mountainous western provinces require extensive bored tunnels through karst and faulted terrain. State procurement pipelines prioritize contractors with captive boring machine fleets and in-house geotechnical expertise.
Market Restraints
- Specialized Equipment Supply Concentration:Herrenknecht and CRCC Heavy Industry dominate large-diameter TBM manufacturing. Lead times for 10+ meter diameter machines now exceed 18 months, constraining project scheduling flexibility.
- Rebar and Cement Price Volatility:Tunnel lining concrete requires sulphate-resistant Portland cement and epoxy-coated rebar. Input cost swings of 15-25 percent within single fiscal years compress fixed-price contract margins.
- Geological Uncertainty Insurance:Variable ground conditions in Himalayan and Andean corridors trigger force majeure disputes. Underwriters now exclude rockburst and methane inflow coverage from standard contractor policies.
Strategic Opportunities
- Digital Twin Integration:Real-time ground monitoring using fiber-optic strain sensing and BIM-integrated convergence analysis is reducing overbreak by 8-12 percent. Early adopters in Swiss and Austrian alpine projects are capturing performance-based contract bonuses.
- India's Suburban Rail Corridors:Mumbai, Bengaluru, and Delhi metro expansions represent underpenetrated demand for shallow cut-and-cover and immersed tube methods. Domestic contractors lack experience in underwater tunneling, creating entry points for specialized foreign joint ventures.
- Japan's Carbon-Neutral Tunnel Mandate:METI guidelines for 2050 net-zero infrastructure are accelerating electric muck haulage and regenerative braking in TBM cutterhead drives. Equipment suppliers with battery-electric portfolios are securing preferred vendor status.
Industry Challenges
- Shotcrete Nozzleman Skill Scarcity:NATM-dependent markets face acute shortages of certified wet-mix spray operators. Training cycles of 18-24 months lag project ramp schedules in Southeast Asia and Latin America.
- ISO 9001 and IRIS Certification Timelines:Pre-qualification for EU rail tenders requires 12-18 month audit cycles. Smaller contractors miss bidding windows while pursuing dual certification tracks.
- Legacy Ventilation System Retrofit Complexity:Existing road tunnels in Italy and Austria require F-Gas-compliant cooling upgrades. Space constraints in 1970s-era cross-sections limit equipment footprint and access for installation crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnels Design and Construction Market |
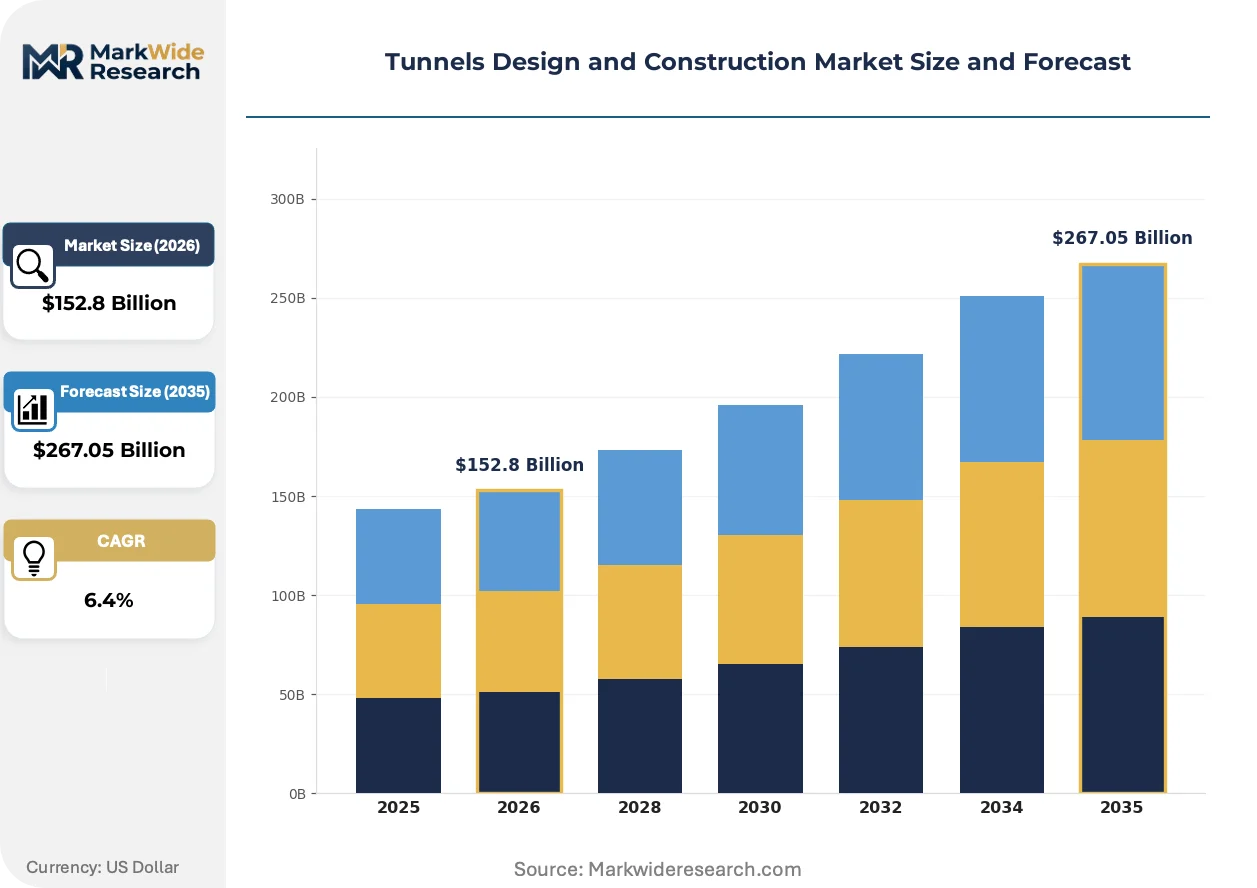
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $267.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sprayed Concrete, Tunnel Boring Machine, Cut-and-Cover, NATM End User: Public Sector, Private Developers, Mining Companies, Transportation Authorities Installation: Onshore, Underground, Offshore, Urban Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Strabag SE, Larsen & Toubro Limited, China Railway Construction Corporation Limited, Kiewit Corporation, Obayashi Corporation, Vinci Construction, Skanska AB, AECOM, Bechtel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnels Design and Construction Market Trends and Innovations
Digitalization of geotechnical workflows is compressing survey-to-bid timelines while embedding predictive ground models directly into construction sequencing. This shift is redistributing value from traditional engineering consultancies toward integrated data-analytics contractors.
Robotic shotcrete application is miniaturizing nozzle positioning systems to traverse confined tunnel headings under 4-meter diameter. Japanese and Austrian contractors are deploying these units in sewer rehabilitation and hydropower penstock projects. The technology is miniaturizing crew footprints in restricted-access headings, reducing ventilation demand and enabling continuous single-shift operations previously requiring multi-team rotation.
EU F-Gas Regulation phase-down schedules are banning hydrofluorocarbon refrigerants in tunnel climate control systems. Contractors must now specify CO2 transcritical heat pumps or ammonia-based chillers in bid documents. Alpine corridor projects in Switzerland and Austria face the steepest compliance curves, with 2027 deadlines forcing early equipment procurement to secure limited supplier capacity.
Asset-owner procurement teams are unbundling long-term maintenance liability from construction contracts. Transport for London and RATP now tender 30-year performance agreements separately from civil works, shifting risk to specialized O&M consortia. This bifurcation is most advanced in UK and French urban transit markets, where concession financing models separate construction equity from operational revenue streams.
Tunnels Design and Construction Market Segmentation
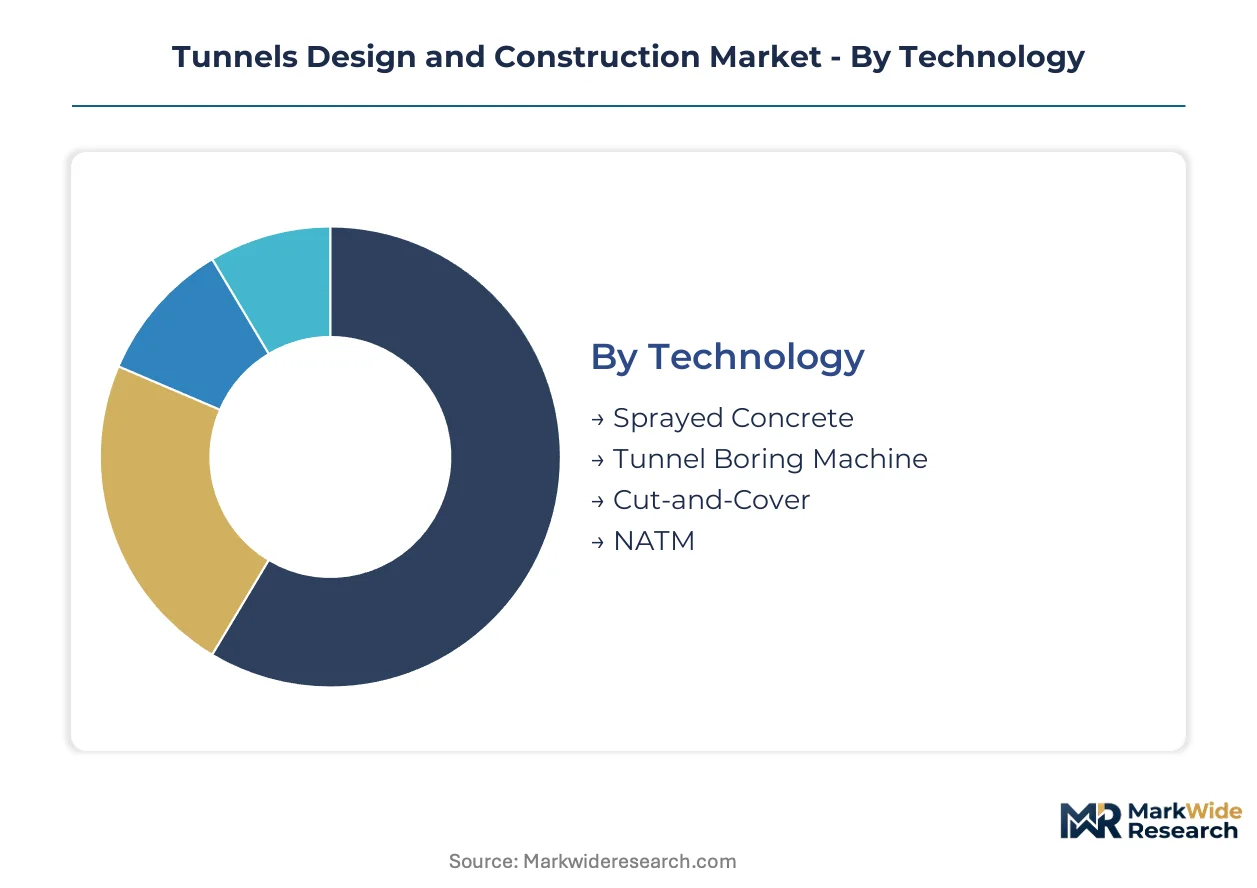
Tunnel construction methods fragment sharply across geology, surface constraints, and owner risk appetite. Technology choice locks in 60-70 percent of lifecycle cost structure, while project size determines contractor eligibility and financing architecture.
Technology:
Margin pools concentrate in mechanized excavation where equipment utilization rates and advance speeds outpace labor-dependent alternatives.
- Sprayed Concrete:Wet-mix shotcrete applied through robotic nozzles forms initial ground support in variable geology. Demand clusters in Himalayan hydropower headrace tunnels where rock mass rating fluctuates kilometer-to-kilometer, requiring adaptive support thickness.
- Tunnel Boring Machine:Full-face mechanized excavation using rotating cutterheads with disc cutters and drag bits. Contracts in China's Sichuan and Yunnan provinces specify dual-mode TBMs for alternating soft ground and hard rock, with state rail authorities mandating captive fleet ownership as pre-qualification criteria.
- Cut-and-Cover:Open-trench excavation with subsequent backfill for shallow urban transit corridors. Mumbai Metro and Bengaluru suburban rail deploy this method in saturated alluvium where groundwater dewatering costs remain manageable.
- NATM:Sequential excavation with immediate shotcrete and rockbolt support in observational methodology. Alpine corridor projects in Austria and Switzerland favor NATM for fault zones where TBM entrapment risk exceeds acceptable thresholds.
Tunnel Boring Machine holds installed capacity. Sprayed Concrete is rotating up the share rankings in hydropower rehabilitation contracts.
End User:
Procurement concentration shapes contractor specialization, with public sector tenders dominating volume and mining companies commanding premium pricing for remote site execution.
- Public Sector:National and municipal governments tendering rail, road, and utility tunnels through competitive bidding frameworks. India's Ministry of Railways and China's National Railway Administration account for the largest contract pipelines, with payment security backed by sovereign guarantees.
- Private Developers:Real estate and infrastructure funds financing urban utility and road tunnels on concession terms. Singapore and Hong Kong harbor crossings attract institutional equity seeking long-dated revenue streams from tolling or availability payments.
- Mining Companies:Base metal and coal operators developing decline shafts, ore passes, and ventilation raises. Chilean copper majors and Australian iron ore producers specify rapid development rates with bonus-penalty structures tied to monthly advance meters.
- Transportation Authorities:Metro corporations and highway operators with dedicated capital programs and in-house technical capacity. Transport for London and RATP maintain standing design frameworks that compress tender-to-award cycles.
Public Sector holds installed capacity. Private Developers are climbing the fastest as pension capital seeks infrastructure yield.
Installation:
Geographic deployment context determines methodology constraints, with urban settings commanding the strictest surface disruption limits and offshore environments imposing marine logistics complexity.
- Onshore:Terrestrial tunneling through mountains, valleys, and coastal plains with conventional surface access. Norway's subsea road tunnels and Turkey's mountain highway corridors exemplify this category's scale.
- Underground:Deep rock excavation below 100 meters with limited vertical shaft access. South African gold mining tunnels and Finnish nuclear waste repositories operate at depths exceeding one kilometer.
- Offshore:Subsea bored tunnels or immersed tubes beneath harbors and straits. The Fehmarn Belt Fixed Link between Germany and Denmark represents the largest ongoing immersed tube contract.
- Urban:Shallow tunneling beneath dense infrastructure with strict vibration and settlement limits. Paris Metro Line 15 and Sydney Metro West specify ground freezing and compensation grouting to protect heritage foundations.
Onshore holds installed capacity. Urban is gaining share fastest as metro expansion accelerates across Southeast Asian capitals.
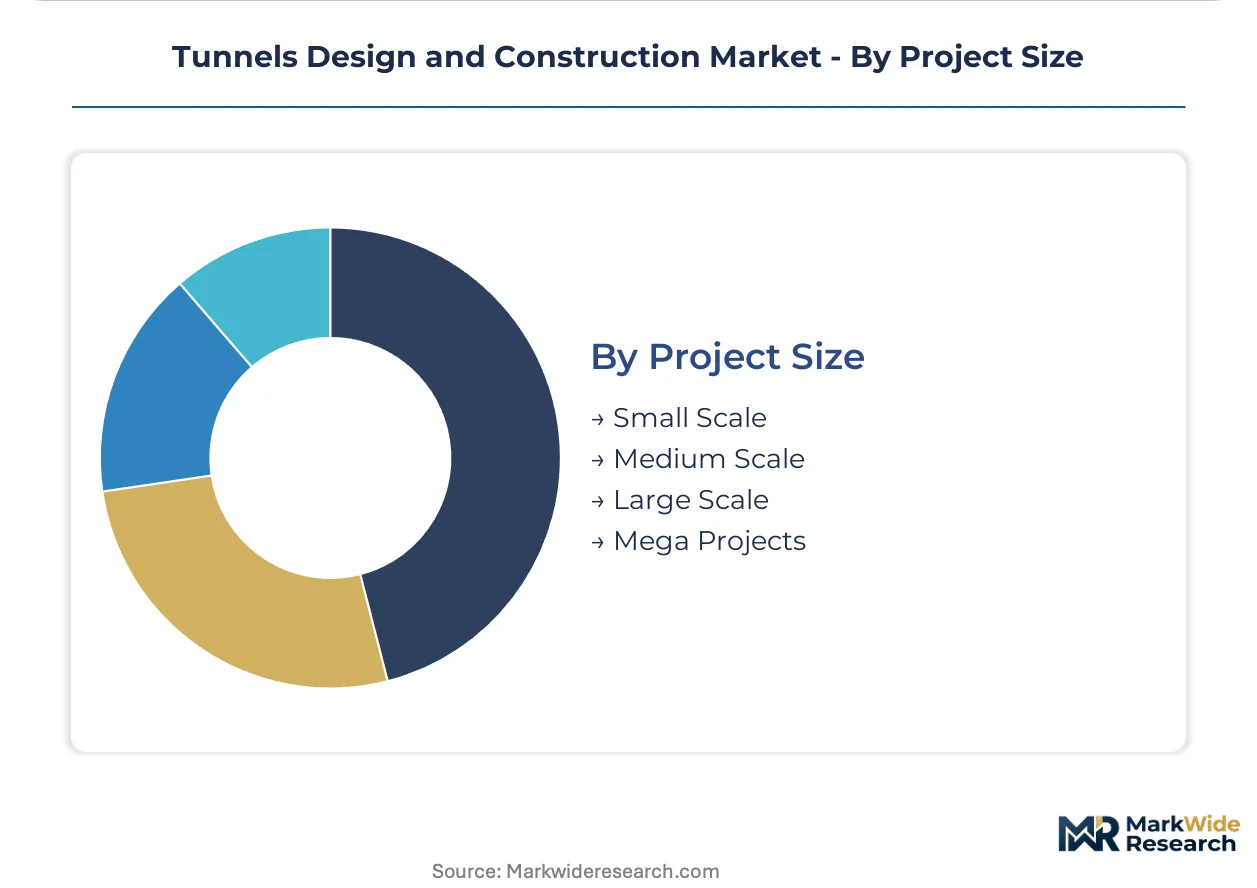
Project Size:
Scale tier determines contractor tiering, with mega projects consolidating among consortia possessing balance sheet capacity for multi-year execution risk.
- Small Scale:Utility crossings, pedestrian subways, and sewer relining under 500 meters. Municipal maintenance budgets in Italy and Spain sustain this segment despite compressed margins.
- Medium Scale:Road tunnels, rail cuttings, and water conveyance between 500 meters and 5 kilometers. Regional contractors in Poland and Turkey dominate this tier through equipment leasing rather than ownership.
- Large Scale:Mountain highway tunnels and urban metro sections between 5 and 20 kilometers. Alpine base tunnels and Japanese Shinkansen extensions cluster here, requiring joint venture structures to spread geological risk.
- Mega Projects:Corridor-length developments exceeding 20 kilometers with multi-billion contract values. The Brenner Base Tunnel and Lyon-Turin high-speed link exemplify this tier's decade-long execution horizons and specialized insurance requirements.
Mega Projects hold installed capacity. Medium Scale is rotating up the share rankings as regional governments accelerate deferred infrastructure backlogs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State rail authorities and municipal transit agencies concentrate procurement power across Asia-Pacific and European corridors. Alpine nations and China's western provinces anchor project pipelines through sovereign-backed tendering frameworks.
China
High-speed rail expansion through Sichuan and Yunnan provinces drives bored tunnel demand through karst terrain. The National Railway Administration mandates captive TBM fleet ownership as pre-qualification criteria for corridor contracts. Chengdu and Kunming anchor contractor deployment zones where state procurement pipelines prioritize in-house geotechnical expertise.
India
Mumbai, Bengaluru, and Delhi metro authorities tender underground packages exceeding 50 kilometers per project. The Ministry of Railways specifies NATM-TBM hybrid methodologies to minimize surface disruption in dense urban cores. Domestic contractors lack underwater tunneling experience, creating entry points for specialized foreign joint ventures in coastal corridors.
Switzerland
Alpine base tunnel projects concentrate value pools among consortia with decade-long execution capacity. F-Gas Regulation phase-down schedules force CO2 transcritical heat pump specification in climate control systems. The Gotthard and Brenner corridors exemplify this tier's specialized insurance requirements and geological risk structures.
United States
Hydroelectric tunnel safety inspections fall under FERC guidelines that govern crew sizing and equipment automation. Urban transit authorities in New York and Los Angeles specify ground freezing for heritage foundation protection. OSHA confined-space protocols directly shape contractor bidding strategies in deep rock excavation.
Japan
METI guidelines for 2050 net-zero infrastructure accelerate electric muck haulage mandates in TBM operations. Tokyo and Osaka metro corporations maintain standing design frameworks that compress tender-to-award cycles. Equipment suppliers with battery-electric portfolios secure preferred vendor status under carbon-neutral tunnel procurement.
Tunnels Design and Construction Market Competitive Landscape
Player mix skews toward integrated engineering conglomerates with captive equipment fleets and specialized tunneling divisions. Market structure consolidates around state-backed contractors with sovereign procurement access and European alpine specialists with NATM expertise. Two strategic archetypes dominate: vertically integrated builders with in-house boring machine ownership, and methodology specialists with robotic shotcrete and digital twin capabilities. Competitive moves center on joint venture formation for mega-project risk distribution and certification pursuit for EU rail tender pre-qualification.
Within the integrated conglomerate tier, Strabag SE and China Railway Construction Corporation Limited exemplify divergent geographic anchoring strategies. Strabag leverages its tunneling division across Central European alpine and urban corridors, while CRCC sustains throughput via state-backed procurement pipelines. Larsen & Toubro Limited occupies a position among South Asian contractors through captive manufacturing of tunnel segments and specialized formwork systems. These three entities represent the spectrum from European methodology specialization to Asian scale-driven deployment.
| Leading Market Players |
|---|
| Strabag SE |
| Larsen & Toubro Limited |
| China Railway Construction Corporation Limited |
| Kiewit Corporation |
| Obayashi Corporation |
| Vinci Construction |
| Skanska AB |
| AECOM |
| Bechtel Corporation |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 and IRIS certification cycles simultaneously gate supplier qualification and stratify contract pricing tiers across European rail tenders, compressing margins for uncertified contractors while enabling premium capture among dual-certified incumbents. This regulatory overlay concentrates procurement power among state-backed authorities that index payments to material cost fluctuations, reshaping how contractors hedge rebar and cement exposure.
Pricing Analysis
Cost-plus contracts with steel and cement indexation dominate public sector rail tenders in China and India, insulating contractors from raw material volatility while capping upside. Price differentiation rests on TBM fleet ownership and in-house segment manufacturing, with vertically integrated players commanding 15-20 percent premiums over equipment-leasing competitors. Cost compression in cut-and-cover segments is intensifying because municipal budget constraints are squeezing contingency allowances. Mining companies show least price sensitivity, accepting bonus-penalty structures tied to advance rates.
Supply Chain Analysis
Inventory cycles for large-diameter TBMs now stretch beyond 18 months, constraining project scheduling flexibility and forcing early procurement commitments. Manufacturing concentrates in Germany, China, and Japan, with Herrenknecht and CRCC Heavy Industry anchoring capacity. The supply chain draws from specialized steel foundries, hydraulic systems suppliers, and disc cutter manufacturers. Single-source vulnerability in 10+ meter diameter machine components creates bottleneck risk. Distribution runs through direct sales to contractor consortia and state procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunnel construction sits in early-cycle expansion as metro authorities across Southeast Asia tender corridor packages exceeding 50 kilometers, with penetration rates in Vietnam and Indonesia still below 30 percent of projected network completion.
For Market Incumbents: Fortify captive TBM fleet utilization through multi-project scheduling optimization and backward integration into segment manufacturing. ISO 9001 and IRIS certification investments are essential defensive moats as EU rail tenders tighten pre-qualification windows. Geotechnical expertise retention offers the strongest lever against emerging data-analytics contractors. For New Entrants and Emerging Players: Lead with digital twin integration and robotic shotcrete capabilities to capture performance-based contract bonuses in Swiss and Austrian alpine corridors. India's underwater tunneling gap represents the most penetrable white space, with Mumbai coastal road and Bengaluru suburban rail projects lacking domestic experience. Joint venture structures with established European methodology specialists offer the cleanest go-to-market path. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mega-project consortia as decade-long execution horizons demand expanded balance sheet capacity. Five-to-ten year viability favors contractors with demonstrated F-Gas Regulation compliance and battery-electric equipment portfolios. The acquisition target archetype is mid-scale regional players with captive geotechnical capabilities and pending IRIS certification. Equipment supplier order backlogs signal demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Spreads geological risk across Brenner Base Tunnel and Lyon-Turin corridor consortia. |
| Backward Integration | Captive segment manufacturing at Larsen & Toubro insulates against rebar price volatility. |
| Digital Twin Deployment | Fiber-optic strain sensing at Swiss alpine projects reduces overbreak and captures performance bonuses. |
| Certification Investment | Dual ISO 9001 and IRIS tracks unlock EU rail tender access for South Asian contractors. |
| Electric Fleet Transition | Battery-electric TBM portfolios secure preferred vendor status under Japan's METI carbon-neutral mandates. |
Research Methodology
Cross-validation between primary interviews with tunnel project directors, geotechnical engineers, procurement officers at state rail authorities, and TBM fleet managers anchors the qualitative findings against secondary validation from FERC inspection guidelines, EU CSRD disclosure frameworks, EIA construction spending data, and contractor SEC filings. Bottom-up project pipeline aggregation triangulates against top-down market sizing across technology, end-user, and installation segments.
Sensitivity analysis on advance rate assumptions, geological risk contingencies, and material cost indexation shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include excavation methodology, owner type, deployment context, and project scale tier. CAGRs derive from fitted growth curves applied to disclosed contract values and sovereign infrastructure budget trajectories. Forecast inputs incorporate TBM fleet utilization rates and shotcrete labor productivity benchmarks.
Underlying assumptions cover stable sovereign credit ratings for state-backed procurement, with deviation risk concentrated in force majeure exclusions for rockburst and methane inflow coverage. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Honduras Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
France Prefab Homes Market
Building Construction
Africa Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
Qatar Construction Market
Building Construction
Precast Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Egypt Residential Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
India Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
North America Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
Indonesia Prefabricated Buildings Market