
 Metal Rollforming System Market | 2026-2036
Metal Rollforming System Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Rollforming System Market Insights
The capital-intensity divergence between integrated mill builders and modular equipment suppliers is unwinding as order backlogs favor firms with captive steel processing capabilities. SMS group GmbH leverages its metallurgical heritage to supply complete lines with upstream coil handling integration. Bradbury Group anchors the North American aftermarket through a regionally dense service network and spare-parts logistics. Dreistern differentiates via precision roll tooling engineered for thin-gauge high-strength steel alloys.
A metal rollforming system comprises a series of contoured rolls that progressively bend continuous metal strip into uniform profiles with tolerances typically held within 0.5 mm; the process runs at line speeds from 15 to 150 meters per minute depending on profile complexity and material thickness. These systems produce structural and architectural profiles for building envelopes, racking systems, and transportation components with minimal material waste versus press-brake alternatives. Roofing sheets and purlins dominate volume demand, though wall panel lines command premium pricing due to insulated composite configurations and tighter seam tolerances. Automatic technology lines are capturing share from semi-automatic equipment as labor scarcity in developed markets accelerates payback calculations for full coil-to-stack automation. Contractors represent the largest end-user channel, but OEM direct procurement is expanding as appliance and solar racking manufacturers internalize profile production.
OSHA machine guarding standards and the EU Machinery Directive shape equipment design mandates, forcing retrofit cycles and limiting market access for non-certified suppliers. EPA emissions rules for metal coating operations indirectly influence downstream rollforming demand by redirecting investment toward uncoated galvanized substrates processed at ambient temperatures. Buyers must weigh European CE marking requirements against North American electrical standards when specifying multinational production footprints.
Market Dynamics
Automated coil-to-stack systems are compressing payback periods as labor scarcity across Texas, California, and Ontario construction markets forces contractors toward full-line automation. The structural force is the replacement of semi-automatic equipment by integrated lines with upstream coil handling and downstream packaging.
Growth Catalysts
- Clean energy manufacturing incentives:The U.S. Inflation Reduction Act redirects capital toward domestic metal building component production, accelerating orders for structural rollforming capacity.
- Steel framing substitution:Mid-rise builders across Texas and Arizona are displacing traditional lumber with cold-formed steel purlins and studs, expanding automated line demand.
- Reshoring warehouse construction:Energy-sector and logistics facility builds in Houston and Dallas absorb record volumes of rollformed structural sections.
Market Restraints
- High-strength steel coil volatility:Thin-gauge advanced high-strength steel supply concentrates among integrated mills, creating input cost uncertainty for equipment buyers.
- CE marking friction:European Machinery Directive compliance requirements limit market access for North American suppliers lacking EU certification infrastructure.
- Press-brake substitution in custom runs:Low-volume architectural profiles remain economical on brake-forming equipment, capping rollformer penetration in specialty fabrication shops.
Strategic Opportunities
- India warehouse construction:Cold chain and logistics facility expansion under the PLI scheme creates demand for purlin and cladding rollforming capacity.
- Solar racking verticalization:Photovoltaic mounting system manufacturers internalize profile production to control supply timelines and alloy specifications.
- Insulated composite wall panels:Tighter seam tolerances and thermal bridging requirements command premium pricing for precision rollformed envelope systems.
Industry Challenges
- Roll tooling design expertise:Precision engineering for thin-gauge high-strength alloys requires specialized metallurgical knowledge that outpaces vocational training pipelines.
- OSHA guarding retrofit cycles:Evolving machine safety standards force costly line modifications for installed base equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Rollforming System Market |
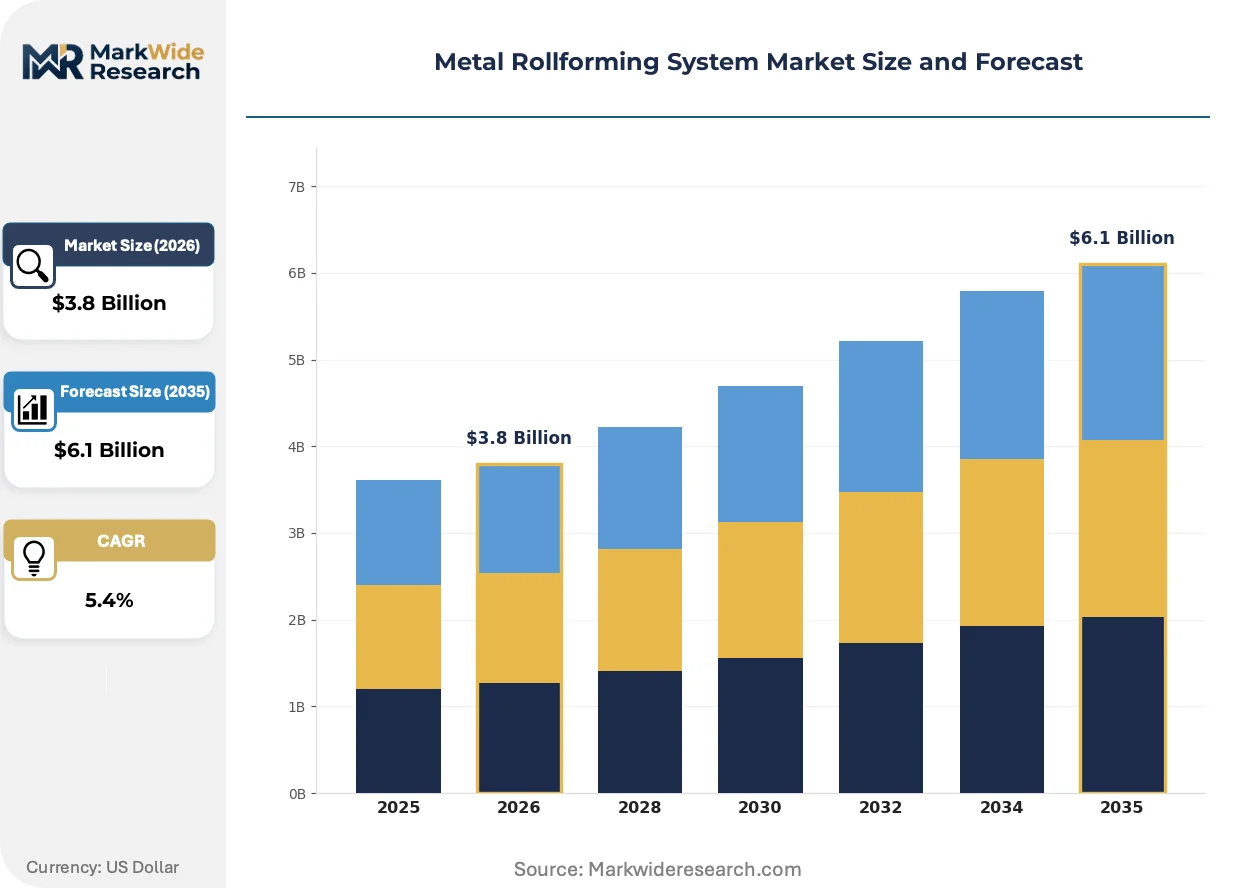
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roofing Sheets, Wall Panels, Cee Purlins, Zed Purlins Application: Industrial, Commercial, Residential, Agricultural Technology: Automatic, Semi-Automatic, Manual, Hybrid End User: Contractors, OEMs, Fabricators, Builders |
| Companies Covered | SMS group GmbH, Bradbury Group, Gasparini Industries, Dallan S.p.A, Formtek, Samco Machinery, Dreistern, Faccin S.p.A, Akyapak Makina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Rollforming System Market Trends and Innovations
Digital roll tooling and servo-electric drive systems are compressing changeover times and enabling lot-size-one production economics. The convergence of automation hardware with predictive maintenance software is reshaping equipment specification criteria across buyer segments.
Servo-electric rollforming lines are displacing hydraulic and mechanical drive systems in mid-gauge applications. Appliance manufacturers and solar racking OEMs are adopting servo-controlled lines for rapid profile changeovers. The technology is displacing legacy equipment in applications requiring frequent tooling swaps, compressing the viable market for conventional mechanical lines.
The EU Machinery Directive's 2023 update tightens functional safety requirements for collaborative automation interfaces. Equipment builders must integrate certified safety PLCs and light curtain systems to maintain CE marking validity. European rollformer suppliers are absorbing compliance costs into base pricing, while non-certified Asian competitors face exclusion from EU project tenders.
Direct procurement from OEMs is fragmenting the traditional contractor-dominant channel. Solar racking, appliance, and electric vehicle battery enclosure manufacturers are internalizing profile production to capture margin and control alloy specifications. This pattern is most visible in Texas and California, where energy-sector and clean-tech manufacturing clusters concentrate captive rollforming investments.
Metal Rollforming System Market Segmentation
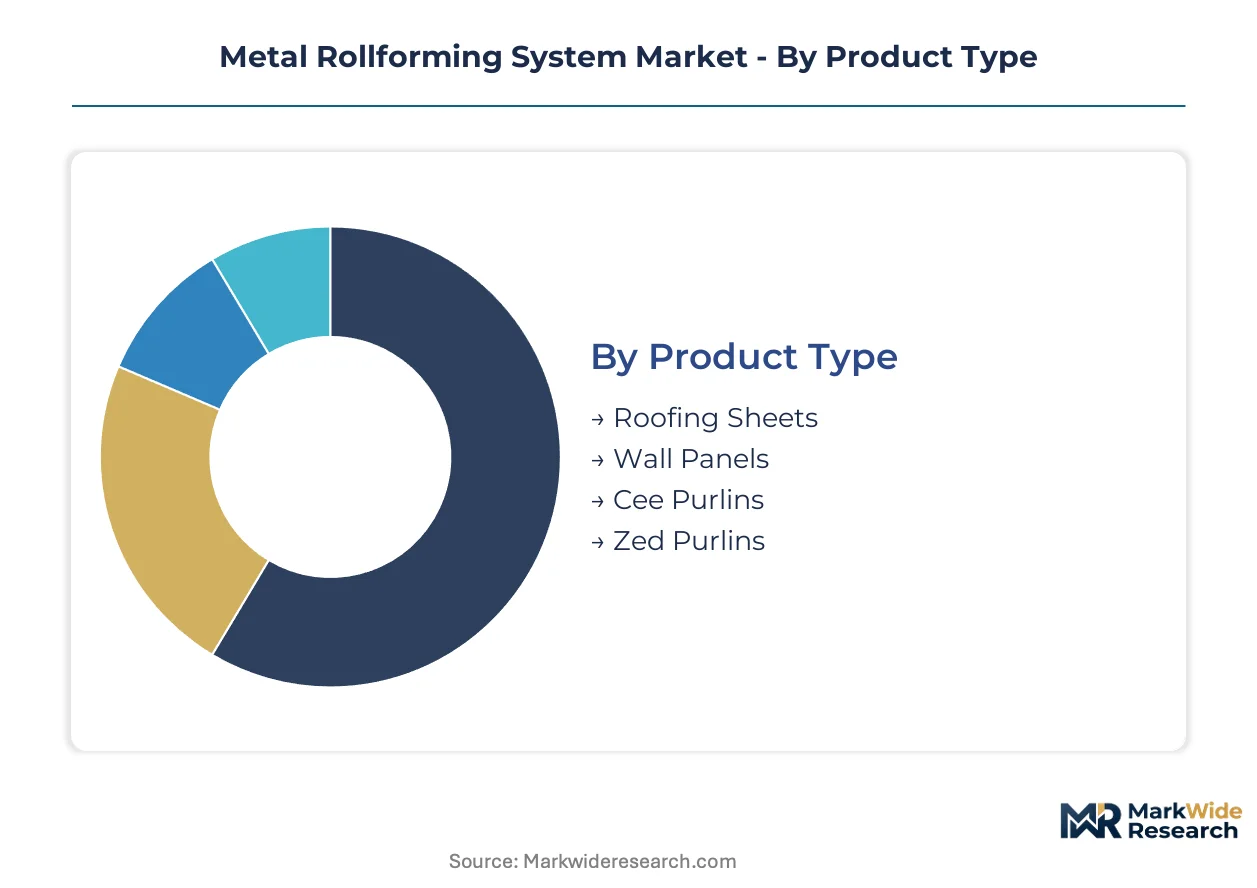
Segmentation in metal rollforming systems reveals where substitution pressure from press-brake fabrication and alternative materials is reshaping equipment specifications. Understanding these divisions clarifies which product configurations justify automation investment versus manual operation.
Product Type:
Press-brake substitution looms largest for thin-gauge architectural profiles, while structural sections maintain rollforming dominance due to volume economics.
- Roofing Sheets:Corrugated and standing-seam profiles formed from galvanized steel coils dominate warehouse and agricultural construction. Demand concentrates in Texas energy-sector builds where rapid envelope installation compresses project schedules.
- Wall Panels:Insulated composite configurations with thermal breaks require precision rollforming for seam integrity. Cold storage and controlled-atmosphere facilities in California and Arizona drive specification for tighter tolerances and composite bonding compatibility.
- Cee Purlins:Cold-formed steel sections for secondary structural framing displace lumber in mid-rise construction. Labor scarcity across Ontario and Texas accelerates automated line demand.
- Zed Purlins:Asymmetric profiles optimize material efficiency for clear-span roof systems. European CE marking requirements constrain supplier options for North American exporters.
Roofing sheets anchors the volume base while wall panels gains share at the steepest rate.
Application:
Cost tier differentiation separates high-automation industrial specifications from price-sensitive agricultural equipment.
- Industrial:Heavy-gauge structural lines with integrated coil handling serve manufacturing facilities and distribution centers. Reshoring warehouse construction in Houston and Dallas absorbs record volumes of automated capacity.
- Commercial:Mid-rise steel framing for retail and office buildings demands rapid-profile-changeover capabilities. U.S. Inflation Reduction Act incentives redirect capital toward domestic component production.
- Residential:Light-gauge stud and track systems compete with traditional lumber in multi-family construction. California building codes accelerate cold-formed steel adoption in fire-prone zones.
- Agricultural:Basic purlin and cladding lines prioritize throughput over precision for barn and storage structures. Semi-automatic equipment retains viability where labor costs remain subdued.
Industrial applications command the premium tier while residential specifications expand most quickly.
Technology:
Customer type fragmentation splits the market between labor-scarce regions demanding full automation and specialty shops retaining manual flexibility.
- Automatic:Servo-electric coil-to-stack systems with predictive maintenance software compress payback periods in high-wage markets. Solar racking manufacturers in Texas internalize production with rapid-changeover lines.
- Semi-Automatic:Hybrid configurations balance capital constraints with partial material handling automation. Custom fabrication shops in Ontario retain this tier for low-volume architectural work.
- Manual:Entry-level equipment serves developing markets and specialty prototype runs. OSHA guarding retrofit cycles force costly upgrades for aging installed base.
- Hybrid:Modular designs allow staged automation upgrades as volumes justify investment. Appliance manufacturers adopt this pathway for evolving product portfolios.
Automatic systems capture the margin pool while hybrid configurations climb the fastest as a transitional category.
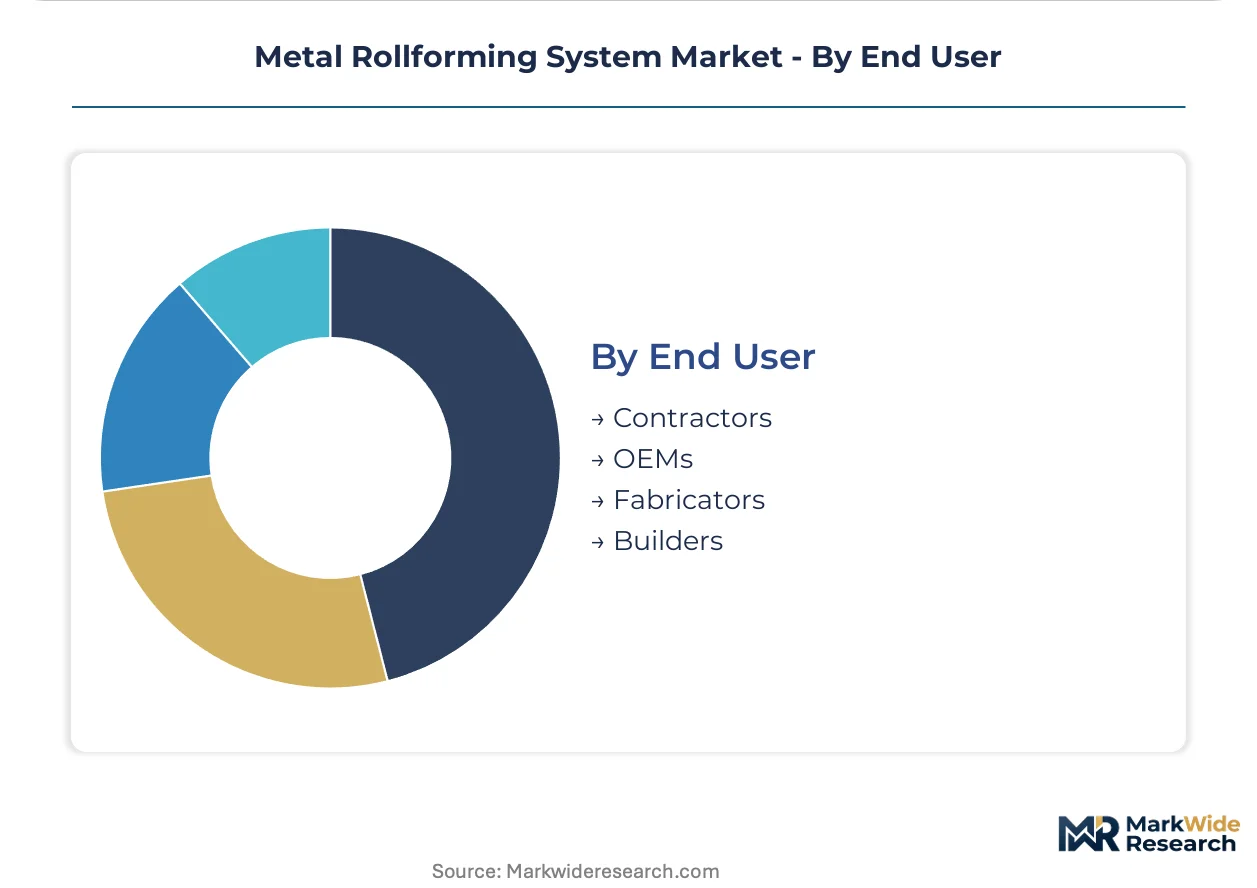
End User:
Supply concentration among integrated mill builders favors captive steel processing capabilities over standalone equipment purchases.
- Contractors:Construction firms represent the traditional channel for purlin and roofing line procurement. Texas and California labor scarcity accelerates full-automation specifications.
- OEMs:Solar racking, appliance, and battery enclosure manufacturers internalize profile production. Direct procurement fragments the contractor-dominant channel in clean-tech manufacturing clusters.
- Fabricators:Independent metal service centers balance custom work with standardized profile runs. Press-brake competition constrains rollformer penetration for architectural specialties.
- Builders:Vertical construction firms integrate envelope production for project control. Arizona mid-rise steel framing adoption expands this segment.
Contractors retain the volume foundation while OEMs demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, driving demand for semi-automatic and manual equipment tiers, whereas North American and European contractors absorb premium pricing for full coil-to-stack automation amid severe labor scarcity.
United States
Energy-sector warehouse construction in Houston and Dallas absorbs record volumes of automated structural rollforming capacity. The Inflation Reduction Act's clean energy manufacturing incentives redirect capital toward domestic metal building component production. California and Texas construction markets face acute labor scarcity, compressing payback periods for full-automation investments.
Germany
Precision engineering demand for thin-gauge high-strength steel alloys sustains premium equipment specifications. The EU Machinery Directive's 2023 update tightens functional safety requirements for collaborative automation interfaces. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate roll tooling design expertise and servo-electric line manufacturing.
China
Domestic warehouse and logistics facility construction drives volume demand for standardized purlin and roofing lines. The country's national industrial standards body mandates equipment certification for metal processing machinery. Manufacturing activity concentrates in the Yangtze River Delta and Pearl River Delta regions, where local fabricators serve both domestic and export markets.
India
Cold chain and logistics facility expansion under the PLI scheme creates demand for purlin and cladding rollforming capacity. Bureau of Indian Standards certification requirements shape equipment import specifications and local assembly incentives. Industrial corridors in Maharashtra and Gujarat absorb new capacity for mid-rise steel framing applications.
Mexico
Nearshoring manufacturing investment accelerates demand for structural steel envelope systems in industrial facility construction. The country's national labor regulations influence equipment guarding specifications for cross-border production footprints. Manufacturing clusters in Nuevo León and the Bajío Region concentrate new rollforming capacity serving North American automotive and appliance supply chains.
Metal Rollforming System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with metallurgical heritage and captive steel processing capabilities distinguishing the upper stratum from modular equipment suppliers. The market structure reflects capital-intensity divergence unwinding as order backlogs favor firms with upstream coil handling integration. Three archetypes dominate: integrated mill builders with metallurgical lineage, regional aftermarket anchors with dense service networks, and precision tooling specialists for advanced alloys. Competitive moves center on captive processing capability expansion and predictive maintenance software integration to lock in specification influence.
Within the integrated mill builder tier, SMS group GmbH exemplifies the metallurgical heritage archetype, while Bradbury Group anchors the North American aftermarket through regional service density. Dreistern occupies a position among precision specialists, representing the tooling-engineering archetype for thin-gauge high-strength applications. These three firms illustrate how competitive positioning fragments across capability vectors rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| SMS group GmbH |
| Bradbury Group |
| Gasparini Industries |
| Dallan S.p.A |
| Formtek |
| Samco Machinery |
| Dreistern |
| Faccin S.p.A |
| Akyapak Makina |
| Others |
Pricing and Supply Chain Analysis
CE marking compliance under the EU Machinery Directive gates both supplier qualification and price tiering simultaneously, forcing European buyers toward certified premium lines while excluding non-compliant competitors from tender participation. This certification barrier concentrates pricing power among integrated builders with metallurgical heritage, compressing margins for modular equipment suppliers lacking upstream coil handling capabilities.
Pricing Analysis
Aftermarket service contracts and spare-parts logistics anchor lifetime value capture for rollforming equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates servo-electric automated lines from semi-automatic hybrids and manual entry systems. Cost compression in the economy tier is intensifying because Asian manufacturers without CE certification face exclusion from EU project tenders. Contractors in Texas and California demonstrate lowest price sensitivity due to labor scarcity compressing automation payback calculations, while Indian cold-chain developers exhibit acute sensitivity favoring semi-automatic configurations.
Supply Chain Analysis
Germany and Italy anchor precision roll tooling engineering and servo-electric drive system manufacturing for advanced alloy applications. Equipment production draws from specialized high-strength steel coil supply concentrated among integrated mills, precision-machined roll sets, and certified safety PLC components. Single-source vulnerability in thin-gauge advanced high-strength steel coil supply creates input cost uncertainty for equipment buyers specifying high-performance lines. Distribution runs through regional service networks for aftermarket support, with direct OEM procurement fragmenting traditional contractor channels in Texas and California clean-tech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal rollforming systems sit in early-cycle expansion as steel framing displaces lumber in mid-rise construction across fire-prone California zones and labor-scarce Texas markets. The U.S. Inflation Reduction Act's clean energy manufacturing incentives redirect capital toward domestic component production, accelerating specification for automated structural capacity.
For Market Incumbents: Secure captive coil processing capabilities to defend margin position against integrated mill builders with metallurgical heritage. Expand predictive maintenance software integration to lock in specification influence among solar racking OEMs internalizing profile production. Densify spare-parts logistics networks in Texas and Ontario where labor scarcity accelerates automation retrofit demand. For New Entrants and Emerging Players: Anchor in India's PLI-driven cold chain and logistics facility expansion, where price-sensitive demand for purlin and cladding capacity outpaces certified European supplier presence. Target semi-automatic equipment tiers for mid-rise steel framing applications in Maharashtra and Gujarat industrial corridors. Pursue Bureau of Indian Standards certification pathway to qualify for government-backed infrastructure tenders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-electric automated lines as order backlogs favor firms with upstream coil handling integration. Long-term viability favors precision tooling specialists with metallurgical engineering depth over modular equipment assemblers. Monitor solar racking manufacturer verticalization announcements as inflection signal for captive production displacement of contractor-channel volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Processing | SMS group GmbH leverages metallurgical heritage to supply complete lines with upstream handling integration. |
| Predictive Maintenance Software Integration | Equipment builders lock in specification influence among appliance manufacturers adopting rapid-changeover servo lines. |
| Regional Service Network Densification | Bradbury Group anchors North American aftermarket through spare-parts logistics and field technician proximity. |
| CE Marking Certification Investment | European suppliers absorb compliance costs into base pricing while excluding Asian competitors from EU tenders. |
| Solar Racking Verticalization Partnership | Photovoltaic mounting system manufacturers internalize profile production to control supply timelines in Texas clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC 10-K filings of listed equipment manufacturers, customs and trade data for rollformed product flows, OSHA machine guarding standard updates, and EU Machinery Directive regulatory filings. Bottom-up equipment shipment tallies triangulated against top-down construction spending allocations for metal building components.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, automation technology tier, end-user channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of equipment order backlogs and substitution elasticity estimates for steel framing versus lumber. Forecast inputs incorporated labor scarcity indices for construction markets and Inflation Reduction Act incentive disbursement trajectories for clean energy manufacturing.
Material uncertainties — high-strength steel coil price volatility, CE marking compliance cost inflation, and press-brake substitution thresholds in custom architectural runs — sit outside the modeled envelope. Forecasts reflect documented assumptions about automation adoption curves and reshoring warehouse construction momentum. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Broaching Machine Market
Construction Equipment
Tower Crane Market
Construction Equipment
Derinding Machines Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Cold Planers Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
GCC Crane Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Concrete Testers Market