
 Europe Used Construction Machinery Market | 2026-2036
Europe Used Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Used Construction Machinery Market Foresight
Modular rebuild kits and certified pre-owned bundles is consolidating buyer preference across Europe, reducing procurement complexity for mid-sized contractors. Liebherr International anchors its German manufacturing heritage through rigorous refurbishment protocols at its Kirchdorf facility. Caterpillar Inc. competes via its European dealer network's Cat Certified Used program, leveraging standardized inspection checklists. JCB sustains brand loyalty through dedicated used equipment hubs in the UK and continental Europe.
Europe used construction machinery encompasses second-hand earthmoving, lifting, and material-handling equipment typically reconditioned to operational standards with documented service histories and remaining lifecycle assessments of 5,000 to 15,000 operating hours. These assets serve contractors and rental firms seeking capital-efficient fleet expansion without new-equipment delivery delays of 12 to 18 months. Excavators dominate transaction volumes due to universal applicability across residential, commercial, and civil engineering projects, while electric technology segments gain structural attention as urban emission zones expand and diesel restrictions tighten in Benelux and Nordic cities. Auction houses and dealer networks capture the largest margin pools by controlling inspection certification and financing access, whereas online platforms remain concentrated in lower-value lots where buyer risk tolerance runs higher.
CE marking requirements under the EU Machinery Directive mandate safety conformity for resold equipment, while national regulators including Germany's KBA and France's ANSM-aligned labor inspectorates enforce operator certification and workplace safety standards that indirectly filter eligible used inventory into circulation. The EU Green Deal's Stage V emission benchmarks progressively disqualify older diesel units from public procurement tenders, redirecting demand toward compliant used models. Stakeholders must monitor regulatory phase-out calendars and residual value curves to time fleet turnover decisions optimally.
Market Dynamics
Stage V emission mandates under the EU Green Deal are structurally filtering diesel machinery circulation, compressing residual values for non-compliant excavators and loaders while elevating certified pre-owned bundles with documented emission histories.
Growth Catalysts
- EU Green Deal Stage V deadlines:Public procurement tenders across Germany and France now exclude pre-2019 diesel units, redirecting contractor demand toward compliant used inventory with verified emission certifications.
- Rhine-Ruhr infrastructure corridor:Germany's dense construction clustering generates concentrated equipment turnover, feeding regional auction networks with steady supply of mid-life excavators and wheel loaders.
- Telematics integration:Refurbishment facilities now bundle hour-meter verification with remote diagnostic capabilities, reducing buyer uncertainty and accelerating transaction velocity for certified pre-owned assets.
Market Restraints
- Steel and hydraulic component volatility:Rebuild cost sensitivity tracks commodity swings, squeezing margin predictability for independent refurbishment shops dependent on spot-market cylinder and track supplies.
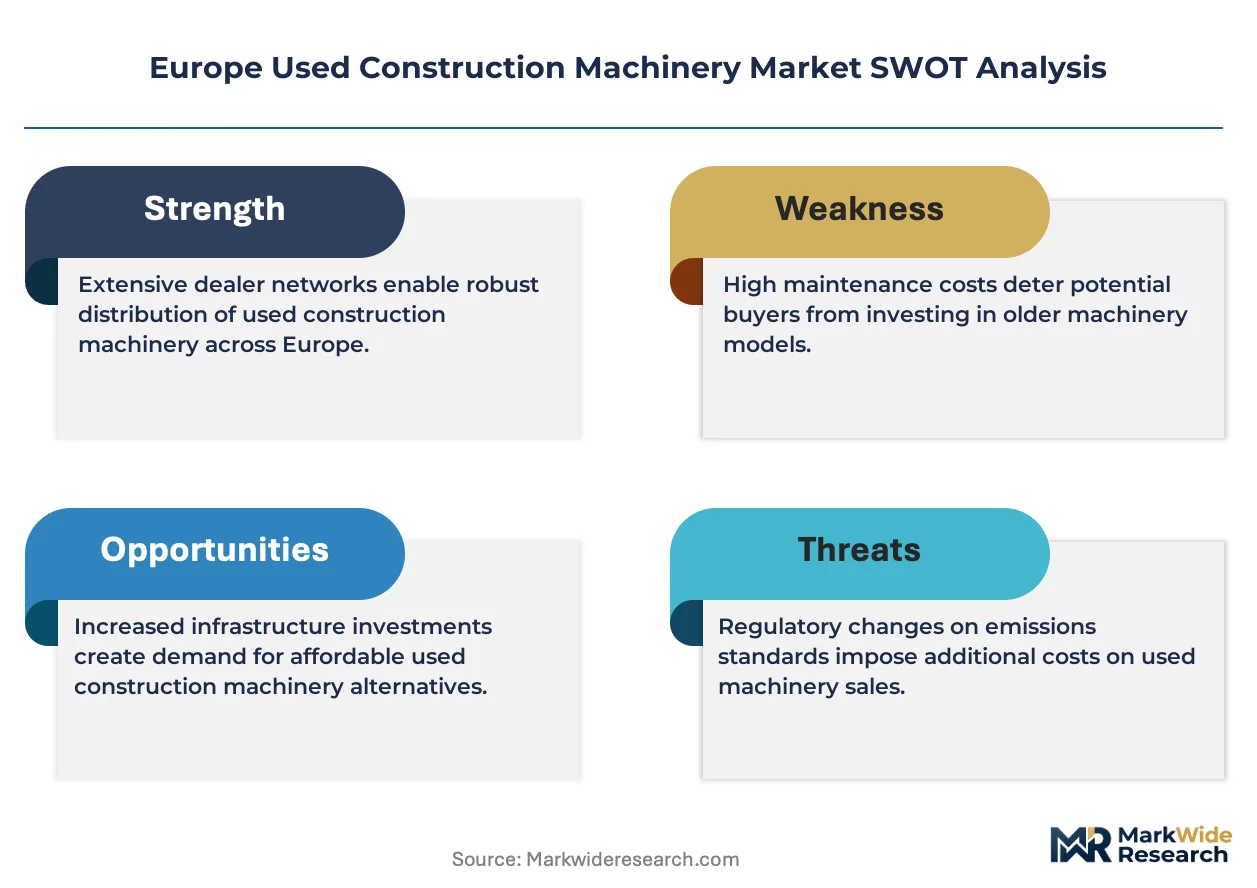
- Dealer network concentration:Major OEM-affiliated channels control 60-70% of certified used flow in Western Europe, limiting price transparency and access for smaller contractors outside established relationships.
- Battery-electric range limitations:Current used electric construction equipment offers insufficient operating duration for rural earthmoving applications, constraining resale liquidity outside urban emission zones.
Strategic Opportunities
- Poland infrastructure belt expansion:EU cohesion fund allocations for road and rail projects are generating equipment demand that outpaces new machinery delivery capacity, opening used import channels from Germany and Benelux.
- Modular retrofit electrification:Convergence of battery-swapping architectures with standardized hydraulic interfaces enables diesel-to-electric conversion services for mid-life excavators serving urban demolition contractors.
- Online auction platform penetration:Digital marketplaces with embedded inspection verification are capturing lower-value lot transactions previously consigned to regional dealer trade-ins, expanding geographic buyer pools.
Industry Challenges
- Stage V certification documentation gaps:Inconsistent engine retrofit records across Eastern European origin units create compliance verification delays at German and Austrian border inspections, extending procurement timelines.
- Telematics technician scarcity:Refurbishment facilities struggle to recruit diagnostics specialists capable of validating connected equipment data integrity, constraining throughput for certified pre-owned programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Used Construction Machinery Market |
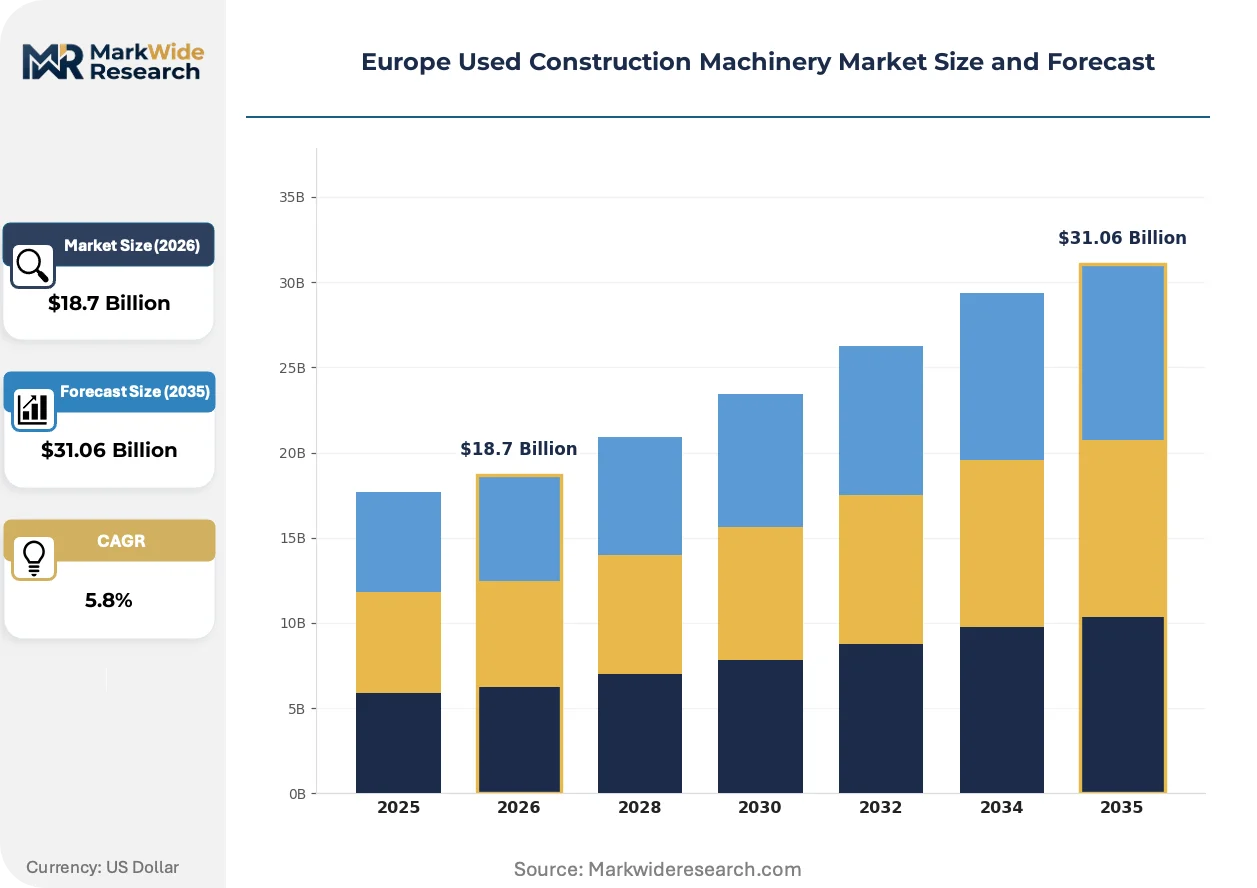
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Forklifts End User: Contractors, Rental Companies, Government Agencies, Private Developers Technology: Hydraulic, Electric, Diesel, Pneumatic Sales Channel: Direct Sales, Online Platforms, Auction Houses, Dealers |
| Companies Covered | John Deere & Co., Liebherr International, Caterpillar Inc., JCB, Mitsubishi Heavy Industries, Volvo Construction Equipment, Kobelco Construction Machinery, Hitachi Construction Machinery, Komatsu, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Used Construction Machinery Market Shifts & Advancements
Telematics-enabled condition monitoring is collapsing information asymmetry between sellers and buyers, while regulatory emission benchmarks and procurement model experimentation are compressing traditional equipment lifecycle assumptions.
Blockchain-based equipment history registries are decentralizing provenance verification across the European used machinery trade. Mid-sized rental firms in the Netherlands and Belgium now prioritize assets with immutable service records over lower-priced undocumented alternatives. This transparency compression is eroding price premiums previously captured by OEM-affiliated channels with captive documentation systems.
CE marking enforcement under the EU Machinery Directive is tightening conformity assessment requirements for cross-border resale. National labor inspectorates in France and Germany now coordinate inspection protocols, reducing regulatory arbitrage between member states. Contractors in the Benelux region face heightened scrutiny of imported used loader documentation, accelerating compliance investment by export-oriented refurbishment facilities.
Subscription-based equipment access is displacing outright purchase for seasonal construction segments. German residential developers and Polish road contractors now favor hour-based fleet arrangements with embedded maintenance, transferring residual value risk to specialized lessors. This preference compression is visible most acutely in excavator categories where utilization volatility complicates ownership economics for project-based operators.
Europe Used Construction Machinery Market Segmentation
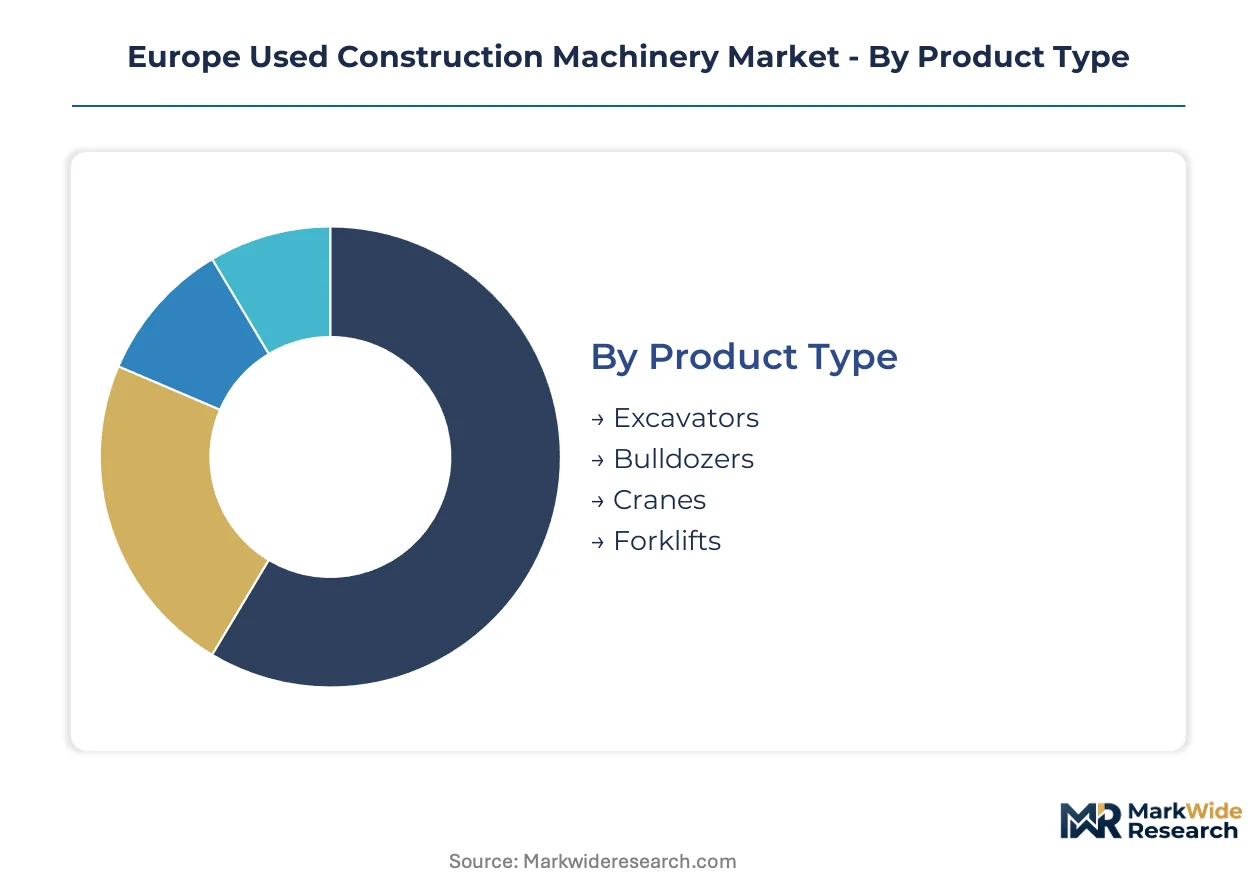
Segmentation in the Europe used construction machinery market reveals how procurement complexity fragments across equipment lifecycles, buyer risk appetites, and regulatory compliance tiers. Understanding these divisions exposes where margin pools concentrate and where digital disruption is rewriting traditional channel economics.
Product Type:
Excavators dominate transaction flow by volume, yet premium pricing accrues to specialized lifting equipment with verified service histories and remaining lifecycle certifications.
- Excavators:Universal applicability across residential, commercial, and civil engineering projects drives the highest transaction velocity. Demand concentrates in Germany's Rhine-Ruhr corridor and Poland's infrastructure belt, where contractors seek mid-life units with 5,000 to 15,000 operating hours to avoid new equipment lead times of 12 to 18 months.
- Bulldozers:Earthmoving specialists favor these assets for grading and site preparation where precision control matters. French road contractors and Benelux landfill operators represent the core demand cluster, constrained by Stage V emission compliance requirements that filter older diesel units from public procurement eligibility.
- Cranes:Tower and mobile variants command residual value premiums due to stringent CE marking conformity assessments under the EU Machinery Directive. Nordic urban construction zones and Dutch port expansion projects absorb certified pre-owned inventory with documented load-testing histories.
- Forklifts:Material-handling workhorses circulate through warehouse logistics and manufacturing supply chains. Electric variants gain traction in emission-restricted Benelux cities, though battery range limitations constrain rural resale liquidity.
Today's leader: Excavators. Tomorrow's challenger: Electric forklifts.
End User:
Contractor procurement patterns favor ownership economics, while rental company fleet decisions prioritize utilization flexibility and residual value risk transfer.
- Contractors:Project-based operators across Germany and Poland favor outright purchase of mid-life excavators and wheel loaders. Capital efficiency pressures and irregular utilization cycles drive preference for documented maintenance histories over lowest acquisition cost.
- Rental Companies:Fleet managers in the Netherlands and Belgium now expand refurbished equipment holdings to circumvent OEM delivery backlogs. Hour-based subscription models with embedded maintenance are displacing traditional ownership for seasonal construction segments.
- Government Agencies:Public procurement tenders in France and Germany now exclude pre-2019 diesel units, redirecting demand toward Stage V compliant used inventory with verified emission certifications and complete KBA or ANSM-aligned documentation.
- Private Developers:Residential construction firms favor certified pre-owned bundles that reduce procurement complexity. German developers in particular prioritize assets with telematics integration and remote diagnostic capabilities to minimize site downtime.
Rental companies capture the steepest expansion trajectory as fleet-as-a-service models displace traditional ownership.
Technology:
Hydraulic systems retain installed-base dominance, yet electrification is climbing fastest where urban emission zones tighten diesel restrictions.
- Hydraulic:Mature technology with established refurbishment protocols and spare parts availability. Independent refurbishment shops in Eastern Europe specialize in cylinder and track rebuilds, though steel commodity volatility squeezes margin predictability.
- Electric:Battery-powered excavators and forklifts gain structural attention in Nordic and Benelux cities with diesel bans. Current range limitations constrain rural earthmoving applications, compressing resale liquidity outside urban emission zones.
- Diesel:Stage V emission benchmarks under the EU Green Deal progressively disqualify older units from public tenders. Residual value curves for non-compliant excavators and loaders face structural compression as compliance documentation gaps create border inspection delays.
- Pneumatic:Niche applications in hazardous environments and specialized material handling. Limited circulation volume constrains secondary market depth and financing access.
Technology migration favors electric in cities, diesel in rural corridors.
Sales Channel:
Dealer networks control premium certified flow, while digital platforms erode regional trade-in concentration at the value tier.
- Direct Sales:OEM-affiliated refurbishment facilities like Liebherr's Kirchdorf operation capture margin through rigorous inspection protocols and standardized certification. Major channels control 60-70% of certified used flow in Western Europe.
- Online Platforms:Digital marketplaces with embedded inspection verification are capturing lower-value lot transactions previously consigned to regional dealer trade-ins. Geographic buyer pool expansion accelerates transaction velocity for undocumented assets where risk tolerance runs higher.
- Auction Houses:Physical and hybrid auction networks feed on Rhine-Ruhr infrastructure corridor turnover, generating steady supply of mid-life excavators. Control of inspection certification and financing access captures the largest margin pools in the secondary market.
- Dealers:Cat Certified Used and comparable programs leverage standardized inspection checklists to reduce buyer uncertainty. Established relationships limit price transparency for smaller contractors outside network coverage.
Dealers defend premium positioning. Online platforms challenge at the volume tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's post-war industrial reconstruction established the foundational infrastructure for Europe's used construction machinery trade, with Bavarian engineering clusters and North Rhine-Westphalian steelworks creating the continent's first dense secondary equipment networks.
Germany
KBA emission documentation requirements filter cross-border imports at Bavarian and Baden-Württemberg checkpoints, redirecting contractor demand toward Stage V certified inventory. The Rhine-Ruhr corridor generates concentrated equipment turnover through dense construction clustering. Liebherr's Kirchdorf refurbishment facility anchors premium certified flow with standardized inspection protocols.
Poland
EU cohesion fund allocations for road and rail projects generate equipment demand that outpaces new machinery delivery capacity. National labor inspectorates enforce operator certification standards that filter eligible used inventory into circulation. The infrastructure belt between Warsaw and Kraków absorbs steady imports of mid-life excavators from German auction networks.
France
ANSM-aligned labor inspectorates coordinate with German counterparts on cross-border inspection protocols, reducing regulatory arbitrage. Public procurement tenders exclude pre-2019 diesel units, compressing residual values for non-compliant loaders. Île-de-France urban construction zones and Provence port expansion projects absorb certified cranes with documented load-testing histories.
Netherlands
Benelux diesel restrictions in Rotterdam and Amsterdam port zones elevate demand for electric forklifts with verified battery performance records. Hour-based subscription models with embedded maintenance displace traditional ownership for seasonal residential developers. Randstad logistics corridors circulate material-handling equipment through warehouse automation upgrade cycles.
United Kingdom
JCB's used equipment hubs in Staffordshire and Gloucestershire sustain brand loyalty through dedicated refurbishment channels. CE marking conformity assessments under post-Brexit UKCA arrangements create documentation friction for continental imports. London residential developers and Midlands infrastructure contractors favor telematics-integrated assets to minimize site downtime.
Europe Used Construction Machinery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification documentation and telematics integration depth. OEM-affiliated refurbishment channels control sixty to seventy percent of certified used flow in Western Europe, limiting price transparency for contractors outside established relationships. Three archetypes dominate: integrated manufacturers with captive refurbishment facilities, independent rebuild specialists in Eastern Europe, and auction houses controlling inspection certification and financing access. Competitive moves concentrate on modular retrofit electrification partnerships and blockchain-based provenance verification systems.
Within the integrated manufacturer tier, Liebherr International and Caterpillar Inc. exemplify archetypes leveraging rigorous inspection protocols and standardized certification programs. JCB occupies a position bridging manufacturer heritage with dedicated used equipment hub infrastructure. These anchors represent contrasting geographic emphases—German manufacturing heritage, North American dealer network scale, and British brand loyalty consolidation—each capturing margin through documentation control and buyer risk reduction.
| Leading Market Players |
|---|
| John Deere & Co. |
| Liebherr International |
| Caterpillar Inc. |
| JCB |
| Mitsubishi Heavy Industries |
| Volvo Construction Equipment |
| Kobelco Construction Machinery |
| Hitachi Construction Machinery |
| Komatsu |
| Others |
Supply & Pricing Matrix
Telematics technician scarcity across Bavaria and Baden-Württemberg inflates refurbishment labor costs, compressing margins for independent shops while widening price spreads between OEM-certified bundles and undocumented Eastern European imports. This workforce bottleneck forces contractors to absorb premium tier pricing or accept compliance documentation gaps at lower price points.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction flow. Premium tiers capture Stage V-certified excavators with telematics verification from Liebherr's Kirchdorf facility; economy tiers circulate undocumented units through Polish border auctions. Price differentiation rests on certification completeness and hour-meter audit trails. Cost compression in the economy tier is intensifying because steel commodity volatility squeezes rebuild margins for independent shops. Rental companies exhibit lowest price sensitivity due to residual value risk transfer, while Polish road contractors show highest sensitivity to acquisition cost.
Supply Chain Analysis
Domestic-content mandates under EU Machinery Directive CE marking requirements are reshaping sourcing patterns for cross-border refurbishment. Supply concentrates in Germany, Poland, and the Netherlands. Component sourcing draws from hydraulic cylinder foundries in North Rhine-Westphalia, track assemblies from Czech steel mills, and electronic control modules from Dutch automation suppliers. Single-source vulnerability runs through German hydraulic component manufacturers dependent on spot-market steel. Distribution runs through OEM-affiliated dealer networks controlling sixty to seventy percent of certified used flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage corridor where Stage V compliance cost differentials between German KBA enforcement and Polish labor inspectorate standards create margin capture opportunities for refurbishment facilities with cross-border documentation capabilities.
For Market Incumbents: To counter blockchain-based provenance verification eroding documentation premiums, OEM-affiliated channels should deepen backward integration into telematics data infrastructure and expand captive refurbishment capacity in Poland's infrastructure belt. Certification investment in Stage V retrofit protocols at Eastern European facilities preserves margin capture as border inspection scrutiny tightens. For New Entrants and Emerging Players: Enter via modular retrofit electrification services for mid-life excavators serving Benelux urban demolition contractors, the most penetrable segment where diesel bans accelerate technology turnover. Target independent refurbishment shops in Eastern Europe lacking telematics diagnostic capabilities. Go-to-market leverage: embedded battery-swapping architecture partnerships with established hydraulic interface suppliers. For Investors and Strategic Acquirers: Rental companies are the most active acquirer in this space, consolidating used equipment fleets to circumvent OEM delivery backlogs. Long-term viability favors platforms with cross-border documentation capabilities and subscription-based fleet-as-a-service infrastructure. Acquisition target archetype: independent refurbishment facilities with established Polish-German logistics corridors. Signal to watch: EU Green Deal regulatory phase-out calendar acceleration compressing residual value curves for non-compliant diesel inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Electrification | Enables diesel-to-electric conversion for mid-life excavators serving Benelux urban contractors facing emission zone restrictions. |
| Blockchain Provenance Verification | Decentralizes equipment history registries, eroding price premiums previously captured by OEM-affiliated channels with captive documentation. |
| Telematics Integration Partnership | Bundles hour-meter verification with remote diagnostic capabilities, reducing buyer uncertainty and accelerating transaction velocity. |
| Cross-Border Refurbishment Expansion | Captures labor cost differentials between German KBA enforcement zones and Polish infrastructure belt demand clusters. |
| Subscription Fleet-as-a-Service | Transfers residual value risk to specialized lessors, displacing outright purchase for seasonal German residential developers. |
Research Methodology
Direct dialogue with refurbishment facility managers, rental company fleet directors, OEM aftermarket service heads, and Polish infrastructure contractors grounded qualitative findings. Secondary validation drew from EU Machinery Directive regulatory filings, KBA emission documentation databases, German customs trade records, and auction house transaction logs. Bottom-up equipment flow modeling triangulated against top-down regional construction spend estimates.
Bottom-up volume modeling tracked excavator, bulldozer, crane, and forklift transaction flows by certification tier, technology type, and sales channel across the projection horizon. Segmentation dimensions included product lifecycle stage, buyer risk appetite, and regulatory compliance tier. CAGRs were derived from equipment turnover velocity analysis and replacement cycle compression patterns. Industry-specific inputs incorporated Stage V phase-out calendar assumptions and telematics penetration curves in refurbishment facilities.
Inputs from auction house transaction databases and OEM dealer network disclosures were available through the study window; gaps in independent refurbishment shop cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and steel commodity trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Global Excavators Market
Construction Equipment
Trenchers Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market