
 Walform Machines Market | 2026-2036
Walform Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Walform Machines Market Insights
Aerospace parts manufacturing is recalibrating its supplier qualification criteria, pushing Tier-1 suppliers and component manufacturers toward precision cold-forming platforms. Eaton Corporation leverages its hydraulic systems heritage to anchor positions in servo-driven walform configurations. Parker Hannifin Corporation sustains R&D intensity across electromechanical actuation modules for aviation-qualified tube-forming cells. Komatsu dominates heavy-gauge press machine deployments for construction equipment OEMs in East Asia.
Walform machines cold-form metal tubes and pipes into leak-free flareless fittings through radial compression, typically achieving 600 bar pressure ratings without cutting or welding the workpiece. The process displaces traditional brazed and welded joints in hydraulic, fuel, and pneumatic distribution networks where vibration fatigue and thermal cycling resistance matter. Press machines lead the machine type category due to their ubiquity in high-volume automotive and appliance lines, while servo-driven technology captures the fastest expansion as end users retire hydraulic power units for precision and energy-efficiency gains. Application demand concentrates in automotive components, where OEMs and Tier-1 suppliers specify walform joints for brake, steering, and transmission fluid circuits.
ISO 19879 pressure-containment testing standards and the EU Machinery Directive shape product certification requirements for European equipment builders. The EPA's NESHAP metal fabrication rules and OSHA machine guarding mandates tighten compliance costs for U.S. manufacturing facilities evaluating walform cell upgrades. Stakeholders must monitor how REACH substance restrictions on hydraulic fluids and lubricants redirect technology choices toward dry or minimal-lubrication forming processes.
Market Dynamics
Servo-driven walform technology is compressing cycle times and energy consumption simultaneously, forcing equipment replacement decisions across automotive and aerospace supplier networks. Tier-1 hydraulic component manufacturers face capital allocation pressure between upgrading legacy press lines and migrating to fully electric forming cells.
Growth Catalysts
- EPA NESHAP metal fabrication rules:U.S. facilities must retrofit or replace emission-intensive brazing equipment, accelerating walform adoption for leak-free joint formation without thermal processes.
- Automotive brake and steering fluid circuits:OEM specification of flareless fittings for high-pressure hydraulic systems creates sustained demand for precision cold-forming capacity.
- Germany's automotive OEM cluster:Concentrated investment in Industry 4.0-compliant production lines drives procurement of networked walform machines with integrated quality feedback loops.
Market Restraints
- High-grade alloy steel price volatility:Input cost swings for tool-grade materials compress margin predictability for machine builders and contract manufacturers alike.
- Specialized servo drive supplier concentration:Dependence on a limited set of precision motion control vendors creates bottleneck risk for equipment delivery timelines.
- Technical limitation in ultra-large diameter tube forming:Current radial compression tooling struggles beyond 50mm nominal bore sizes, excluding heavy industrial piping applications.
Strategic Opportunities
- India's automotive component export zones:Underpenetrated precision forming capacity near Chennai and Pune offers first-mover positioning for ISO-certified equipment suppliers.
- REACH substance restrictions on hydraulic fluids:Regulatory pressure toward dry or minimal-lubrication processes creates demand for advanced tooling coatings and modified forming kinematics.
- Convergence of walform and additive manufacturing:Hybrid production cells combining cold-formed fluid distribution manifolds with printed structural brackets enable lightweight aerospace subsystem integration.
Industry Challenges
- ISO 19879 pressure-containment certification timelines:Extended validation protocols for aviation-qualified equipment delay revenue recognition and tie up engineering resources.
- Integration complexity with legacy MES architectures:Retrofitting servo-driven walform cells into existing shop-floor data systems requires custom middleware development and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walform Machines Market |
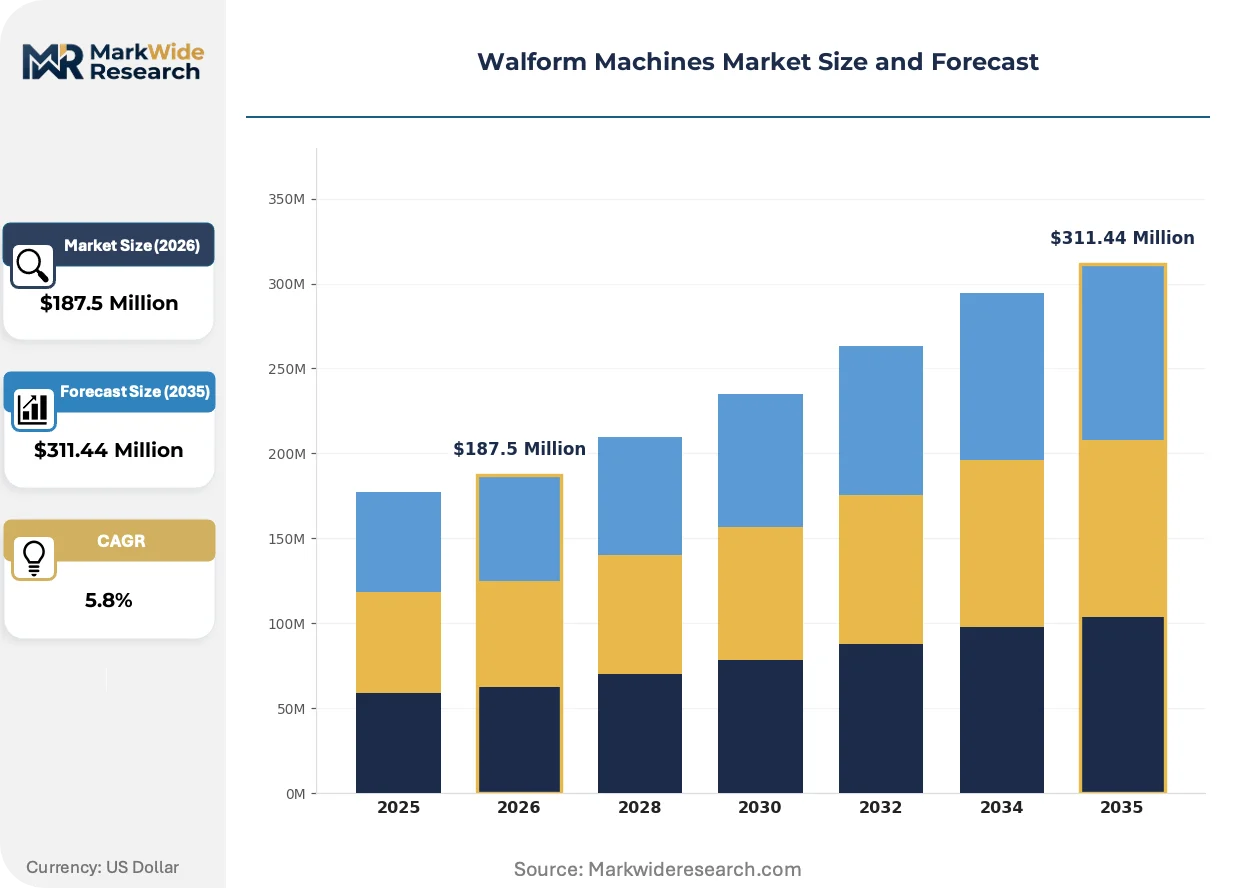
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Press Machines, Transfer Machines, Drawer Machines, Progressive Machines, Combination Machines Technology: Hydraulic, Mechanical, Pneumatic, Servo-driven, Electromechanical Application: Electronics Components, Electrical Appliances, Automotive Components, Aerospace Parts, Hardware Manufacturing End User Industry: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Component Manufacturers, Assembly Plants |
| Companies Covered | Eaton Corporation, GS-Hydro, Chuan Kok Hardware & Machinery, Hydroproduct, Armada Marine Hydraulics, Komatsu, Fagor Arrasate, Wafios, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walform Machines Market Trends and Innovations
Active magnetic bearing spindles and real-time force-feedback control loops are redefining precision thresholds in tube-forming operations. Equipment differentiation now hinges on data architecture and predictive maintenance capability rather than mechanical specifications alone.
Electromechanical servo press architectures are unifying position control, force monitoring, and energy recovery in single-axis designs. Aerospace Tier-1 suppliers are adopting these systems for lot-size-one production of flight-qualified hydraulic fittings. This unifying platform approach collapses the traditional separation between setup, forming, and inspection stations into continuous in-process verification.
REACH substance restrictions on chromium-based plating and certain hydraulic fluid formulations are forcing reformulation of lubrication strategies across European manufacturing facilities. Equipment builders must qualify alternative surface treatments and dry-film lubricants for tooling longevity. German automotive suppliers are responding fastest, pressuring machine vendors to pre-certify minimal-lubrication process windows.
Buyer consolidation among hydraulic system integrators is compressing vendor qualification cycles and demanding outcome-based performance guarantees. Traditional equipment sales with separate service contracts are giving way to throughput-based agreements where the machine builder assumes uptime risk. This shift is most visible in Germany's automotive supply chain, where Bosch Rexroth and Continental have centralized forming equipment procurement under technical performance scorecards.
Walform Machines Market Segmentation
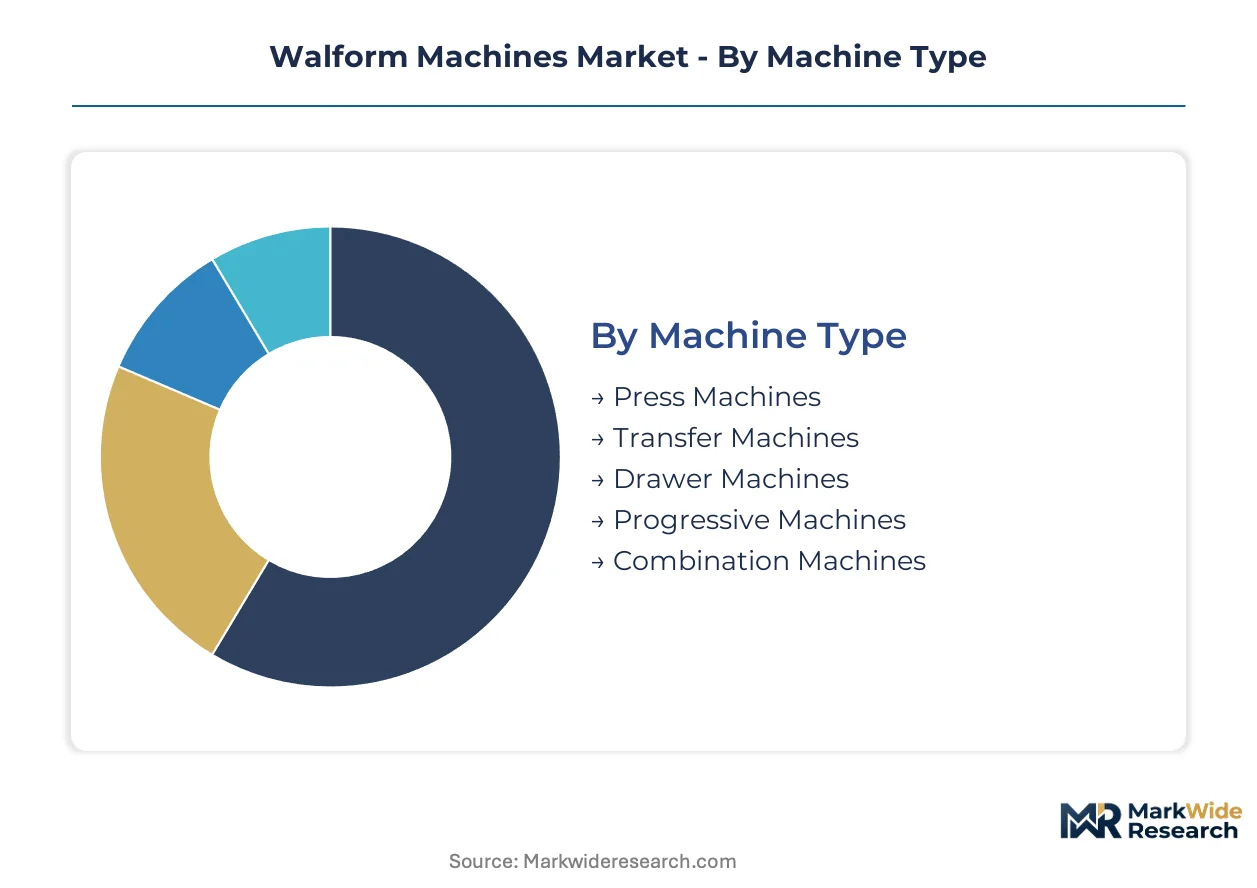
Walform equipment procurement follows distinct technical and commercial logics that reshape vendor priorities across machine architectures, power systems, and customer tiers. Segment boundaries determine tooling specifications, certification requirements, and aftermarket revenue potential.
Machine Type:
Supply concentration clusters around high-volume automotive platforms, with specialized configurations serving aerospace and appliance niches.
- Press Machines:Radial compression platforms dominate automotive brake and steering line production, achieving cycle times under three seconds for standardized tube diameters. German Tier-1 suppliers anchor demand for networked press cells with integrated force monitoring.
- Transfer Machines:Multi-station architectures move workpieces through sequential forming, inspection, and marking operations. Aerospace-qualified transfer lines concentrate in France and Germany, where ANSM and KBA certification requirements extend validation timelines.
- Drawer Machines:Longitudinal forming systems for complex manifold geometries serve hydraulic system integrators.
- Progressive Machines:Continuous-feed configurations support high-volume appliance component manufacturing in East Asia.
- Combination Machines:Hybrid architectures merge press and transfer functions for flexible lot-size-one production.
Press machines absorb the bulk of installed capacity; combination machines are expanding most quickly.
Technology:
Cost tier differentiation separates legacy hydraulic installations from precision servo architectures commanding premium positioning.
- Servo-driven:Electromechanical actuation with sub-micron position control and energy recovery captures aerospace Tier-1 procurement. Eaton Corporation and Parker Hannifin specifications favor servo platforms for flight-qualified fitting production.
- Hydraulic:Fluid-power systems retain installed base in heavy-gauge construction equipment manufacturing. Komatsu deployments in Japan and South Korea sustain demand for high-tonnage hydraulic forming.
- Mechanical:Cam-driven architectures serve cost-sensitive appliance component stamping.
- Pneumatic:Compressed-air systems occupy low-force precision applications in electronics hardware.
- Electromechanical:Integrated motor-ballscrew designs unify forming and inspection in single-axis platforms.
Servo-driven systems claim the steepest expansion trajectory; hydraulic technology retains the largest installed base.
Application:
Volume concentration in automotive brake and transmission circuits contrasts with margin-rich aerospace qualification programs.
- Automotive Components:Flareless fitting production for brake, steering, and transmission fluid networks drives standard press machine procurement. OEM specification of ISO 19879-compliant joints sustains capacity investment near Stuttgart and Wolfsburg.
- Aerospace Parts:Aviation-qualified tube forming demands REACH-compliant lubrication strategies and extended pressure-containment validation. German and French Tier-1 suppliers concentrate electromechanical servo adoption here.
- Electronics Components:Miniature fitting production for semiconductor fluid distribution occupies precision pneumatic niches.
- Electrical Appliances:Refrigeration and HVAC manifold manufacturing favors transfer machine configurations.
- Hardware Manufacturing:General industrial fitting production serves construction and agricultural equipment aftermarket.
Automotive components absorb the bulk of installed capacity; aerospace parts are gaining share fastest.
End User Industry:
Customer type determines procurement authority, with OEMs centralizing technical specifications and Tier-1 suppliers controlling equipment selection.
- Tier-1 Suppliers:Bosch Rexroth and Continental procurement departments consolidate forming equipment qualification under performance-based scorecards. These stakeholders drive servo migration and predictive maintenance requirements.
- OEMs:Automotive and aerospace original equipment manufacturers set joint specifications that constrain supplier equipment choices. EPA NESHAP compliance deadlines accelerate their specification of cold-forming alternatives to brazed assemblies.
- Component Manufacturers:Independent precision forming shops serve fragmented hydraulic system aftermarket demand.
- Aftermarket Suppliers:Repair and replacement fitting producers favor lower-cost mechanical and pneumatic platforms.
- Assembly Plants:Final integration facilities procure pre-formed fittings rather than forming capacity directly.
Tier-1 suppliers absorb the bulk of installed capacity; OEMs are expanding forming ownership most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart and Wolfsburg concentrate precision metal-forming investment, drawing equipment procurement toward ISO-certified cold-forming platforms. Tax incentives for Industry 4.0 adoption accelerate walform cell deployment in automotive supplier parks.
Germany
Bosch Rexroth and Continental consolidate forming equipment procurement under performance-based technical scorecards. REACH compliance deadlines pressure hydraulic fluid reformulation toward minimal-lubrication process windows. Stuttgart's automotive OEM cluster drives networked walform machine adoption with integrated quality feedback loops.
United States
EPA NESHAP metal fabrication rules force retrofit of emission-intensive brazing equipment across hydraulic system manufacturers. OSHA machine guarding mandates tighten compliance costs for facilities evaluating walform cell upgrades. Michigan and Ohio automotive supplier networks anchor demand for servo-driven press configurations.
China
Construction equipment OEMs sustain demand for heavy-gauge hydraulic forming capacity in East Asian manufacturing corridors. MIIT industrial upgrading programs incentivize electromechanical press adoption over legacy hydraulic systems. Yangtze River Delta precision component clusters expand cold-forming capacity for export-oriented automotive Tier-1 suppliers.
France
ANSM and KBA certification requirements extend validation timelines for aviation-qualified tube-forming equipment. ECHA substance restrictions redirect lubrication strategies toward dry-film alternatives in aerospace Tier-1 facilities. Auvergne-Rhône-Alpes aerospace supplier networks concentrate electromechanical servo adoption for flight-qualified fitting production.
India
Automotive component export zones near Chennai and Pune offer first-mover positioning for ISO-certified equipment suppliers. BIS standards alignment with ISO 19879 pressure-containment protocols shapes import qualification requirements. Tamil Nadu precision manufacturing corridors attract cold-forming capacity expansion serving brake and steering fluid circuit exporters.
Walform Machines Market Competitive Landscape
Top-tier vendors anchor aerospace and automotive OEM qualification programs, while mid-tier fabricators serve regional hydraulic system aftermarket demand. The vendor base stratifies across three capability tiers: electromechanical servo specialists, hydraulic power unit traditionalists, and cost-optimized mechanical press builders. Strategic archetypes include precision motion control integrators, heavy-gauge construction equipment suppliers, and Industry 4.0 platform developers. Competitive moves concentrate on M&A for servo drive technology access and geographic expansion into underpenetrated automotive export zones.
Within the precision motion control tier, Eaton Corporation and Parker Hannifin Corporation exemplify electromechanical servo platform development for aviation-qualified applications. Komatsu anchors heavy-gauge hydraulic forming capacity serving construction equipment OEMs in East Asia. These three entities represent distinct competitive vectors: aerospace Tier-1 qualification depth, hydraulic systems heritage, and scale-driven construction equipment deployment.
| Leading Market Players |
|---|
| Eaton Corporation |
| GS-Hydro |
| Chuan Kok Hardware & Machinery |
| Hydroproduct |
| Armada Marine Hydraulics |
| Komatsu |
| Fagor Arrasate |
| Wafios |
| Parker Hannifin Corporation |
| Others |
Pricing and Supply Chain Analysis
EPA NESHAP metal fabrication rules gate qualified supply access and premium-tier pricing power by mandating emission-compliant cold-forming equipment that only certified vendors can deliver. Tier-1 automotive and aerospace buyers pay substantial premiums for ISO 19879-validated walform machines with guaranteed lead times, while spot-market mechanical presses trade at discounts due to surplus inventory in construction equipment channels.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent aerospace procurement from scheduled automotive capacity additions, with 12-week delivery premiums commanding 25-40% markups over standard 20-week cycles. Three-tier pricing structure across premium servo-driven, standard hydraulic, and economy mechanical configurations reflects certification grade and energy efficiency differentials. Cost compression in the hydraulic tier is intensifying because German Tier-1 suppliers centralize procurement under performance scorecards. Aftermarket component manufacturers exhibit highest price sensitivity, while aviation-qualified Tier-1 suppliers prioritize technical compliance over unit cost.
Supply Chain Analysis
High-grade alloy steel supply rests on German, Japanese, and Austrian specialty metallurgical producers serving precision tooling manufacturers. Electromechanical servo drives, precision ballscrews, and REACH-compliant lubricant formulations constitute critical input dependencies. Single-source vulnerability concentrates in precision motion control subsystems from a limited vendor set serving aerospace qualification programs. Distribution runs through direct OEM and Tier-1 supplier relationships, with regional fabricators accessing equipment through authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The walform machines market functions as a cost-of-compliance arena where REACH substance restrictions and EPA NESHAP rules erect durable barriers to entry for non-certified equipment builders. Regulatory validation timelines exceeding 18 months for aviation-qualified platforms protect incumbent positions while raising capital requirements for prospective entrants.
For Market Incumbents: To counter servo drive supplier concentration risk, anchor supply security through backward integration into precision motion control manufacturing or long-term capacity reservations with German and Japanese electromechanical vendors. Defend aerospace Tier-1 relationships by pre-certifying minimal-lubrication process windows ahead of REACH enforcement deadlines.
For New Entrants and Emerging Players: Digital-channel routes through predictive maintenance platforms and remote diagnostics subscriptions offer lower-friction entry than capital equipment sales. Target India's automotive component export corridors near Chennai and Pune where ISO-certified cold-forming capacity remains underpenetrated. Lead with throughput-based service contracts rather than traditional equipment sales to bypass incumbent qualification advantages.
For Investors and Strategic Acquirers: Tier-1 supplier consolidation into centralized procurement scorecards is the leading indicator that vendor qualification depth is becoming the primary value driver. Position acquisition screening around electromechanical servo specialists with existing aviation qualification pathways. Monitor EPA NESHAP enforcement intensity as the signal for accelerated replacement demand across U.S. hydraulic system manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Technology Acquisition | Secures precision motion control capabilities essential for aerospace Tier-1 qualification programs. |
| Minimal-Lubrication Process Certification | Addresses REACH hydraulic fluid restrictions ahead of German automotive supplier mandates. |
| India Market Entry Partnership | Establishes first-mover positioning in underpenetrated automotive export zones near Chennai. |
| Predictive Maintenance Platform Launch | Enables outcome-based contracts where machine builders assume uptime risk from Tier-1 buyers. |
| ISO 19879 Validation Acceleration | Compresses aviation qualification timelines to capture OEM specification windows. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC 10-K disclosures from publicly traded industrial equipment manufacturers formed the secondary backbone of this analysis. Primary fieldwork encompassed structured interviews with plant engineers at automotive Tier-1 suppliers, procurement directors at hydraulic system integrators, aftermarket service heads, and technical R&D leads at precision forming equipment builders. Bottom-up equipment shipment data triangulated against top-down end-use industry capacity expansion plans to validate volume estimates across the analysis window.
Historical trendline analysis of press machine and servo-driven platform deployments established baseline growth trajectories, with forward projections incorporating technology substitution rates and regulatory compliance deadlines. Segmentation modeling spanned machine architecture, power system type, application end-use, and customer tier dimensions. CAGRs derived from fitted growth curves adjusted for equipment replacement cycles and Industry 4.0 adoption intensity in German automotive supplier parks. Forecast inputs included MIIT industrial upgrading program incentives and EPA NESHAP retrofit timelines.
The model holds under stable alloy steel pricing and sustained REACH enforcement; deviation in servo drive supply disruptions or tariff escalations on precision motion control imports would shift equipment delivery timelines and pricing trajectories. A small set of named triggers—ECHA substance restriction expansion, FAA airframe production rate adjustments, and German automotive OEM electrification capex reallocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Press Brakes Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
North America Construction Equipment Market