
 Industrial Hose Assemblies Market | 2026-2036
Industrial Hose Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hose Assemblies Market Outlook
Modular hose-assembly bundling is realigning buyer choice across capital-intensive industries. Parker Hannifin Corp. leverages integrated fitting-and-hose kits to reduce field installation time for hydraulic systems. Gates Corporation anchors its position through advanced rubber-compounding R&D for extreme-temperature oil and gas service. Continental AG differentiates via thermoplastic composite constructions that compete on weight reduction against traditional rubber architectures.
Industrial hose assemblies consist of flexible reinforced tubes with permanently attached end fittings, typically rated by working pressure, temperature tolerance, and chemical compatibility with conveyed media. They convey fluids, gases, and granular materials under pressure across fixed infrastructure gaps in manufacturing, extraction, and processing environments. Rubber hoses dominate mature replacement demand in mining and agriculture, while composite hoses capture margin pools in chemical handling where corrosion resistance commands specification premiums. PVC hoses sustain volume in water-transfer applications where cost sensitivity outweighs performance thresholds.
OSHA regulates pressure-equipment safety in US industrial workplaces, while REACH governs chemical compatibility and material disclosure across European supply chains. ISO 1436 and SAE J517 establish dimensional and performance baselines that shape product access into OEM and aftermarket channels. Stakeholders must monitor evolving PFAS restrictions and bio-based elastomer certifications that will redefine material qualification pathways.
Market Dynamics
Modular bundling of hose-assembly kits is compressing procurement cycles across capital-intensive sectors, forcing suppliers to integrate fitting-and-hose configurations that slash field installation time and reduce total cost of ownership for hydraulic system operators.
Growth Catalysts
- REACH chemical disclosure mandates:European manufacturers are upgrading material certifications to capture specification premiums in chemical-handling applications where corrosion-resistant composite hoses command higher margins than standard rubber alternatives.
- Permian Basin exploration intensity:High-pressure composite hose procurement is accelerating as drilling contractors replace legacy equipment to handle sour gas and abrasive drilling fluids in West Texas shale formations.
- Automotive fluid-transfer line replacement:Germany's industrial manufacturing corridor sustains steady aftermarket demand for hydraulic hose assemblies as OEMs maintain rigid preventive maintenance schedules across stamping and assembly lines.
Market Restraints
- Natural rubber price volatility:Input cost swings for synthetic and natural rubber compounds constrain margin stability for manufacturers serving price-sensitive agricultural and water-transfer segments.
- Specialty elastomer supply concentration:Fluoroelastomer production for extreme-temperature oil and gas service concentrates among a handful of chemical suppliers, creating vulnerability for hose makers dependent on FKM compounds.
- PVC substitution ceiling:Thermoplastic PVC hoses face performance barriers in high-pressure hydraulic applications above 3,000 PSI, limiting penetration into premium industrial segments.
Strategic Opportunities
- Bio-based elastomer certification pathways:Emerging USDA and EU Green Deal bio-preferred standards are creating first-mover advantages for compounders developing renewable feedstock alternatives to petroleum-derived rubber.
- Offshore Brazil pre-salt development:Deepwater production infrastructure in the Santos Basin is driving demand for subsea-rated hose assemblies with enhanced fatigue resistance and saltwater corrosion protection.
- Predictive maintenance integration:Sensor-embedded smart hose assemblies that monitor pressure cycles and wear states are opening service-contract revenue streams for industrial distributors.
Industry Challenges
- PFAS material phase-out complexity:Hose manufacturers face reformulation timelines and retesting costs as EPA and ECHA restrictions on per- and polyfluoroalkyl substances force substitution of legacy PTFE-lined assemblies.
- Pressure-equipment directive harmonization:Misalignment between OSHA workplace safety enforcement and ISO 1436 dimensional standards creates certification friction for suppliers serving both North American and European OEM channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hose Assemblies Market |
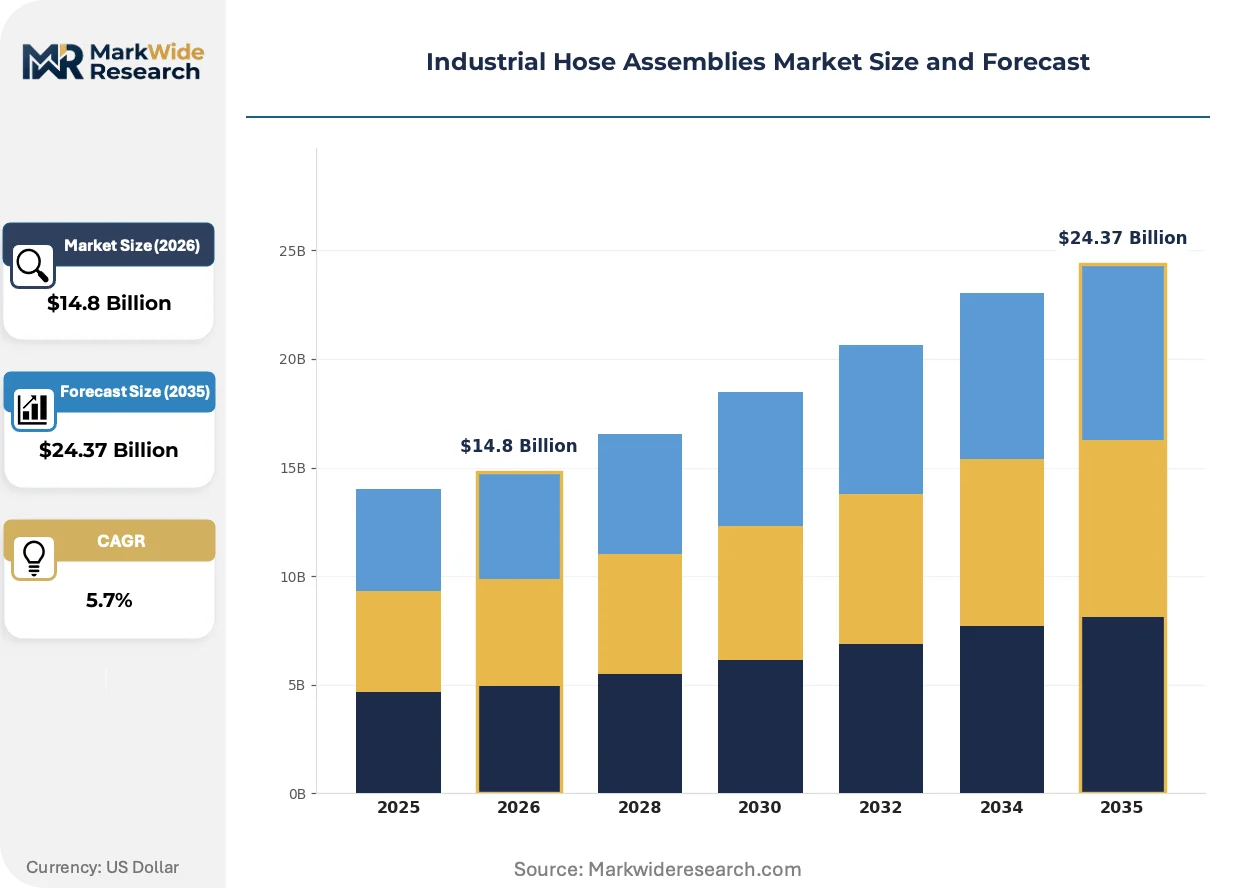
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen Hoses, Rubber Hoses, PVC Hoses, Composite Hoses Application: Water Transfer, Chemical Handling, Oil & Gas, Air and Gas End User: Manufacturing, Construction, Agriculture, Mining Distribution Channel: Direct Sales, Online Retail, Distributor Network, Wholesalers |
| Companies Covered | Parker Hannifin Corp., Gates Corporation, Continental AG, Eaton Corporation Plc., Trelleborg AB, Manuli Hydraulics Group, Alfagomma Group, Transfer Oil Group, Semperit AG Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hose Assemblies Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are forcing simultaneous reinvention of hose construction architectures and compliance documentation protocols across industrial supply chains.
Thermoplastic composite constructions are rewriting competitive positioning in weight-critical mobile equipment applications. These hybrid tube-reinforcement systems deliver 30-40% mass reduction versus conventional rubber-wire architectures. Agricultural machinery OEMs and aerial lift manufacturers are accelerating specification shifts toward thermoplastic alternatives for boom and implement hydraulics. The technology is rewriting sourcing patterns as Tier-1 suppliers backward-integrate composite extrusion capabilities previously held by specialized compounders.
REACH Article 33 substance disclosure requirements are tightening material traceability obligations across European chemical-handling supply chains. Hose assemblers must now document full constituent chemistry down to 0.1% weight concentration for SVHC-listed compounds. German process industry buyers are demanding extended-SDS documentation as a condition of contract award. This regulatory pressure is compressing supplier qualification timelines and favoring vertically integrated manufacturers with captive compound development.
Integrated fitting-and-hose kit procurement is displacing component-level purchasing in maintenance-repair-operations channels. Industrial distributors are bundling pre-crimped assemblies with installation torque specifications and warranty coverage. Mining and construction fleet operators in Australia and Canada are consolidating vendor relationships around single-source kit suppliers. This consolidation is visible most acutely in remote resource extraction sites where inventory reduction and field reliability outweigh unit price considerations.
Industrial Hose Assemblies Market Segmentation
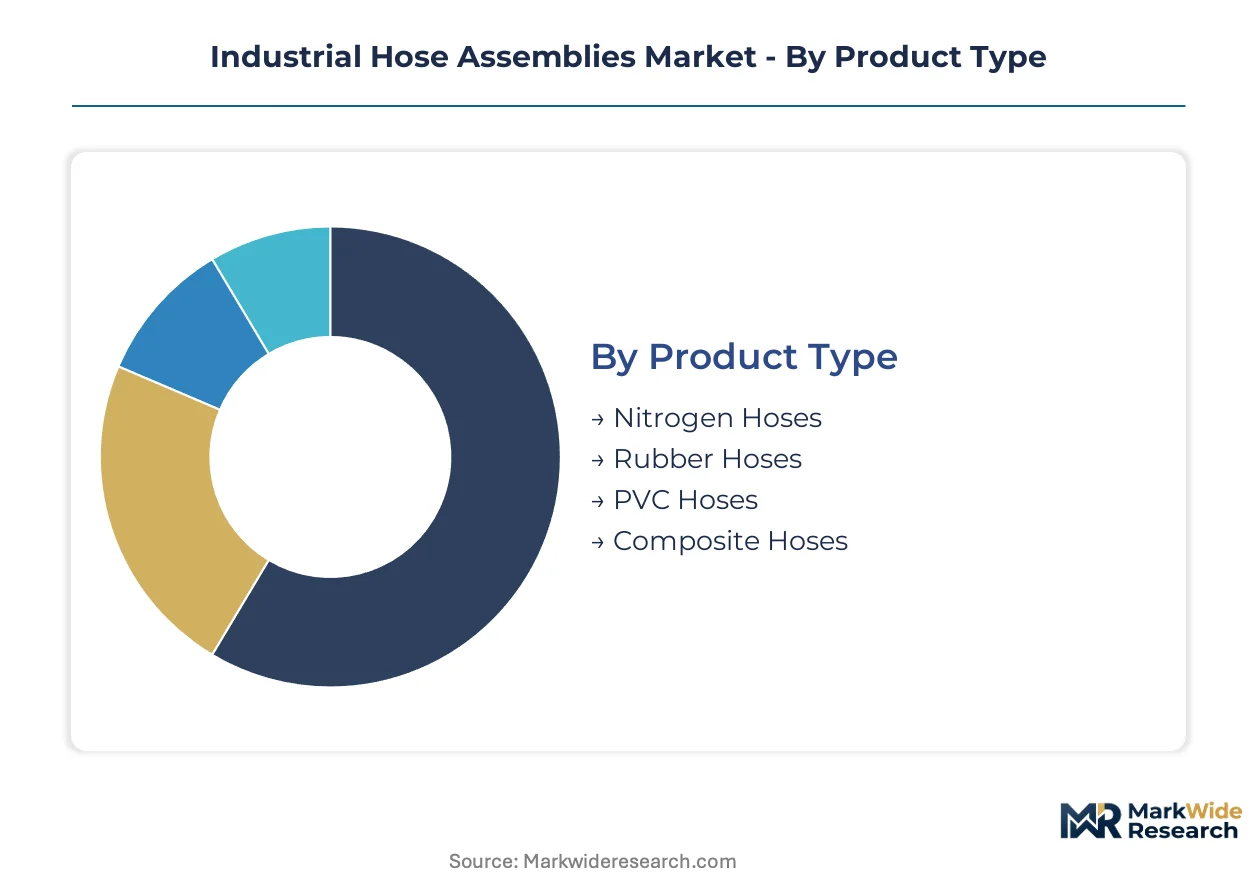
Segmentation in industrial hose assemblies reveals how capital intensity, regulatory exposure, and operational criticality reshape procurement patterns across end-use industries. Buyers prioritize working pressure ratings, chemical compatibility matrices, and total cost of ownership calculations that vary sharply by application environment.
Product Type:
Capital intensity escalates dramatically from commodity thermoplastic extrusion to multi-layer composite constructions requiring specialized mandrel-winding equipment and pressure-testing infrastructure.
- Composite Hoses:Multi-layer thermoplastic and metal foil constructions with internal wire helix reinforcement deliver corrosion resistance for aggressive chemical and sour gas service. Demand concentrates in German chemical processing corridors and Permian Basin drilling contractors where REACH compliance and sour gas exposure command specification premiums.
- Rubber Hoses:Reinforced elastomer tubes with steel wire or textile braid reinforcement dominate high-pressure hydraulic applications above 3,000 PSI. Mining operations in Western Australia and agricultural machinery OEMs in Iowa sustain replacement cycles for standard rubber architectures where temperature tolerance and abrasion resistance outweigh weight considerations.
- PVC Hoses:Lightweight thermoplastic constructions serve cost-sensitive water transfer and low-pressure pneumatic applications.
- Nitrogen Hoses:Specialized high-pressure assemblies for inert gas service in semiconductor fabrication and food processing environments.
Most installed capacity flows through Rubber Hoses. Expansion is steepest in Composite Hoses.
Application:
Margin structures diverge based on consequence of failure, with hydrocarbon containment and toxic chemical handling commanding certification premiums that water transfer cannot support.
- Oil & Gas:High-pressure composite and steel-reinforced rubber assemblies withstand sour gas, abrasive drilling fluids, and subsea saltwater exposure in Brazil's Santos Basin and West Texas shale formations. Specification requirements from API and ISO 13628-5 drive qualification timelines exceeding 18 months for subsea-rated constructions.
- Chemical Handling:Corrosion-resistant composite hoses with PTFE or polypropylene liners convey acids, solvents, and caustics under REACH Article 33 disclosure mandates. German process industry buyers demand extended-SDS documentation as a condition of contract award, compressing supplier qualification timelines.
- Water Transfer:PVC and standard rubber hoses serve irrigation, dewatering, and construction site fluid movement where cost sensitivity dominates specification criteria.
- Air and Gas:Compressed air and inert gas service in manufacturing facilities requires oil-mist-resistant liners and anti-static constructions.
Specification value concentrates in Oil & Gas. Regulatory complexity is expanding most quickly in Chemical Handling.
End User:
Procurement sophistication scales with fleet size and downtime costs, with integrated mining operators and automotive OEMs driving kit-bundling consolidation that fragmented agricultural buyers cannot match.
- Manufacturing:Automotive stamping and assembly lines in Germany's industrial corridor sustain preventive maintenance schedules for hydraulic hose assemblies. OEMs specify ISO 1436-compliant constructions with documented fatigue life ratings to minimize unplanned downtime.
- Mining:Remote extraction operations in Western Australia and Canada's oil sands consolidate vendor relationships around single-source kit suppliers. Inventory reduction and field reliability outweigh unit price considerations where logistics costs compound procurement economics.
- Construction:Mobile equipment fleets and temporary infrastructure projects drive spot purchasing through distributor networks.
- Agriculture:Seasonal equipment operators prioritize replacement cost over performance specifications for irrigation and implement hydraulics.
Contract discipline is tightest in Manufacturing. Consolidation pressure is most intense in Mining.
Distribution Channel:
Channel selection reflects technical complexity and geographic concentration, with direct relationships dominating specification-intensive applications and distributor networks capturing fragmented maintenance demand.
- Distributor Network:Industrial distributors bundle pre-crimped assemblies with installation torque specifications and warranty coverage. Mining and construction fleet operators in remote resource extraction sites depend on distributor technical support and localized inventory availability.
- Direct Sales:OEM and large fleet accounts negotiate multi-year supply agreements with captive compound development and dedicated field engineering support. German automotive manufacturers and Brazilian pre-salt contractors specify direct relationships for critical fluid-transfer lines.
- Online Retail:Standardized commodity hoses move through digital channels for small fleet and individual equipment owner maintenance.
- Wholesalers:Bulk volume aggregation serves regional agricultural and construction supply houses with limited technical specification capabilities.
Technical support requirements favor Distributor Network for complex applications. Direct Sales captures specification control in OEM channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial hose assemblies industry traces its modern scale to post-war manufacturing corridors in Germany and the United States, where hydraulic systems for automotive and aerospace applications drove standardization of reinforced elastomer constructions.
United States
Permian Basin drilling contractors drive high-pressure composite hose procurement for sour gas and abrasive drilling fluid handling. OSHA pressure-equipment directives enforce material certification requirements for chemical-handling applications. Houston-Gulf Coast petrochemical clusters sustain replacement cycles for refinery and offshore service lines.
Germany
Automotive fluid-transfer lines and hydraulic systems in stamping and assembly operations sustain steady aftermarket demand. REACH compliance mandates tighten material traceability obligations for chemical-handling supply chains. The industrial manufacturing corridor spanning Baden-Württemberg and North Rhine-Westphalia concentrates specification-intensive procurement from process industry buyers.
Brazil
Pre-salt development in the Santos Basin accelerates demand for subsea-rated hose assemblies with enhanced fatigue resistance. ANVISA and environmental licensing requirements govern offshore equipment certification timelines. Rio de Janeiro-Petrobras supply chain clusters anchor procurement for deepwater production infrastructure.
China
Mining equipment manufacturing and agricultural machinery production sustain volume demand for rubber hose architectures. GB standards and MIIT industrial safety regulations shape product access into domestic OEM channels. Yangtze River Delta manufacturing zones concentrate fabrication capacity for export-oriented hydraulic system suppliers.
Australia
Remote mining operations in Western Australia's Pilbara region consolidate vendor relationships around single-source kit suppliers for inventory reduction. Work health and safety regulations enforce pressure-equipment inspection protocols for mobile fleet hydraulics. Perth-based distributor networks provide localized technical support for resource extraction sites where logistics costs compound procurement economics.
Industrial Hose Assemblies Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and application complexity dimensions, with integrated compounders capturing specification premiums in chemical-handling and subsea service while standardized rubber fabricators compete on unit cost for agricultural and water-transfer segments. Market structure reflects moderate consolidation among Tier-1 system integrators alongside fragmentation across regional hose assemblers serving maintenance-repair-operations channels. Three archetypes dominate: vertically integrated elastomer compounders with captive fitting production, specialized composite extrusion houses serving weight-critical mobile equipment, and distributor-assemblers bundling kit configurations for fleet operators. Competitive intensity centers on backward integration into polymer compounding and geographic expansion through distributor network acquisitions.
Among diversified industrial conglomerates with hydraulics divisions, Parker Hannifin Corp. and Eaton Corporation Plc. occupy positions as system-level suppliers integrating hose-and-fitting configurations. Gates Corporation exemplifies the compound-specialist archetype with deep elastomer formulation capabilities. Continental AG anchors the automotive-tier vector with thermoplastic composite constructions competing on weight reduction. Trelleborg AB represents the engineered polymer house serving extreme-environment oil and gas applications.
| Leading Market Players |
|---|
| Parker Hannifin Corp. |
| Gates Corporation |
| Continental AG |
| Eaton Corporation Plc. |
| Trelleborg AB |
| Manuli Hydraulics Group |
| Alfagomma Group |
| Transfer Oil Group |
| Semperit AG Holding |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM preventive maintenance schedules in Germany's industrial corridor are compressing procurement cycles and forcing suppliers to absorb certification documentation costs into bundled kit pricing. This demand-side discipline is reshaping how compounders and assemblers negotiate raw material pass-through clauses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade and volume scale as primary price differentiation drivers. Cost compression in agricultural and water-transfer segments is intensifying because natural rubber price volatility constrains margin stability. Mining fleet operators in Australia show least price sensitivity, while seasonal agricultural equipment buyers prioritize unit cost over performance specifications.
Supply Chain Analysis
Domestic-content mandates in Brazil's ANVISA licensing framework and China's GB standards compliance are reshaping sourcing patterns for subsea-rated and hydraulic system suppliers. Manufacturing concentrates in Germany, China, and the United States, with supply chains drawing from fluoroelastomer producers, synthetic rubber compounders, and steel wire reinforcement suppliers. Single-source vulnerability in FKM specialty elastomer production creates qualification risk for extreme-temperature oil and gas service lines. Distribution runs through industrial distributors bundling pre-crimped assemblies with technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based elastomer certification premiums that command specification advantages as REACH and USDA bio-preferred standards tighten.
For Market Incumbents: Extend captive compound development capabilities to capture REACH Article 33 documentation premiums and insulate against fluoroelastomer supply concentration. Backward integration into thermoplastic composite extrusion counters weight-driven specification shifts from agricultural machinery OEMs. Channel control through distributor network acquisitions in Australia's Pilbara region locks in remote mining fleet relationships. For New Entrants and Emerging Players: Digital distributor platforms serving fragmented agricultural and construction maintenance-repair-operations channels offer lowest barrier to entry. Sensor-embedded smart hose assemblies for predictive maintenance contracts represent the most penetrable white-space, with industrial distributors as the natural go-to-market partner for field reliability guarantees. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized composite extrusion houses serving weight-critical mobile equipment applications, where thermoplastic constructions displace rubber architectures. The five-to-ten-year viability window favors compounders with USDA bio-preferred certification pathways. Watch EPA and ECHA PFAS restriction timelines as inflection indicators for PTFE-lined assembly substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of REACH-compliant elastomers secures German chemical-handling contract awards. |
| Bio-Based Elastomer Certification Investment | USDA bio-preferred pathways create first-mover pricing power in sustainable specification tiers. |
| Distributor Network Geographic Expansion | Perth-based technical support capabilities capture Western Australia mining fleet consolidation. |
| Smart Hose Predictive Maintenance Development | Sensor-embedded assemblies open recurring service-contract revenue streams with industrial distributors. |
| Subsea-Rated Assembly Qualification | ANVISA-compliant fatigue-resistant constructions access Brazil Santos Basin pre-salt infrastructure procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydraulic system procurement managers, maintenance directors at mining operations, aftermarket service heads, and technical R&D directors at compounders with secondary validation from customs trade data, SEC filings, ACC and Cefic industry reports, and OSHA enforcement records. Bottom-up assembly of segment-level demand and top-down macroeconomic triangulation anchored volume estimates.
Historical reference periods established baseline penetration rates for composite versus rubber architectures, with projections calibrated across the analysis window using modeled segmentation across product type, application environment, end-user procurement sophistication, and distribution channel structure. CAGRs derived from regression of replacement cycle frequencies, capital expenditure patterns in oil and gas exploration, and regulatory compliance cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for bio-based elastomer certification and PFAS substitution timelines would alter the outlook. Forecasts reflect assumptions about REACH enforcement intensity, natural rubber price stability, and mining fleet consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Forklift Tire Market