
 Global Construction Industry Core Drill Market | 2026-2036
Global Construction Industry Core Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Industry Core Drill Market Analysis
Chinese carbide bit manufacturers are rebalancing capacity toward higher-margin diamond segments after raw material cost shifts. Hilti leverages direct-to-contractor service networks across Europe and North America to sustain premium positioning. Husqvarna anchors its competitive stance through integrated dust extraction systems that extend jobsite compliance capabilities. Bosch competes on brushless motor platforms that reduce thermal fatigue during continuous concrete cutting operations.
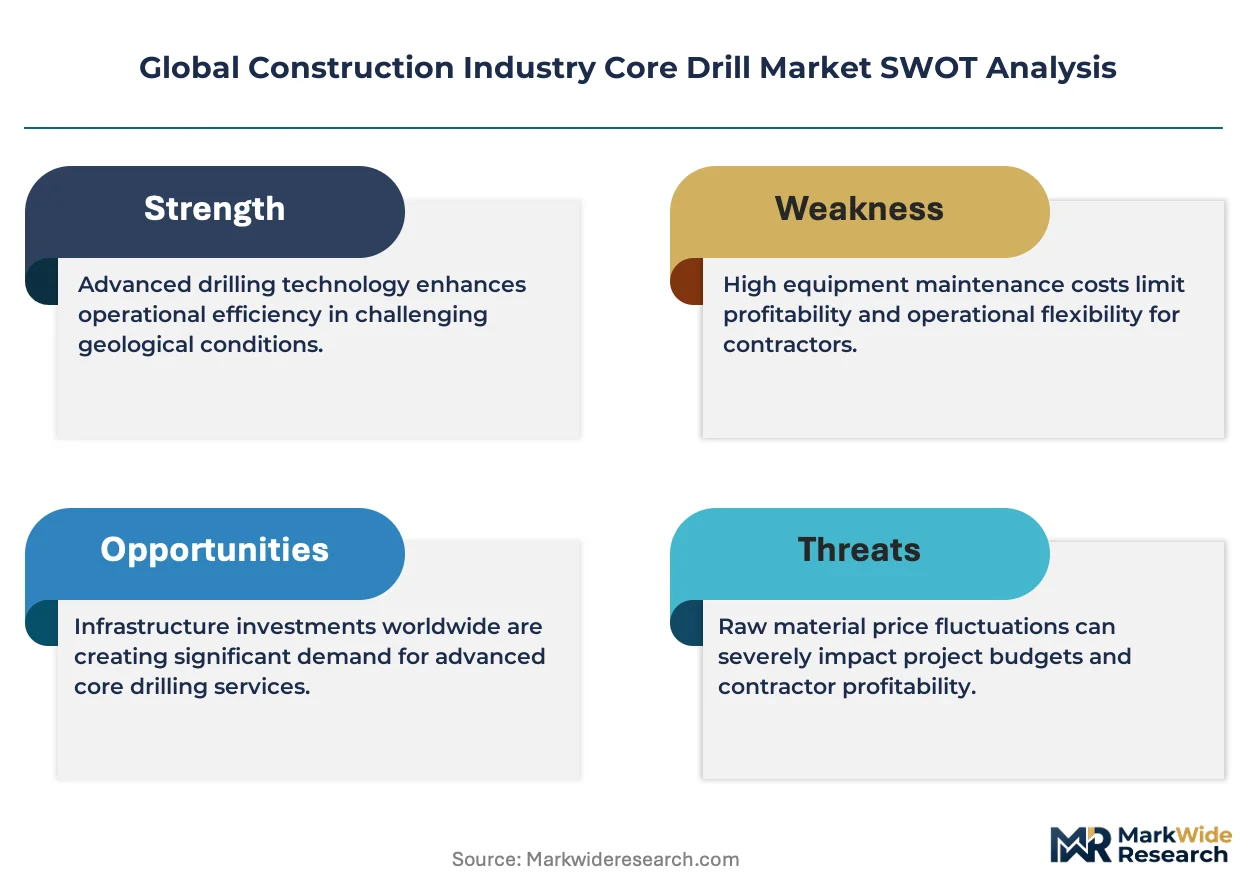
Construction industry core drills are rotary cutting tools engineered to extract cylindrical cores from reinforced concrete, masonry, and asphalt substrates, typically operating at controlled RPM ranges between 400 and 2,500 depending on bit diameter and material density. Diamond core drills dominate commercial applications where precision through heavily reinforced structural concrete justifies higher consumable costs, while carbide variants occupy residential and light commercial segments where intermittent duty cycles limit wear penalties. Electric technology leads volume shipments due to plug-in convenience on grid-connected sites, though hydraulic systems are gaining share in remote infrastructure and underwater piling projects where pneumatic or manual alternatives face power source constraints.
OSHA silica exposure limits in the United States and the EU Machinery Directive's vibration emission standards are forcing manufacturers to redesign guard systems and integrate wet-cutting suppression as default configurations. China's SAMR enforcement of GB construction equipment safety codes is raising import barriers for uncertified equipment entering Asian project supply chains. Contractors and rental fleet operators must monitor how regional certification divergence affects cross-border equipment mobility and residual value retention.
Market Dynamics
OSHA silica exposure limits and the EU Machinery Directive's vibration emission standards are compressing equipment replacement cycles and forcing wet-cutting suppression as default across contractor fleets.
Growth Catalysts
- Metro Rail Expansion in India:Urban tunneling projects in Delhi, Mumbai, and Bangalore are accelerating contractor equipment replacement cycles for diamond core drill systems.
- CE Marking Compliance:The EU Machinery Directive's tightened guard system and dust extraction mandates are driving fleet upgrades among European rental operators.
- Hydraulic Technology Penetration:Remote infrastructure and underwater piling projects across Southeast Asia are adopting hydraulic systems where grid power remains unavailable.
Market Restraints
- Synthetic Diamond Cost Volatility:Fluctuations in industrial diamond supply from Russian and African sources are compressing margins for bit manufacturers.
- Carbide Bit Substitution Pressure:Light commercial and residential contractors are extending carbide tool life rather than upgrading to diamond consumables.
- GB Standards Import Barriers:China's SAMR enforcement of construction equipment safety codes is blocking uncertified equipment from entering Asian project supply chains.
Strategic Opportunities
- Vietnam Infrastructure Build-Out:Highway tunneling and port expansion projects are creating first-mover advantages for wet-cutting system suppliers.
- Brushless Motor Convergence:Integration of brushless platforms with IoT-enabled torque monitoring is opening premium positioning for fleet telemetry providers.
- EU Green Deal Procurement Mandates:Public works contractors must demonstrate embodied carbon reduction in equipment selection, favoring refurbished and remanufactured drill systems.
Industry Challenges
- Diamond Segment Bonding Expertise Gap:Specialized metallurgical knowledge for matrix formulation is concentrating among aging technical workforces in Germany and Japan.
- Multi-Jurisdiction Certification Timelines:Contractors operating across US, EU, and Chinese projects face divergent testing protocols for electromagnetic compatibility and operator safety systems.
- Legacy Fleet Electrification Compatibility:Retrofitting dust extraction and vibration damping onto existing drill rigs requires engineering resources most rental operators lack.
Report Scope
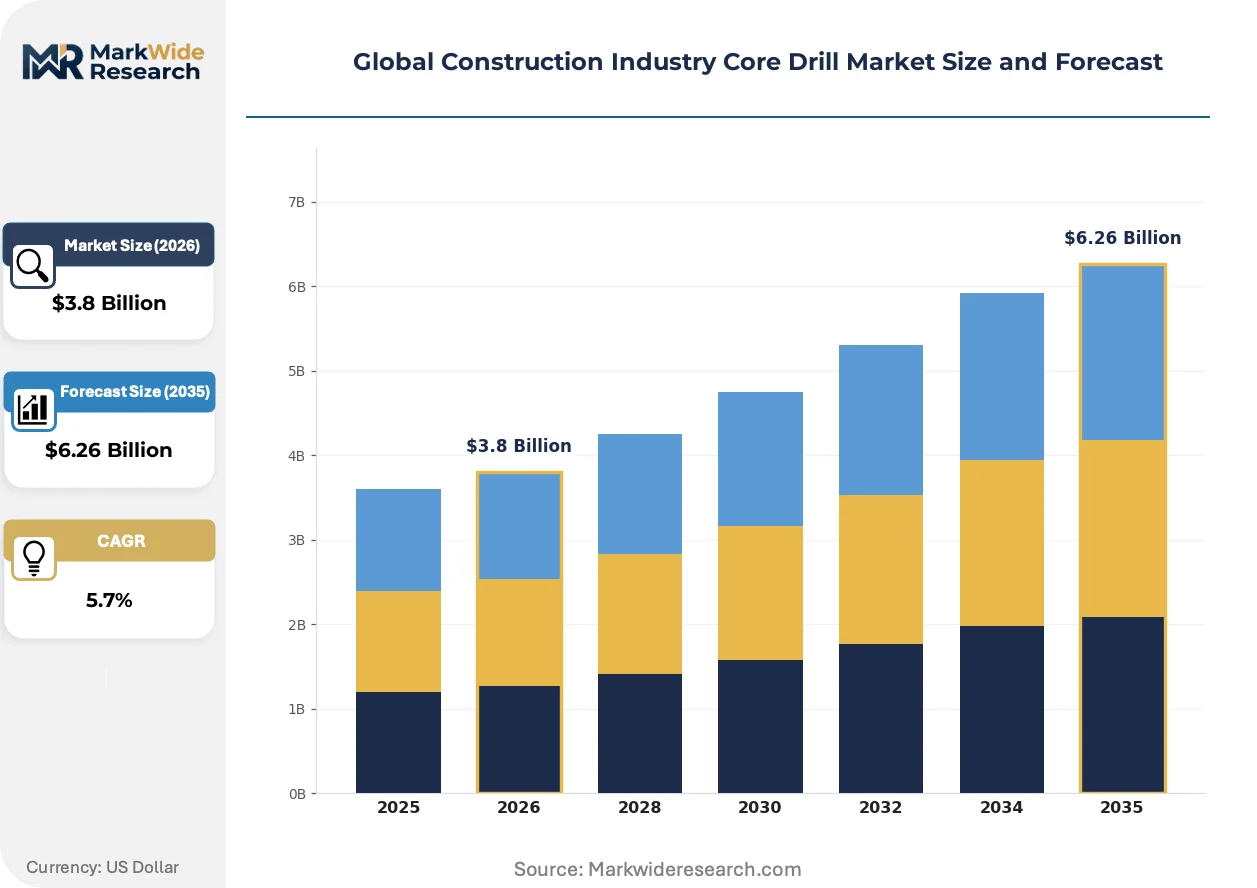
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Industry Core Drill Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Core Drills, Carbide Core Drills, Water Core Drills, Hollow Core Drills End User: Commercial Contractors, Residential Builders, Infrastructure Developers, Demolition Services Application: Concrete Cutting, Road Construction, Mineral Exploration, Reinforced Concrete Drilling Technology: Electric Core Drill, Pneumatic Core Drill, Hydraulic Core Drill, Manual Core Drill |
| Companies Covered | Hilti, Husqvarna, Bosch, Makita, Tyrolit, DeWalt, Milwaukee, Eibenstock, Dr. Schulze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Industry Core Drill Market Emerging Trajectories
Equipment intelligence and regulatory compliance automation are converging to reshape how contractors specify, operate, and maintain core drill assets across project portfolios.
Brushless motor platforms with integrated thermal management are converging with real-time torque feedback systems. Large-scale infrastructure contractors in Germany and Australia are specifying these configurations for continuous concrete cutting operations. This convergence is compressing the performance gap between mid-tier and premium equipment tiers while extending mean time between failures.
REACH restrictions on hexavalent chromium in metal coatings are forcing manufacturers to reformulate diamond bit matrices and protective guard finishes. The industrial consequence is elevated R&D expenditure and extended product qualification timelines. Wet-cutting suppression systems are seeing accelerated adoption in EU public works contracts as the compliance pathway of least resistance.
Rental fleet operators are unbundling after-sales service from equipment procurement, contracting maintenance and bit resupply separately from capital acquisition. This pattern is displacing traditional bundled distributor relationships in North American metropolitan construction markets. Equipment-as-a-service pilots are most visible in Texas and Florida where contractor liquidity constraints favor operational expenditure models.
Global Construction Industry Core Drill Market Segmentation
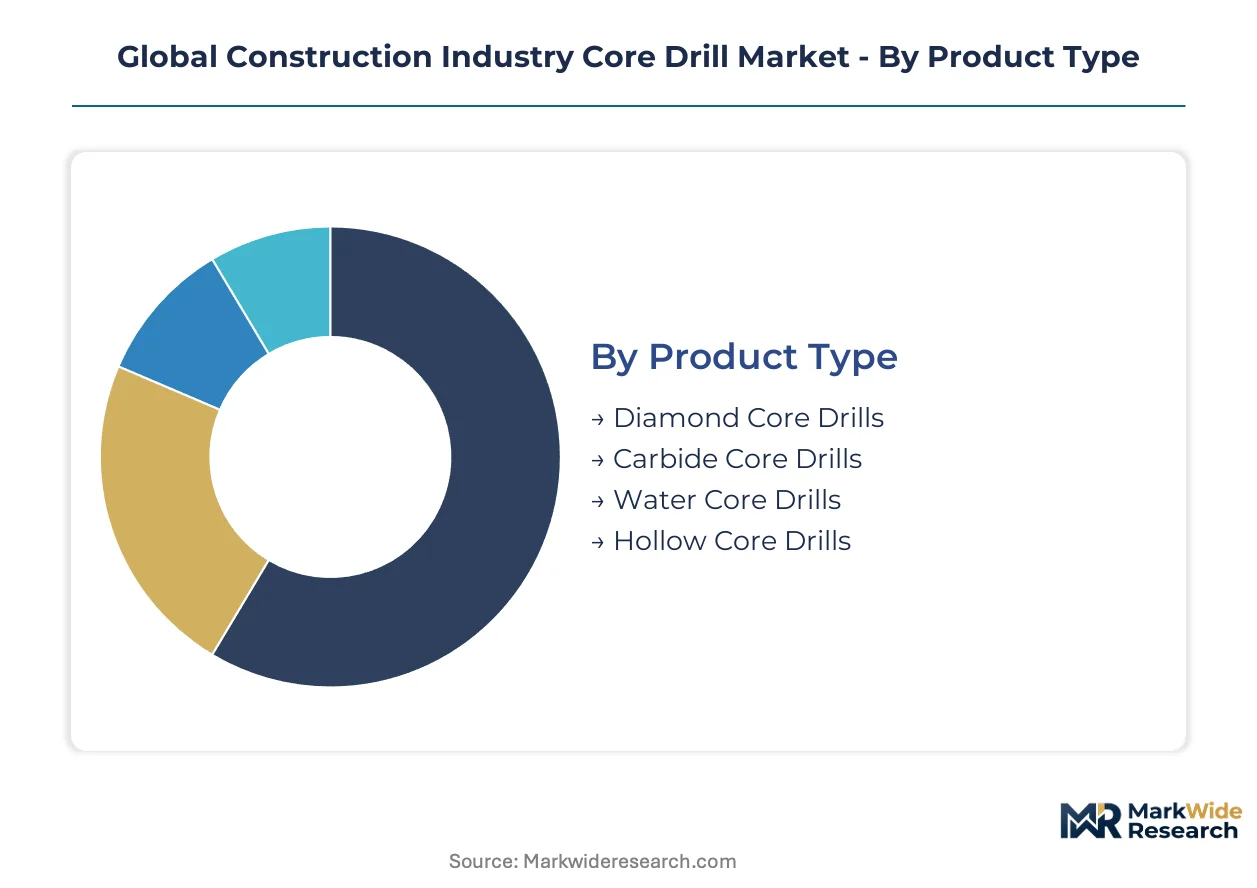
Segmentation reveals how core drill specifications diverge across project scales and substrate demands. Contractors match bit composition, power source, and cutting mechanism to material density, reinforcement levels, and jobsite power availability.
Product Type:
Diamond segments function as standalone precision tools for engineered concrete, while carbide variants embed into broader residential toolkits as intermittent-duty options.
- Diamond Core Drills:Synthetic diamond segments bonded to steel cores cut through heavily reinforced structural concrete with minimal deviation. Demand concentrates in German and Australian infrastructure projects where specification engineers mandate precision tolerances for structural integrity testing.
- Carbide Core Drills:Tungsten carbide tipped bits operate at lower RPM ranges suitable for masonry and light concrete. Residential builders across Texas and Florida extend tool life through selective deployment rather than upgrading to diamond consumables.
- Water Core Drills:Integrated coolant channels suppress silica dust and extend bit life in continuous cutting operations. OSHA compliance mandates in the United States accelerate specification for commercial demolition crews.
- Hollow Core Drills:Annular cutting geometry removes only material perimeter, leaving solid core intact for extraction. Mineral exploration teams in Western Australia deploy these for geotechnical sampling where core preservation matters.
Volume placements concentrate in carbide systems; the faster expansion belongs to diamond segments as infrastructure specifications tighten.
End User:
Customer type determines procurement cadence, with fleet operators replacing on compliance cycles versus project-based acquisition.
- Commercial Contractors:Mid-rise and high-rise concrete specialists maintain diversified bit inventories across diameter ranges. European rental operators serving these contractors face CE marking upgrade deadlines that compress replacement timelines.
- Residential Builders:Single-family and light commercial developers prioritize portability and plug-in convenience over cutting speed. These operators show highest price sensitivity and extend carbide tool life through intermittent duty patterns.
- Infrastructure Developers:Metro rail and highway tunneling contractors in India specify hydraulic diamond rigs for continuous reinforced concrete penetration. Public procurement mandates increasingly require dust suppression and vibration compliance as default.
- Demolition Services:Structural dismantling specialists demand rapid bit change systems and integrated extraction. REACH restrictions on hexavalent chromium coatings force these operators to validate supplier reformulation timelines.
Commercial contractors drive current volume; infrastructure developers are climbing the fastest as megaproject pipelines accelerate across Southeast Asia.
Application:
Substrate density and reinforcement concentration dictate cutting mechanism selection across project phases.
- Concrete Cutting:General-purpose coring for HVAC penetrations, electrical conduits, and plumbing rough-ins represents baseline demand. Brushless motor platforms with thermal management gain specification in German continuous-operation contracts.
- Road Construction:Asphalt and concrete pavement coring for quality control testing requires wet suppression to manage silica exposure. State DOT procurement in the United States increasingly mandates integrated dust extraction.
- Mineral Exploration:Geotechnical core extraction demands hollow bit geometry and precise RPM control to preserve sample integrity. Exploration contractors in Western Australia specify telemetry-enabled torque monitoring for remote site documentation.
- Reinforced Concrete Drilling:High-density rebar penetration requires diamond segments with optimized bond matrices. Japan's aging metallurgical workforce concentrates specialized matrix formulation knowledge among limited suppliers.
General concrete cutting holds volume dominance; reinforced concrete drilling shows steepest expansion trajectory as structural engineering specifications tighten globally.
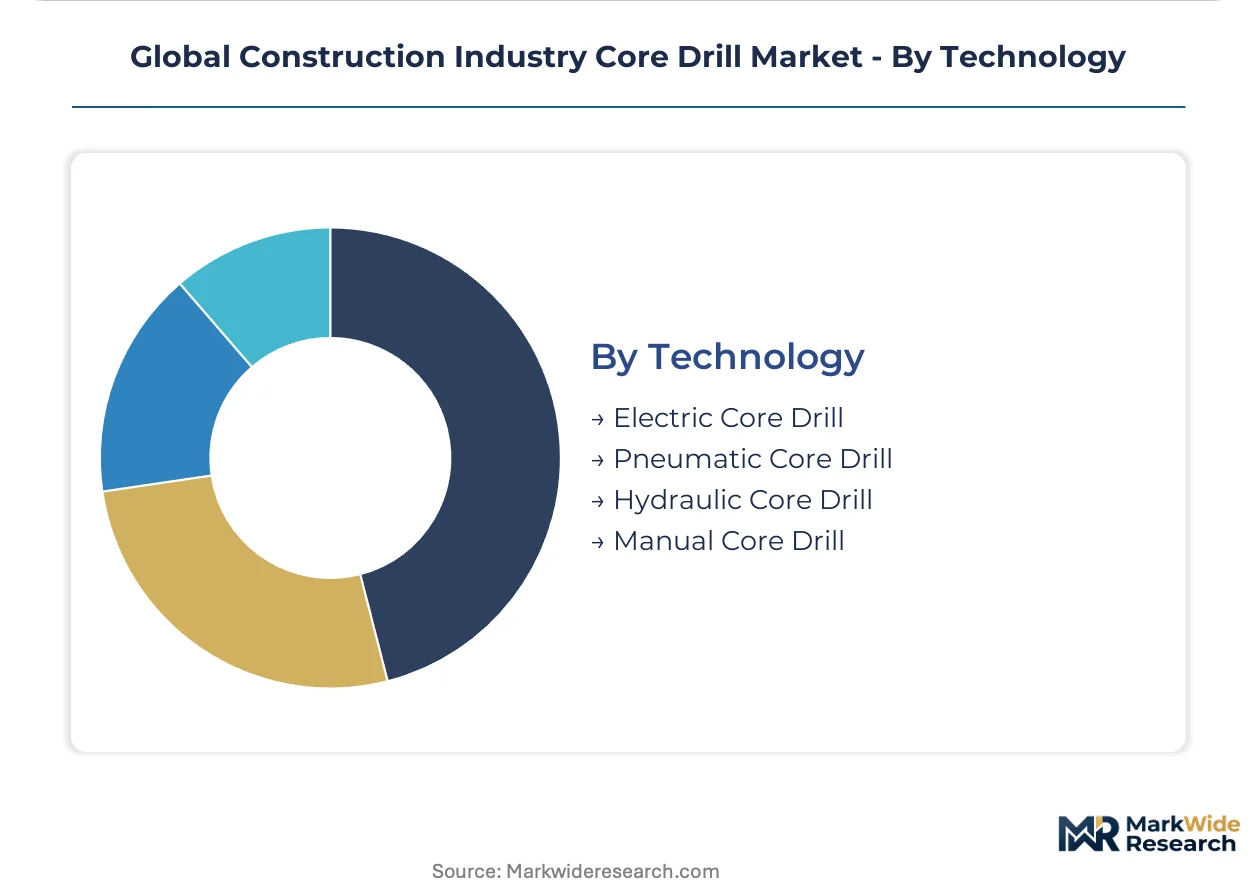
Technology:
Power source selection tracks jobsite infrastructure availability and duty cycle intensity.
- Electric Core Drill:Grid-connected sites favor brushless motor platforms that reduce thermal fatigue during extended cutting sequences. Bosch competes through integrated motor-thermal management systems in North American metropolitan markets.
- Pneumatic Core Drill:Compressed air systems eliminate electrical hazard in wet cutting environments. These units retain niche positioning in mining and tunneling operations where explosive atmosphere certification applies.
- Hydraulic Core Drill:Remote infrastructure and underwater piling projects across Vietnam and Indonesia adopt hydraulic systems where grid power remains unavailable. Southeast Asian procurement is accelerating for port expansion and highway tunneling.
- Manual Core Drill:Hand-operated units serve limited penetration depths in residential renovation and archaeological preservation. These systems face displacement as lightweight electric alternatives improve portability.
Electric systems anchor current volume placements; hydraulic configurations are gaining share fastest in Southeast Asian infrastructure build-out.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic diamond feedstock from Russian and African sources anchors manufacturing cost structures across multiple geographies. Infrastructure investment intensity varies sharply by country, with regulatory divergence creating distinct equipment specification environments.
United States
Commercial demolition crews and highway contractors drive diamond core drill procurement for reinforced concrete penetration. OSHA silica exposure limits mandate wet-cutting suppression systems as default configurations across federal and state-level projects. Texas and Florida metropolitan construction markets show highest rental fleet replacement velocity as compliance deadlines compress.
Germany
Precision infrastructure specifications from engineering consultants sustain premium diamond segment demand for structural integrity testing. CE marking requirements under the EU Machinery Directive force guard system redesigns and vibration emission reductions. Industrial clusters around Stuttgart and Munich concentrate metallurgical expertise for diamond matrix formulation.
China
Urban metro expansion and highway tunneling accelerate contractor equipment replacement cycles in megaproject corridors. SAMR enforcement of GB construction equipment safety codes blocks uncertified imports from entering Asian project supply chains. Yangtze River Delta manufacturing bases rebalance carbide bit capacity toward higher-margin diamond segments.
India
Delhi, Mumbai, and Bangalore metro rail tunneling projects specify hydraulic diamond rigs for continuous reinforced concrete operations. Central government infrastructure procurement mandates increasingly require dust suppression and vibration compliance as technical bid preconditions. Western and Southern state highway authorities are accelerating port expansion equipment procurement.
Vietnam
Highway tunneling and port expansion projects across the Mekong Delta and Northern economic corridor create first-mover advantages for wet-cutting system suppliers. National infrastructure build-out programs prioritize equipment with integrated dust extraction for worker safety compliance. Ho Chi Minh City and Hai Phong industrial zones concentrate contractor fleet procurement decisions.
Global Construction Industry Core Drill Market Vendor Landscape
Global majors compete with regional champions across certification and service network dimensions. The vendor base clusters around three strategic tiers: premium integrated solution providers, mid-tier motor-technology specialists, and regional fabrication houses serving price-sensitive segments. Dominant competitive moves include geographic expansion through distributor acquisition and technology licensing for brushless motor platforms.
Among European-anchored premium-tier providers, Hilti and Husqvarna occupy positions emphasizing direct-to-contractor service networks and integrated dust extraction capabilities. Bosch represents the motor-technology specialist archetype through brushless platform development. Chinese and Japanese manufacturers including Makita and Tyrolit exemplify regional champions competing on manufacturing scale and Asia-Pacific distribution density. Milwaukee and DeWalt sit within the professional tool conglomerate structure, leveraging cross-category brand recognition.
| Leading Market Players |
|---|
| Hilti |
| Husqvarna |
| Bosch |
| Makita |
| Tyrolit |
| DeWalt |
| Milwaukee |
| Eibenstock |
| Dr. Schulze |
| Others |
Supply Flow & Price Mechanics
Captive synthetic diamond production in Russian and African mining operations anchors both raw material security and tiered pricing power for premium bit manufacturers. This upstream control separates diamond segment suppliers from carbide competitors facing tungsten price volatility and spot-market exposure.
Pricing Analysis
Warranty and service bundling unbundling patterns are reshaping procurement economics across contractor segments. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking compliance grade and integrated dust extraction capability. Price differentiation hinges on after-sales service inclusion versus separate maintenance contracting. Cost compression in economy carbide tiers is intensifying because rental fleet operators extend tool life rather than upgrade. Residential builders in Texas and Florida exhibit highest price sensitivity; infrastructure developers in India and Germany show lowest.
Supply Chain Analysis
Direct-to-contractor channels handle fleet operator demand while distributor networks serve fragmented residential buyers. Synthetic diamond feedstock concentrates in Russian and African extraction operations; tungsten carbide sourcing centers on Chinese powder metallurgy. Steel core fabrication and matrix bonding expertise clusters in Germany and Japan. Supply chain risk rests on single-source vulnerability for specialized metallurgical workforce knowledge. Distribution runs through regional rental houses in North America and authorized service dealers in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is unfolding as manufacturers pursue captive synthetic diamond supply to defend margin structures against raw material volatility.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Hilti and Husqvarna should accelerate CE marking and OSHA compliance integration to block uncertified imports from Chinese competitors. Backward integration into diamond segment bonding expertise in Stuttgart and Munich industrial clusters protects against Japan's aging metallurgical workforce attrition. Channel control through direct service networks reinforces premium positioning against mid-tier motor-technology specialists. For New Entrants and Emerging Players: The premium-to-economy price-point gap in wet-cutting suppression systems creates entry space for specification-focused challengers. Vietnam's highway tunneling and port expansion programs represent the most penetrable geography for hydraulic system specialists. Brushless motor platform licensing from established electronics suppliers offers a capital-efficient go-to-market angle for technology-focused entrants targeting fleet telemetry contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial tool conglomerates seeking Asia-Pacific distribution density. Long-term viability favors manufacturers with integrated dust extraction and vibration compliance capabilities as regulatory thresholds tighten across jurisdictions. Acquisition targets should demonstrate SAMR GB standards certification for China market access. The signal to watch is synthetic diamond supply contract renegotiation patterns as Russian source uncertainty persists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Supply | Captive feedstock from Russian and African sources insulates margin compression from commodity volatility. |
| CE Marking and OSHA Compliance Certification | Guard system redesigns and wet-cutting defaults satisfy EU Machinery Directive and silica exposure mandates. |
| Brushless Motor Platform Development | Thermal management integration with IoT torque monitoring opens premium fleet telemetry positioning. |
| Direct-to-Contractor Service Network Expansion | Hilti's European and North American service density sustains premium pricing against distributor-dependent competitors. |
| Hydraulic System Localization for Southeast Asia | Port expansion and highway tunneling projects in Vietnam and Indonesia demand grid-independent power solutions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with equipment procurement managers at infrastructure developers, aftermarket service heads at rental fleet operators, and R&D directors at bit manufacturers combined with OSHA enforcement records, EU Machinery Directive implementation guidance, and SAMR GB standards documentation. Bottom-up project pipeline tracking across Delhi, Mumbai, and Bangalore metro authorities triangulated against top-down manufacturing capacity assessments from Yangtze River Delta industrial zones.
Granularity-level modeling addressed product type at the bit composition tier, power source at the motor technology level, and end-use at the contractor segment resolution across the projection horizon. CAGRs derived from equipment replacement cycle analysis tied to compliance deadline clustering and megaproject award timelines. Segment-level forecasts incorporated brushless motor adoption curves, hydraulic system penetration rates in Southeast Asian infrastructure, and carbide-to-diamond substitution elasticity in residential construction.
Inputs from Russian and African diamond mining operations and Chinese tungsten powder suppliers were available through the study window; gaps in real-time contractor fleet inventory data introduce uncertainty bands around replacement cycle timing. Forecasts reflect assumptions regarding SAMR enforcement consistency, REACH coating restriction timelines, and infrastructure procurement budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Garage Equipment Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Cranes Rental Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Shield Machines Market
Construction Equipment
Felling Heads Market
Construction Equipment
Yard Crane Market
Construction Equipment
Dock Door Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Global Cone Crusher Market