
 Industrial Agitators Market | 2026-2036
Industrial Agitators Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Agitators Market Intelligence
Direct-to-plant technical sales channels is reshaping how industrial agitators reach processing facilities, bypassing traditional distributor networks in favor of application engineering teams embedded at customer sites. Sulzer Ltd. leverages its rotating equipment portfolio to anchor long-term service contracts alongside hardware sales. SPX Flow, Inc. competes through vertical integration into proprietary impeller metallurgy and computational fluid dynamics design tools. Ekato Group specializes in reactor-integrated agitation systems for polymerization and crystallization duties.
Industrial agitators are mechanical devices comprising a motor, drive train, shaft, and impeller assembly designed to induce controlled fluid motion in vessels ranging from laboratory beakers to 50,000-liter reactors, with power ratings spanning fractional horsepower to several hundred kilowatts and rotational speeds adjustable from 10 to 1,500 RPM depending on shear requirements. Their primary purpose is to achieve uniform blending, heat transfer enhancement, solids suspension, gas dispersion, or chemical reaction promotion across process industries. Top entry configurations dominate heavy-duty chemical and mineral processing installations where shaft stability and bearing longevity outweigh access constraints. Magnetic drive technology is displacing conventional packed-gland seals in pharmaceutical and hazardous chemical applications where zero-emission containment is non-negotiable. Water treatment represents a mature application segment with stable replacement demand but thinner margin pools compared to custom-engineered pharmaceutical and specialty chemical systems.
EPA NESHAP standards for hazardous air pollutants and REACH chemical registration requirements in Europe are mandating sealless or low-emission agitator designs, effectively raising technical barriers for equipment lacking certified containment architectures. FDA cGMP guidelines and EMA manufacturing directives for active pharmaceutical ingredients further constrain material selection, surface finish specifications, and cleanability validation protocols for agitators deployed in drug synthesis. Buyers should monitor evolving PFAS restrictions under state-level regulations in the US and proposed EU perfluorinated substance limits, as these will reshape seal and bearing material specifications across the installed base.
Market Dynamics
Magnetic drive systems are compressing the addressable market for conventional packed-gland seals as EPA NESHAP and REACH compliance deadlines harden zero-emission requirements across chemical processing clusters.
Growth Catalysts
- REACH chemical registration mandates:European facilities face mandatory upgrades to sealed containment architectures, forcing replacement cycles for legacy agitator installations in polymerization and crystallization duties.
- Pharmaceutical capacity scaling:Active pharmaceutical ingredient manufacturers in India and China are procuring reactor-integrated agitation systems with validated cleanability protocols under FDA cGMP and CDSCO oversight.
- High-viscosity mixing demand:Specialty chemical producers in Germany and the United States are expanding procurement of heavy-duty top-entry configurations for multi-phase reaction vessels.
Market Restraints
- Stainless steel and exotic alloy input costs:Hastelloy and duplex stainless price volatility compresses margin pools for custom-engineered pharmaceutical systems relative to standardized water treatment units.
- Magnetic drive supplier concentration:Certified containment architecture production clusters in Switzerland and Germany create bottleneck risk for sealless system procurement timelines.
- PFAS material restrictions:Proposed EU perfluorinated substance limits and emerging US state-level regulations threaten seal and bearing material specifications across the installed base.
Strategic Opportunities
- India pharmaceutical manufacturing zones:Underpenetrated demand for cGMP-validated agitation systems exists in Andhra Pradesh and Gujarat bulk drug clusters seeking import substitution.
- Computational fluid dynamics integration:Convergence of physics simulation tools with additive manufacturing enables application-specific impeller geometries without tooling investment.
- Direct-to-plant technical sales:Embedded application engineering teams bypass distributor networks to anchor long-term service contracts alongside hardware placement.
Industry Challenges
- Computational fluid dynamics talent scarcity:Process simulation expertise for multi-phase mixing optimization remains concentrated among rotating equipment specialists with decade-long training curves.
- cGMP validation timelines:FDA and EMA surface finish documentation requirements extend pharmaceutical project commissioning cycles by twelve to eighteen months.
- Legacy DCS integration friction:Variable frequency drive retrofits for existing agitator motors face protocol incompatibility with proprietary distributed control systems in mature chemical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Agitators Market |
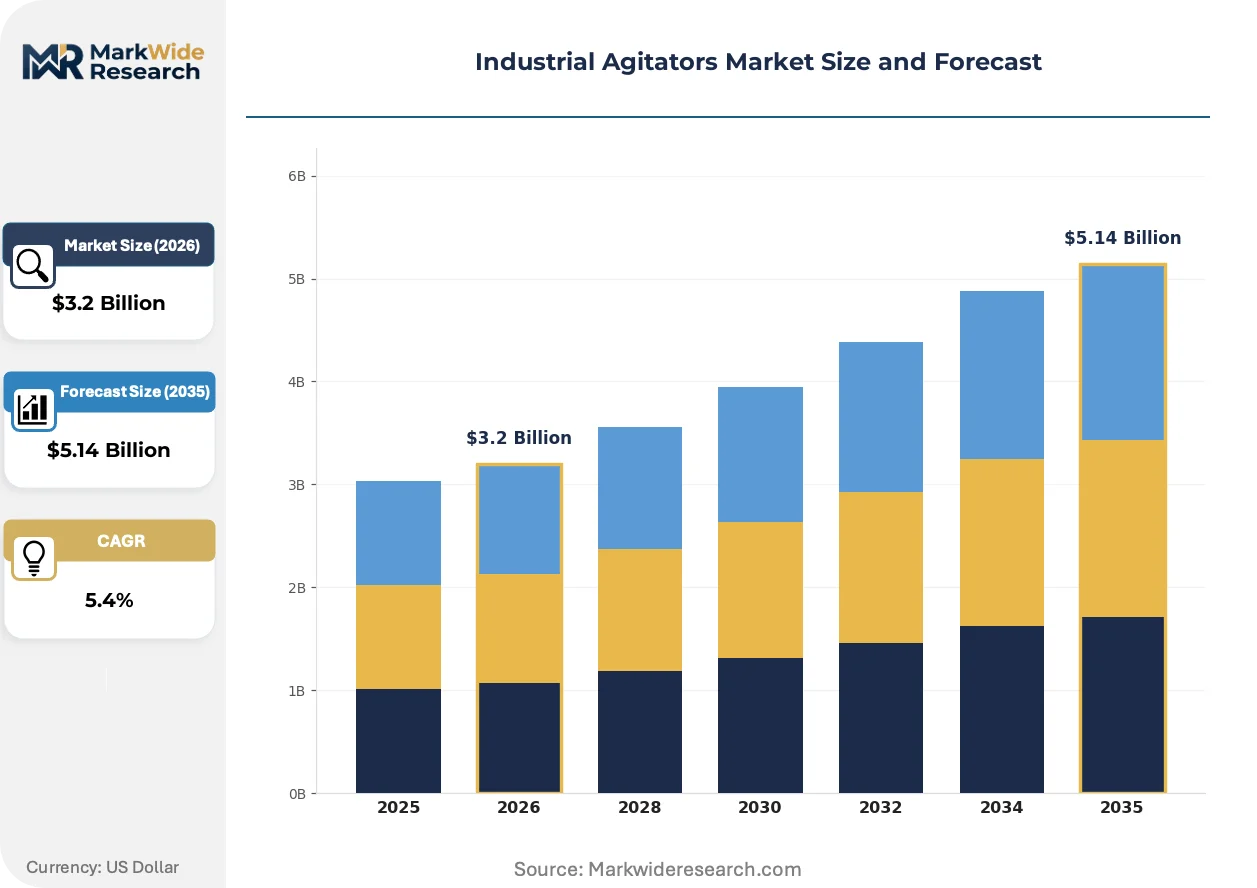
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Entry, Side Entry, Bottom Entry, Portable, Magnetic Drive Technology: Hydraulic, Pneumatic, Electric, Mechanical, Magnetic Application: Chemical Processing, Water Treatment, Food Processing, Paints & Coatings, Pharmaceuticals End User: Manufacturing Plants, Research Laboratories, Processing Facilities, Quality Control Units |
| Companies Covered | Sulzer Ltd., Dynamix Agitators Inc., SPX Flow, Inc., Philadelphia Mixing Solutions Ltd., Silverson Machines, Inc., Xylem Inc., NOV Inc., Charles Ross & Son Company, Ekato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Agitators Market Strategic Shifts & Innovations
Digital twin architectures and predictive maintenance algorithms are reconfiguring how processing facilities specify agitation equipment, shifting capital allocation from hardware margins to embedded software and service revenue streams.
Computational fluid dynamics simulation platforms are virtualizing the traditional impeller design process. Pharmaceutical and specialty chemical engineers now specify mixing performance through validated turbulence models before physical prototyping. This compression of design iteration cycles enables application-specific geometries at batch quantities previously uneconomical for custom fabrication.
EPA NESHAP standards for hazardous air pollutants are mandating sealless magnetic drive architectures in US chemical processing facilities. The regulatory pressure eliminates conventional packed-gland configurations from new procurement shortlists. Pharmaceutical manufacturers respond by consolidating supplier relationships with vendors holding certified containment test protocols.
After-sales service unbundling is fragmenting traditional equipment procurement bundles. Processing facilities now source predictive maintenance algorithms and spare part logistics separately from initial hardware placement. This pattern concentrates in North American chemical clusters where operating expenditure budgets dominate capital allocation decisions.
Industrial Agitators Market Segmentation
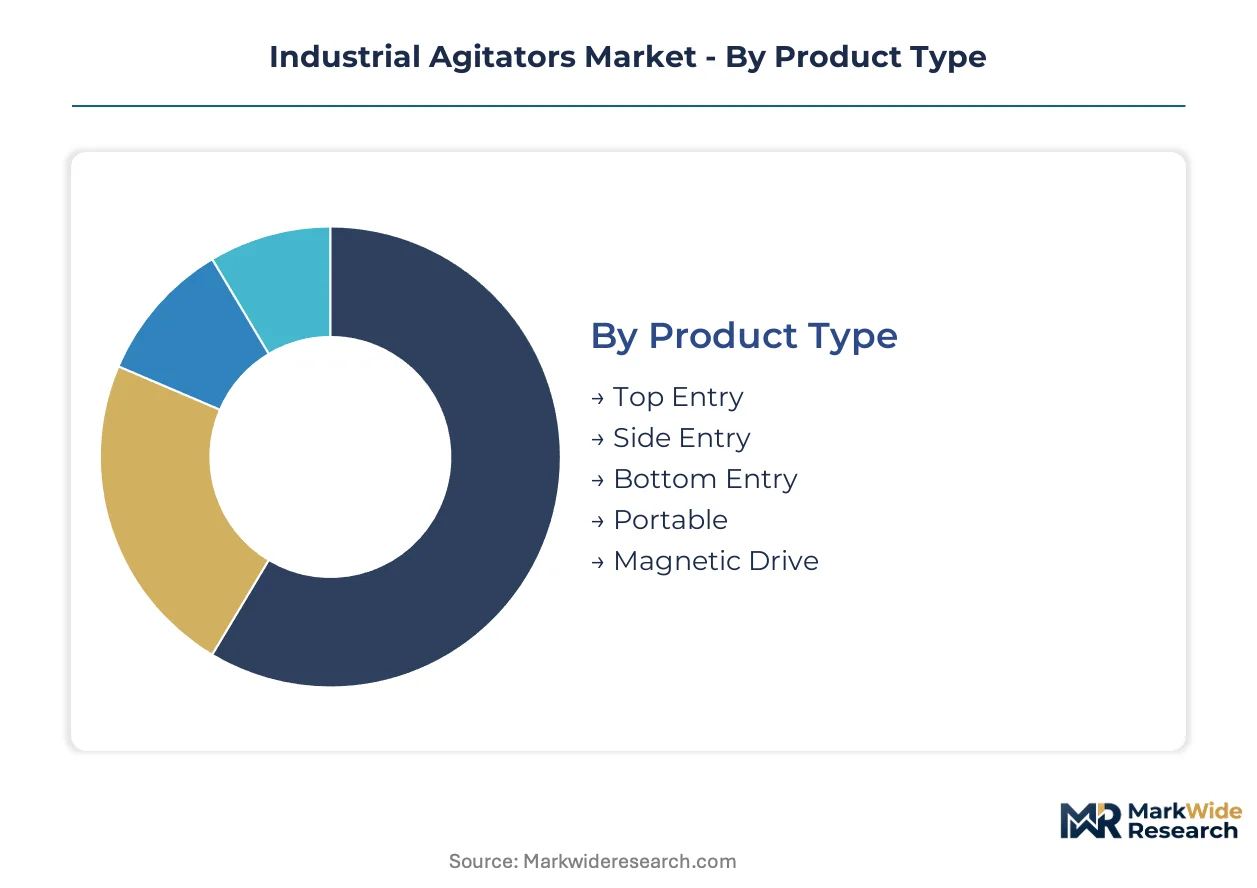
Agitator procurement patterns diverge sharply across installation geometry, power transmission method, and regulatory exposure. Segmentation reveals where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Mature configurations anchor heavy-duty chemical installations while emerging geometries penetrate specialized containment environments.
- Top Entry:Heavy-duty shaft-and-impeller assemblies dominate multi-phase reaction vessels in Germany and United States specialty chemical clusters. German producers favor these for high-viscosity polymerization duties where bearing longevity outweighs maintenance access constraints.
- Magnetic Drive:Sealless containment architectures eliminate packed-gland emissions. Pharmaceutical manufacturers in India and China consolidate procurement with vendors holding EPA NESHAP and REACH-certified test protocols under FDA cGMP and CDSCO oversight.
- Side Entry:Horizontal shaft configurations suit large storage tanks where top mounting proves structurally impractical.
- Bottom Entry:Submerged drive units serve crystallization vessels requiring minimal shaft deflection.
- Portable:Fractional horsepower units address batch-scale flexibility in contract manufacturing environments.
Top Entry handles the majority of throughput; Magnetic Drive is the fastest mover on share.
Technology:
Cost tiers separate commodity power transmission from precision-controlled process integration.
- Electric:Variable frequency drive compatibility enables precise RPM control for shear-sensitive pharmaceutical formulations. Indian API manufacturers specify these for validated cleanability protocols under CDSCO manufacturing directives.
- Magnetic:Coupled motor-to-impeller torque transfer eliminates mechanical seals entirely. REACH chemical registration mandates in European facilities force replacement cycles for legacy installations in polymerization and crystallization duties.
- Hydraulic:High-torque fluid power suits mining slurry applications where explosive atmosphere classification prohibits electrical equipment.
- Pneumatic:Compressed air drives serve hazardous zone classifications with intrinsic safety requirements.
- Mechanical:Direct-coupled gearboxes persist in mature water treatment infrastructure with stable replacement demand.
Electric motors command the largest installed base; Magnetic coupling technology is expanding most quickly in regulated process environments.
Application:
Customer type stratification separates specification-intensive engineered systems from catalog-standard replacement units.
- Chemical Processing:Multi-phase reaction vessels in Germany and United States demand heavy-duty top-entry configurations. EPA NESHAP hazardous air pollutant standards mandate sealless magnetic drive architectures for new procurement.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis requires surface finish documentation and cleanability validation. FDA cGMP and EMA manufacturing directives extend commissioning cycles by twelve to eighteen months.
- Water Treatment:Municipal and industrial clarification processes generate stable replacement demand with thinner margin pools compared to custom-engineered systems.
- Food Processing:Hygienic design standards under FDA and FSSAI jurisdiction constrain material selection and cleanability protocols.
- Paints & Coatings:High-shear dispersion duties favor specific impeller geometries for pigment suspension.
Chemical Processing absorbs the greatest equipment value; Pharmaceuticals is climbing the fastest as capacity scales in India and China.
End User:
Supply concentration clusters around processing facilities with integrated maintenance capabilities versus distributed laboratory environments.
- Processing Facilities:Continuous production environments in chemical and pharmaceutical sectors anchor long-term service contracts. Sulzer Ltd. and SPX Flow, Inc. embed application engineering teams at customer sites to bypass distributor networks.
- Manufacturing Plants:Discrete batch operations in specialty chemical and food sectors specify modular agitation systems for production flexibility.
- Research Laboratories:Pilot-scale units support process development before commercial scale-up.
- Quality Control Units:Small-volume mixing supports analytical sample preparation and stability testing.
Processing Facilities represent the dominant procurement channel; Research Laboratories are expanding most quickly as contract development organizations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors command premium pricing for high-viscosity agitation systems while Indian pharmaceutical manufacturers compete on volume procurement of cGMP-validated units. This asymmetry shapes capital allocation patterns across procurement clusters.
United States
Specialty chemical producers in Texas and Louisiana are expanding heavy-duty top-entry agitator procurement for multi-phase reaction vessels. EPA NESHAP hazardous air pollutant standards mandate sealless magnetic drive architectures for new installations. The Gulf Coast petrochemical corridor anchors replacement cycles for legacy packed-gland systems.
Germany
Polymerization and crystallization duty agitators face mandatory upgrades under REACH chemical registration mandates. ECHA compliance deadlines compress procurement timelines for sealed containment architectures. The Ruhr industrial basin and Bavarian chemical clusters concentrate demand for reactor-integrated systems.
India
Active pharmaceutical ingredient manufacturers in Andhra Pradesh and Gujarat are scaling cGMP-validated agitation capacity under CDSCO manufacturing directives. Import substitution policies favor domestic fabrication of surface-finish-documented systems. Hyderabad and Ahmedabad bulk drug clusters anchor the fastest procurement expansion.
China
Specialty chemical capacity scaling in Jiangsu and Zhejiang provinces drives demand for precision-controlled electric agitation systems. NMPA oversight of pharmaceutical manufacturing equipment constrains material selection protocols. The Yangtze River Delta chemical corridor concentrates magnetic drive adoption for zero-emission containment.
Switzerland
Certified containment architecture production clusters face bottleneck risk as global pharmaceutical manufacturers consolidate supplier relationships. Swissmedic manufacturing equipment standards validate surface finish specifications for API synthesis agitators. Basel-region precision engineering capabilities anchor premium-tier magnetic drive system supply.
Industrial Agitators Market Key Industry Players
Full-line rotating equipment specialists and application-focused agitation engineers split the market along service-integration versus technology-specialization lines. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with embedded service contracts, precision-focused specialists in reactor-integrated systems, and regional fabricators serving standardized replacement demand. Dominant competitive moves include backward integration into proprietary impeller metallurgy and geographic expansion through direct-to-plant technical sales teams.
Within the diversified conglomerate tier, Sulzer Ltd. and SPX Flow, Inc. anchor positions through rotating equipment portfolio breadth and vertical control over critical components. Ekato Group exemplifies the reactor-integrated specialization archetype with crystallization and polymerization system expertise. These three entities represent the primary competitive anchors against which procurement teams benchmark technical specifications and service contract structures.
| Leading Market Players |
|---|
| Sulzer Ltd. |
| Dynamix Agitators Inc. |
| SPX Flow, Inc. |
| Philadelphia Mixing Solutions Ltd. |
| Silverson Machines, Inc. |
| Xylem Inc. |
| NOV Inc. |
| Charles Ross & Son Company |
| Ekato Group |
| Others |
Cost & Logistics Intelligence
Basel-region precision engineering clusters anchor certified containment architecture production, concentrating premium-tier magnetic drive supply and amplifying pricing power for Swiss and German vendors serving pharmaceutical manufacturers under FDA cGMP and EMA directives.
Pricing Analysis
The customization-premium spread separates configured-to-order reactor-integrated systems from catalog-standard water treatment units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and surface finish documentation intensity. Cost compression in standard-grade electric motor configurations intensifies because Indian and Chinese fabricators scale domestic API manufacturing capacity. Water treatment municipalities exhibit highest price sensitivity; pharmaceutical bulk drug clusters under CDSCO oversight show lowest sensitivity due to validation timeline penalties.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for Hastelloy and duplex stainless alloy inputs. Certified containment architecture production draws from Switzerland, Germany, and select Austrian precision engineering clusters. Permanent magnet rare earth dependencies rest on Chinese processing concentration. Single-source vulnerability concentrates in Swissmedic-validated surface finish documentation capabilities. Distribution runs through direct-to-plant technical sales teams embedded at Texas and Louisiana petrochemical corridor facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as REACH chemical registration mandates and EPA NESHAP compliance deadlines force replacement cycles for legacy packed-gland installations across European and US chemical processing clusters.
For Market Incumbents: Harden certified containment test protocol portfolios against emerging PFAS material restriction threats under proposed EU perfluorinated substance limits. Deepen backward integration into proprietary impeller metallurgy to offset Hastelloy price volatility compressing margin pools for custom-engineered pharmaceutical systems. Anchor long-term service contracts through embedded application engineering teams at Andhra Pradesh and Gujarat bulk drug clusters. For New Entrants and Emerging Players: Pursue underpenetrated demand for cGMP-validated agitation systems in Indian pharmaceutical manufacturing zones seeking import substitution. Target crystallization and polymerization duty specialization where Ekato Group's reactor-integrated expertise has created white space for mid-tier challengers. Lead with computational fluid dynamics simulation capabilities to compress design iteration cycles for batch-quantity custom geometries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates rotating equipment portfolios where agitation systems represent non-core assets. Long-term viability favors vendors with captive magnetic drive technology and validated cleanability protocols under FDA and EMA manufacturing directives. Watch NMPA enforcement patterns in Jiangsu and Zhejiang provinces as inflection indicator for Chinese specialty chemical capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Impeller Metallurgy | SPX Flow's vertical control over critical components anchors margin defense against alloy price volatility. |
| Direct-to-Plant Technical Sales Expansion | Sulzer's embedded application engineering teams bypass distributor networks to capture service contract revenue. |
| Certified Containment Architecture Investment | Swiss and German vendors consolidate supplier relationships as EPA NESHAP eliminates packed-gland configurations. |
| Computational Fluid Dynamics Platform Integration | Additive manufacturing convergence enables application-specific geometries without tooling investment for batch quantities. |
| Long-term Service Agreement Structuring | After-sales unbundling in North American chemical clusters shifts capital allocation toward operating expenditure budgets. |
Research Approach
A standing panel of plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads provided ongoing calibration across the study period. Primary interviews with rotating equipment specialists at chemical processing and pharmaceutical manufacturing facilities combined with secondary validation from SEC 10-K filings, customs and trade data, and ACC and Cefic industry reports. Bottom-up equipment procurement tracking and top-down capacity installation estimates underwent iterative triangulation.
Scenario-bracketing around regulatory compliance timelines and raw material price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include agitator configuration geometry, power transmission technology, end-use application intensity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and capacity scaling announcements. Industry-specific forecast inputs incorporated REACH chemical registration mandate deadlines and CDSCO manufacturing directive enforcement patterns.
Macroeconomic conditions sit as an overlay; deviation in specialty alloy pricing and pharmaceutical capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and magnetic drive technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
India Crane Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Europe Construction Machinery Rental Market