
 BRICS Aerial Work Platforms Market | 2026-2036
BRICS Aerial Work Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
BRICS Aerial Work Platforms Market Analysis
Chinese aerial platform manufacturing is consolidating as domestic foundry capacity scales to serve BRICS infrastructure timelines. XCMG Group leverages integrated chassis production to anchor supply across Belt-and-Road-linked projects. Sany Group sustains R&D intensity in telescopic boom engineering, while Zhejiang Dingli Machinery Co Ltd differentiates through compact scissor lift specialization for Asian warehousing layouts.
Aerial work platforms are self-propelled or vehicle-mounted mechanical devices with extendable boom or scissor assemblies designed to elevate personnel, tools, and materials to elevated work zones, typically spanning vertical reaches from 8 meters to over 60 meters depending on configuration. Scissor lifts dominate fleet composition in BRICS warehousing and maintenance sectors due to stable platform geometry and rapid cycle times, while boom lifts command premium positioning in utilities and construction where horizontal outreach and up-and-over capability justify higher operating expenditure. Battery powered variants represent the fastest-growing power source segment as construction site emissions rules tighten across member states.
Brazil's ANVISA and China's SAMR enforce operator certification and equipment inspection protocols that shape product design requirements and aftermarket service obligations. India's BIS standards for mobile elevating work platforms, coupled with South Africa's occupational health and safety frameworks, create multi-jurisdictional compliance complexity for unified product portfolios. Stakeholders must monitor regulatory divergence on electrification mandates and local content thresholds when configuring regional manufacturing and distribution investments.
Market Dynamics
China's dual carbon goals and India's PLI scheme for manufacturing equipment are restructuring procurement standards across BRICS infrastructure projects, forcing fleet operators to accelerate electrification timelines while localizing supply chains.
Growth Catalysts
- Urban verticalization:China's eastern coastal provinces drive fleet renewal as high-rise construction density elevates demand for extended-reach boom configurations in megacity clusters.
- PLI scheme incentives:India's production-linked incentive framework for construction equipment manufacturing reduces import dependency and anchors domestic assembly capacity for regional export.
- Battery chemistry advances:Lithium-iron-phosphate cell cost reductions enable competitive total-cost-of-ownership positioning for electric scissor lifts against diesel equivalents in warehousing applications.
Market Restraints
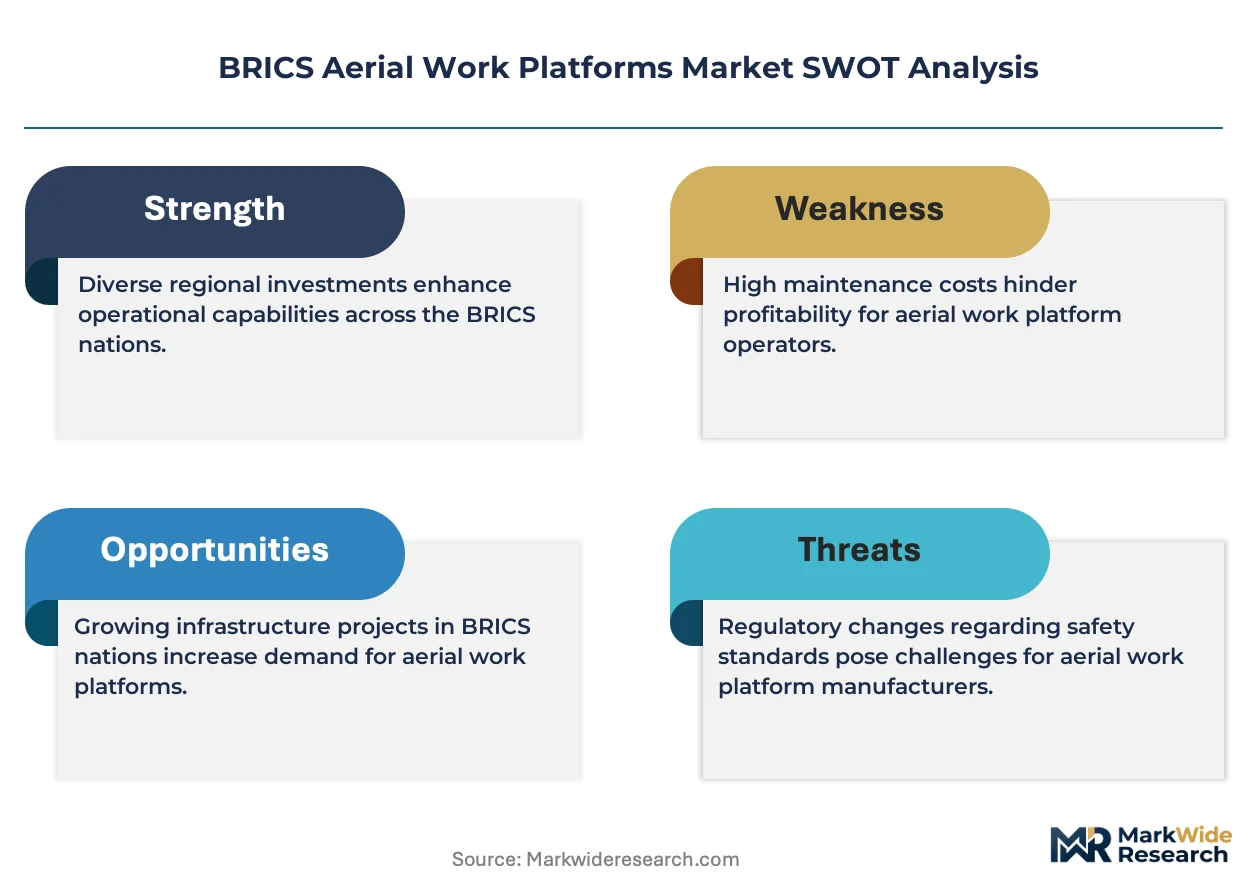
- Steel price volatility:Boom fabrication relies on high-strength alloy plate whose cost fluctuations compress margin visibility for fleet procurement cycles exceeding five years.
- Foundry concentration:Hydraulic component casting capacity clusters in China's Shandong and Jiangsu provinces, creating single-source vulnerability for Brazilian and South African distributors.
- Horizontal outreach limits:Electric boom architectures face payload-range tradeoffs that restrict deployment in utilities maintenance requiring 25-meter plus lateral extension.
Strategic Opportunities
- South African mining services:Underground shaft maintenance contracts remain underpenetrated by MEWP fleets, with rope-suspended platforms dominating vertical access.
- Russia Arctic infrastructure:Cold-climate battery thermal management creates first-mover advantage for manufacturers solving sub-zero duty cycles in LNG facility construction.
- Rental channel digitization:Telematics-integrated fleet management platforms enable usage-based billing models that compress customer switching costs.
Industry Challenges
- Multi-jurisdictional certification:Brazil's ANVISA operator mandates, China's SAMR inspection protocols, and India's BIS standards create parallel compliance tracks that fragment product development resources.
- Electrification skill gaps:High-voltage battery maintenance and thermal runaway response training lags fleet electrification rates across rental technician workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRICS Aerial Work Platforms Market |
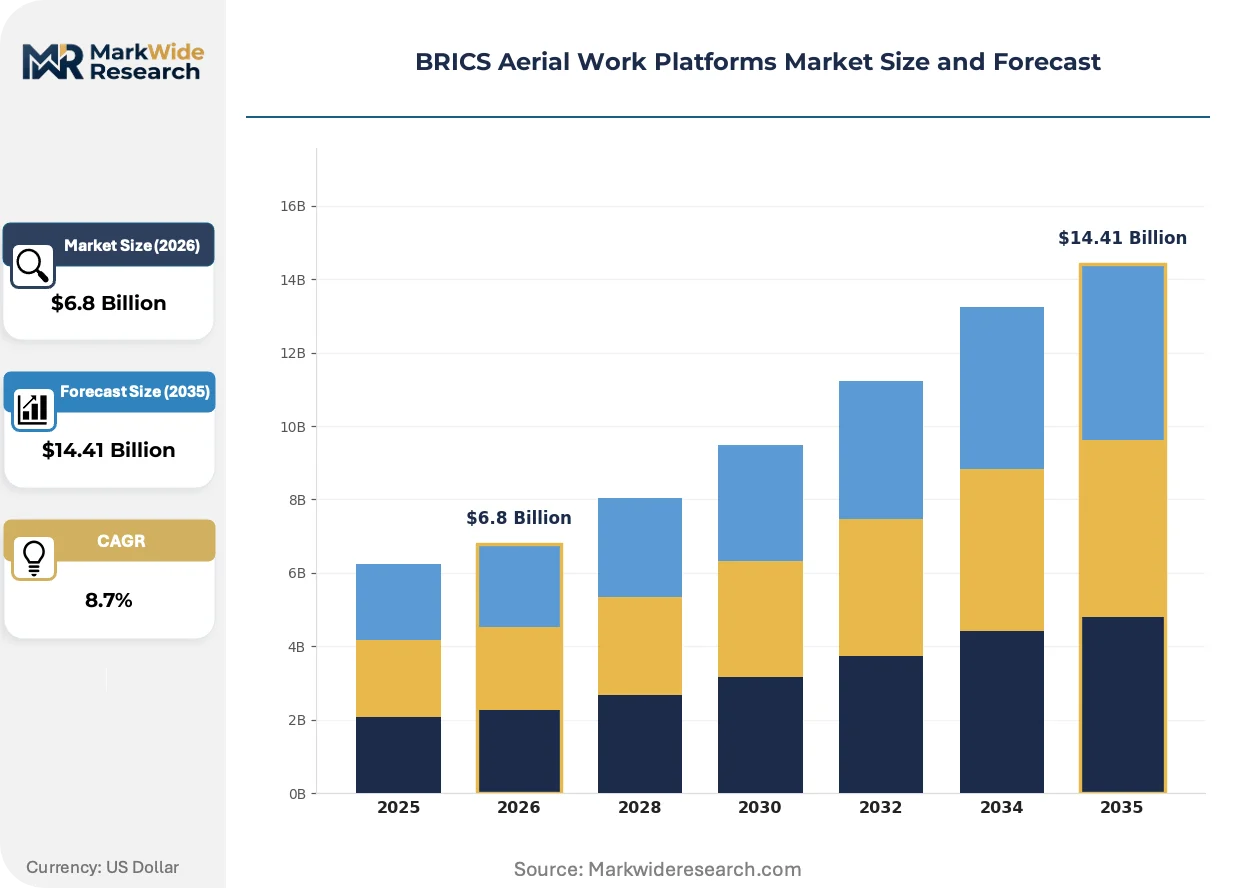
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Vertical Mast Lifts, Trailer Mounted Lifts End User: Construction, Utilities, Maintenance, Warehousing Power Source: Battery Powered, Diesel Powered, Electric Powered, Hybrid Powered Drive Type: Two-Wheel Drive, Four-Wheel Drive, Track Drive, Manual Drive |
| Companies Covered | Terex Corporation, Haulotte Group, MEC Aerial Work Platforms, Tadano Ltd., Aichi Corporation, Sany Group, XCMG Group, Zhejiang Dingli Machinery Co Ltd, Hunan Sinoboom Intelligent Equipment Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRICS Aerial Work Platforms Market Emerging Trajectories
Telematics integration and lithium-ion powertrains are converging to redefine fleet utilization models, while regulatory pressure on construction site emissions accelerates product architecture decisions across BRICS member states.
Lithium-iron-phosphate battery systems are converging with IoT-enabled predictive maintenance platforms to enable remote state-of-health monitoring. Rental fleet operators in China's Pearl River Delta deploy these configurations to minimize unplanned downtime in 24-hour warehousing operations. This convergence is compressing service interval spacing and shifting aftermarket revenue from reactive repair to subscription diagnostics.
China's dual carbon goals mandate construction equipment electrification timelines that exceed current battery energy density trajectories. SAMR emission standards for non-road mobile machinery tighten particulate limits in urban zones, forcing manufacturers to prioritize electric architectures for domestic certification. The scissor lift segment faces the steepest compliance gradient as municipal procurement rules in Shanghai and Shenzhen exclude diesel units from public project tenders.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale Brazilian construction firms facing working capital constraints. Rental aggregators capture volume through bundled maintenance and certification packages that internal fleet management cannot replicate. This shift concentrates most visibly in São Paulo's commercial high-rise sector where project duration uncertainty favors operational expense treatment over asset ownership.
BRICS Aerial Work Platforms Market Segmentation
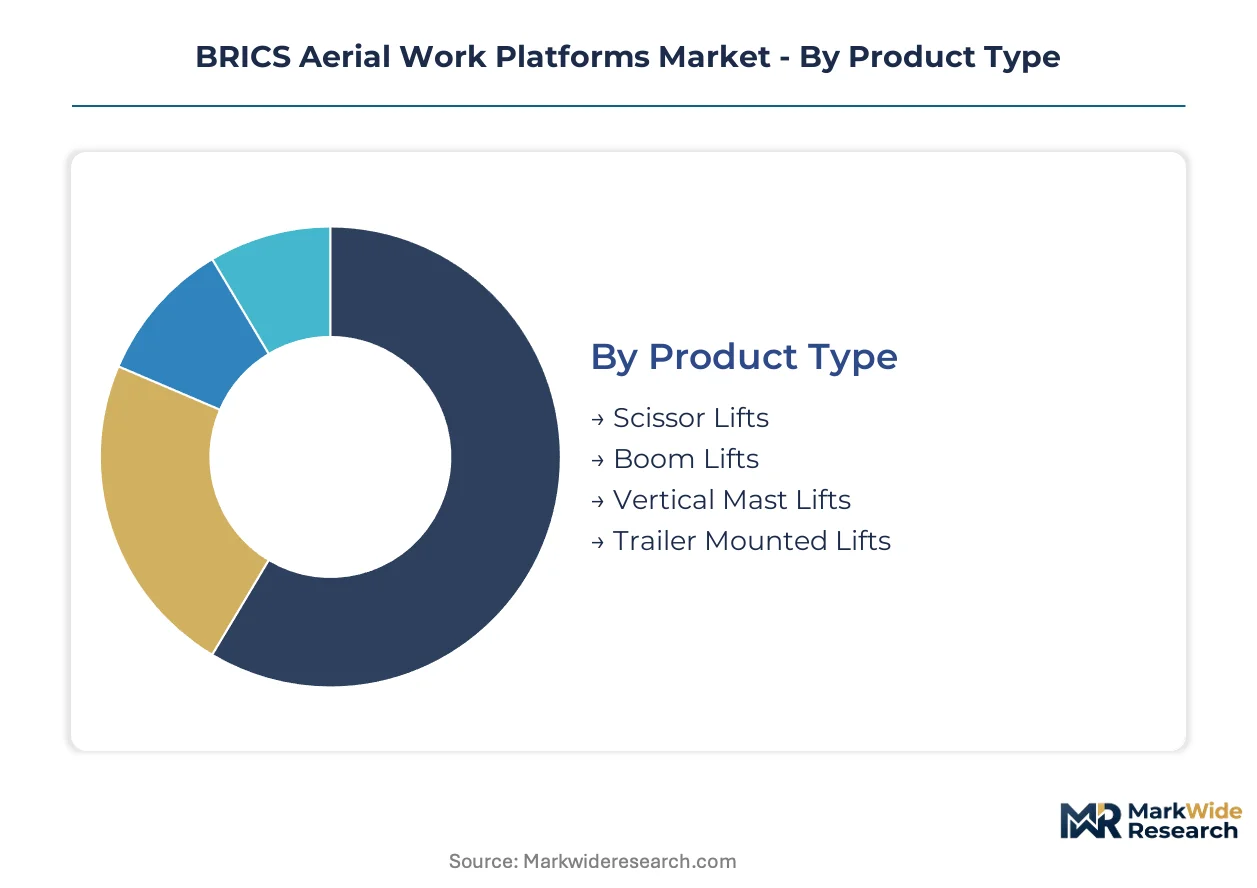
Segmentation in BRICS aerial work platforms reveals how procurement patterns diverge across infrastructure maturity levels and regulatory environments. Fleet composition varies sharply between China's electrified warehousing corridors and Brazil's diesel-dependent commercial construction sites.
Product Type:
Foundry capacity for hydraulic cylinders and boom assemblies clusters in China's eastern manufacturing belts, anchoring supply availability for platform variants.
- Scissor Lifts:These platforms deploy crisscrossing linked supports that extend vertically while maintaining rigid horizontal stability. Demand concentrates in India's warehousing zones around Mumbai and Delhi where rapid vertical storage retrieval justifies rapid cycle times. The PLI scheme's domestic assembly incentives reduce landed cost disadvantages against Chinese imports.
- Boom Lifts:Articulated or telescopic arm configurations deliver horizontal outreach and up-and-over capability for utility maintenance and high-rise construction. China's coastal megacity clusters drive fleet renewal as building height regulations relax in Shenzhen and Guangzhou. Diesel variants retain dominance where electrification infrastructure remains sparse.
- Vertical Mast Lifts:Single-mast push-around units serve narrow-aisle maintenance in retail and institutional facilities.
- Trailer Mounted Lifts:Towable configurations address intermittent access needs in municipal services and event infrastructure across South African urban centers.
Today's leader: Scissor Lifts. Tomorrow's challenger: Boom Lifts.
End User:
Application intensity varies by sector, with construction absorbing the highest platform hours per project and utilities demanding specialized outreach specifications.
- Construction:Commercial high-rise and infrastructure projects deploy mixed fleets across boom and scissor configurations. Brazil's São Paulo corridor concentrates demand as ANVISA certification requirements shape rental fleet specifications. Working capital constraints among mid-scale contractors accelerate equipment-as-a-service adoption.
- Utilities:Power transmission and telecommunications maintenance require extended horizontal reach and insulated platform options. Russia's LNG facility construction in Arctic zones creates demand for cold-climate battery thermal management solutions that domestic manufacturers have yet to perfect.
- Maintenance:Facility management contracts favor compact scissor and vertical mast units for scheduled building upkeep.
- Warehousing:E-commerce fulfillment centers in China's Pearl River Delta drive 24-hour utilization patterns that stress battery duty cycles.
Construction commands current procurement volume. Warehousing posts the steepest expansion trajectory as logistics automation accelerates across BRICS member states.
Power Source:
Procurement standards are restructuring around emission mandates, with municipal tender rules increasingly excluding combustion alternatives from urban project eligibility.
- Battery Powered:Lithium-iron-phosphate cell configurations now achieve competitive total-cost-of-ownership against diesel equivalents in indoor warehousing applications. SAMR emission standards for non-road mobile machinery tighten particulate limits in Shanghai and Shenzhen, forcing fleet operators to accelerate electrification timelines.
- Electric Powered:Grid-tethered or battery-electric architectures with standardized charging interfaces dominate new fleet specifications in China's eastern provinces.
- Diesel Powered:Compression-ignition engines retain position in outdoor construction and remote infrastructure where refueling infrastructure outweighs emission compliance costs.
- Hybrid Powered:Dual-mode systems combining battery electric with range-extending combustion address payload-range tradeoffs that restrict pure electric deployment in heavy-lift utility applications.
Battery Powered variants are gaining share fastest. Diesel Powered retains installed base dominance but faces accelerating replacement pressure.
Drive Type:
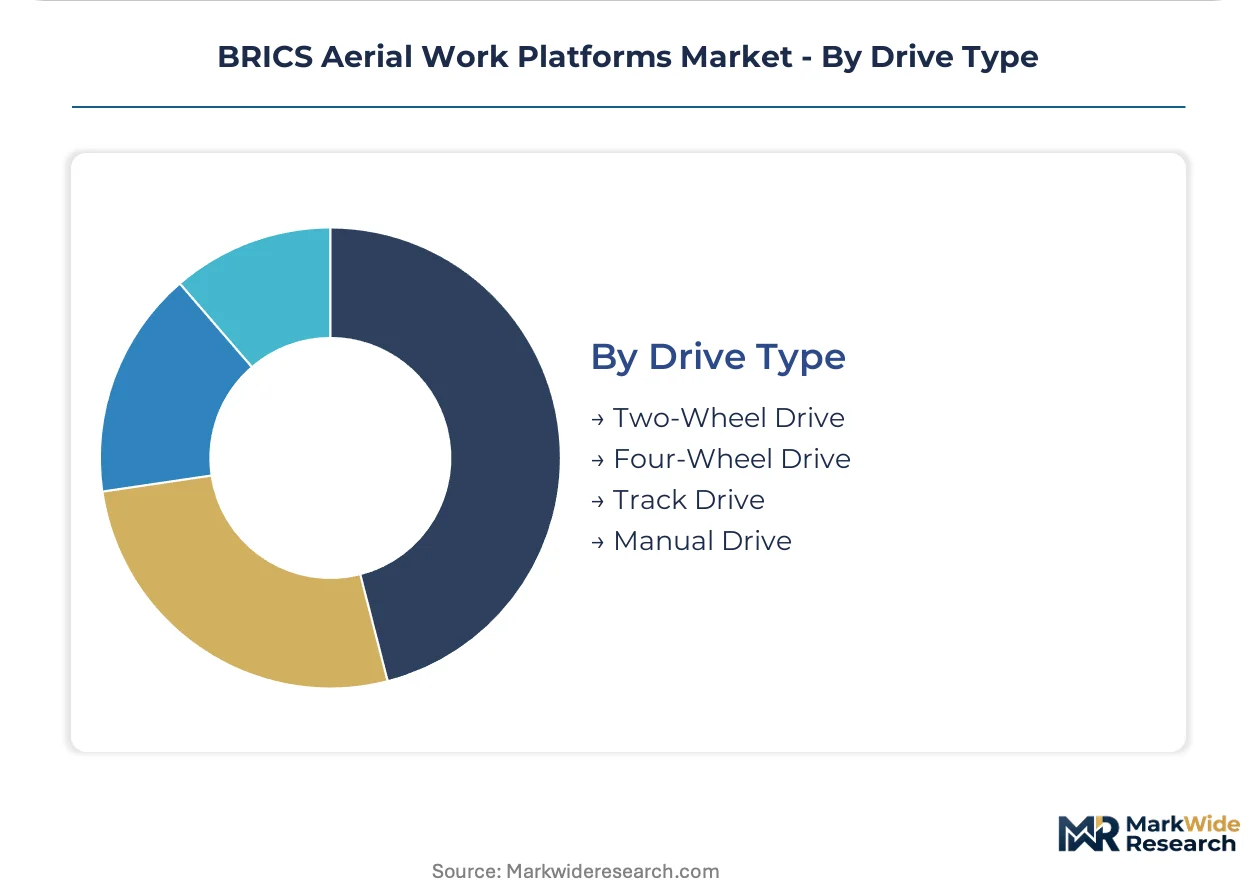
Chassis configuration determines terrain accessibility and transport economics, with differential specifications across BRICS geographies reflecting surface conditions and road infrastructure quality.
- Four-Wheel Drive:All-terrain traction systems with oscillating axles serve unpaved construction sites and mining support operations. South African mining services contracts remain underpenetrated by MEWP fleets, with rope-suspended platforms still dominating underground shaft maintenance.
- Two-Wheel Drive:Simplified drivetrains reduce acquisition cost and maintenance burden for warehouse and paved-yard applications.
- Track Drive:Continuous track configurations distribute ground pressure for soft or sensitive surfaces in landscaping and utility right-of-way maintenance.
- Manual Drive:Push-around or towable units eliminate drivetrain complexity for intermittent low-height access needs.
Four-Wheel Drive anchors outdoor construction demand. Track Drive addresses niche terrain constraints with limited volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal provinces command fleet renewal velocity that outpaces Brazilian commercial construction by a factor of three, while India's warehousing corridors generate scissor lift procurement intensity unmatched elsewhere in the bloc.
China
Urban verticalization in Shenzhen and Guangzhou drives demand for extended-reach boom configurations as building height regulations relax. SAMR emission standards for non-road mobile machinery tighten particulate limits in Shanghai, forcing municipal procurement rules to exclude diesel units from public tenders. The Yangtze River Delta manufacturing belt anchors foundry capacity for hydraulic cylinders serving Belt-and-Road-linked projects.
India
E-commerce fulfillment centers around Mumbai and Delhi generate 24-hour utilization patterns for compact scissor lifts in rapid vertical storage retrieval. The PLI scheme for construction equipment manufacturing reduces landed cost disadvantages against Chinese imports while anchoring domestic assembly capacity. The Delhi-Mumbai Industrial Corridor concentrates warehousing automation investments that stress battery duty cycles.
Brazil
Commercial high-rise construction in São Paulo concentrates mixed fleet deployment across boom and scissor configurations as ANVISA certification requirements shape rental specifications. Working capital constraints among mid-scale contractors accelerate equipment-as-a-service adoption over capital purchase. The southeastern industrial belt remains diesel-dependent where electrification infrastructure remains sparse.
Russia
LNG facility construction in Arctic zones creates demand for cold-climate battery thermal management solutions that domestic manufacturers have yet to perfect. Sub-zero duty cycles in Yamal and Gydan peninsula projects test electric architecture limits. The northwestern extraction corridor remains tethered to combustion powertrains where range-extending capability outweighs emission compliance costs.
South Africa
Underground shaft maintenance contracts in platinum and gold mining remain underpenetrated by MEWP fleets, with rope-suspended platforms dominating vertical access. Occupational health and safety frameworks create compliance complexity for unified product portfolios against BRICS counterparts. The Gauteng mining services corridor presents conversion opportunity as mechanized access displaces legacy suspended systems.
BRICS Aerial Work Platforms Market Vendor Landscape
Chinese producers anchor one tier; European and Japanese specialists hold premium positioning through certification density and aftermarket service networks. The vendor base stratifies across three tiers: integrated chassis manufacturers with captive foundry capacity, boom engineering specialists sustaining R&D intensity, and compact equipment fabricators targeting Asian warehousing layouts. Dominant competitive moves include capacity expansion in Shandong and Jiangsu provinces and strategic partnerships linking telematics platforms to rental channel digitization.
Within the integrated chassis tier, XCMG Group and Sany Group exemplify backward integration into foundry operations that compress procurement lead times for Belt-and-Road deployments. Zhejiang Dingli Machinery Co Ltd occupies a position among compact scissor specialists addressing narrow-aisle warehousing configurations. Terex Corporation and Haulotte Group sit within the premium-certification segment where multi-jurisdictional compliance documentation commands price premiums. Hunan Sinoboom Intelligent Equipment Co. Ltd. represents the scale-driven archetype consolidating domestic volume before regional export expansion.
| Leading Market Players |
|---|
| Terex Corporation |
| Haulotte Group |
| MEC Aerial Work Platforms |
| Tadano Ltd. |
| Aichi Corporation |
| Sany Group |
| XCMG Group |
| Zhejiang Dingli Machinery Co Ltd |
| Hunan Sinoboom Intelligent Equipment Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive foundry operations in China's Shandong and Jiangsu provinces anchor both supply security and pricing power for integrated chassis manufacturers serving Belt-and-Road deployments. This backward integration into hydraulic cylinder casting compresses procurement lead times while insulating tier-one producers from alloy plate cost volatility that squeezes margin visibility for distributors in Brazil and South Africa.
Pricing Analysis
Capacity additions in China's eastern manufacturing belts are reshaping price floors for scissor lift configurations as domestic foundry scale economies diffuse through export pricing. Three-tier pricing structure across premium CE-certified, standard BIS-compliant, and economy non-certified tiers separates fleet operators by certification burden and after-sales bundling intensity. Cost compression in the economy tier is intensifying because Brazilian rental aggregators consolidate procurement volume through bundled maintenance contracts. Mid-scale contractors in São Paulo's commercial high-rise sector exhibit highest price sensitivity, while Arctic LNG developers in Russia's Yamal peninsula demonstrate lowest sensitivity due to cold-climate specification premiums.
Supply Chain Analysis
Skilled technician availability in Jiangsu and Shandong provinces feeds from vocational training pipelines aligned with provincial manufacturing targets. Geographic supply concentration centers on China for foundry capacity, South Korea for precision hydraulic valves, and Germany for high-pressure hose assemblies. Raw material dependencies rest on high-strength alloy steel plate, lithium-iron-phosphate battery cells, and specialized hydraulic seals. Single-source vulnerability clusters in Chinese hydraulic component casting create disruption risk for Brazilian and South African distributors. Distribution runs through rental channel aggregators in São Paulo, direct OEM supply in China's Pearl River Delta, and mining services contractors in South Africa's Gauteng corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where municipal tender rules in Shanghai and Shenzhen exclude uncertified units, forcing fleet operators toward premium electrified specifications with embedded telematics.
For Market Incumbents: Anticipate margin compression in diesel-dependent configurations as SAMR emission standards tighten particulate limits for non-road mobile machinery in urban zones. Consolidate position through captive foundry capacity expansion in Shandong province to compress procurement lead times for Belt-and-Road-linked projects. Deepen backward integration into lithium-iron-phosphate battery pack assembly to capture electrification value migration from combustion architectures. For New Entrants and Emerging Players: Underground shaft maintenance contractors in South Africa's platinum and gold mining corridors present the most penetrable buyer archetype, with rope-suspended platforms still dominating vertical access in underpenetrated mechanization zones. Target cold-climate battery thermal management solutions for Russia's Arctic LNG construction as domestic manufacturers have yet to perfect sub-zero duty cycles. Enter through equipment-as-a-service contracting models that bundle certification compliance and predictive maintenance subscriptions to displace capital purchase barriers among working capital-constrained mid-scale Brazilian contractors. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet operators because telematics-integrated platforms enable usage-based billing models that compress customer switching costs and generate recurring revenue visibility. Long-term viability hinges on electrification transition completion across BRICS municipal procurement rules. Target acquisition archetype: mid-scale Brazilian rental aggregators with ANVISA certification density and established maintenance infrastructure in São Paulo's southeastern industrial belt. Signal to watch: battery chemistry cost curves crossing diesel total-cost-of-equivalence thresholds in heavy-lift utility applications requiring 25-meter plus lateral extension.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables usage-based billing models that compress switching costs for rental fleet operators in China's Pearl River Delta. |
| Foundry Capacity Expansion | Captive hydraulic cylinder casting in Shandong province secures supply for Belt-and-Road-linked infrastructure timelines. |
| Cold-Climate Battery Development | Thermal management solutions for sub-zero duty cycles unlock Russia's Yamal and Gydan peninsula LNG construction demand. |
| PLI Scheme Localization | Domestic assembly incentives under India's production-linked framework reduce landed cost disadvantages against Chinese imports. |
| Rental Channel Digitization | Predictive maintenance subscriptions shift aftermarket revenue from reactive repair to recurring diagnostics in 24-hour warehousing operations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with fleet managers at rental aggregators in São Paulo, maintenance directors at Chinese warehousing operators in the Pearl River Delta, procurement leads at Brazilian commercial construction firms, and aftermarket service heads at Indian domestic assemblers. Secondary validation drew from SAMR emission standard filings, ANVISA operator certification databases, BIS mobile elevating work platform standards, customs trade data for hydraulic component flows, and SEC disclosures from listed equipment manufacturers. Bottom-up fleet deployment estimates triangulated against top-down infrastructure investment projections across BRICS member states.
Segment-weighting approaches modeled product type splits between scissor, boom, vertical mast, and trailer-mounted configurations alongside power source trajectories across battery, electric, diesel, and hybrid architectures. End-use segmentation captured construction, utilities, maintenance, and warehousing intensity patterns. Drive type differentiation across four-wheel, two-wheel, track, and manual configurations anchored terrain accessibility modeling. CAGRs were derived from installed base replacement cycles, electrification mandate timelines, and infrastructure project pipelines across the analysis window. Industry-specific forecast inputs included battery chemistry cost curves, alloy steel price volatility indices, and municipal tender rule adoption rates.
Underlying measurement precision varies by segment; battery-powered scissor lift deployment in China's eastern coastal provinces carries tighter precision than Arctic LNG construction demand in Russia due to project concentration and visibility. Forecasts reflect assumptions on electrification infrastructure buildout rates, PLI scheme disbursement continuity, and SAMR emission standard enforcement intensity across municipal procurement jurisdictions. Material deviation in steel price volatility, battery thermal management breakthrough timelines, or ANVISA certification processing delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Rotary Dryers Market