
 Vertical Grinding Mills Market | 2026-2036
Vertical Grinding Mills Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Grinding Mills Market Analytics
Specialty cement and slag processors are collapsing their historical preference for ball mills in favor of vertical roller configurations that cut specific energy use. Loesche GmbH leverages its modular grinding system architecture to anchor large-scale clinker replacement projects across European cement corridors. Gebr. Pfeiffer SE sustains competitive position through deep specialization in multi-drive vertical mill designs for high-finish-capacity installations. FLSmidth & Co. A/S competes on integrated plant automation, combining mill controls with pyroprocess optimization to reduce operator labor intensity.
A vertical grinding mill employs a rotating table and conical or cylindrical rollers to crush, grind, or pulverize feed material under controlled pressure, with typical table diameters spanning two to six meters and drive ratings reaching ten megawatts for cement raw meal circuits. The design prioritizes drying, grinding, and classification within a single compact footprint, eliminating separate drying equipment for moist feeds like blast furnace slag or wet limestone. Mineral grinders lead product type revenue due to sustained copper and gold ore throughput expansion in South American and Central Asian concentrators. Stationary installations dominate the installation category, though semi-stationary configurations are gaining traction in remote mining districts where modular relocation offsets infrastructure capital. Cryogenic grinding technology posts the fastest technology growth, driven by polymer and rubber recycling lines requiring embrittlement to achieve fine particle sizes without thermal degradation.
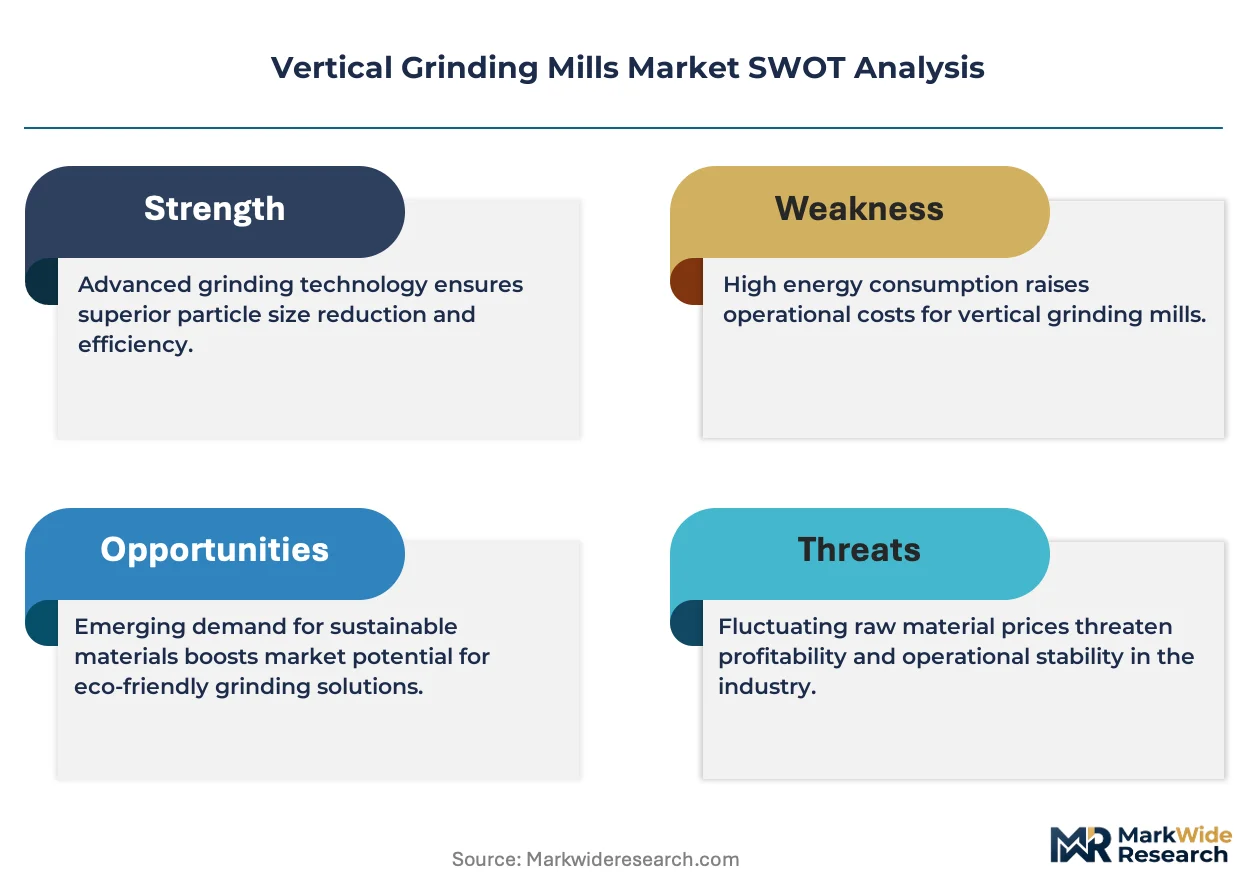
EPA emissions standards for Portland cement manufacturing and MEE air quality enforcement in China's Yangtze River Economic Belt are reshaping capital allocation toward vertical mill retrofits that reduce kiln exhaust volumes and enable waste heat recovery. CE marking under the EU Machinery Directive and China's GB standard alignment for mining equipment safety further condition market access and product liability exposure. Stakeholders must monitor how evolving carbon border adjustments and Scope 3 disclosure requirements redirect procurement criteria toward verifiable energy efficiency metrics rather than upfront capital cost alone.
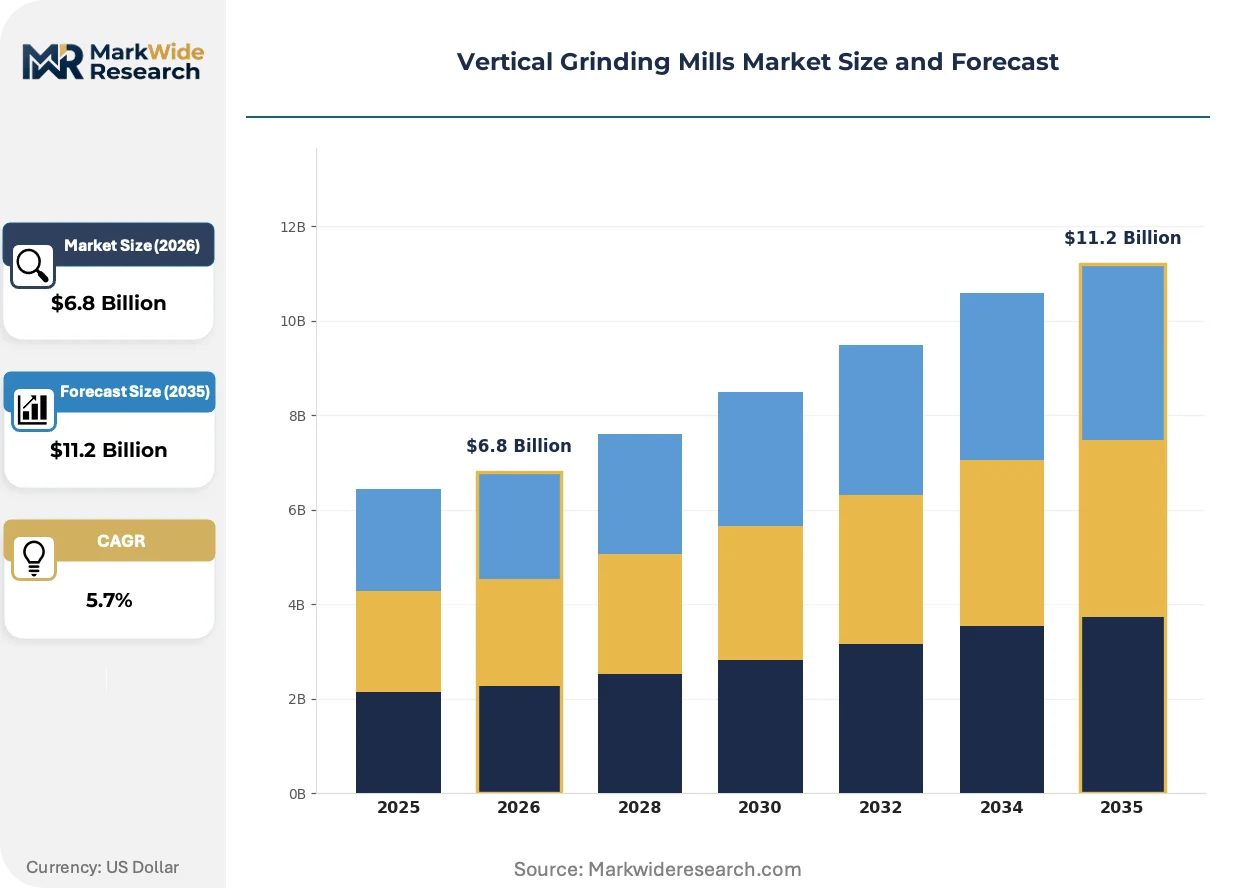
Market Dynamics
EPA emissions standards for Portland cement manufacturing and MEE air quality enforcement in China's Yangtze River Economic Belt are forcing capital reallocation toward vertical mill retrofits that reduce kiln exhaust volumes and enable waste heat recovery systems.
Growth Catalysts
- Clinker replacement mandates:European cement corridors face binding carbon reduction targets under EU Green Deal frameworks, accelerating procurement of vertical roller mills for slag and pozzolan grinding to lower process emissions.
- MEE enforcement intensity:China's Ministry of Ecology and Environment is tightening particulate discharge limits across the Yangtze River Economic Belt, compelling integrated kiln-grinding line upgrades from legacy ball mill circuits.
- Copper-gold concentrator expansion:Mineral grinders command sustained throughput investment across South American and Central Asian mining districts where ore hardness favors vertical roller configurations over SAG mill alternatives.
Market Restraints
- High-alloy roller wear component costs:Chromium-molybdenum grinding table segments face volatile alloy pricing, compressing maintenance margin predictability for high-duty slag processing installations.
- Specialized fabrication concentration:Precision-machined mill housings and multi-drive gearboxes concentrate among German and Japanese capital equipment suppliers, exposing procurement timelines to single-source bottlenecks.
- Ball mill residual installed base:Existing ball mill circuits with unamortized capital investment create substitution friction against vertical roller retrofits despite superior energy efficiency metrics.
Strategic Opportunities
- Modular semi-stationary configurations:Remote mining districts in Kazakhstan and Mongolia favor containerized vertical mill skids that enable relocation between ore bodies without permanent infrastructure commitment.
- Cryogenic grinding convergence:Polymer and rubber recycling lines are integrating cryogenic embrittlement systems with vertical mill classification to achieve fine particle sizes without thermal degradation of elastomer feedstocks.
- India PLI scheme alignment:Domestic cement equipment manufacturing incentives under India's Production Linked Incentive scheme create localized supply chain advantages for vertical mill module fabrication serving South Asian markets.
Industry Challenges
- Millwright and pyroprocess technician scarcity:Integrated vertical mill-kiln optimization requires cross-functional expertise in grinding dynamics and thermal systems that outpaces vocational training pipeline output in mature industrial economies.
- Legacy DCS integration complexity:Brownfield vertical mill retrofits must interface with existing distributed control system architectures from disparate vintages, extending commissioning timelines and operator retraining burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Grinding Mills Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Grinders, Mineral Grinders, Asphalt Grinders, Metal Grinders End User: Construction, Mining, Manufacturing, Recycling Installation: Stationary, Portable, Semi-Stationary, Mobile Technology: Diamond Grinding, Chemical Grinding, Mechanical Grinding, Cryogenic Grinding |
| Companies Covered | Loesche GmbH, Gebr. Pfeiffer SE, FLSmidth & Co. A/S, Thyssenkrupp AG, Metso Outotec, Ube Machinery Corporation, Sinoma International Engineering Co. Ltd., CITIC Heavy Industries Co. Ltd., CHAENG (Xinxiang Great Wall Machinery Corporation), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Grinding Mills Market Evolving Landscape
Digital twin deployment and predictive maintenance algorithms are compressing unplanned downtime in high-throughput grinding circuits, while cryogenic and hybrid drive architectures open application frontiers beyond traditional mineral processing.
Multi-drive vertical mill technology is fragmenting historical single-motor power limitations. High-finish-capacity installations in European cement corridors now deploy segmented drive trains that distribute torque across four to six motor modules. This architecture enables table diameters beyond six meters without gearbox scaling penalties. Clinker replacement projects at slag-intensive plants are adopting these configurations to maintain specific energy targets despite rising feed moisture variability.
REACH chemical registration requirements and F-Gas Regulation phase-down schedules are reshaping lubricant and hydraulic system specifications for European vertical mill installations. Synthetic ester-based roller bearing lubricants are displacing mineral oil formulations to eliminate polycyclic aromatic hydrocarbon exposure risks. Cement producers in Germany and Poland face accelerated compliance timelines that favor equipment suppliers with pre-certified component packages.
Service unbundling is separating mill operation from maintenance liability. Mining operators in Chile and Peru now contract grinding circuit availability rather than capital ownership, transferring roller wear monitoring and table regrinding obligations to OEM service arms. This consumption-pattern shift concentrates procurement influence among site general managers rather than centralized engineering functions, compressing vendor qualification cycles and elevating local spare parts inventory requirements.
Vertical Grinding Mills Market Segmentation
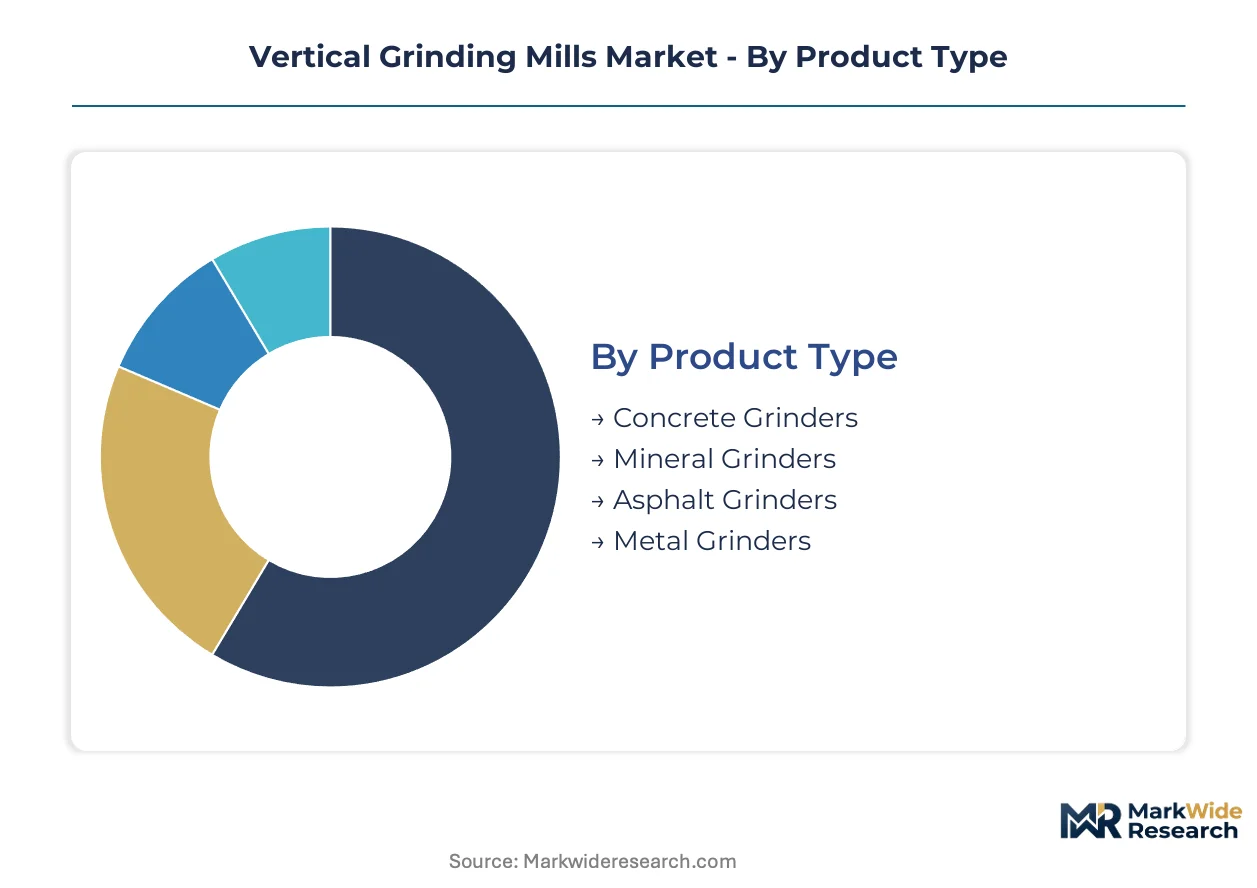
Vertical grinding mill procurement varies sharply by material hardness, regulatory exposure, and mobility requirements. Equipment specifications diverge across cement slag processing, copper ore concentration, and polymer recycling lines, each imposing distinct table diameter, drive rating, and classification constraints.
Product Type:
EPA Portland cement standards and MEE Yangtze River Belt enforcement create divergent compliance burdens across grinder categories, reshaping capital allocation toward configurations that reduce kiln exhaust volumes.
- Mineral Grinders:Engineered for copper and gold ore pulverization with table diameters spanning four to six meters and drive ratings reaching ten megawatts. Demand concentrates in Chilean and Kazakh copper concentrators where ore hardness favors vertical roller configurations over semi-autogenous mill alternatives, constrained by high-alloy roller wear component volatility.
- Concrete Grinders:Deployed for clinker and slag processing in integrated cement kiln-grinding lines, prioritizing drying-grinding-classification within single compact footprints. Procurement clusters in Germany and Poland under accelerated REACH lubricant compliance timelines, with slag moisture variability driving multi-drive architecture adoption.
- Asphalt Grinders:Specialized for reclaimed asphalt pavement processing with thermal integration requirements.
- Metal Grinders:Configured for ferrous and non-ferrous scrap size reduction with magnetic separation compatibility.
Established volume favors Mineral Grinders; emerging adoption favors Concrete Grinders.
End User:
Customer procurement authority is fragmenting across engineering, operations, and site management functions, with service unbundling transferring maintenance liability to OEM service arms.
- Mining:Copper-gold concentrator operators in South American and Central Asian districts contract grinding circuit availability rather than capital ownership. Chilean and Peruvian sites now transfer roller wear monitoring obligations to OEM service arms, elevating local spare parts inventory requirements.
- Construction:Cement producers face binding EU Green Deal carbon reduction targets accelerating slag and pozzolan grinding procurement. European cement corridors are collapsing historical ball mill preference in favor of vertical roller configurations that cut specific energy use.
- Manufacturing:Precision component finishing and surface preparation operations.
- Recycling:Polymer and rubber lines integrating cryogenic embrittlement with vertical mill classification.
Contracting authority concentrates in Mining; sustainability compliance pressures concentrate in Construction.
Installation:
Mobility requirements track infrastructure permanence and ore body depletion timelines, with modular configurations gaining traction in remote districts lacking permanent power or transport links.
- Stationary:Permanent foundations for high-throughput cement raw meal and slag circuits with uninterruptible power supply integration. Dominates European kiln-grinding line modernization where waste heat recovery system coupling requires fixed infrastructure.
- Semi-Stationary:Containerized skids enabling relocation between ore bodies without permanent infrastructure commitment. Kazakhstan and Mongolian mining districts favor these configurations to offset capital exposure in remote copper districts with uncertain reserve longevity.
- Portable:Trailer-mounted units for short-duration construction or maintenance grinding.
- Mobile:Self-propelled configurations for quarry face or demolition site operations.
Capital efficiency favors Stationary; operational flexibility favors Semi-Stationary.
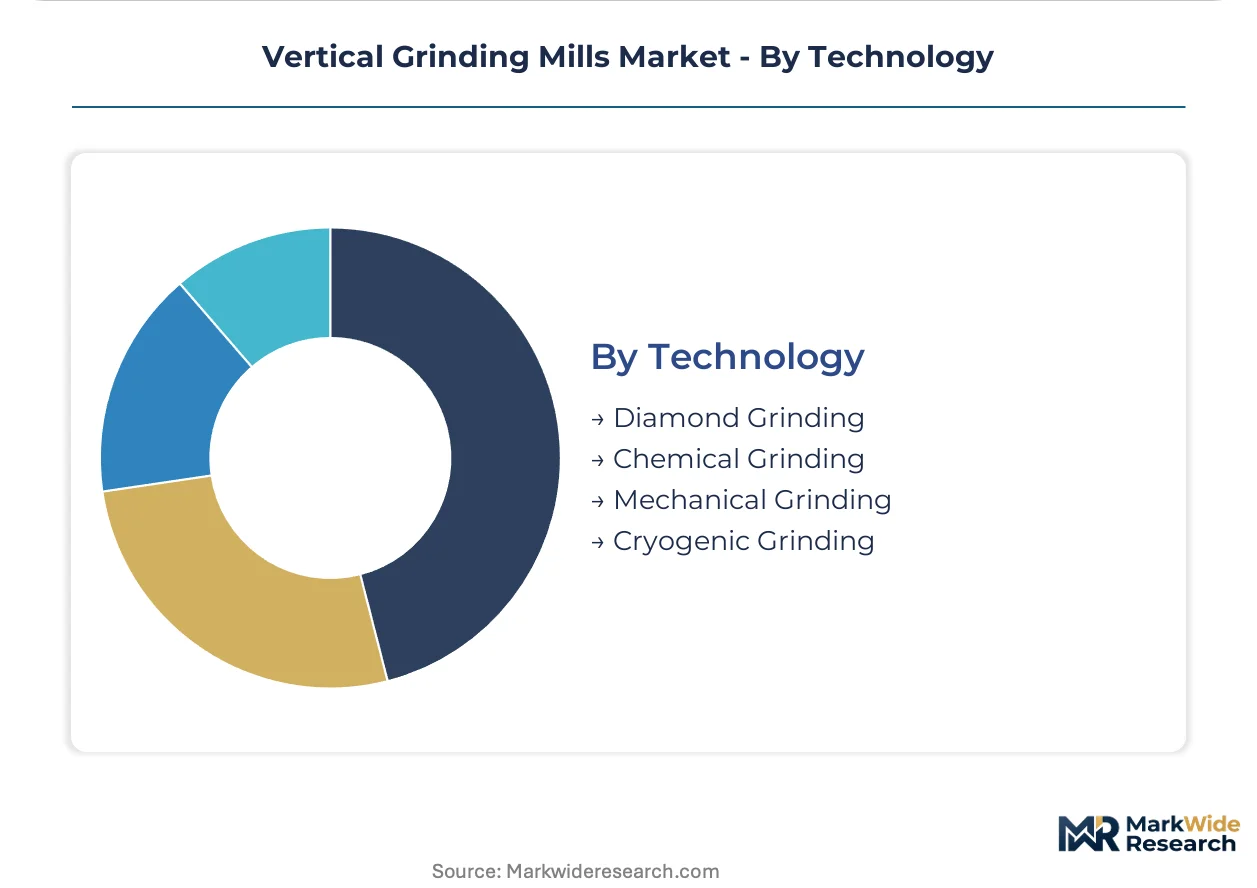
Technology:
Process temperature control and feed material embrittlement requirements are fragmenting technology selection, with cryogenic integration opening polymer recycling applications previously inaccessible to mechanical grinding.
- Cryogenic Grinding:Liquid nitrogen embrittlement systems integrated with vertical mill classification for elastomer and thermoplastic feedstocks. Polymer recycling lines in Germany and Poland adopt these configurations to achieve fine particle sizes without thermal degradation, climbing the fastest as F-Gas Regulation phase-down schedules reshape refrigerant system specifications.
- Diamond Grinding:Superabrasive tooling for ultra-hard material precision finishing.
- Chemical Grinding:Additive-assisted size reduction for reactive or heat-sensitive feeds.
- Mechanical Grinding:Conventional roller-table compression for standard mineral and cement processing.
Feed versatility favors Cryogenic Grinding; unit economics favor Mechanical Grinding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vertical grinding mill fabricators export heavily into Poland and Czech cement corridors, while Chinese engineering groups supply copper concentrators across Kazakhstan and Mongolia through Belt and Road infrastructure financing.
China
Copper-gold concentrator expansion in Central Asian mining districts drives mineral grinder procurement from Chinese capital equipment suppliers. MEE enforcement across the Yangtze River Economic Belt tightens particulate discharge limits, compelling integrated kiln-grinding line upgrades. Sichuan-Chongqing cement clusters are retrofitting legacy ball mill circuits with vertical roller configurations to enable waste heat recovery coupling.
Germany
Slag-intensive cement plants in the Rhine-Ruhr corridor are adopting multi-drive vertical mill architectures to maintain specific energy targets under EU Green Deal carbon reduction mandates. REACH chemical registration and F-Gas Regulation phase-down schedules accelerate synthetic ester lubricant conversion. Bavarian precision machining centers concentrate mill housing and multi-drive gearbox fabrication, exposing procurement timelines to single-source bottlenecks.
India
Integrated cement groups in Gujarat and Maharashtra are modernizing kiln-grinding lines under domestic manufacturing incentives from the PLI scheme. BIS alignment with GB mining equipment safety standards conditions market access for imported vertical mill modules. Rajasthan limestone belts favor stationary installations with uninterruptible power supply integration for high-throughput raw meal circuits.
Chile
Copper concentrator operators in the Atacama Desert contract grinding circuit availability rather than capital ownership, transferring roller wear monitoring obligations to OEM service arms. Antofagasta mining districts favor vertical roller configurations over SAG mill alternatives for ore hardness profiles. Service unbundling elevates local spare parts inventory requirements across Chilean and Peruvian sites.
Poland
Cement producers face accelerated REACH lubricant compliance timelines that favor equipment suppliers with pre-certified component packages. Slag moisture variability from regional steelmaking residues drives multi-drive architecture adoption. Silesian industrial corridors anchor clinker replacement projects deploying vertical roller mills for pozzolan grinding to lower process emissions.
Vertical Grinding Mills Market Competitive Landscape
Player mix skews toward German-Japanese precision fabricators and Chinese state-linked engineering conglomerates. The vendor base concentrates around mill housing specialists, multi-drive gearbox suppliers, and integrated plant automation providers. Three archetypes dominate: European modular system architects, Asian scale-driven fabricators, and mining-focused service unbundlers. Competitive moves center on strategic partnerships for remote service coverage and technology licensing for cryogenic grinding integration.
Among German-based precision fabricators, Loesche GmbH and Gebr. Pfeiffer SE occupy positions within the modular system architect tier, exemplifying deep specialization in segmented drive train configurations for high-finish-capacity installations. FLSmidth & Co. A/S represents the integrated plant automation archetype, anchoring competitive positioning through pyroprocess optimization bundling. These three entities collectively illustrate how European engineering heritage converges with sustainability compliance pressures to shape procurement influence in cement corridor modernization programs.
| Leading Market Players |
|---|
| Loesche GmbH |
| Gebr. Pfeiffer SE |
| FLSmidth & Co. A/S |
| Thyssenkrupp AG |
| Metso Outotec |
| Ube Machinery Corporation |
| Sinoma International Engineering Co. Ltd. |
| CITIC Heavy Industries Co. Ltd. |
| CHAENG (Xinxiang Great Wall Machinery Corporation) |
| Others |
Value Network & Pricing Analysis
Clinker replacement material substitution—slag, pozzolan, and calcined clay displacing conventional Portland cement—simultaneously redraws procurement geography toward steelmaking-adjacent regions and compresses grinding circuit pricing power as buyers prioritize energy efficiency metrics over capital cost alone. German and Chinese OEMs now compete on lifecycle cost models that bundle roller wear monitoring with upfront equipment sales.
Pricing Analysis
Mechanical grinding technology pricing gaps separate legacy single-drive installations from next-generation multi-drive architectures and emerging cryogenic configurations. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels tracks CE marking and REACH pre-certification status. Cost compression in economy tiers intensifies because Chinese fabricators expand module exports under Belt and Road financing. Mining operators contracting availability-based service agreements show least price sensitivity; independent cement processors in emerging markets exhibit highest.
Supply Chain Analysis
Strait of Malacca transit underwrites chromium-molybdenum alloy flows from South African mining districts to Japanese and German precision machining centers. Bavarian and Thuringian fabrication clusters draw from Norwegian ferroalloy smelters and Ukrainian steel billet sources. Single-source vulnerability concentrates in multi-drive gearbox production, where two German engineering groups control segmented torque distribution technology. Distribution runs through OEM-direct project contracting for large cement installations and regional distributor networks for aftermarket wear components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical grinding mill penetration sits at early-cycle expansion in polymer recycling and remote mining mobility segments, justified by cryogenic embrittlement convergence and modular semi-stationary adoption accelerating beyond traditional cement and mineral processing strongholds.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance algorithms that lock in roller wear monitoring contracts before Chinese competitors establish local service arms. Prioritize backward integration into synthetic ester lubricant formulation to capture REACH compliance premiums that commodity suppliers forfeit.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or Poland unlocks European cement corridor procurement where incumbent lead times extend beyond project sanction deadlines. Target cryogenic grinding module supply to polymer recyclers in Central European industrial clusters as the most penetrable white space. Lead with containerized skid configurations for Kazakh copper districts where infrastructure capital constraints block stationary installations.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors modular system architects with pre-certified component packages over pure fabrication scale. Long-term viability hinges on service revenue attachment rates exceeding equipment margins. Monitor MEE enforcement intensity across China's Yangtze River Economic Belt as the inflection signal for accelerated retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Drive Technology Licensing | Segmented torque distribution enables table diameters beyond six meters without gearbox scaling penalties. |
| Cryogenic System Integration | Liquid nitrogen embrittlement opens polymer recycling applications previously inaccessible to mechanical grinding. |
| Service Unbundling Expansion | Availability-based contracting transfers maintenance liability to OEM arms and elevates local inventory requirements. |
| Backward Integration into Lubricants | Synthetic ester formulation captures REACH compliance premiums in German and Polish cement corridors. |
| Semi-Stationary Modular Deployment | Containerized skids enable relocation between Mongolian and Kazakh ore bodies without permanent infrastructure. |
Research Methodology
Desk research of trade customs databases, EU ETS emissions registry filings, and MEE discharge permit records preceded structured interviews with cement plant engineering directors, copper concentrator maintenance managers, OEM aftermarket service heads, and polymer recycling line operators. Primary fieldwork across German fabrication clusters and Chinese engineering group headquarters combined with secondary validation from SEC filings and Belt and Road project finance disclosures. Bottom-up equipment procurement tracking and top-down sectoral demand modeling underwent triangulation against disclosed capacity expansion announcements.
Variance decomposition across product type, installation mobility, and technology temperature regime shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include material hardness category, regulatory exposure cluster, and end-user procurement authority structure. CAGRs derived from installed base turnover rates and greenfield project sanctioning velocity incorporated ore body depletion timelines for mining applications and clinker replacement mandates for cement processing.
The analysis sits within stated boundaries; outcomes outside sustained copper concentrate throughput expansion or accelerated EU carbon border adjustment implementation would require recalibration. Forecasts reflect assumptions regarding alloy price stability and MEE enforcement continuity. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and India PLI scheme localization incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
CNC Machine Market