
 North America Mobile Crane Market | 2026-2036
North America Mobile Crane Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Crane Market Analytics
Market Context
OSHA crane operator certification requirements are repositioning rental fleet operators toward higher-specification equipment with documented maintenance histories. Manitowoc leverages its domestic manufacturing footprint to sustain shorter lead times for North American contractors. Liebherr Group anchors its competitive stance through technology leadership in wind turbine erection cranes. Terex Corporation differentiates via specialized rough terrain models optimized for oil patch applications in the Permian Basin.
Technical Definition and Segment Structure
North America mobile cranes encompass self-propelled lifting machines mounted on wheeled or crawler undercarriages, with load capacities spanning five to thirty-plus tons and boom configurations including telescopic and lattice designs, engineered for rapid site-to-site relocation without permanent foundation requirements. All-terrain variants command premium positioning due to their dual highway and off-road capability, while crawler cranes dominate margin pools in heavy-lift applications including refinery turnaround work and bridge construction. The 30-plus ton capacity tier leads value contribution as infrastructure owners specify larger single-lift solutions to compress project schedules, with truck-mounted units retaining volume dominance in utility and residential construction segments.
Regulatory Framework and Outlook
FAA obstruction evaluation requirements shape crane deployment near airports across the United States, while Transport Canada enforces provincial weight and dimension regulations that constrain cross-border fleet mobility. OSHA, EPA, and state-level environmental agencies collectively determine equipment eligibility through emissions tiers and operator qualification mandates. Stakeholders must monitor the trajectory of EPA Tier 5 rulemaking and corresponding state-level zero-emission equipment mandates to calibrate fleet replacement cycles and powertrain investment priorities.
Market Dynamics
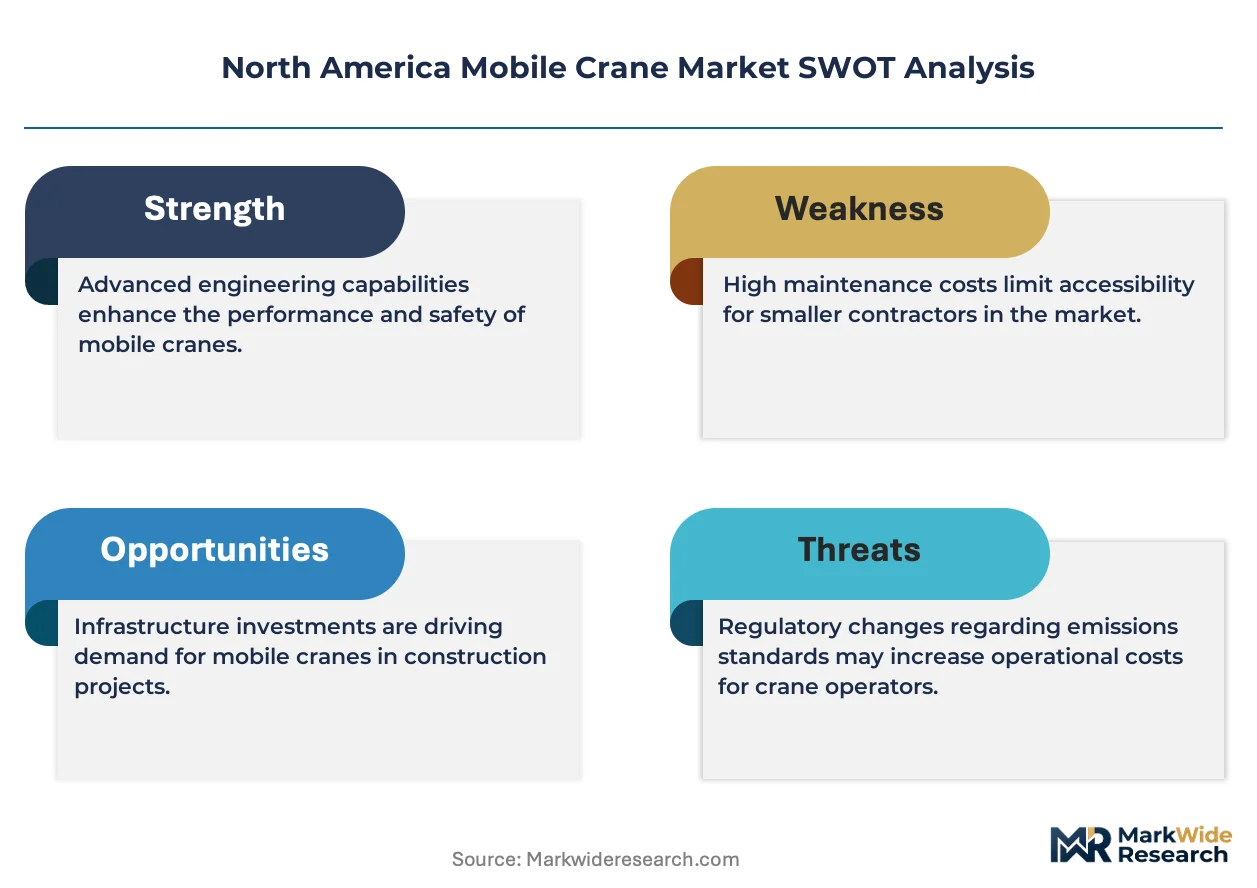
EPA Tier 4 Final and emerging Tier 5 emissions mandates are compressing fleet replacement cycles across rental and contractor operations, forcing capital deployment toward electrified powertrains before total cost parity matures.
Growth Catalysts
- Utility-scale solar and wind construction:Texas and California renewable energy corridors are accelerating crawler crane deployment for turbine nacelle lifts and solar module installation.
- OSHA 1926 Subpart CC enforcement:Mandatory operator certification is pushing fleet operators toward newer equipment with documented maintenance histories and telematics integration.
- Permian Basin petrochemical expansion:Rough terrain crane demand concentrates in West Texas and Louisiana Gulf Coast for refinery turnaround and midstream infrastructure.
Market Restraints
- Steel and high-strength alloy input volatility:Boom fabrication costs fluctuate with specialty plate and weldment pricing, compressing OEM margin buffers.
- Cross-border fleet mobility friction:Transport Canada provincial weight restrictions and US state permitting variance limit equipment repositioning efficiency.
- Battery energy density limitations:Electrified all-terrain models sacrifice lift capacity or operating hours versus diesel equivalents, constraining adoption in heavy-cycle applications.
Strategic Opportunities
- Data center construction vertical:Hyperscale facility builds in Northern Virginia and Phoenix are creating demand for rapid-deployment rough terrain fleets with 24-hour mobilization capability.
- Telematics-enabled predictive maintenance:OEMs are bundling IoT sensor packages to capture recurring software revenue and lock in aftermarket parts flow.
- Canadian federal infrastructure stimulus:Ottawa's capital commitments to bridge and transit projects are expanding addressable demand in Ontario and British Columbia.
Industry Challenges
- Certified operator pipeline constraints:NCCCO testing backlogs and aging workforce demographics are extending project staffing timelines in tight labor markets.
- Powertrain transition capex burden:Dual-fleet maintenance competency and charging infrastructure deployment are demanding capital allocation ahead of revenue certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Crane Market |
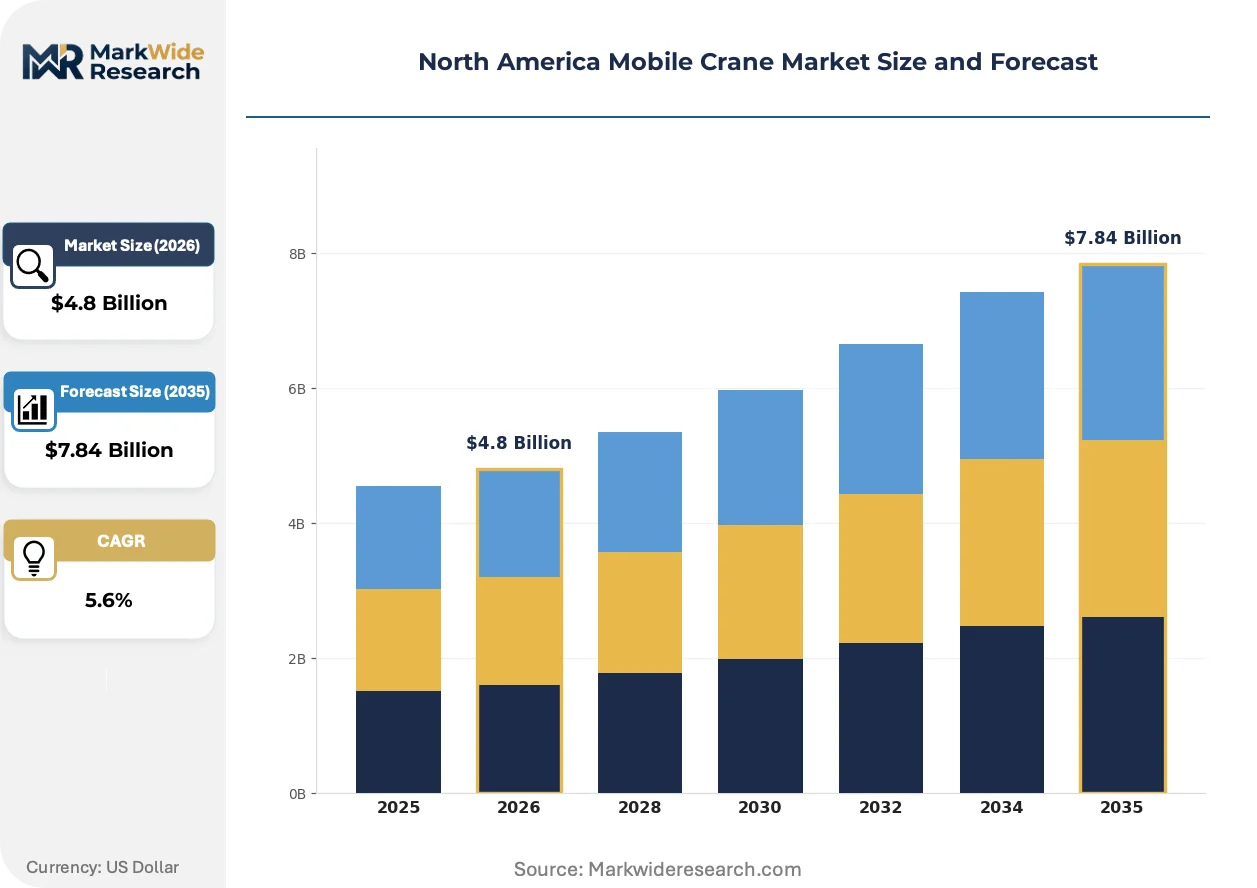
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted, Rough Terrain, All-Terrain, Crawler End User: Construction, Demolition, Manufacturing, Mining Installation: Permanent, Temporary, Mobile, Fixed Capacity: 5-10 Tons, 10-20 Tons, 20-30 Tons, 30+ Tons |
| Companies Covered | Manitowoc, Liebherr Group, Tadano, Terex Corporation, Konecranes, Cargotec Corporation, Link-Belt Cranes, National Crane, Tadano America Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Crane Market Evolving Landscape
Telematics integration and emissions compliance are converging to reshape equipment specification criteria, with buyers prioritizing connectivity-enabled fleets that demonstrate regulatory readiness and utilization transparency.
Hybrid-electric powertrain architecture is unifying diesel range extension with zero-emission site operation capability. Data center contractors in Virginia and Arizona are specifying these configurations to meet corporate sustainability mandates while maintaining uptime. The technology is unifying previously separate equipment categories into single-platform solutions that reduce fleet complexity.
EPA Tier 5 rulemaking trajectory is pressuring OEMs to accelerate electrification roadmaps ahead of final rule publication. Engine suppliers are reallocating R&D toward battery thermal management and hydrogen combustion alternatives. The crawler crane segment faces the steepest compliance cost escalation due to high-displacement diesel dependency.
Rental fleet operators are consolidating supplier relationships around full-service maintenance agreements that transfer uptime risk to OEMs. Large contractors in Texas and Florida are displacing transactional rental with multi-year managed fleet contracts. This shift concentrates procurement influence among national rental chains with balance sheet capacity for fleet refresh programs.
North America Mobile Crane Market Segmentation
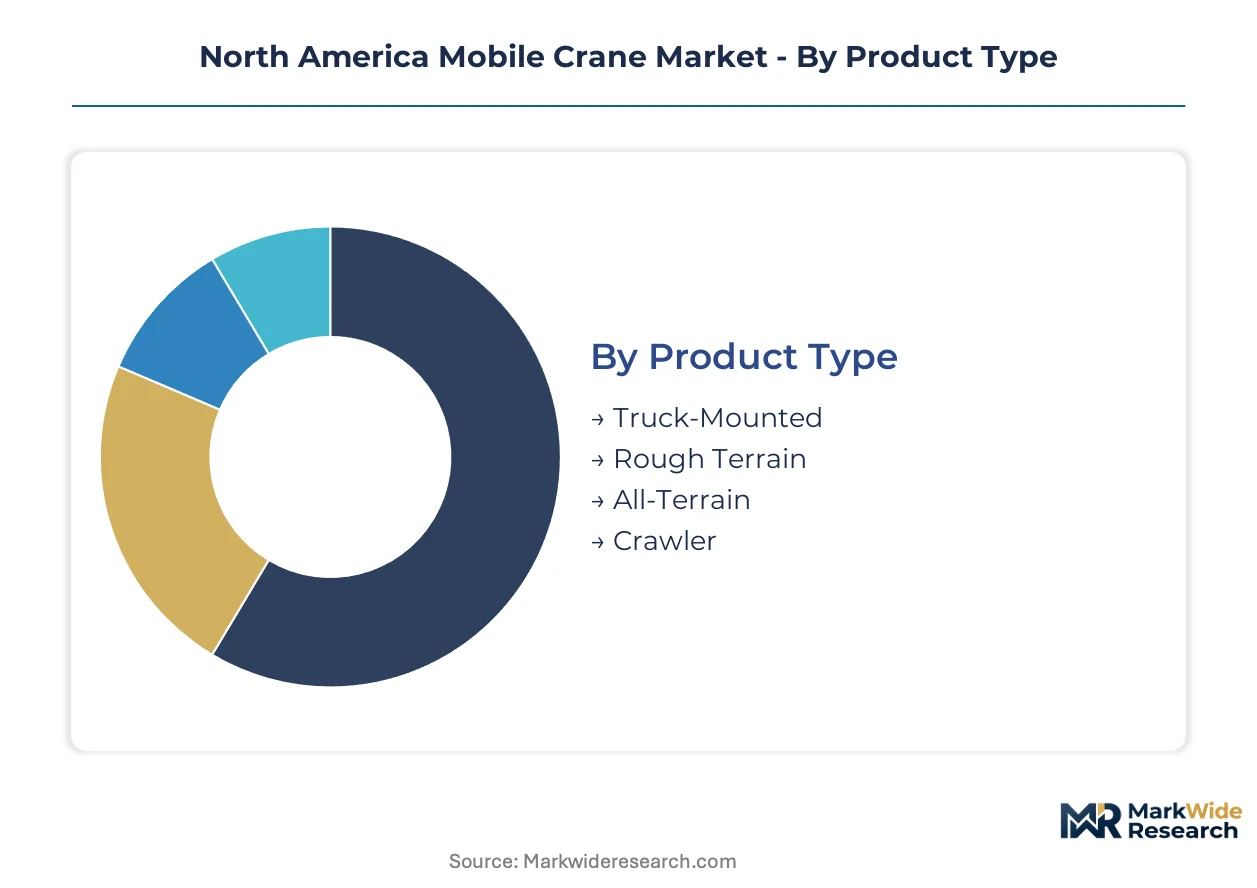
Mobile crane specification varies sharply across lifting requirements, site mobility constraints, and project duration. Fleet operators and rental houses configure procurement around capacity thresholds, terrain adaptability, and end-use regulatory exposure rather than generic equipment classes.
Product Type:
Technology differentiation centers on undercarriage mobility and boom configuration rather than lifting mechanism alone.
- Truck-Mounted:Highway-legal chassis with telescopic booms enable rapid inter-city repositioning without lowboy transport. Demand clusters in utility line work across Texas and Florida where crews require same-day site arrival.
- Rough Terrain:Four-wheel-drive outrigger systems with compact turning radii dominate oil patch turnaround work in the Permian Basin. EPA Tier 4 Final compliance costs are compressing rental fleet replacement cycles for this category.
- All-Terrain:Dual-mode highway and off-road capability commands premium positioning in data center construction corridors.
- Crawler:Lattice boom configurations with ground-bearing pressure distribution anchor heavy-lift applications including wind turbine nacelle erection.
Truck-mounted units lead on scale; all-terrain configurations lead on momentum.
End User:
Application-specific duty cycles and safety compliance exposure reshape equipment specification priorities.
- Construction:Infrastructure and commercial building projects drive volume demand with OSHA 1926 Subpart CC certification requirements favoring newer fleets with documented maintenance histories.
- Demolition:High-cycle precision lifting with extended reach requirements concentrates crawler crane deployment in urban core deconstruction projects.
- Manufacturing:Indoor material handling and assembly line integration favors electric or hybrid powertrains to satisfy corporate sustainability mandates.
- Mining:Harsh operating environments with continuous duty cycles specify heavy-capacity crawler units with reinforced undercarriages.
Construction commands absolute volume; demolition shows steepest expansion trajectory.
Installation:
Deployment duration and foundation requirements segment procurement between capital acquisition and rental models.
- Permanent:Fixed tower configurations with poured foundations serve multi-year industrial facility builds.
- Temporary:Rapid-mobilization units with minimal site preparation dominate turnaround and maintenance cycles.
- Mobile:Self-propelled designs with outrigger stabilization balance flexibility against setup time in utility construction.
- Fixed:Long-term infrastructure projects including bridge construction specify dedicated crawler placement with limited relocation.
Mobile installation leads on scale; temporary installation leads on momentum.
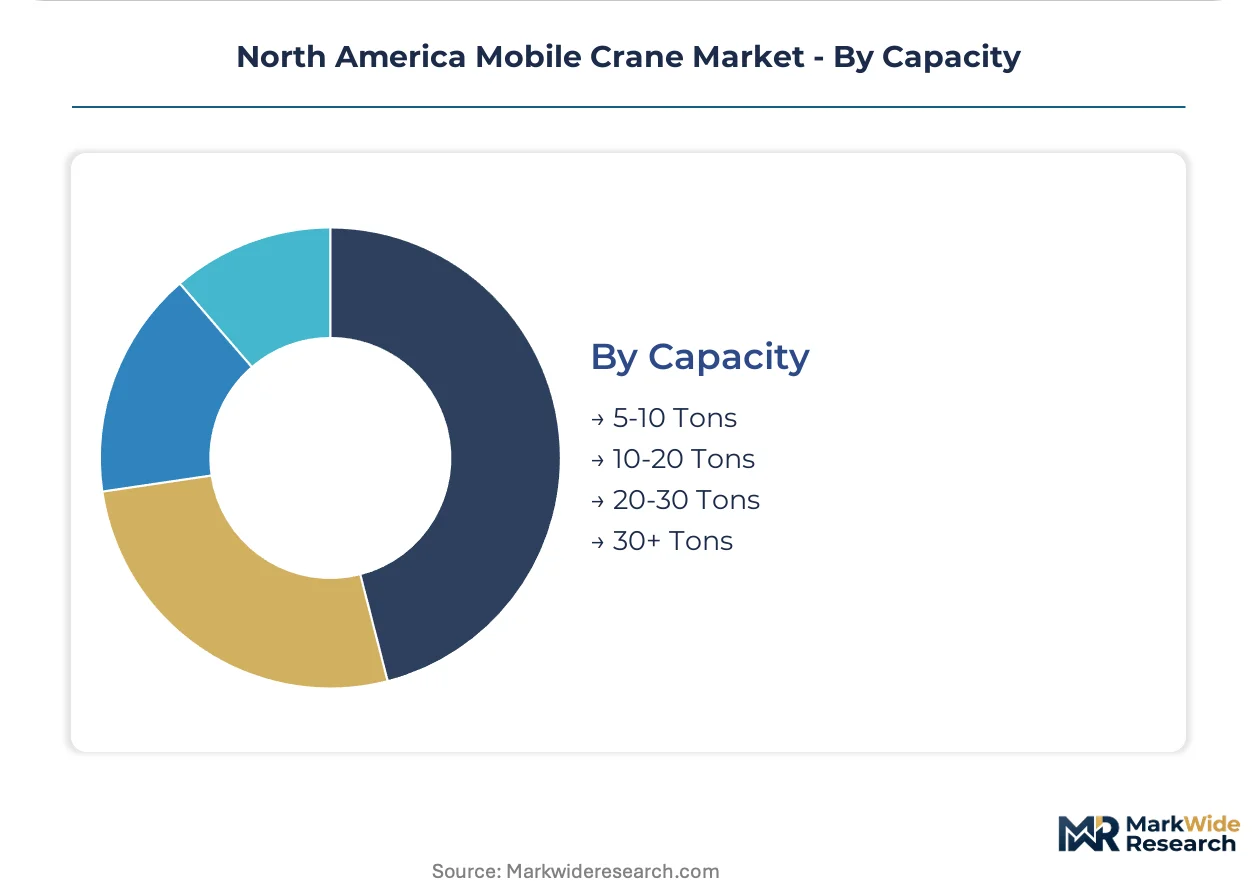
Capacity:
Load rating thresholds determine boom engineering, counterweight configuration, and transport classification.
- 5-10 Tons:Compact truck-mounted units serve residential construction and light utility work with standard CDL licensing requirements.
- 10-20 Tons:Mid-range rough terrain models balance lifting capability against single-operator deployment efficiency.
- 20-30 Tons:Crossover capacity tier attracts rental fleet investment for diversified project coverage.
- 30+ Tons:Heavy-lift specifications with modular counterweight systems compress project schedules through single-lift solutions in refinery and renewable energy construction.
30-plus ton capacity leads on scale; 10-20 ton capacity leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile crane manufacturing first achieved industrial scale in the United States during the post-war infrastructure boom of the 1950s, with crawler and truck-mounted designs proliferating across highway and petrochemical construction. Canadian and Mexican markets subsequently developed as integrated supply chain extensions, though regulatory divergence has complicated cross-border fleet mobility.
United States
Data center construction in Northern Virginia and Phoenix is accelerating rough terrain crane deployment for rapid-mobilization concrete and steel erection. EPA Tier 4 Final and anticipated Tier 5 emissions mandates are compressing fleet replacement cycles across rental and contractor operations. Texas renewable energy corridors anchor crawler crane demand for utility-scale wind turbine nacelle lifts in the Permian Basin and Gulf Coast regions.
Canada
Federal infrastructure stimulus commitments are expanding bridge and transit project pipelines in Ontario and British Columbia. Transport Canada enforces provincial weight and dimension regulations that constrain cross-border equipment repositioning from US rental fleets. Montreal and Toronto construction clusters specify all-terrain units for urban high-rise development with tight site access constraints.
Mexico
Nearshoring manufacturing expansion in Nuevo León and Baja California is driving demand for truck-mounted cranes in industrial facility construction. Mexican federal energy reform implementation is accelerating petrochemical infrastructure investment along the Gulf Coast. Monterrey and Tijuana industrial corridors represent emerging demand centers as automotive and electronics manufacturing capacity relocates from Asia.
North America Mobile Crane Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive crane divisions alongside specialized lifting equipment manufacturers. Tiered positioning separates premium technology leaders from volume-oriented rental fleet suppliers and regional rough terrain specialists. Two dominant archetypes define the field: integrated industrial groups leveraging cross-divisional manufacturing scale, and focused crane specialists optimizing for specific terrain or capacity segments. Competitive moves concentrate on telematics-enabled service bundling and multi-year managed fleet contracts displacing transactional rental relationships.
Among diversified industrial groups, Manitowoc and Liebherr Group exemplify contrasting geographic anchoring strategies, with the former leveraging domestic US manufacturing footprint and the latter representing European-based technology leadership in heavy-lift crawler configurations. Terex Corporation occupies a position within the specialized rough terrain tier, with company nomenclature indicating North American incorporation. These three named entities represent archetype diversity across integrated conglomerate, European technology specialist, and terrain-focused regional player categories.
| Leading Market Players |
|---|
| Manitowoc |
| Liebherr Group |
| Tadano |
| Terex Corporation |
| Konecranes |
| Cargotec Corporation |
| Link-Belt Cranes |
| National Crane |
| Tadano America Corp. |
| Others |
Value Network & Pricing Analysis
Electrified powertrain development across OEM engineering centers is simultaneously escalating R&D cost absorption and consolidating supplier relationships around battery thermal management specialists. Tier 4 Final compliance investments have already compressed margin buffers, forcing pricing architecture to absorb technology transition costs before scale economies mature.
Pricing Analysis
Full-service maintenance agreements versus transactional per-day rental rates now define the dominant pricing split. Three-tier pricing structure across premium telematics-enabled fleets, standard certified units, and economy-grade legacy equipment reflects OSHA documentation requirements and EPA compliance tiers. Cost compression in the economy tier is intensifying because rental fleet operators face accelerated replacement cycles. Price-sensitive independent contractors in residential construction gravitate toward economy tiers, while data center EPCs with corporate sustainability mandates absorb premium positioning for hybrid-electric configurations.
Supply Chain Analysis
High-strength alloy plate supply rests on integrated US steel mills and German specialty metal producers with certified weldment capabilities. Boom fabrication draws from domestic fabrication shops in Wisconsin and Pennsylvania, while hydraulic system components source from Japanese and Italian precision engineering clusters. Single-source vulnerability in EPA-certified engine supply creates procurement risk as Tier 5 rulemaking approaches. Distribution runs through national rental chains with balance sheet capacity for fleet refresh programs, displacing regional independents in major metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American mobile crane demand has shifted toward premium specifications with documented maintenance histories and telematics integration, transforming procurement from commodity rental to quality-assured service contracting. This late-cycle quality story rewards OEMs with captive service capabilities and penalizes undifferentiated volume players.
For Market Incumbents: Anticipate EPA Tier 5 publication by accelerating electrified powertrain certification ahead of final rule implementation. Consolidate aftermarket parts flow through IoT-enabled predictive maintenance bundling to lock in multi-year managed fleet contracts. Defensive positioning requires backward integration into battery thermal management systems to preserve margin control as engine suppliers exit diesel development. For New Entrants and Emerging Players: Capture underserved demand in Mexican nearshoring corridors where US rental fleet cross-border mobility faces Transport Canada weight restriction barriers. Monterrey and Tijuana industrial construction represents the most penetrable geography, with truck-mounted crane specifications for manufacturing facility builds. Go-to-market execution should emphasize rapid-deployment capability with 24-hour mobilization SLAs matching data center contractor requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional rough terrain specialists lacking telematics infrastructure and multi-year contract books. Long-term viability across the projection horizon favors OEMs with captive North American manufacturing footprints and EPA certification track records. The signal to watch is Tier 5 rulemaking trajectory acceleration, which would trigger distressed asset availability among undifferentiated rental fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Powertrain Certification | EPA Tier 5 readiness secures fleet eligibility ahead of diesel phaseout timelines. |
| Telematics Platform Integration | IoT sensor bundling captures recurring software revenue from predictive maintenance contracts. |
| Multi-Year Managed Fleet Agreements | Texas and Florida contractors displace transactional rental with uptime-guaranteed service models. |
| Domestic Manufacturing Footprint Expansion | Wisconsin and Pennsylvania fabrication capacity shortens lead times for North American contractors. |
| Aftermarket Parts Supply Consolidation | Channel control over high-wear components reinforces OEM margin protection in replacement cycles. |
Research Methodology
Bottom-up construction sector modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with fleet maintenance directors, plant engineers at rental houses, OEM procurement teams, and aftermarket service heads were validated against secondary sources including EPA emissions certification databases, OSHA enforcement records, and SEC 10-K equipment revenue disclosures. Triangulation across demand-side project pipeline tracking and supply-side manufacturing output data ensures segmentation integrity.
Historical trendline analysis of capacity deployment patterns across utility-scale renewable energy, data center construction, and petrochemical infrastructure projects informed projection modeling. Segmentation dimensions include product type, capacity tier, installation duration, and end-use regulatory exposure. CAGRs were derived from equipment replacement cycle analysis and capital expenditure trajectory assessment. Forecast inputs incorporate EPA rulemaking timelines, steel input cost volatility, and certified operator pipeline constraints.
EPA Tier 5 publication delays, steel alloy price spikes, and NCCCO certification backlogs are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding regulatory implementation schedules and infrastructure stimulus disbursement pacing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Earthmover Market
Construction Equipment
Piles Turner Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Yard Crane Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Construction Lasers Market