
 Mortar Testing Equipment Market | 2026-2036
Mortar Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mortar Testing Equipment Market Outlook
ASTM C109-grade calibration protocols is reorganizing procurement priorities across the mortar testing equipment sector. Controls Group leverages its European laboratory footprint to sustain premium positioning in compression tester supply. Humboldt Mfg. Co. anchors North American demand through its long-standing distribution network for field-ready flow tables. ELE International competes on technical service density in emerging markets where EN-standard compliance is becoming mandatory.
Mortar testing equipment encompasses instruments that measure compressive strength, workability, setting time, and dimensional stability of cementitious binding materials using standardized load frames, flow tables, and controlled environmental chambers. These devices operate within precise tolerances—typically ±1% load accuracy for compression testers—to ensure batch consistency in structural masonry and plaster applications. Compression testers command the largest installed base among product types due to their universal requirement across quality control protocols. Laboratory testing applications generate higher per-unit margins than field testing despite slower replacement cycles. Testing laboratories represent the most concentrated end-user segment, though construction companies are internalizing basic on-site capability to reduce third-party dependency.
ASTM International governs North American equipment certification while the European Committee for Standardization enforces EN 196 and EN 459 frameworks that dictate calibration intervals and measurement uncertainty limits. China's SAMR aligns GB standards with ISO 679 to facilitate cross-border equipment acceptance, creating compliance complexity for multinational suppliers. Stakeholders must monitor harmonization gaps between regional certification regimes as specification divergence threatens to fragment product development roadmaps.
Market Dynamics
ASTM C109-grade calibration mandates are compressing replacement cycles for compression testers as laboratories face audit scrutiny on load accuracy tolerances. Equipment suppliers must now certify ±1% precision across wider temperature ranges to maintain procurement eligibility.
Growth Catalysts
- Infrastructure rehabilitation:Germany's federal bridge maintenance program is accelerating orders for field-portable flow tables. Municipal testing labs require EN 196-1 compliant units to verify masonry mortar batches on aging concrete structures.
- EN 459 framework expansion:The European Committee for Standardization's updated dimensional stability testing protocols is mandating environmental chamber upgrades. Render and plaster manufacturers must document thermal expansion coefficients for CE marking.
- Automated load frame adoption:Construction companies in commercial high-rise projects are internalizing compression testing to bypass third-party laboratory queues. Touchscreen-controlled units with automatic peak-load detection reduce technician variability.
Market Restraints
- Load cell supply concentration:Precision strain gauge manufacturing clusters in Japan and Germany. Equipment assemblers face extended lead times when specialty sensor suppliers prioritize semiconductor equipment customers.
- Calibration service fragmentation:ISO 17025-accredited laboratories for compression tester verification concentrate in metropolitan corridors. Rural construction firms absorb travel costs for on-site recertification or risk non-compliance.
- Manual tester substitution:Small-scale masonry contractors in emerging markets continue using hand-operated Vicat apparatus for setting time tests. Price sensitivity delays electrified penetration resistance meter adoption.
Strategic Opportunities
- India's PLI scheme alignment:Domestic manufacturing incentives for construction equipment components reduce import duties on load frame assemblies. Local assembly partnerships circumvent BIS certification delays for foreign brands.
- Cloud-connected diagnostics:IoT-enabled compression testers transmit load-displacement curves to centralized quality databases. Ready-mix concrete suppliers leverage this for batch-to-batch traceability and liability documentation.
- SAMR-ISO harmonization:China's alignment of GB standards with ISO 679 creates cross-border equipment acceptance pathways. Multinational suppliers can streamline single-SKU production for Asia-Pacific distribution.
Industry Challenges
- Metrology technician scarcity:ISO 17025 calibration laboratories report vacancies for load cell characterization specialists. Training programs for deadweight force standard operation lag equipment deployment rates.
- Legacy analog integration:Construction firms with 1990s-era compression testers face data format incompatibilities when connecting to modern laboratory information management systems. Retrofit digitization modules require custom software bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortar Testing Equipment Market |
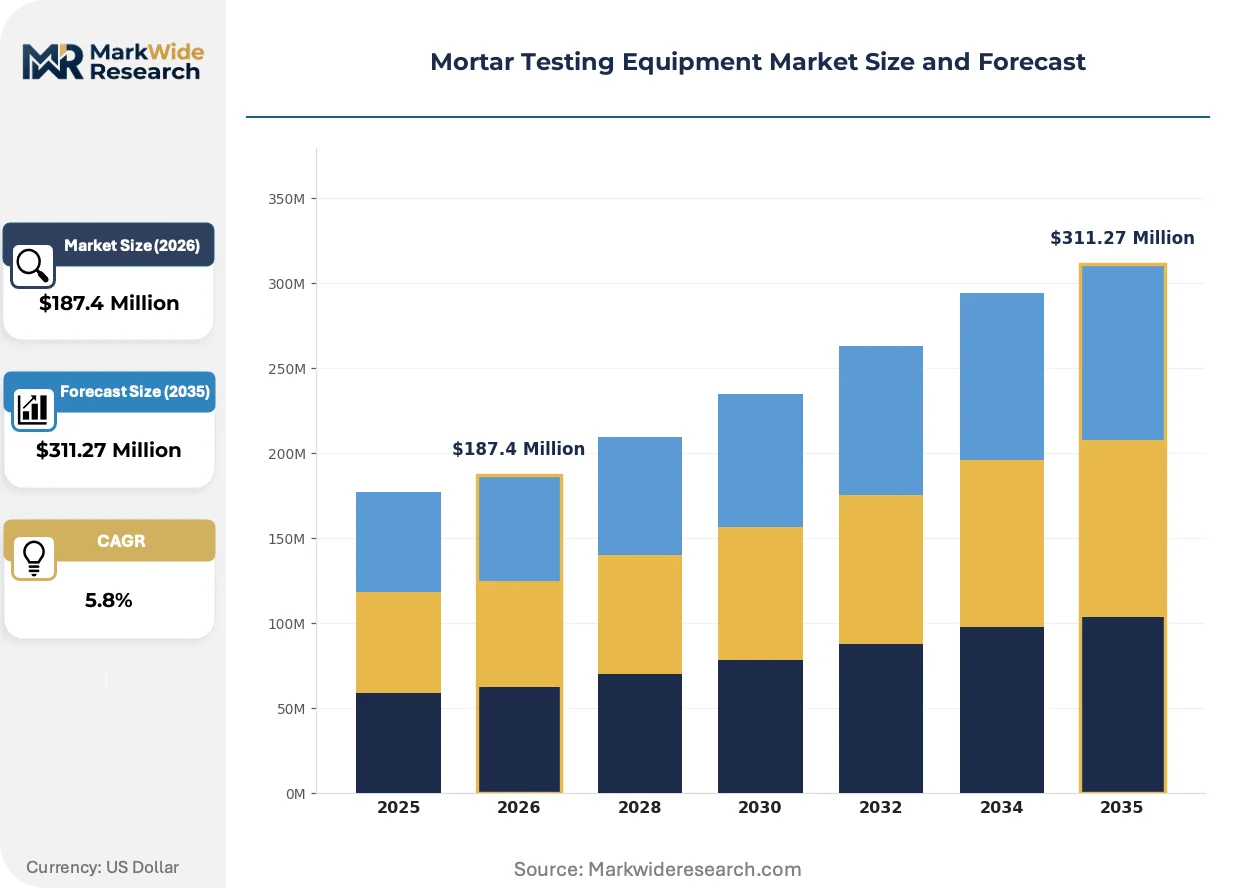
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Testers, Flow Tables, Measuring Devices, Curing Chambers Application: Quality Control, Research & Development, Field Testing, Laboratory Testing End User: Construction Companies, Testing Laboratories, Research Organizations, Educational Institutions Installation: On-Site Testing, Off-Site Testing, Laboratory Setup, User-Friendly Design |
| Companies Covered | Humboldt Mfg. Co., Controls Group, ELE International, Matest, Forney LP, Aimil Ltd., Qualitest International, NL Scientific Instruments Sdn Bhd, Accro-Tech Scientific Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortar Testing Equipment Market Strategic Shifts
Digital load control architectures are displacing hydraulic systems across mortar testing equipment categories. This shift compresses maintenance intervals while enabling remote diagnostic capabilities that reshape service contract structures.
Servo-electric compression testers with closed-loop load control is supplanting traditional hydraulic power packs in laboratory environments. Commercial building material laboratories in Germany and the United States are specifying these units for cyclic fatigue testing protocols. The technology is supplanting annual hydraulic fluid maintenance contracts with predictive motor-bearing monitoring, reducing total cost of ownership for high-throughput facilities.
REACH Annex XVII restrictions on hexavalent chromium coatings are forcing load frame manufacturer redesigns. Surface treatment suppliers must certify alternative zinc-nickel plating for environmental chamber humidity resistance. European equipment vendors absorb recertification costs fastest, while Asian exporters face delayed market access until coating process validation completes.
Consolidated procurement through construction material distributors is displacing direct manufacturer relationships for field testing equipment. Independent testing laboratories in China now source flow tables and penetrometers through regional building supply cooperatives. This channel compression pressures equipment margins while expanding geographic reach into county-level construction bureaus previously served by traveling sales engineers.
Mortar Testing Equipment Market Segmentation
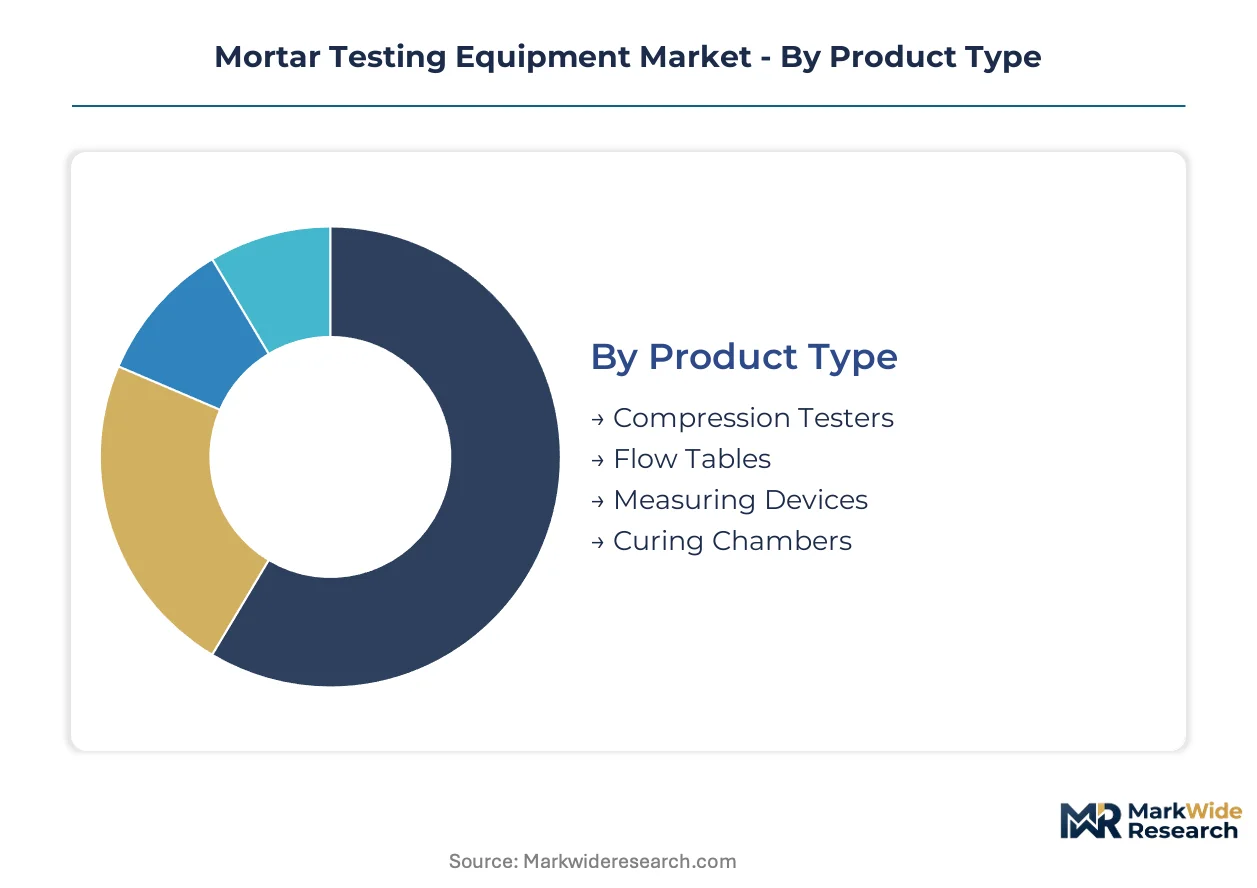
Segmentation in mortar testing equipment reveals distinct procurement patterns shaped by calibration mandates and channel consolidation. Equipment specifications diverge sharply between laboratory certification requirements and field portability needs, creating parallel supply chains with minimal overlap.
Product Type:
Channel concentration varies dramatically by equipment complexity, with compression testers flowing through specialized distributors while flow tables reach contractors via building supply cooperatives.
- Compression Testers:Electromechanical load frames deliver ±1% accuracy across 50-3000 kN ranges for ASTM C109 compliance. German commercial laboratories and US construction material suppliers dominate procurement as infrastructure rehabilitation accelerates batch verification requirements.
- Flow Tables:Standardized brass or stainless steel tables with 300mm diameter tops measure mortar workability per EN 1015-3. Municipal testing labs in Germany order field-portable units for bridge maintenance programs, bypassing third-party laboratory queues.
- Measuring Devices:Digital calipers and dial gauges for dimensional stability testing.
- Curing Chambers:Temperature-humidity controlled cabinets maintaining 20±1°C and 95% relative humidity.
By volume, compression testers lead. By growth pace, curing chambers are expanding most quickly as EN 459 thermal expansion protocols mandate environmental upgrades.
Application:
Margin structures invert across application tiers, with laboratory testing commanding premium pricing despite slower replacement cycles while field testing sacrifices margin for volume throughput.
- Quality Control:Batch consistency verification at ready-mix plants and masonry manufacturing facilities. China's SAMR-aligned GB standards drive compliance investments across provincial construction bureaus.
- Research & Development:Novel binder formulation and admixture performance characterization. Research organizations in Germany specify servo-electric frames for cyclic fatigue protocols on sustainable cement alternatives.
- Field Testing:On-site compressive strength and workability verification.
- Laboratory Testing:Certified reference testing for dispute resolution and export certification.
Quality control absorbs the highest equipment volume. Research and development claims the steepest expansion trajectory as carbon-reduction mandates intensify binder innovation.
End User:
Procurement sophistication stratifies sharply, with testing laboratories demanding ISO 17025-traceable calibration chains while construction companies prioritize technician-operable interfaces.
- Construction Companies:Internalized testing capability for commercial high-rise projects. US firms specify touchscreen-controlled compression testers with automatic peak-load detection to reduce technician variability and bypass third-party queues.
- Testing Laboratories:Accredited facilities serving legal and commercial certification needs. German laboratories face compressed replacement cycles as EN 196-1 calibration scrutiny intensifies on load accuracy tolerances.
- Research Organizations:Universities and national institutes advancing material science.
- Educational Institutions:Vocational training programs for construction technicians.
Construction companies represent the largest addressable population. Testing laboratories generate the highest revenue per account.
Installation:
Service contract structures diverge by installation mode, with laboratory setups bundling predictive maintenance while on-site deployments emphasize rapid field repair networks.
- On-Site Testing:Portable equipment for construction location deployment. Rural US firms absorb travel costs for ISO 17025 recertification or risk non-compliance with ASTM calibration intervals.
- Off-Site Testing:Centralized facilities processing samples from multiple project locations. Chinese independent laboratories now source through regional building supply cooperatives, compressing margins while expanding county-level reach.
- Laboratory Setup:Fixed installations with climate control and vibration isolation.
- User-Friendly Design:Simplified interfaces reducing technician training requirements.
Laboratory setup commands the highest per-unit investment. User-friendly design is gaining share fastest as construction firms internalize basic testing capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized load cell manufacturing clusters in Germany and Japan constrain equipment availability for regional assemblers. Procurement patterns diverge sharply between mature calibration-heavy markets and emerging economies where manual testers persist.
United States
Federal bridge rehabilitation programs drive municipal laboratory upgrades for ASTM C109 compliance. OSHA-aligned workplace safety protocols accelerate replacement of legacy hydraulic compression testers. Chicago-area construction material distributors now consolidate field equipment procurement for county-level testing bureaus.
Germany
The federal transport ministry's infrastructure maintenance initiative expands orders for EN 196-1 compliant flow tables. REACH Annex XVII coating restrictions force load frame manufacturers toward zinc-nickel surface treatments. Bavarian commercial building laboratories specify servo-electric frames for cyclic fatigue testing of sustainable binders.
China
Provincial construction bureaus align GB standards with ISO 679 under SAMR direction, streamlining cross-border equipment acceptance. The dual carbon goals intensify R&D investment in low-carbon cement alternatives requiring advanced testing protocols. Yangtze River Delta ready-mix suppliers internalize quality control to reduce third-party laboratory dependency.
India
PLI scheme incentives for construction equipment components reduce import duties on load frame assemblies. BIS certification requirements delay foreign brand market entry, favoring domestic assembly partnerships. Maharashtra-based infrastructure contractors absorb travel costs for ISO 17025 recertification of field-portable units.
Japan
Precision strain gauge manufacturers prioritize semiconductor equipment customers, extending lead times for mortar testing equipment assemblers. METI-funded material science programs sustain demand for research-grade compression testers. Osaka-area industrial clusters concentrate high-accuracy load cell production for regional equipment builders.
Mortar Testing Equipment Market Competitive Environment
Concentration sits with established European and North American laboratory equipment specialists holding premium positions through calibration service density. The vendor base stratifies across three tiers: integrated multinationals with full testing portfolios, regional specialists dominating single geography compliance, and emerging Asian fabricators competing on component cost. Dominant competitive moves include backward integration into load frame manufacturing and cloud-connected diagnostic service bundling.
Among the named specialists, Controls Group exemplifies European laboratory-centric positioning through its continental service footprint. Humboldt Mfg. Co. anchors North American demand via distribution network depth for field-deployable equipment. ELE International occupies a position bridging emerging market penetration with EN-standard technical compliance. These three represent distinct archetypes: continental service density, regional distribution anchoring, and emerging market standardization respectively.
| Leading Market Players |
|---|
| Humboldt Mfg. Co. |
| Controls Group |
| ELE International |
| Matest |
| Forney LP |
| Aimil Ltd. |
| Qualitest International |
| NL Scientific Instruments Sdn Bhd |
| Accro-Tech Scientific Industries |
| Others |
Value Chain & Pricing Dynamics
ASTM C109 and EN 196-1 calibration protocols gate both supplier qualification and price differentiation simultaneously, compressing equipment margins for uncertified assemblers while rewarding accredited laboratories with premium positioning. Procurement officers at German commercial building laboratories and US municipal testing facilities absorb higher upfront costs to secure ISO 17025-traceable calibration chains, creating parallel pricing universes segmented by compliance tier rather than hardware specifications alone.
Pricing Analysis
ASTM C109 dictates the pricing tier structure across mortar testing equipment, separating EN 196-1 certified laboratories from field-deployable units with reduced calibration documentation. Three-tier pricing structure across premium, standard, and economy levels reflects load accuracy tolerances, touchscreen automation, and bundled service contracts. Cost compression in economy-tier manual testers is intensifying because small-scale masonry contractors in emerging markets delay electrified upgrades. Construction companies internalizing quality control exhibit lowest price sensitivity; rural firms dependent on third-party recertification face highest cost pressure.
Supply Chain Analysis
Strategic stockpiling of precision strain gauges distinguishes Japanese and German equipment assemblers from competitors running lean inventory on specialty sensor procurement. Load frame manufacturing draws from Japan, Germany, and China for strain gauge supply, with surface treatment dependencies on REACH-compliant coating vendors. Single-source vulnerability concentrates in high-accuracy load cell production clusters. Distribution runs through construction material cooperatives for field equipment and specialized laboratory distributors for certified units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 calibration technician shortages constrain expansion velocity for testing service networks, creating acquisition premiums for accredited facilities with trained metrology staff already in place.
For Market Incumbents: Consolidate calibration service density in metropolitan corridors where municipal laboratory audits are compressing replacement cycles. Acquire regional load frame assemblers to secure captive supply of EN 196-1 compliant compression testers. Channel control through building supply cooperatives defends margin position against emerging Asian fabricators competing on component cost. For New Entrants and Emerging Players: Anchor in India's PLI-aligned domestic assembly partnerships to circumvent BIS certification delays burdening direct import strategies. Target county-level construction bureaus in China's Yangtze River Delta where ready-mix suppliers internalize quality control. Cloud-connected diagnostic bundling offers differentiated go-to-market positioning against established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-electric compression tester manufacturing as REACH Annex XVII coating recertification absorbs working capital. Long-term viability favors accredited laboratories with ISO 17025 calibration chains over pure equipment assemblers exposed to raw material volatility. Acquisition target archetype: regional specialists with dense service footprints in infrastructure rehabilitation corridors. Signal to watch: SAMR-ISO harmonization completion triggering cross-border equipment acceptance standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Frame Manufacturing | Controls Group secures captive supply of EN 196-1 certified compression testers against Japanese sensor lead time volatility. |
| Cloud-Connected Diagnostic Service Bundling | IoT-enabled load-displacement monitoring creates recurring revenue streams from ready-mix concrete batch traceability contracts. |
| Regional Calibration Laboratory Acquisition | Humboldt Mfg. Co. extends ISO 17025 service density into rural US corridors absorbing travel costs for field recertification. |
| PLI-Aligned Domestic Assembly Partnership | ELE International circumvents BIS certification delays through Maharashtra-based joint ventures serving infrastructure contractors. |
| REACH-Compliant Coating Process Validation | European vendors absorb zinc-nickel plating recertification costs fastest, delaying Asian exporter market access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory managers at German commercial building facilities, procurement officers at US construction material distributors, metrology technicians at ISO 17025 calibration laboratories, and field engineers at Chinese provincial construction bureaus. Secondary validation incorporated ASTM International certification records, EN standard harmonization documentation from the European Committee for Standardization, SAMR GB standard alignment notices, customs data on load frame component trade flows, and SEC filings from listed laboratory equipment suppliers. Bottom-up equipment shipment tracking triangulated against top-down infrastructure spending forecasts.
Across the analysis window, volume projections model compression tester, flow table, curing chamber, and measuring device categories against quality control, R&D, field testing, and laboratory testing applications. Segmentation dimensions include product type, application tier, end-user sophistication, and installation mode. CAGRs derive from replacement cycle compression under tightening calibration mandates and infrastructure rehabilitation program acceleration. Forecast inputs incorporate German federal bridge maintenance spending trajectories and China's dual carbon goals intensifying low-carbon cement R&D equipment demand.
Material uncertainties — regulatory harmonization gaps between ASTM, EN, and GB frameworks, strain gauge supply allocation shifts toward semiconductor equipment customers, and REACH coating restriction enforcement variability — sit outside the modeled envelope. Forecasts reflect assumptions of steady infrastructure rehabilitation funding continuity and calibration audit scrutiny intensification. Revision becomes warranted when SAMR-ISO harmonization completion or load cell supply concentration disruption crosses thresholds altering equipment availability timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Jib Crane Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Vibratory Plate Compactors Market