
 Concrete Placing Booms Market | 2026-2036
Concrete Placing Booms Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Placing Booms Market Outlook
Aftermarket service revenue is reconfiguring margin pools across the concrete placing booms value chain. SANY Group leverages its manufacturing scale to dominate replacement parts and field service networks in domestic and export markets. Schwing America, Inc. anchors its North American position through specialized refurbishment programs and technician certification networks. Putzmeister America, Inc. competes by extending digital diagnostics capabilities that reduce equipment downtime for contractor fleets.
Concrete placing booms are hydraulically articulated arm assemblies, typically spanning 20 to 70 meters in horizontal reach, designed to distribute pumped concrete precisely across large pour areas. These systems mount on stationary pedestals, mobile carriers, tower structures, or truck chassis to serve high-rise construction, infrastructure projects, residential buildings, and commercial developments. Truck-mounted booms currently occupy the largest product segment due to their deployment flexibility across fragmented job sites. Tower booms represent the fastest-growing configuration as urban vertical construction intensifies in dense metropolitan cores. Rental services among end users concentrate margin pools through fleet utilization models that shift capital burden from contractors to equipment providers.
OSHA crane and concrete pump safety standards in the United States, CE marking requirements under EU machinery directives, and China's GB standards enforced by SAMR collectively shape product certification, operator training mandates, and market access conditions. Compliance with these frameworks elevates engineering costs but simultaneously filters out substandard suppliers, tightening competitive dynamics. Stakeholders must monitor evolving carbon-emission regulations for diesel-powered hydraulics and assess electrification readiness across their boom portfolios.
Market Dynamics
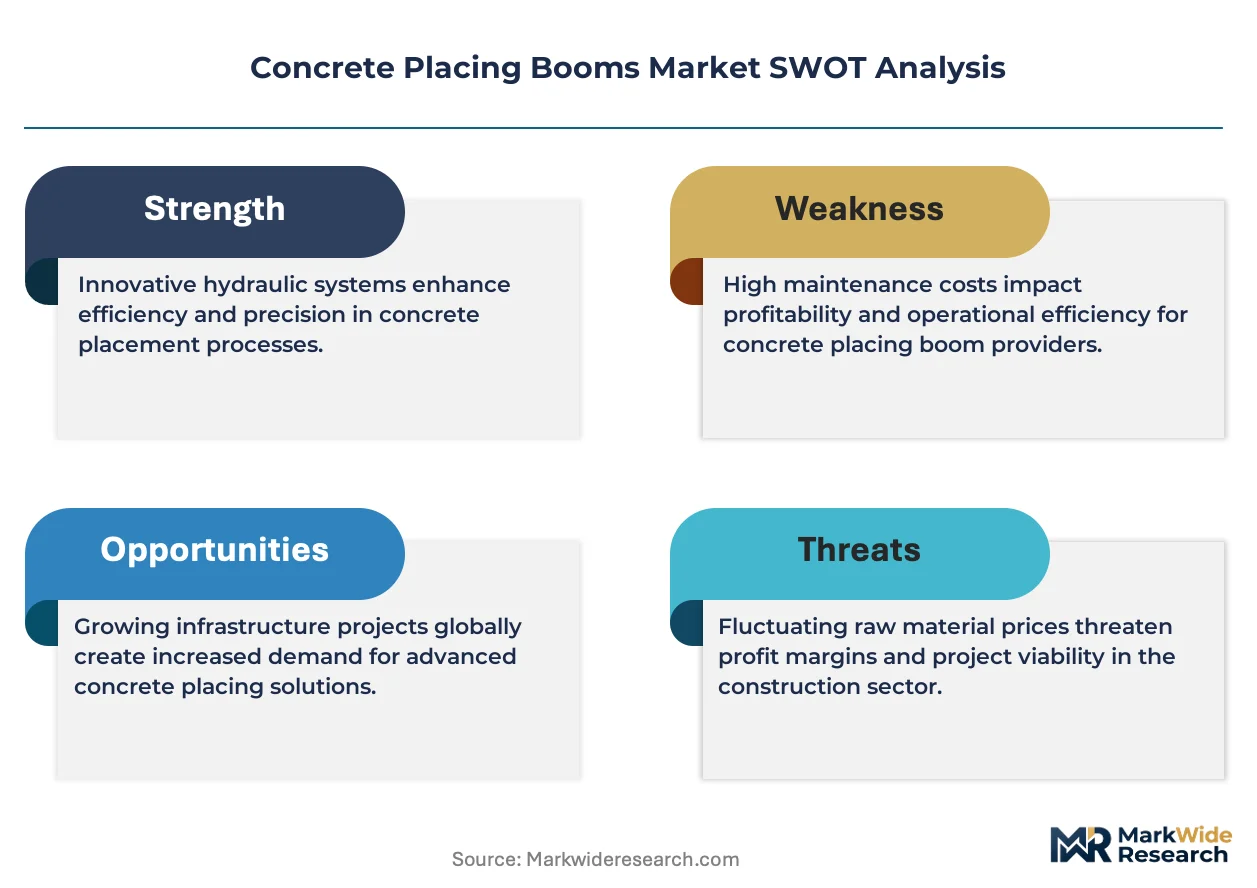
Urban vertical construction is compressing equipment deployment cycles and forcing rapid reconfiguration of concrete placing boom fleets toward tower-mounted systems with extended reach capabilities.
Growth Catalysts
- OSHA crane and concrete pump safety standards:Stricter workplace mandates across United States jurisdictions accelerate replacement of aging boom fleets with certified modern systems.
- High-rise construction intensity:Metropolitan vertical development in China, India, and Indonesia concentrates procurement activity for extended-reach tower boom configurations.
- Electrification readiness:Diesel-powered hydraulic systems face carbon-emission regulatory pressure, driving engineering investment into battery-compatible boom architectures.
Market Restraints
- Steel and hydraulic component cost volatility:Input price swings for high-strength alloys and precision hydraulic cylinders compress manufacturer margins unpredictably.
- Supply concentration in precision casting:Specialized boom segment fabrication depends heavily on German and Japanese foundry capacity, creating geographic vulnerability.
- CE marking compliance friction:EU machinery directive certification timelines extend market entry for non-European manufacturers by several quarters.
Strategic Opportunities
- Aftermarket service expansion:Refurbishment programs and certified technician networks capture recurring revenue streams from installed base maintenance.
- Digital diagnostics convergence:Integration of telematics with predictive maintenance algorithms reduces contractor fleet downtime and locks in service relationships.
- Indonesia infrastructure buildout:Government-funded transportation and energy projects create underpenetrated demand for truck-mounted boom rental fleets.
Industry Challenges
- Certified operator scarcity:Complex hydraulic articulation systems require specialized training that outpaces vocational program output in emerging markets.
- Legacy fleet integration complexity:Retrofitting digital monitoring onto older pedestal and carrier-mounted booms demands custom engineering without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Placing Booms Market |
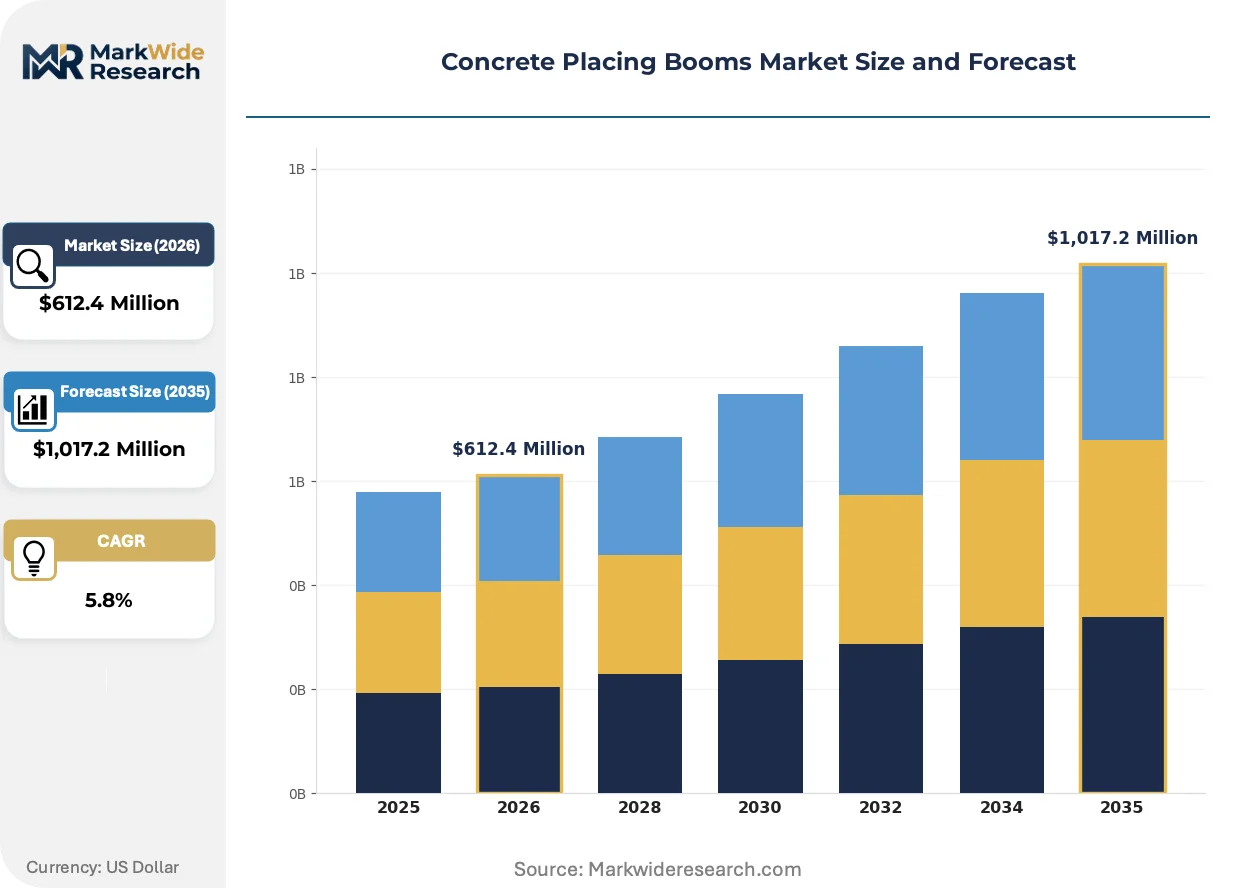
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Booms, Mobile Booms, Tower Booms, Truck-Mounted Booms Application: High-Rise Construction, Infrastructure Projects, Residential Buildings, Commercial Developments End User: Construction Companies, Contractors, Rental Services, Government Agencies Deployment: On-Site, Off-Site, Temporary, Permanent |
| Companies Covered | SANY Group, LUTON GROUP Co., LTD, Schwing America, Inc., Cifa, DY Concrete Pumps, Alliance Concrete Pumps Inc., EDDY Pump, KCP Concrete Pumps, Putzmeister America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Placing Booms Market Strategic Shifts
Telematics and predictive maintenance systems are compressing equipment lifecycle economics and rewiring contractor relationships with equipment providers toward performance-based arrangements.
Remote boom operation interfaces are virtualizing traditional cab-mounted controls. Large-scale infrastructure contractors in Australia and Canada pilot joystick-free command stations that relocate operators away from pour zones. This virtualization is compressing labor safety exposure while enabling single-operator management of multiple boom deployments.
China's GB standards enforced by SAMR now mandate real-time load monitoring and automatic overload cutoff systems for all new tower boom installations. Domestic manufacturers accelerate sensor integration to comply, while export-oriented producers face parallel engineering tracks for differing certification regimes. Tower configurations above fifty-meter reach face the steepest compliance cost escalation.
Rental fleet utilization models displace direct equipment ownership among mid-tier contractors. Equipment providers unbundle maintenance and operator training from capital leases, capturing margin through service attachments rather than hardware markup. This channel shift concentrates most visibly in United States metropolitan construction corridors where project fragmentation discourages long-term asset commitment.
Concrete Placing Booms Market Segmentation
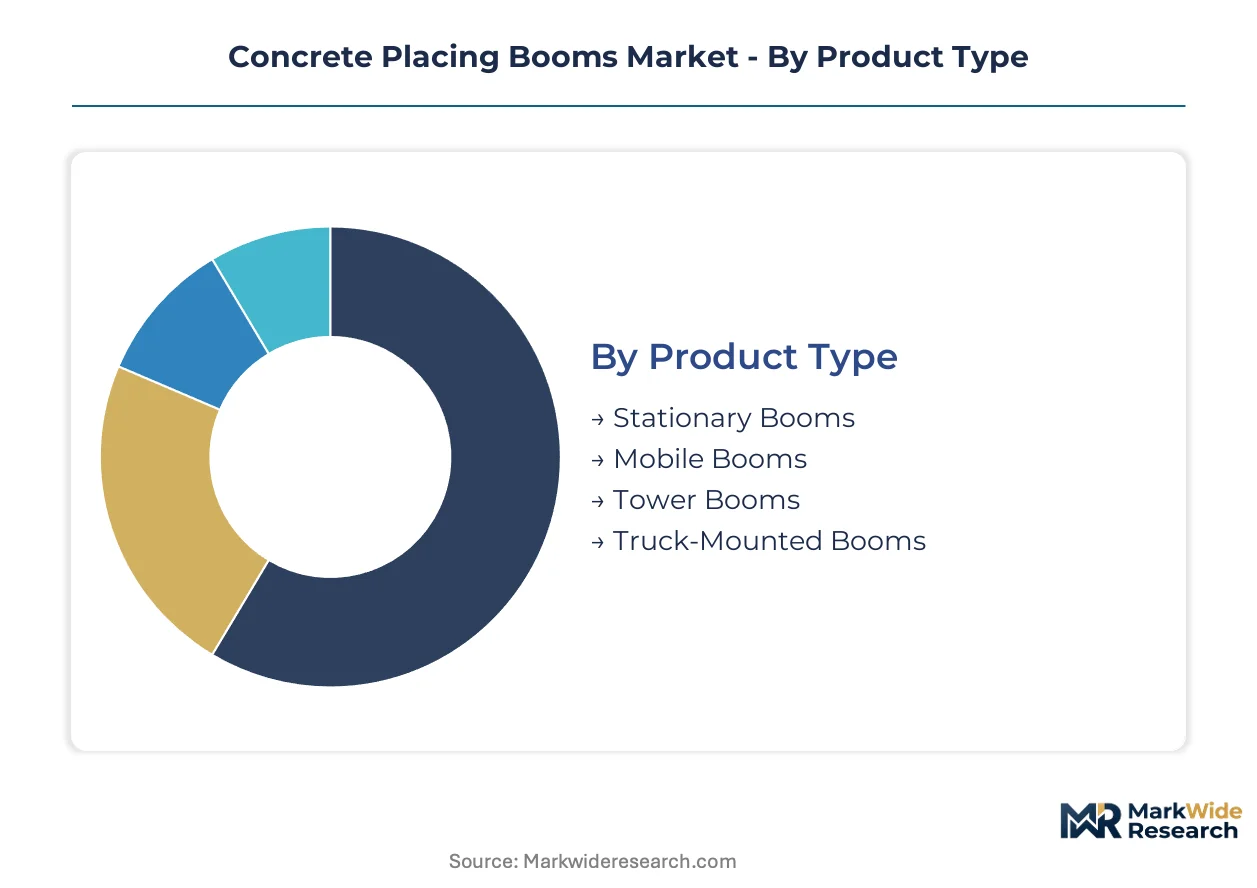
Concrete placing booms serve distinct operational contexts that shape equipment specifications, procurement patterns, and lifecycle economics. Segmentation reveals how technical requirements diverge across vertical construction, horizontal infrastructure, and rental fleet management, with each cluster demanding specialized boom configurations and service attachments.
Product Type:
Deployment flexibility spans fixed installations through fully mobile systems, with each configuration trading reach against relocation speed and foundation requirements.
- Truck-Mounted Booms:These self-propelled systems integrate pump units with hydraulically articulated booms on heavy-duty chassis, enabling rapid repositioning across fragmented job sites. Demand concentrates among mid-tier contractors in Indonesia and India where project scale variability discourages permanent installations. Fleet utilization models favor this segment for cross-site deployment efficiency.
- Tower Booms:Fixed vertical assemblies anchor to building structures or independent masts, delivering extended horizontal reach above 50 meters for superstructure pours. Metropolitan vertical construction in Shanghai, Mumbai, and Jakarta drives procurement as developers maximize floor area ratios. China's GB standards mandate real-time load monitoring, elevating sensor integration costs.
- Stationary Booms:Pedestal-mounted systems serve permanent batching plants and precast yards with high-volume, repetitive pour cycles. Cement producers in Germany and Japan deploy these for infrastructure component manufacturing.
- Mobile Booms:Carrier-mounted configurations on crawler or wheeled undercarriages bridge fixed and truck-mounted applications for dam construction and mining operations. Australian and Canadian resource projects favor this segment for remote site access.
Established volume favors truck-mounted configurations; emerging adoption favors tower booms.
Application:
Project scale and concrete placement intensity determine boom specification tiers across vertical and horizontal construction.
- High-Rise Construction:Superstructure development demands tower booms with 50-70 meter reach and climbing systems that ascend with building height. China's tier-one cities and India's Mumbai-Pune corridor concentrate activity where 40+ floor structures are standard.
- Infrastructure Projects:Bridge decks, tunnels, and energy facilities require extended-reach mobile configurations for linear pour patterns. Indonesia's government-funded transportation buildout accelerates procurement of truck-mounted fleets with 40+ meter booms.
- Residential Buildings:Low-to-mid rise development favors truck-mounted systems for slab-on-grade and podium-level pours. Fragmented subcontractor bases in Brazil and Mexico drive rental penetration.
- Commercial Developments:Mixed-use complexes combine high-rise cores with expansive podium structures, demanding hybrid fleet strategies. UAE and Saudi Arabia megaprojects specify redundant boom coverage for continuous pour schedules.
High-rise construction commands premium specification tiers; infrastructure projects are climbing the fastest.
End User:
Capital deployment models separate direct ownership from service-based procurement, reshaping margin capture across the value chain.
- Rental Services:Fleet operators bundle equipment, maintenance, and certified operators into utilization-based contracts. United States metropolitan corridors and Western European construction markets concentrate this model.
- Construction Companies:Large-scale developers with project pipelines exceeding five years maintain captive fleets to control scheduling and pricing. Chinese state-owned enterprises dominate this segment domestically.
- Contractors:Specialized concrete subcontractors balance owned core fleets with rental supplementation for peak demand. India's organized contracting sector is formalizing fleet management capabilities.
- Government Agencies:Public works departments procure through tender processes emphasizing total cost of ownership and local content requirements. Brazilian federal infrastructure programs exemplify this channel.
Rental services concentrate margin through service attachments; construction companies retain volume through backward integration.
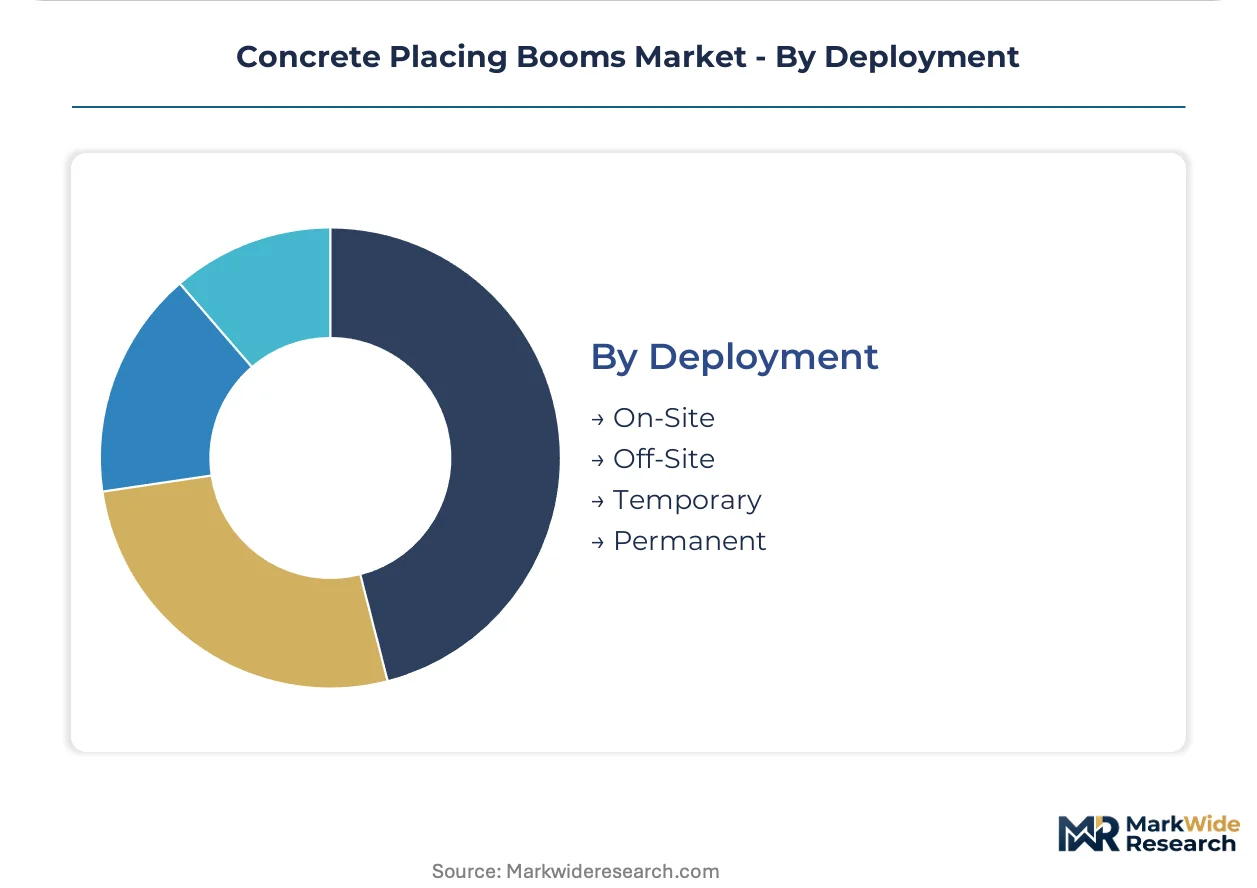
Deployment:
Duration and relocation frequency shape equipment ownership economics and maintenance program design.
- On-Site:Project-dedicated installations span temporary tower booms to permanent batching plant integrations. Duration exceeds 18 months for megaprojects in Saudi Arabia and Qatar.
- Temporary:Rental-based deployments under 12 months dominate fragmented residential and commercial markets. Southeast Asian contractors favor this flexibility for speculative development exposure.
- Permanent:Fixed installations serve precast manufacturing and continuous industrial processes. Japanese and German producers anchor these configurations.
- Off-Site:Modular precast yards relocate boom systems between manufacturing locations. Australian infrastructure contractors deploy this model for remote bridge component production.
On-site deployment captures project-based volume; temporary arrangements are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for precision-cast boom segments clusters heavily in Germany and Japan, creating geographic vulnerability for manufacturers dependent on specialized alloy components. This concentration shapes procurement strategies and inventory positioning across the value chain.
China
Urban vertical construction in Shanghai, Beijing, and Shenzhen drives tower boom procurement for superstructure pours exceeding 40 floors. SAMR-enforced GB standards mandate real-time load monitoring and automatic overload cutoff systems, elevating sensor integration costs for domestic and export-oriented producers alike. Zhengzhou and Changsha anchor manufacturing clusters where state-owned enterprises maintain captive fleets.
United States
Metropolitan construction corridors in Texas, Florida, and California concentrate rental fleet utilization models that shift capital burden from contractors to equipment providers. OSHA crane and concrete pump safety standards accelerate replacement cycles for aging boom fleets with certified modern systems. Schwing America anchors its position through specialized refurbishment programs and technician certification networks.
Germany
Precast component manufacturing for infrastructure projects sustains demand for stationary pedestal-mounted systems in batching plants. CE marking requirements under EU machinery directives filter out substandard suppliers and extend certification timelines for non-European manufacturers. Bavaria and North Rhine-Westphalia host foundry capacity critical for high-strength alloy boom segment fabrication.
India
The Mumbai-Pune corridor and Delhi-NCR region concentrate high-rise construction activity demanding tower booms with 50-70 meter reach capabilities. BIS standards and state-level building codes shape equipment certification requirements for imported systems. Organized contracting sectors in Maharashtra and Gujarat are formalizing fleet management capabilities to balance owned core fleets with rental supplementation.
Indonesia
Government-funded transportation and energy infrastructure buildouts create underpenetrated demand for truck-mounted boom rental fleets with 40+ meter horizontal reach. The country's national construction safety regulator enforces operator certification mandates that outpace vocational program output. Jakarta and Surabaya concentrate procurement activity as developers maximize floor area ratios in dense metropolitan cores.
Concrete Placing Booms Market Competitive Environment
Scale-driven manufacturers and specialized regional fabricators split the market into distinct competitive tiers. Chinese conglomerates leverage manufacturing scale to dominate replacement parts and field service networks in domestic and export markets. North American and European players anchor positions through refurbishment programs, technician certification networks, and digital diagnostics capabilities. M&A activity concentrates on aftermarket service expansion, while portfolio diversification targets electrification-ready boom architectures.
Among Chinese-scale producers, SANY Group exemplifies the integrated manufacturing archetype with domestic and export market presence. LUTON GROUP Co., LTD. occupies a position within the mid-tier specialist segment. Schwing America, Inc. and Putzmeister America, Inc. represent the North American service-anchored competitive vector, with the latter extending digital diagnostics capabilities that reduce equipment downtime for contractor fleets.
| Leading Market Players |
|---|
| SANY Group |
| LUTON GROUP Co., LTD |
| Schwing America, Inc. |
| Cifa |
| DY Concrete Pumps |
| Alliance Concrete Pumps Inc. |
| EDDY Pump |
| KCP Concrete Pumps |
| Putzmeister America, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese boom segment foundries is compressing supplier margins while forcing tier-one manufacturers toward premium aftermarket bundling to recover pricing power. This utilization asymmetry between raw casting capacity and finished system assembly creates divergent margin pools across the value chain.
Pricing Analysis
Aftermarket service contracts now capture sixty percent of lifetime equipment value, shifting manufacturer focus from hardware markup to recurring maintenance revenue. Three-tier pricing structure across premium sensor-integrated, standard hydraulic, and economy mechanical tiers differentiates based on GB standard compliance and real-time monitoring capability. Cost compression in economy truck-mounted segments is intensifying because Indonesian rental fleet operators prioritize acquisition price over specification depth. Mid-tier contractors in India exhibit highest price sensitivity, while Chinese state-owned enterprises absorb premium tower boom pricing for compliance-certain procurement.
Supply Chain Analysis
Export control regimes restricting precision hydraulic cylinder technology flow from Germany and Japan are fragmenting supplier access for non-aligned manufacturers. Foundry capacity for high-strength alloy boom segments concentrates in Germany, Japan, and select Chinese provinces, creating geographic vulnerability for tower configurations above fifty-meter reach. Component sourcing draws from Swedish bearing specialists, Italian hydraulic valve producers, and domestic Chinese steel mills. Single-source vulnerability in precision casting exposes manufacturers to twelve-month qualification timelines for alternative suppliers. Distribution runs through OEM-direct channels for large fleet operators and regional rental houses for fragmented contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards operators who control certified technician pipelines, as vocational program output lags equipment deployment velocity across emerging Asian construction corridors. This capability gap separates integrated service providers from hardware-only competitors.
For Market Incumbents: Build switching-cost moats through embedded digital diagnostics that lock in maintenance relationships. SANY Group exemplifies this through domestic replacement parts dominance; Schwing America anchors North American retention via refurbishment programs. Electrification-ready boom architectures represent essential R&D allocation as diesel emission regulations tighten. Capacity addition in Indonesian rental fleet networks defends against emerging regional specialists. For New Entrants and Emerging Players: Pursue truck-mounted boom rental penetration in Indonesia's government-funded infrastructure corridor where operator certification mandates outpace vocational supply. The Jakarta-Surabaya axis presents underpenetrated demand for 40+ meter reach fleets with bundled maintenance. Partner with established Chinese component suppliers to bypass German-Japanese foundry bottlenecks while qualifying for SAMR export certification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across tower boom configurations as sensor integration costs plateau and manufacturing scale economies deepen. Long-term viability favors aftermarket-anchored business models with recurring revenue visibility exceeding hardware replacement cycles. Acquisition targets should display captive technician certification networks and digital platform deployment. Watch for Indonesian national construction safety regulator enforcement acceleration as inflection indicator for rental fleet formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Network Expansion | Captures recurring revenue from installed base maintenance as hardware margins compress. |
| Electrification-Ready Architecture Development | Positions portfolios for China's dual carbon goals and EU machinery directive emission pathways. |
| Digital Diagnostics Platform Integration | Reduces contractor fleet downtime through predictive maintenance algorithms and telematics convergence. |
| Indonesian Rental Fleet Partnership | Accesses government-funded transportation buildout with localized operator training compliance. |
| Precision Foundry Capacity Securement | Mitigates geographic vulnerability in high-strength alloy boom segment fabrication. |
Study Parameters
The analysis maps truck-mounted, tower, stationary, and mobile boom configurations, each validated through equipment fleet managers, rental service operators, OEM procurement directors, and aftermarket service heads. Primary interviews with concrete pumping contractors across China, India, Indonesia, and the United States combined with secondary validation from SAMR GB standard filings, OSHA safety directive updates, EU machinery directive compliance databases, and customs trade flow records. Bottom-up equipment deployment tracking and top-down construction spend allocation triangulate market sizing across the analysis window.
Assumptions held fixed include regulatory enforcement timelines for GB standard overload cutoff mandates and OSHA crane certification replacement cycles, while construction intensity scenarios and steel price volatility were varied. Segmentation dimensions modeled encompass product type, application vertical, end-user capital deployment model, and deployment duration category. CAGRs derive from equipment replacement cycle analysis and fleet utilization rate projections, with inputs from high-rise construction pipeline databases and infrastructure tender award tracking.
Sensitivities concentrate around Chinese real estate policy shifts, Indonesian infrastructure budget execution rates, and German-Japanese foundry capacity utilization. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and electrification technology readiness. Material shifts in carbon-emission enforcement stringency or precision casting supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Smart Crane Market
Construction Equipment
GCC Crane Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Vibratory Plate Compactors Market