
 Trenchers Market | 2026-2036
Trenchers Market Size, Share, and Industry Trends Forecast 2026-2036
Trenchers Market Intelligence
The modularization of digging chains and cutting wheels for specific soil types is repositioning buyer preference toward versatile equipment platforms. Vermeer Corporation competes with a broad portfolio that spans multiple equipment sizes and applications for diverse contractors. Ditch Witch leverages its established distribution network to serve the critical utility contractor segment. Tesmec S.p.A. differentiates itself with high-powered, specialized machines designed for challenging rock trenching projects.
Trenchers are specialized excavation machines designed to dig continuous trenches of a specified width and depth. They operate using either a toothed metal chain or a large, high-strength steel wheel to cut through soil, asphalt, and rock. While chain trenchers remain the dominant product type for general construction, micro trenchers are seeing accelerated use in telecommunications for fiber optic cable laying. Utility installation and pipeline construction applications continue to form the core demand base for construction companies and agricultural contractors.
Engine emission regulations, including the EPA's Tier 4 standards in the United States and the EU's Stage V requirements, influence equipment design and cost. Worker safety mandates from bodies like OSHA and protocols for CE marking in Europe govern machine operation and safety features. Manufacturers must now balance investments in diesel compliance against developing next-generation electric and autonomous trenching solutions.
Market Dynamics
The expansion of digital infrastructure serves as the central force defining the trenchers market. Global government initiatives aimed at closing the digital divide and the private sector's race to deploy 5G networks are creating sustained demand for efficient excavation machinery.
Growth Catalysts
- Government Infrastructure Spending:Public funding for rural broadband expansion in countries like the United States and India, alongside large-scale utility modernization projects, directly stimulates demand for new trenching equipment for network and pipeline installation.
- Fiber Optic Deployment:The global rollout of 5G and fiber-to-the-home (FTTH) networks by telecommunications companies requires extensive, precise trenching, particularly for micro trenchers used in urban environments for laying fiber optic cables.
- Agricultural Modernization:The adoption of precision agriculture techniques is driving investment in advanced irrigation and drainage systems, which necessitates the use of chain and wheel trenchers for creating channels in large-scale farming operations.
Market Restraints
- High Capital Investment:The significant upfront cost of purchasing trenchers, especially high-powered rock trenchers, presents a substantial financial barrier for small-to-medium-sized contractors and rental companies, limiting market entry.
- Stringent Emission Regulations:Compliance with mandates such as the EPA's Tier 4 standards and the EU's Stage V requirements increases equipment manufacturing costs and design complexity, which are passed on to the end-user.
- Alternative Excavation Technologies:For certain applications, particularly in congested urban areas or for short-distance crossings, alternative methods like horizontal directional drilling (HDD) can offer a less disruptive substitute to open-cut trenching.
Strategic Opportunities
- Equipment Electrification:Developing battery-electric and hybrid-electric trenchers creates opportunities to serve markets with strict noise and emission regulations, such as dense European city centers, and aligns with corporate sustainability goals of major contractors.
- Autonomous and Remote Operation:Investing in tele-operated and autonomous trenching systems can address skilled labor shortages, enhance worksite safety by removing operators from hazardous areas, and improve operational precision through GPS guidance.
- Expansion in Emerging Economies:Targeting infrastructure projects in rapidly developing regions across Africa and Latin America, where utility and communication networks are being built out, represents a significant long-term growth avenue for equipment manufacturers.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of operators with the technical expertise to safely and efficiently run complex, high-horsepower trenching equipment constrains productivity and increases labor costs for construction and utility contractors.
- Complex Supply Chains:Managing the procurement of specialized components, including high-strength steel for cutting elements and advanced hydraulic systems, exposes manufacturers to volatility in raw material pricing and potential supply disruptions.
- Navigating Divergent Safety Protocols:Adhering to varied regional safety standards, such as OSHA requirements in the United States and CE marking protocols in Europe, complicates equipment design and certification, adding to development time and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trenchers Market |
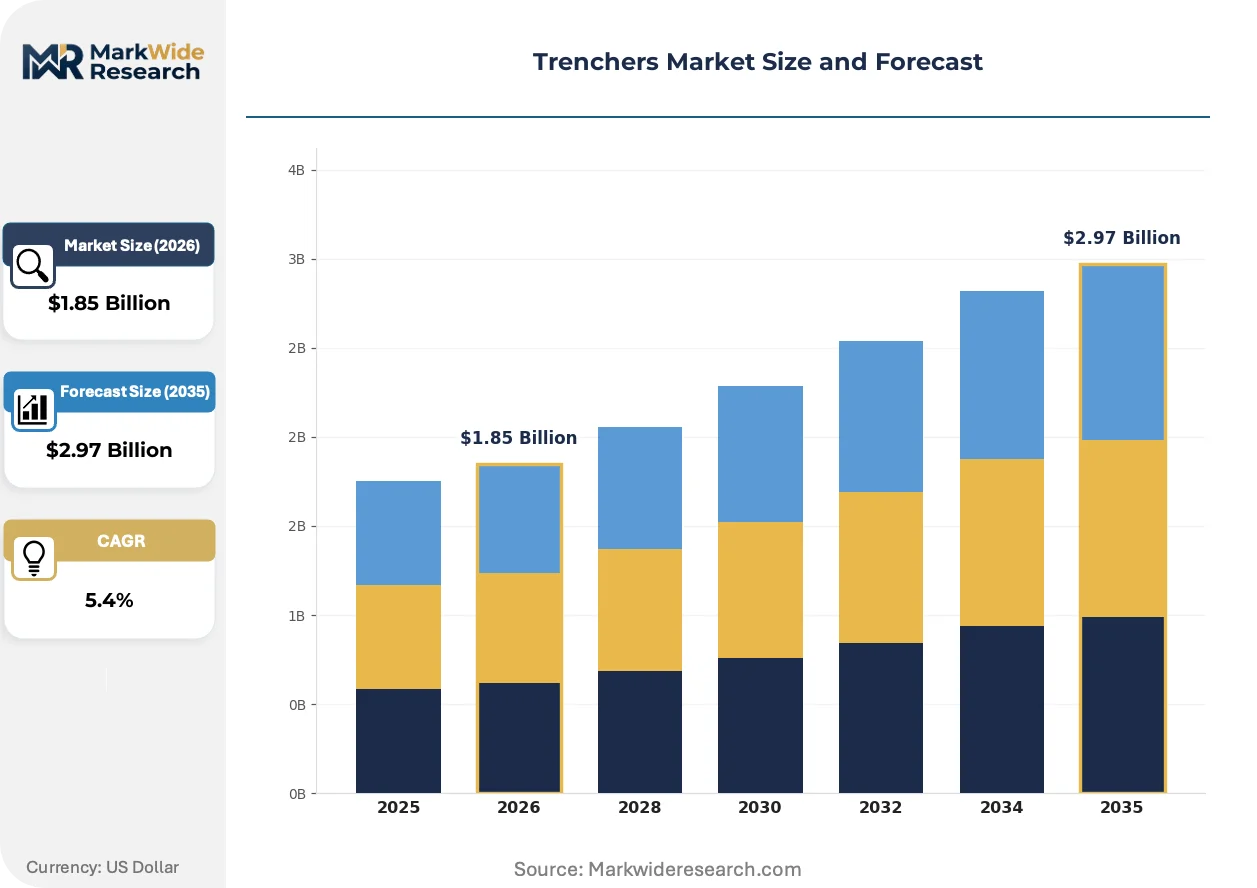
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Trencher, Wheel Trencher, Micro Trencher, Portable Trencher Technology: Hydraulic, Mechanical, Electric, Pneumatic, Diesel-Powered Application: Utility Installation, Pipeline Construction, Irrigation, Cable Laying, Road Construction End User: Construction Companies, Utility Providers, Agricultural Contractors, Telecommunications Firms |
| Companies Covered | Vermeer Corporation, Ditch Witch, Tesmec S.p.A., Wolfe Heavy Equipment, Barreto Manufacturing, Inc., EZ-Trench, LLC, Mastenbroek Limited, Guntert & Zimmerman, Toro Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trenchers Market Strategic Shifts & Innovations
The trenching industry is shifting from a focus on mechanical power to an emphasis on intelligent, connected, and sustainable excavation. This evolution prioritizes data-driven efficiency, regulatory compliance, and adaptable equipment access models to meet the demands of modern infrastructure projects.
Telematics and onboard IoT sensors are becoming standard on new trencher models, providing real-time data on engine performance, hydraulic pressure, and digging chain status. Construction and utility fleet managers are adopting this technology to enable predictive maintenance, optimize fuel consumption, and monitor operator performance remotely. This flow of data is decentralizing job site management, allowing machines to self-adjust to changing soil conditions and alert operators to potential issues before they cause downtime.
Implementation of the European Union's Stage V standards is forcing a significant re-engineering of diesel-powered trenchers sold in the region. These rules require advanced exhaust after-treatment systems to drastically cut particulate matter and NOx emissions. The high-horsepower segment is most impacted, with manufacturers integrating complex technologies that increase both the initial equipment cost and the long-term maintenance requirements for contractors operating in the EU.
A clear behavioral change is the move toward equipment rental and leasing over direct capital purchase, especially among small and mid-sized contractors. This trend disrupts the traditional ownership model, enabling firms to access specialized micro trenchers or large rockwheels for specific project durations without incurring heavy upfront costs. This shift is most visible in the North American and European markets, where extensive rental networks provide access to a wide variety of up-to-date machinery.
Trenchers Market Segmentation
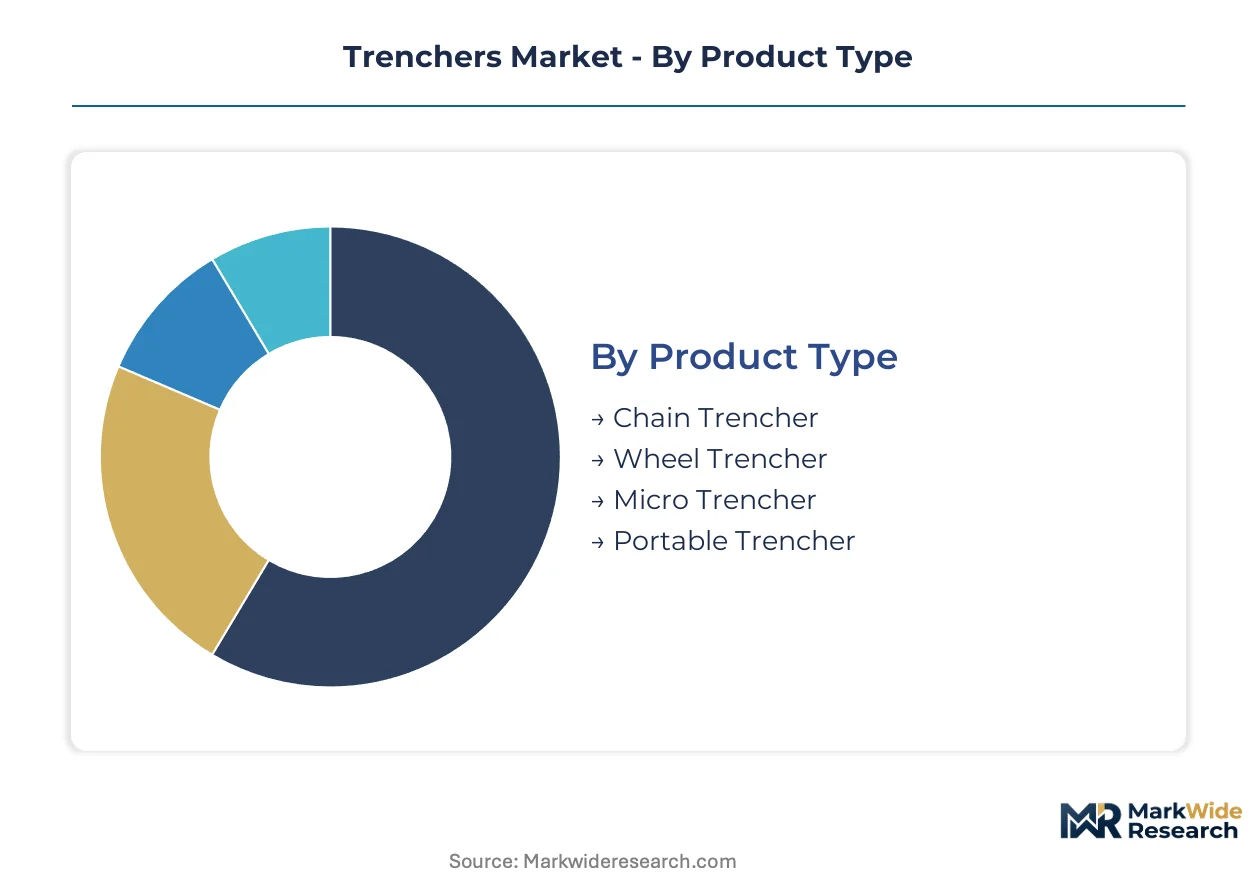
The Trenchers Market segmentation provides a granular view of equipment types, technological advancements, diverse applications, and the distinct end-user groups driving demand. Understanding these segments is crucial for manufacturers to tailor product development and for contractors to select the most efficient machinery for specific project requirements.
Product Type:
The product type segmentation highlights the volume-driven demand for versatile equipment versus the premium investment in specialized, high-performance machinery.
- Chain Trencher:These machines utilize a toothed metal chain to cut through soil and softer ground, remaining the dominant product type for general construction tasks. Demand is consistent from construction companies and agricultural contractors for broad excavation needs across rural areas.
- Micro Trencher:Characterized by their small size and precision, micro trenchers are specifically designed for creating narrow, shallow trenches for fiber optic cable installation. Telecommunications firms in urban environments utilize these for rapid, less disruptive deployment of 5G and fiber-to-the-home networks.
- Wheel Trencher:Wheel trenchers employ a large, high-strength steel wheel to cut through harder materials like asphalt and rock. These are deployed in challenging ground conditions for utility projects.
- Portable Trencher:Lightweight and compact, portable trenchers cater to small-scale landscaping projects and residential utility installations. Their ease of transport appeals to smaller contractors.
Mature deployment sits with Chain Trenchers. Newer deployment is concentrated in Micro Trenchers.
Technology:
The technology segmentation reflects the diverse operational requirements for trenching across various ground conditions and project scales.
- Hydraulic:Hydraulic trenchers leverage fluid power for precise control and high torque, making them versatile for a wide range of soil types and depths. Utility installation and pipeline construction projects frequently employ hydraulic systems for their reliability and power delivery.
- Diesel-Powered:These trenchers utilize internal combustion engines running on diesel fuel, providing robust power for heavy-duty excavation tasks, particularly in remote locations. Large-scale infrastructure projects, such as rural broadband expansion, rely on the sustained power output of diesel engines.
- Mechanical:Mechanical trenchers feature direct power transfer systems, often simpler in design and operation. These are typically found in smaller, less complex trenching applications.
- Electric:Electric trenchers are powered by batteries or direct grid connections, offering zero emissions and reduced noise levels. They are increasingly adopted in urban areas with strict environmental regulations.
- Pneumatic:Pneumatic trenchers operate using compressed air, often for specialized tasks like breaking through compacted soil or rock in confined spaces. Their use is niche for specific ground conditions.
Diesel-Powered technologies currently dominate the market volume, while Electric trenchers are on the steepest expansion trajectory.
Application:
The application segmentation delineates demand based on specific project objectives and the diverse operational environments encountered by contractors.
- Utility Installation:This segment involves digging trenches for essential services like water, sewer, gas, and electrical lines in both urban and rural settings. Infrastructure modernization projects across the United States and Europe drive consistent demand for this application.
- Cable Laying:Cable laying specifically targets the precise excavation required for installing fiber optic, electrical, and telecommunication cables. The global rollout of 5G networks and fiber-to-the-home initiatives by telecommunications companies fuels significant demand in this area.
- Pipeline Construction:Pipeline construction applications require trenchers capable of creating large-diameter trenches for oil, gas, and water transmission lines. These projects are often large-scale and span long distances.
- Irrigation:Agricultural contractors use trenchers for installing and maintaining irrigation and drainage systems in farming operations. Precision agriculture techniques are increasing the need for these systems.
- Road Construction:Trenchers are utilized in road construction for preparing sub-surfaces and installing utilities alongside or underneath new roadways. This application supports broader transportation infrastructure development.
Utility Installation forms the foundational demand, with Cable Laying applications gaining share fastest.
End User:
The end-user segmentation reveals distinct purchasing patterns influenced by project scale, operational budgets, and specialized equipment requirements.
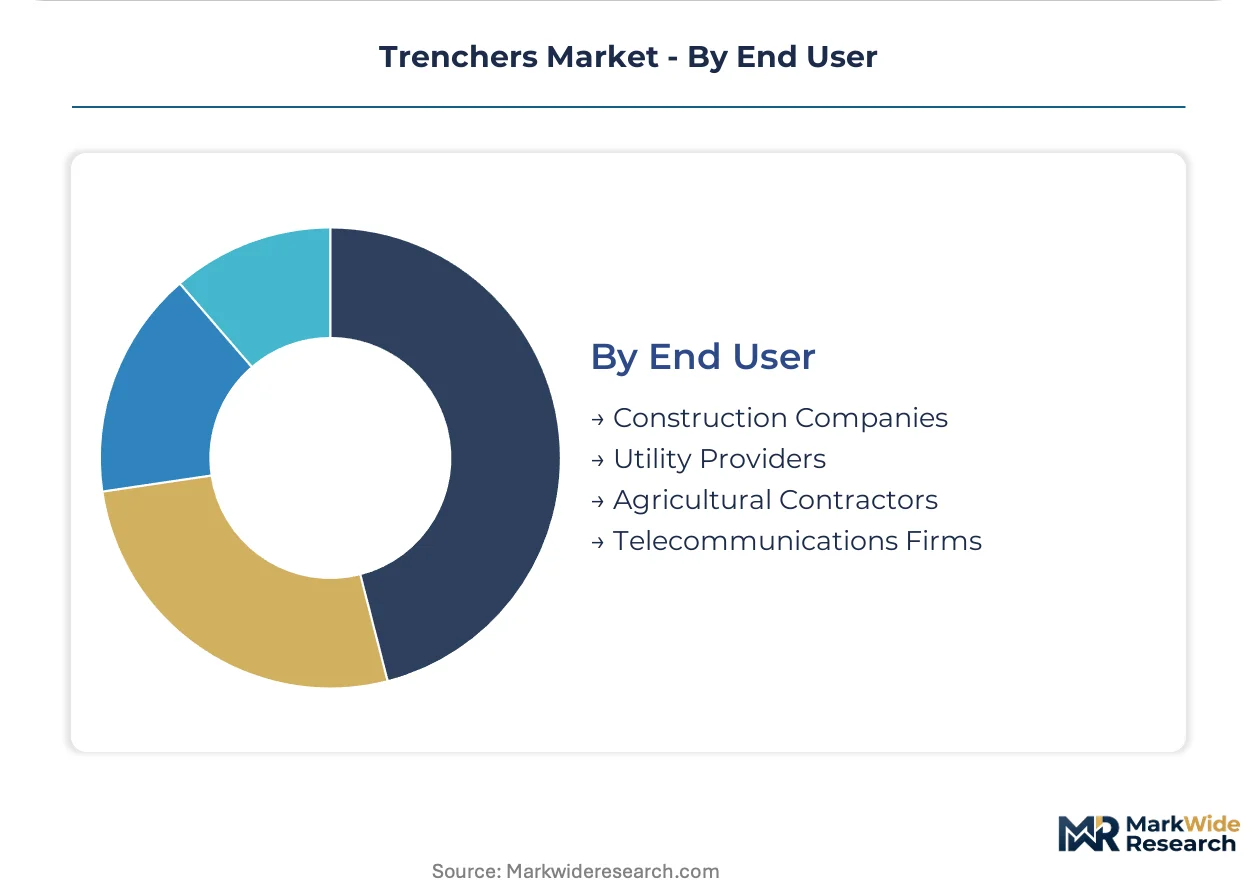
- Construction Companies:This broad category includes general contractors involved in residential, commercial, and large-scale infrastructure projects. Their demand for trenchers spans a wide range of sizes and capabilities to address diverse excavation needs.
- Telecommunications Firms:These companies specialize in deploying and maintaining communication networks, including fiber optic and 5G infrastructure. They require high-precision micro trenchers for efficient cable laying in densely populated areas and remote regions.
- Utility Providers:Electric, gas, and water utility companies utilize trenchers for installing new lines and maintaining existing infrastructure. Their procurement often focuses on reliability and compliance with safety regulations.
- Agricultural Contractors:These contractors serve the farming sector, using trenchers for installing drainage systems, irrigation lines, and other land management infrastructure. Their equipment needs are often tied to seasonal agricultural cycles.
Construction Companies represent the largest end-user group, while Telecommunications Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of trenching equipment concentrates in established industrial economies, while consumption is increasingly driven by emerging markets. This dynamic is shaped by diverse infrastructure demands, from rural broadband expansion to urban utility upgrades. Governments worldwide are investing heavily in digital and physical infrastructure.
United States
Demand for trenchers in the United States stems from extensive rural broadband expansion and utility modernization projects. The EPA's Tier 4 standards influence equipment design and procurement for construction companies. Major infrastructure hubs like Texas and Florida are seeing sustained trenching activity for new developments.
Germany
European demand for trenchers, especially electric models, is strong in Germany due to strict environmental regulations. The EU's Stage V requirements mandate advanced exhaust after-treatment systems for diesel-powered machines. Urban centers like Berlin and Munich prioritize low-noise, zero-emission equipment for city projects.
India
India's trenchers market is propelled by massive government infrastructure spending on rural connectivity and pipeline networks. Public funding initiatives support extensive fiber optic deployment and utility installation across diverse regions. The country's national broadband mission drives demand for efficient excavation machinery in states like Maharashtra.
Vietnam
Rapid infrastructure development in Vietnam creates significant demand for trenching equipment, particularly for telecommunications and utility projects. Government programs support the build-out of new communication networks and modern irrigation systems. Cities like Hanoi and Ho Chi Minh City require micro trenchers for dense urban fiber deployment.
Brazil
Brazil's trenchers market benefits from ongoing investments in utility infrastructure and agricultural modernization. National development plans aim to expand access to clean water and improve irrigation systems in rural areas. Key agricultural regions, including Mato Grosso, utilize trenchers for extensive drainage and irrigation channel construction.
Trenchers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the trenchers market, creating a dynamic competitive environment. The industry exhibits a tiered structure, with established manufacturers offering broad equipment portfolios alongside niche players targeting specific applications like micro-trenching. Strategic archetypes include heavy equipment generalists, utility-focused providers, and specialized rock trenching experts. Manufacturers often engage in portfolio diversification and geographic expansion to capture new project opportunities and address evolving customer needs.
Specialists in high-powered excavation, such as Tesmec S.p.A., exemplify the focus on challenging rock trenching projects with their robust, purpose-built machines. Alongside them, Vermeer Corporation represents a heavy equipment generalist, offering a broad portfolio spanning multiple equipment sizes and applications for diverse contractors. Ditch Witch, a prominent utility-focused provider, leverages its established distribution network to serve critical utility contractor segments, particularly for cable laying and pipeline construction. These companies collectively illustrate the varied approaches to market penetration and customer engagement within the industry, from niche specialization to broad-line offerings.
| Leading Market Players |
|---|
| Vermeer Corporation |
| Ditch Witch |
| Tesmec S.p.A. |
| Wolfe Heavy Equipment |
| Barreto Manufacturing, Inc. |
| EZ-Trench, LLC |
| Mastenbroek Limited |
| Guntert & Zimmerman |
| Toro Company |
| Others |
Cost & Logistics Intelligence
Equipment electrification, driven by environmental regulations, simultaneously reshapes cost economics and introduces new supply concentration points for specialized components. This shift impacts overall equipment pricing and the sourcing strategies of manufacturers.
Pricing Analysis
Cost-down pressure on standard chain trenchers accelerates because of intense competition and the modularization of digging components. The market typically employs per-unit transactional and project-based pricing models, with price differentiation driven by customization for specific soil types and comprehensive after-sales service. Small-to-medium-sized contractors exhibit the highest price sensitivity for general-purpose equipment. Telecommunications firms, however, show lower price sensitivity for specialized micro trenchers due to precise project requirements.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming more common among major trencher manufacturers to mitigate risk. The supply chain for trenching equipment is concentrated in industrial economies like Germany, the United States, and Italy. Production relies heavily on high-strength steel for cutting elements and advanced hydraulic systems. Commodity price volatility, particularly for steel, presents a significant structural risk. Distribution runs primarily through established dealer networks and specialized equipment rental companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trenchers market presents as a supply-constrained story, particularly for specialized high-horsepower equipment. Manufacturing capacity for advanced diesel engines, impacted by stringent emission regulations, forms a key bottleneck propping equipment pricing.
For Market Incumbents: Lock in long-term supply agreements for critical components, especially advanced hydraulic systems and electric drivetrain elements. Invest heavily in electrification R&D to counter the threat from stringent emission regulations and alternative excavation technologies. Expanding rental fleet offerings through established dealer networks provides a crucial lever against high capital investment barriers for smaller contractors. Maintain strong channel control to ensure consistent after-sales service. For New Entrants and Emerging Players: Launch via direct-to-customer models, focusing on specialized micro trenchers for dense urban fiber optic deployment. Target underpenetrated emerging economies across Africa and Latin America, where basic utility and communication networks are being built out. Offering modular, adaptable equipment platforms with strong technical support can overcome established brand loyalty. Focus on electric models for urban centers with strict noise and emission regulations. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers, particularly those developing electric or autonomous trenching solutions. The market exhibits long-term viability, driven by sustained global infrastructure development over the next 5-10 years. Target niche players with proprietary technology in micro trenching or advanced rock excavation. A crucial signal to watch is the consistent allocation of government funding for rural broadband and green utility infrastructure projects.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification R&D Acceleration | Reduces operational emissions and noise, expanding market access in regulated urban environments. |
| Advanced Telematics Integration | Optimizes fleet management and predictive maintenance, enhancing equipment uptime for contractors. |
| Modular Component Design | Repositions buyer preference toward versatile equipment platforms adaptable to diverse soil conditions. |
| Expansion of Rental Networks | Lowers capital investment barriers for small-to-medium contractors, increasing market accessibility. |
| Micro Trencher Production Scale-Up | Addresses the specific, high-volume demand from telecommunications firms for fiber optic cable laying. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for the analysis. Primary insights were gathered through interviews with trenching equipment engineers, utility procurement managers, construction project leads, and rental fleet operators. This approach combined bottom-up market sizing with top-down validation against industry reports and manufacturer disclosures. Data from EPA Tier 4 standards and EU Stage V requirements also informed the regulatory landscape.
Market volume and value were modeled at granular levels across product type, technology, application, end-user, and key country-level demand. Compound Annual Growth Rates were derived from historical data and projected growth drivers, including fiber optic deployment rates and government infrastructure spending. This framework assessed segments like micro trenchers for telecommunications and electric models for urban utility installation across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for autonomous trenching solutions would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory enforcement. Deviation in government infrastructure spending would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete Mixer Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Construction Helmet Market
Construction Equipment
United States Crane Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Global Scaffolding Market