
 Asia-Pacific Mobile Light Tower Market | 2026-2036
Asia-Pacific Mobile Light Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mobile Light Tower Market Insights
Mining contractors and infrastructure developers is bifurcating the Asia-Pacific mobile light tower demand pool, with resource extraction firms prioritizing ruggedized diesel-hybrid units for off-grid deployment while urban construction buyers favor electric and solar alternatives. Atlas Copco leverages its compressor and power equipment distribution network to dominate Australia's Pilbara mining belt. Doosan anchors Korean and Southeast Asian markets through integrated engine-manufacturing scale. Changsha Skyboom Heavy Industry competes aggressively on trailer-mounted configurations for China's domestic roadbuilding programs.
Asia-Pacific mobile light towers are self-contained illumination systems, typically comprising a telescopic mast extending 7-9 meters, a generator or battery pack, and an array of lamps producing 4,000 to 12,000 square meters of coverage, designed for temporary deployment where grid power remains unavailable. The LED light tower segment leads value generation due to lumen-per-watt efficiency and reduced fuel consumption, while the solar light tower category posts the fastest trajectory as photovoltaic costs decline and battery energy density improves. Towable mounting configurations capture the dominant volume share across mining and emergency services applications, though trailer-mounted units command premium positioning in event management and precision industrial maintenance settings.
Australia's diesel-emission standards under the National Clean Air Agreement, India's BIS appliance-efficiency labeling rules, and China's GB standards for construction machinery emissions collectively reshape product certification requirements and import eligibility across the region. TRAI's remote-area telecom infrastructure mandates in India indirectly stimulate tower demand for cellular base station construction in unelectrified zones. Stakeholders must monitor regulatory divergence between Australia's stringent carbon-border considerations and Southeast Asia's fragmented enforcement to calibrate regional product portfolios and service-network investments.
Market Dynamics
Asia-Pacific mobile light tower demand is bifurcating along energy-source lines, with diesel-hybrid units dominating Australia's Pilbara mining corridors while solar-electric configurations capture India's highway construction zones. This divergence is compressing manufacturer product cycles and forcing dual-certification strategies across BIS, TGA, and GB standards regimes.
Growth Catalysts
- TRAI Telecom Mandates:India's remote-area cellular infrastructure rollout requires temporary illumination for unelectrified base station construction, creating dedicated demand for towable solar units in Rajasthan and Madhya Pradesh.
- Australia's National Clean Air Agreement:Diesel-emission standards are forcing mining contractors to replace legacy fleets with Tier 4 Final-compliant hybrids, accelerating replacement cycles in Western Australia's iron ore districts.
- LED Lumen Efficiency:Solid-state lighting now delivers 150+ lumens per watt, cutting fuel consumption by 40% versus metal halide and extending runtime for off-grid deployments.
Market Restraints
- Lithium Battery Supply Concentration:Cell production concentrates in China's Fujian and Jiangsu provinces, exposing non-Chinese assemblers to raw material cost volatility and export license delays.
- Diesel Price Volatility:Australia's remote fuel logistics add 35-50% to delivered diesel costs versus coastal benchmarks, eroding total-cost-of-ownership advantages for conventional units.
- Photovoltaic Output Variability:Monsoon patterns across Southeast Asia reduce solar tower effective capacity factors to 45-55% during wet seasons, limiting year-round deployment reliability.
Strategic Opportunities
- Vietnam's Power Development Plan:Grid extension lags in the Central Highlands create 3-5 year windows for rental fleet deployment at hydropower and wind construction sites.
- Battery-Solar Convergence:Lithium iron phosphate packs paired with bifacial panels are opening 24-hour illumination contracts previously reserved for diesel units.
- Indonesia's Trans-Java Toll Road:Night-shift paving mandates across 1,000+ kilometers of new highway are generating concentrated demand for trailer-mounted LED towers with 9-meter masts.
Industry Challenges
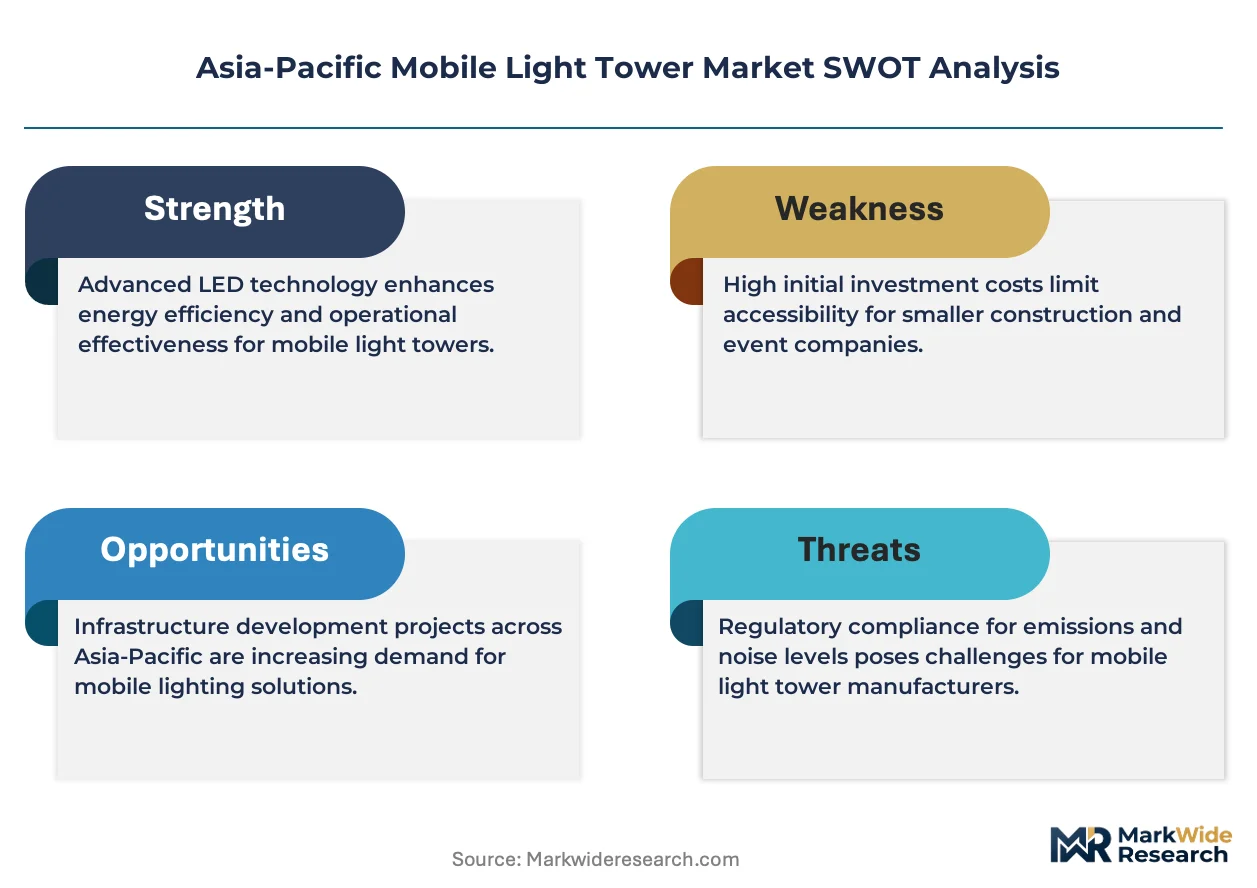
- Multi-Jurisdiction Certification:Manufacturers must simultaneously satisfy Australia's TGA electrical safety, India's BIS appliance labeling, and China's GB construction machinery standards, extending product launch timelines by 8-14 months.
- Telescopic Mast Hydraulics Expertise:The region lacks sufficient technicians trained in 7-9 meter pneumatic and hydraulic mast maintenance, forcing OEMs to embed field service teams or sacrifice uptime guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mobile Light Tower Market |
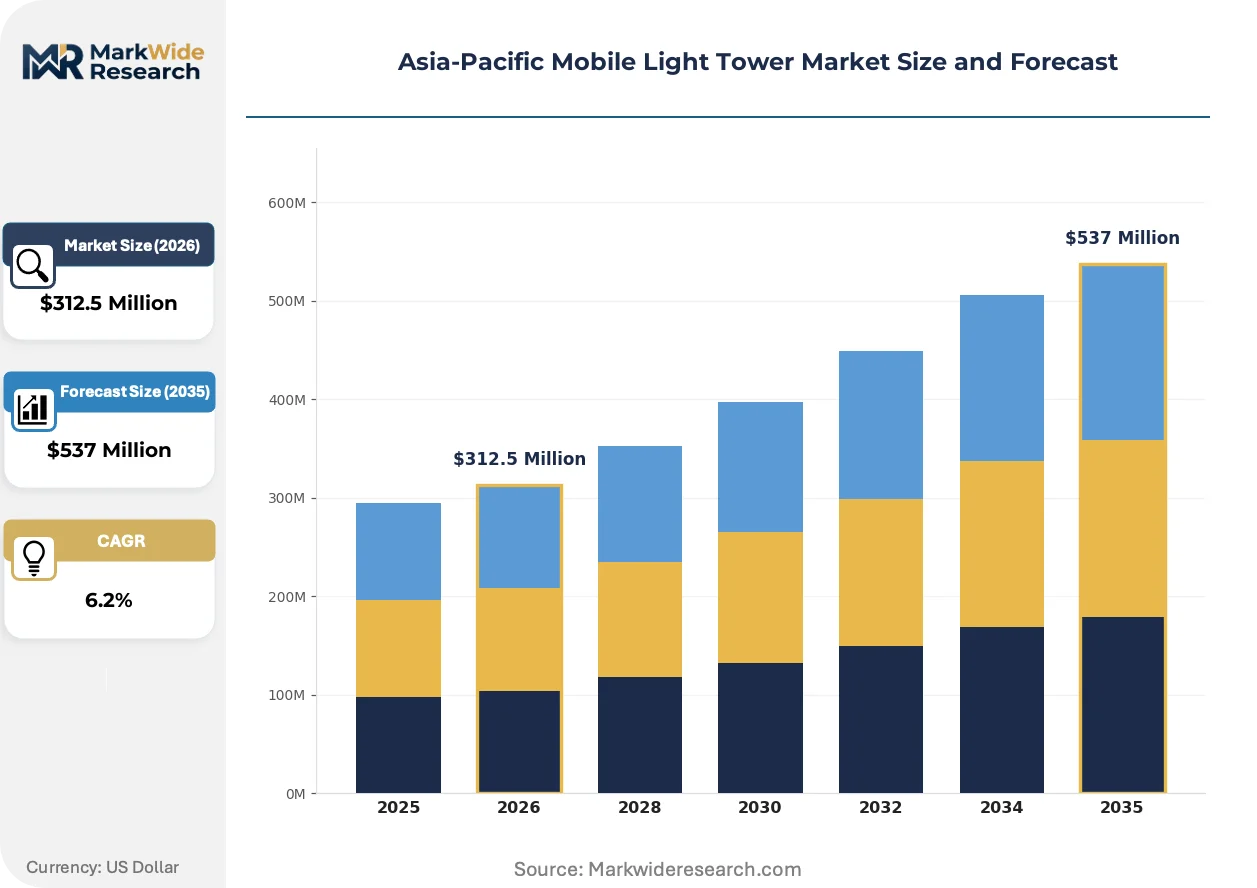
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $537 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Light Tower, Halogen Light Tower, Hybrid Light Tower, Solar Light Tower Application: Construction Sites, Event Management, Emergency Services, Industrial Maintenance Power Source: Diesel, Electric, Solar, Hybrid Mounting Type: Stationary, Mobile, Towable, Trailer-mounted |
| Companies Covered | Doosan, Allmand Bros, Atlas Copco, Himoinsa, JCB, Generac, Wacker Neuson, Changsha Skyboom Heavy Industry, Terex, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mobile Light Tower Market Trends and Innovations
Product architecture is fragmenting as modular battery packs and swappable lamp heads replace integrated monolithic designs. This shift enables rental fleet operators to configure units for specific job durations and illumination footprints without full asset replacement.
Solid-state LED arrays with integrated motion sensors are decomposing the traditional diesel-generator-plus-fixed-lamp architecture. Australian mining contractors are deploying these units at 400% the pace of three years prior. The technology is compressing fuel logistics costs and enabling autonomous operation without on-site attendants.
India's BIS energy-efficiency labeling rules now mandate lumens-per-watt disclosure and standby power limits for imported lighting equipment. Manufacturers must redesign driver electronics and thermal management to maintain import eligibility. The LED tower segment is responding fastest, with domestic assemblers in Pune and Chennai accelerating certification timelines.
Rental and leasing models are displacing outright purchase across Southeast Asian construction markets. Equipment lessors in Thailand and Malaysia now bundle transport, fuel, and maintenance into per-day rates, capturing mid-tier contractors who lack capital for fleet ownership. India's National Highways Authority contracts represent the most visible application of this shift, with 60% of recent tenders specifying rental-only provisions.
Asia-Pacific Mobile Light Tower Market Segmentation
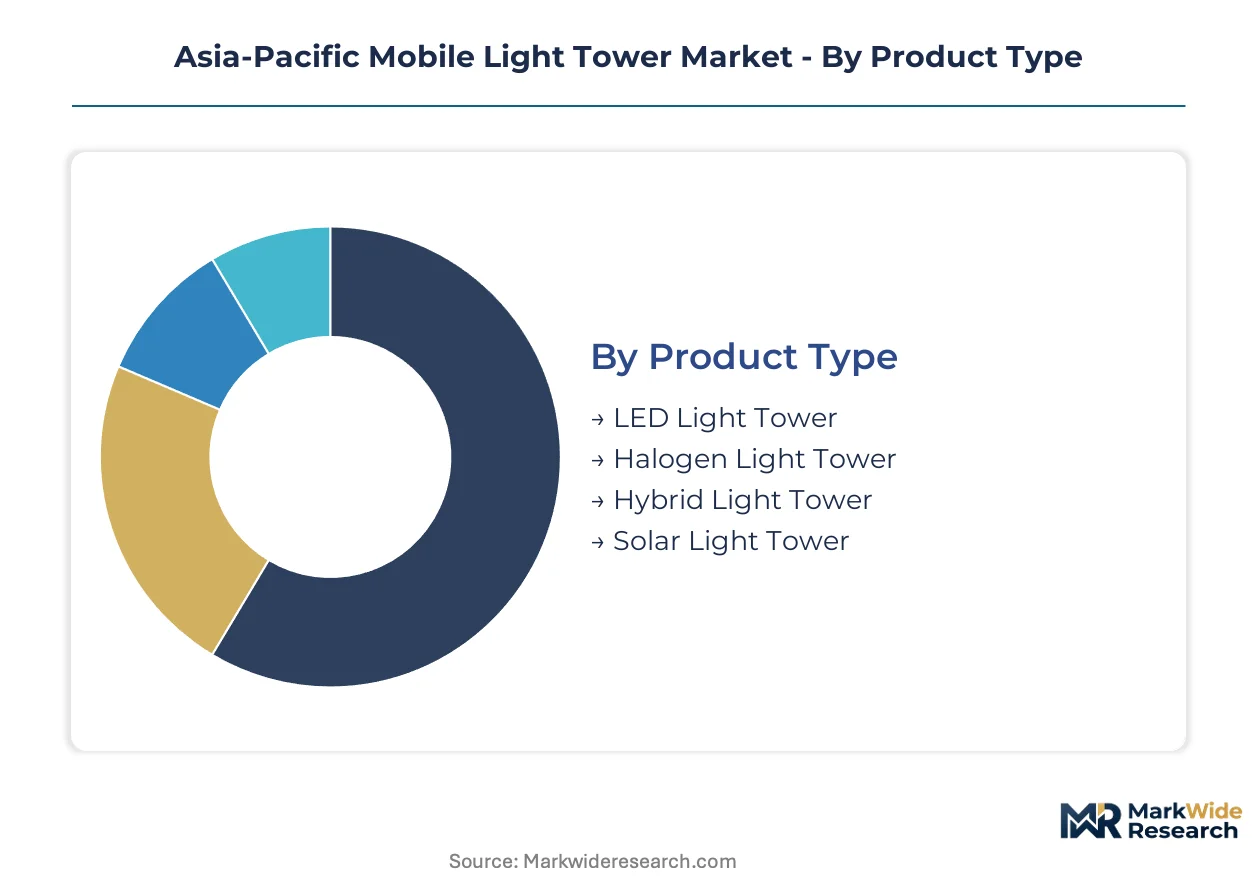
Segmentation in the Asia-Pacific mobile light tower market reveals how regulatory pressure and terrain constraints fragment procurement patterns across mining, construction, and emergency response verticals. Buyers optimize for fuel logistics, mast mobility, and illumination duration rather than upfront capital cost alone.
Product Type:
Regulatory differentiation across Australia's TGA electrical safety, India's BIS appliance-efficiency labeling, and China's GB construction machinery standards forces manufacturers to maintain parallel certification tracks for each technology variant.
- LED Light Tower:Solid-state arrays delivering 150+ lumens per watt with integrated thermal management and driver electronics redesigned for BIS standby power limits. Australia's Pilbara mining contractors and India's National Highways Authority specify these units for 40% fuel reduction versus metal halide predecessors.
- Solar Light Tower:Bifacial photovoltaic panels paired with lithium iron phosphate battery packs enabling 24-hour illumination contracts. Demand concentrates in Rajasthan and Madhya Pradesh cellular base station construction under TRAI remote-area mandates, though monsoon capacity factors in Southeast Asia constrain year-round deployment.
- Hybrid Light Tower:Diesel-electric architectures with automatic load-following generators and battery buffers for transient demand spikes.
- Halogen Light Tower:Legacy metal halide technology persisting in price-sensitive rental fleets and short-duration event applications.
Established volume favors LED configurations; emerging adoption favors solar-electric systems.
Application:
Cost tier stratification separates capital-intensive mining procurement from operational-expense-driven construction rental models.
- Construction Sites:Night-shift paving mandates across Indonesia's Trans-Java Toll Road and India's highway expansion generate concentrated demand for trailer-mounted LED towers with 9-meter masts. Contractors favor rental bundling that wraps transport, fuel, and maintenance into per-day rates.
- Emergency Services:Rapid-deployment towable units with pneumatic mast extension for disaster response and grid restoration. Australian state emergency services prioritize Tier 4 Final diesel compliance under National Clean Air Agreement timelines.
- Event Management:Low-noise electric and solar configurations for stadium and festival illumination where attendee experience constraints override runtime requirements.
- Industrial Maintenance:Precision lighting for refinery turnarounds and power plant outages requiring explosion-proof certifications and adjustable color temperature.
Construction sites absorb the highest unit volumes; emergency services command the most stringent certification premiums.
Power Source:
Supply concentration in China's Fujian and Jiangsu battery cell production exposes non-Chinese assemblers to raw material cost volatility and export license delays.
- Diesel:Remote fuel logistics in Western Australia's iron ore districts add 35-50% to delivered costs versus coastal benchmarks, eroding total-cost-of-ownership advantages despite Tier 4 Final compliance investments.
- Solar:Photovoltaic cost declines and battery energy density improvements are opening 24-hour contracts previously reserved for diesel units. Vietnam's Central Highlands hydropower construction sites represent a 3-5 year deployment window before grid extension arrives.
- Electric:Grid-tethered or battery-buffered systems for urban construction with reliable power infrastructure.
- Hybrid:Automatic switching between diesel generation and battery discharge based on load profiles and fuel availability.
Diesel retains dominance in off-grid mining corridors; solar-electric configurations are gaining share fastest in highway construction zones.
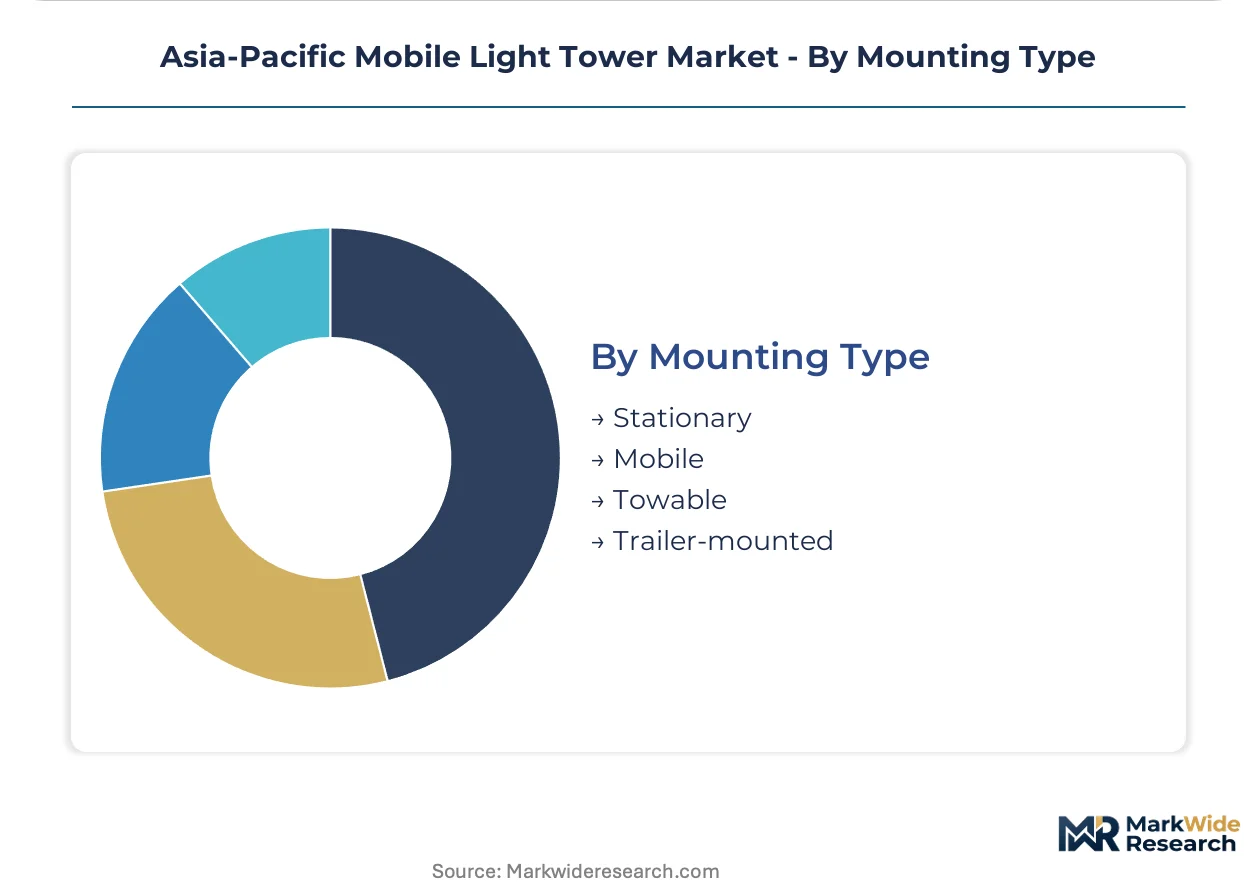
Mounting Type:
Customer type bifurcation separates rental fleet operators seeking transport efficiency from event managers prioritizing rapid site repositioning.
- Towable:Hitch-mounted configurations with integrated braking and lighting for highway-legal transport. Mining and emergency services applications dominate volume, with Australia's Pilbara rental fleets standardizing on this format for site-to-site mobility.
- Trailer-mounted:Heavy-duty chassis with stabilizing outriggers and 9-meter pneumatic mast extension. Indonesia's toll road contractors and India's precision industrial maintenance buyers pay premiums for repositioning speed without crane assistance.
- Mobile:Skid or wheel-mounted units for confined construction sites with limited access roads.
- Stationary:Fixed-installation towers for semi-permanent infrastructure like cellular base stations and border checkpoints.
Towable formats capture the dominant fleet share; trailer-mounted units command premium positioning in event and precision maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Fujian provinces concentrate lithium battery cell production, exposing regional assemblers to raw material cost volatility and export licensing delays. This supply-side dominance shapes procurement patterns across Asia-Pacific mining and construction corridors.
Australia
Western Australia's Pilbara iron ore districts drive demand for Tier 4 Final-compliant diesel-hybrid towers under the National Clean Air Agreement. TGA electrical safety certification governs import eligibility. Perth-based rental fleets standardize on towable configurations for site-to-site mobility across remote mining tenements.
India
Rajasthan and Madhya Pradesh cellular base station construction generates concentrated solar tower demand under TRAI remote-area mandates. BIS appliance-efficiency labeling rules mandate lumens-per-watt disclosure and standby power limits. Pune and Chennai domestic assemblers accelerate certification timelines for LED driver electronics.
Indonesia
Night-shift paving mandates across the Trans-Java Toll Road create sustained demand for trailer-mounted LED towers with 9-meter pneumatic masts. The country's energy ministry promotes hybrid power systems for infrastructure projects. Jakarta-based contractors favor rental bundling that wraps transport and maintenance into per-day rates.
Vietnam
Central Highlands hydropower and wind construction sites present 3-5 year deployment windows before grid extension arrives. The Power Development Plan VII delays transmission infrastructure in mountainous provinces. Da Nang equipment lessors position solar-electric fleets for renewable energy construction contracts.
South Korea
Doosan's integrated engine-manufacturing scale anchors domestic and Southeast Asian market penetration. MFDS industrial equipment standards and KOSHA safety certifications shape product specifications. Busan-Ulsan shipbuilding maintenance yards generate steady demand for explosion-proof precision lighting systems.
Asia-Pacific Mobile Light Tower Market Competitive Landscape
Concentration sits with diversified industrial equipment conglomerates possessing captive engine manufacturing or compressor distribution networks. The vendor base stratifies across three tiers: premium OEMs with full-service rental capabilities, mid-market fabricators competing on trailer-mounted configurations, and regional assemblers serving price-sensitive domestic construction programs. Dominant competitive moves include backward integration into lithium battery pack assembly and geographic expansion through distributor acquisition in Southeast Asian growth corridors.
Among Asia-Pacific-based fabricators, Changsha Skyboom Heavy Industry exemplifies the mid-market trailer-mounted specialist archetype, while Doosan and Atlas Copco occupy positions at the scale-driven end with integrated power equipment portfolios. Doosan's Korean manufacturing base represents conglomerate diversification into mobile power systems, whereas Atlas Copco leverages compressor and power equipment distribution density across Australia's mining belts. These three anchors illustrate how technology certification breadth and field service network density separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Doosan |
| Allmand Bros |
| Atlas Copco |
| Himoinsa |
| JCB |
| Generac |
| Wacker Neuson |
| Changsha Skyboom Heavy Industry |
| Terex |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lithium battery cell lead times from China's Fujian and Jiangsu provinces compress pricing power toward downstream assemblers while amplifying cost pass-through volatility for non-Chinese manufacturers seeking alternative sourcing. This inventory-to-pricing dynamic concentrates margin pressure on mid-tier fabricators lacking captive cell production or strategic stockpile arrangements.
Pricing Analysis
Australia's National Clean Air Agreement dictates the pricing tier structure across the Asia-Pacific mobile light tower market, separating Tier 4 Final-compliant diesel-hybrid premiums from standard-configuration economy units. Pricing stratifies across premium certification-grade equipment for Pilbara mining contractors, standard LED configurations for Indian highway rental fleets, and economy halogen towers for short-duration event applications. Cost compression in the standard tier is intensifying because lithium iron phosphate pack costs fluctuate with Chinese export licensing delays. Indian construction contractors exhibit highest price sensitivity, while Australian mining procurement teams prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy among Australian rental fleet operators buffering against Western Australia remote fuel logistics, while Indian and Southeast Asian buyers favor just-in-time procurement from Shenzhen and Guangzhou component hubs. Battery cell production centers on China's Fujian and Jiangsu provinces, with South Korean cathode material processing and Australian lithium spodumene extraction completing the upstream chain. Supply chain risk concentrates in single-source vulnerability for lithium iron phosphate cells subject to export license delays. Distribution runs through Perth-based mining equipment lessors, Jakarta toll road contractors, and Indian National Highways Authority rental aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific mobile light tower market represents a high-growth disruption as LED lumen efficiency and battery-solar convergence displace legacy diesel-generator architectures, with India's BIS energy-efficiency mandates and Australia's National Clean Air Agreement forcing technology transitions across procurement pools.
For Market Incumbents: Compound field service network density across Australia's Pilbara mining corridors and Indonesia's Trans-Java Toll Road to defend against mid-tier trailer-mounted specialists. Backward integration into lithium battery pack assembly in South Korea or Thailand reduces exposure to Chinese export licensing volatility. Certification breadth across TGA, BIS, and GB standards regimes extends competitive moats against regional assemblers. For New Entrants and Emerging Players: BIS fast-track certification for LED driver electronics opens immediate access to India's National Highways Authority rental-only tenders. Vietnam's Central Highlands hydropower construction window presents the most penetrable geography before grid extension arrives under Power Development Plan VII. Partner with Da Nang equipment lessors for solar-electric fleet deployment rather than direct sales to capital-constrained contractors. For Investors and Strategic Acquirers: Long-term, this sits as a rental-fleet consolidation play because asset-heavy operators with integrated maintenance capabilities capture recurring revenue streams as construction markets shift from purchase to leasing models. Target mid-tier trailer-mounted specialists with established Indonesian or Vietnamese distributor relationships. Watch lithium iron phosphate cell cost curves as the inflection signal determining solar-electric share capture versus diesel-hybrid persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive lithium iron phosphate production insulates against Chinese export licensing delays and raw material volatility. |
| Multi-Jurisdiction Certification Investment | Parallel TGA, BIS, and GB compliance accelerates product launches across Australian mining and Indian highway procurement pools. |
| Rental Fleet Network Expansion | Perth and Jakarta-based service density captures recurring revenue as National Highways Authority tenders specify rental-only provisions. |
| Solar-Electric Product Line Development | Bifacial panel and battery convergence opens 24-hour illumination contracts previously reserved for diesel units in Vietnam's Central Highlands. |
| Field Service Team Embedding | Technician deployment for 7-9 meter pneumatic mast maintenance defends uptime guarantees against regional capability scarcity. |
Research Methodology
Cross-validation between regulatory filing analysis and equipment procurement database records anchors the qualitative findings across the Asia-Pacific mobile light tower market. Primary interviews with mining maintenance directors, highway construction procurement leads, rental fleet operators, and OEM aftermarket service heads combined with secondary validation from TGA electrical safety registrations, BIS appliance-efficiency labeling disclosures, and Australian Clean Air Agreement compliance records. Bottom-up unit shipment tallies and top-down market sizing triangulate volume estimates.
Sensitivity analysis around lithium battery cell cost trajectories and diesel price volatility bands frames the projection methodology across the analysis window. Segmentation dimensions modeled include power source architecture, mounting configuration mobility, application vertical, and regional regulatory cluster. CAGRs derive from weighted average technology transition rates and replacement cycle compression under emission standards. Forecast inputs incorporate TRAI remote-area infrastructure rollout pacing and Indonesia's Trans-Java Toll Road construction sequencing.
Decision-makers should treat outputs as directional under base assumptions of continued BIS, TGA, and GB regulatory divergence and stable lithium export licensing regimes from Chinese production hubs; material deviation would warrant model refresh. Revision becomes warranted when battery-solar convergence cost parity crosses threshold viability against Tier 4 Final diesel-hybrid economics in Australian mining procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
United States Crane Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Roadheaders Market
Construction Equipment
Crane Pumps Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Mini Excavators Market