
 Truck Mounted Knuckle Boom Cranes Market | 2026-2036
Truck Mounted Knuckle Boom Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Mounted Knuckle Boom Cranes Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote diagnostics platforms. Palfinger AG leverages its global dealer network to capture recurring service income across European and North American installed bases. XCMG Group anchors its competitive stance through manufacturing scale and captive supply of structural steel components. Hyva competes aggressively in the municipal and waste-collection segment with compact-mount crane configurations optimized for narrow urban corridors.
Truck mounted knuckle boom cranes are articulated lifting devices mounted on commercial vehicle chassis, typically offering payload capacities from one to over eighty metric tons with hydraulic or electric articulation systems enabling precise load placement in confined spaces. Their primary industrial purpose centers on material handling where conventional straight-boom cranes lack maneuverability, particularly in urban construction, utility maintenance, and forestry operations. Hydraulic cranes dominate current production volumes due to proven power density and established service infrastructure, while electric cranes represent the fastest-expanding segment as chassis electrification and zero-emission zone regulations reshape buyer specifications. Construction end users command the largest share of current demand, though telecommunications applications are gaining traction as 5G infrastructure deployment requires compact, highly maneuverable lifting equipment for cell tower component installation.
The EU Machinery Directive and CE marking requirements govern product safety and market access across European member states, while OSHA standards in the United States mandate operator certification and load stability protocols that influence crane control system design. China's GB standards and SAMR enforcement mechanisms establish domestic technical benchmarks that multinational manufacturers must satisfy for market participation. Stakeholders must monitor evolving battery-electric chassis compatibility standards and regional emissions regulations that will determine which powertrain configurations qualify for public-sector procurement contracts.
Market Dynamics
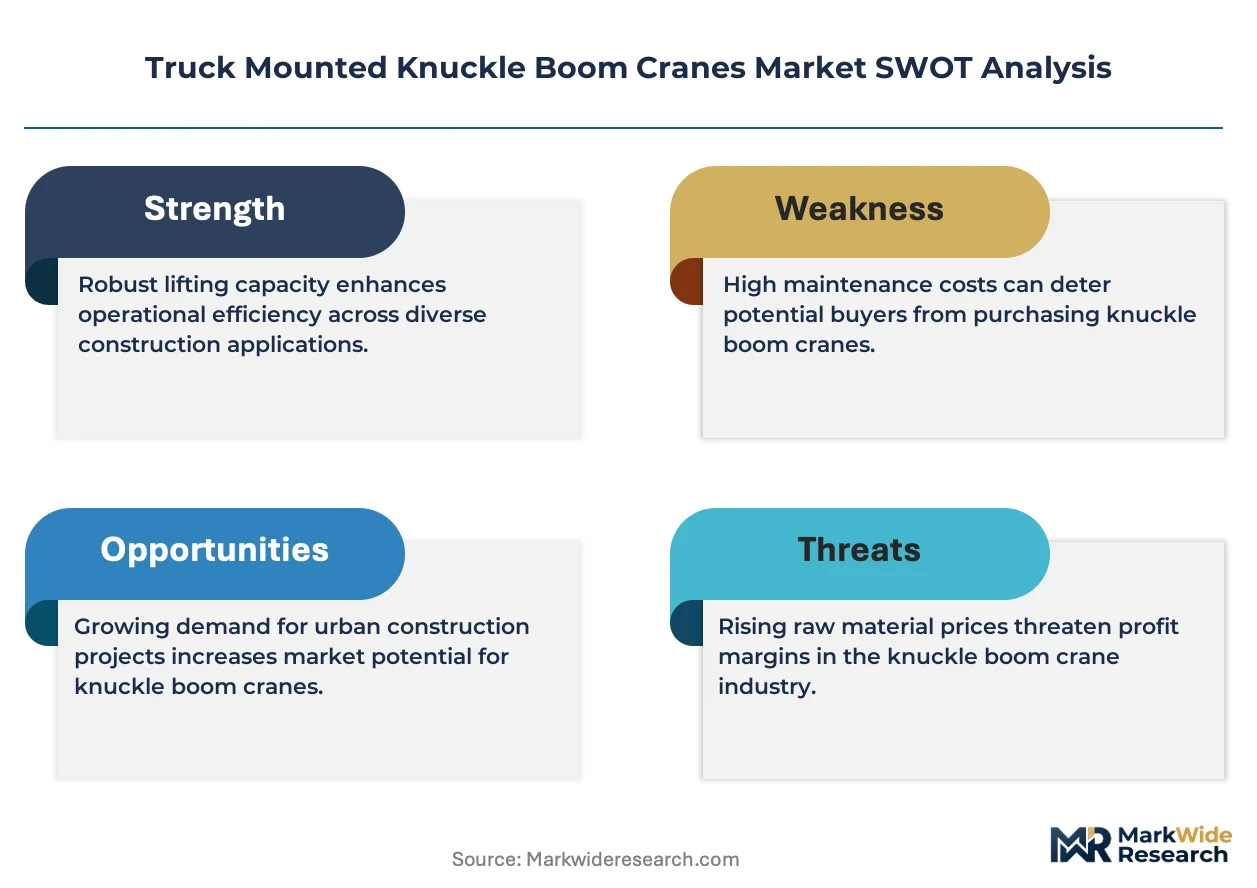
Chassis electrification mandates and battery-electric commercial vehicle rollouts are forcing crane manufacturers to redesign hydraulic power take-off systems and validate electric actuator architectures for zero-emission compatibility.
Growth Catalysts
- EU Machinery Directive updates:Revised CE marking requirements for crane stability control systems are accelerating replacement demand among European municipal fleets seeking compliant equipment.
- 5G telecommunications infrastructure:Cell tower densification programs in Germany, the United States, and China require compact knuckle boom configurations for component lifting in urban rights-of-way.
- Vegetation management contracts:North American utility operators are expanding roadside maintenance fleets to address wildfire mitigation mandates and grid reliability standards.
Market Restraints
- High-strength steel price volatility:Structural component costs fluctuate with scrap metal and alloy input markets, compressing fabrication margins for mid-tier manufacturers.
- Hydraulic component supply concentration:Precision valve and pump sourcing depends on a concentrated German and Italian supplier base, creating delivery risk during capacity constraints.
- Battery-electric chassis payload penalties:Current electric truck platforms sacrifice crane-mount capacity due to battery mass, limiting viable application segments.
Strategic Opportunities
- Indian infrastructure build-out:National highway expansion and smart city programs create first-time fleet procurement demand for utility-mounted lifting equipment.
- Predictive maintenance platforms:IoT-enabled load monitoring and hydraulic diagnostics enable recurring service revenue models beyond equipment sales.
- Forestry biomass harvesting:European renewable energy subsidies for wood chip and pellet production expand crane applications in mechanized logging operations.
Industry Challenges
- Certified operator scarcity:OSHA and national licensing requirements for knuckle boom crane operation create hiring bottlenecks for fleet expansion programs.
- Electric-hydraulic integration complexity:Battery-electric chassis powertrain interfaces require new control software validation, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Mounted Knuckle Boom Cranes Market |
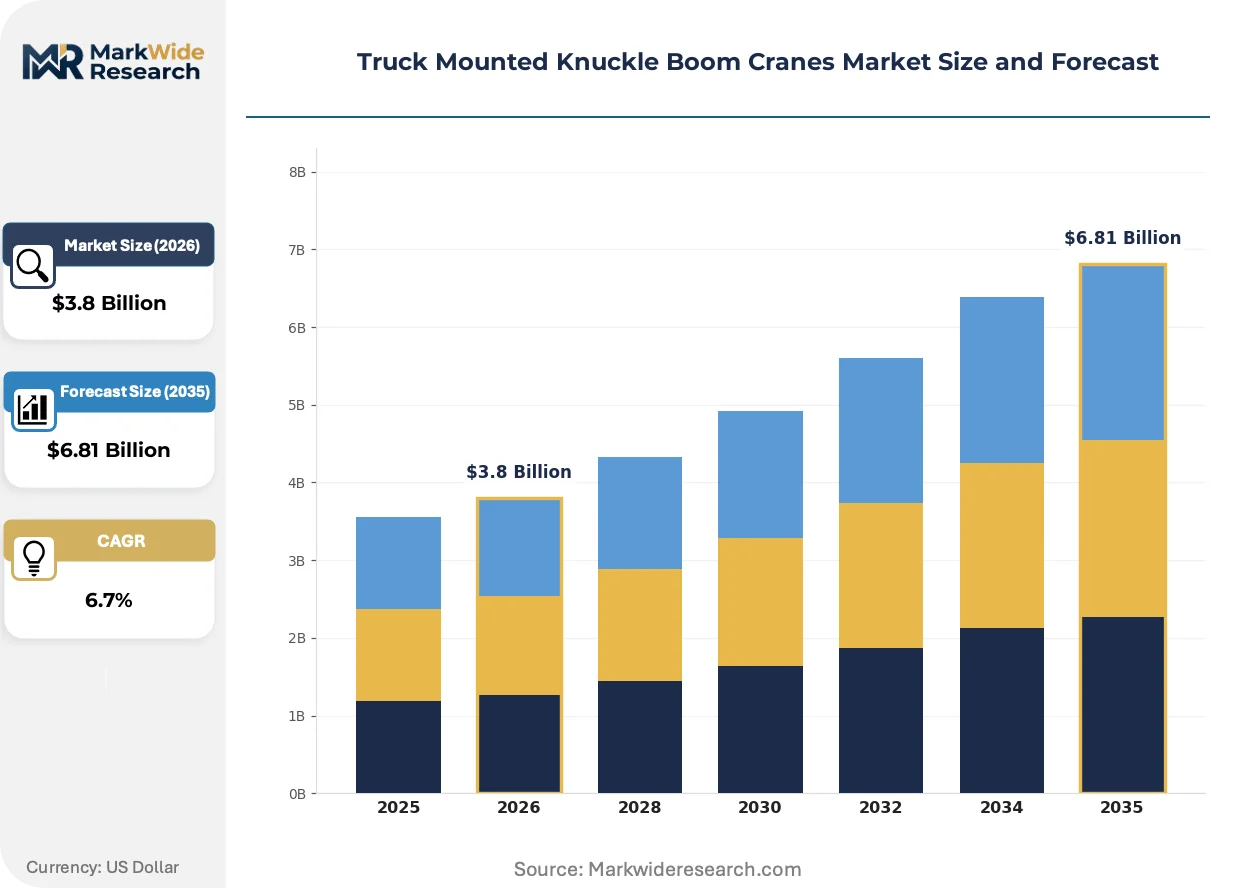
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Cranes, Electric Cranes, Pneumatic Cranes, Manual Cranes End User: Construction, Forestry, Oil & Gas, Telecommunications Application: Lifting, Loading, Unloading, Material Handling Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Hyva, Cargotec Corporation, Palfinger AG, Liebherr Group, XCMG Group, Fassi S.r.l., Terex Corporation, Manitex International, IMT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Mounted Knuckle Boom Cranes Market Evolving Landscape
Electrification architectures and digital service platforms are restructuring how crane manufacturers capture value, shifting competitive advantage from pure hardware specifications to integrated system performance and lifecycle support capabilities.
Electro-hydraulic hybrid actuation is collapsing the traditional separation between diesel-powered hydraulics and all-electric alternatives. Municipal procurement teams in Scandinavian cities are specifying these configurations for zero-emission zone compliance. The technology is collapsing service interval requirements and enabling remote diagnostic integration that pure hydraulic systems cannot support.
OSHA's updated crane operator certification standards are mandating simulator-based training and documented competency verification for load chart interpretation. Equipment purchasers now require control interfaces with embedded load moment limiters and automatic stability warnings. Construction and utility segments in the United States are prioritizing certified-compliant models to reduce liability exposure and insurance premiums.
Telematics-enabled usage-based service contracts are displacing traditional time-based maintenance schedules. Fleet managers in German municipal operations now specify remote monitoring capabilities as standard procurement criteria. Equipment distributors are restructuring service organizations around predictive intervention models rather than reactive repair dispatch.
Truck Mounted Knuckle Boom Cranes Market Segmentation
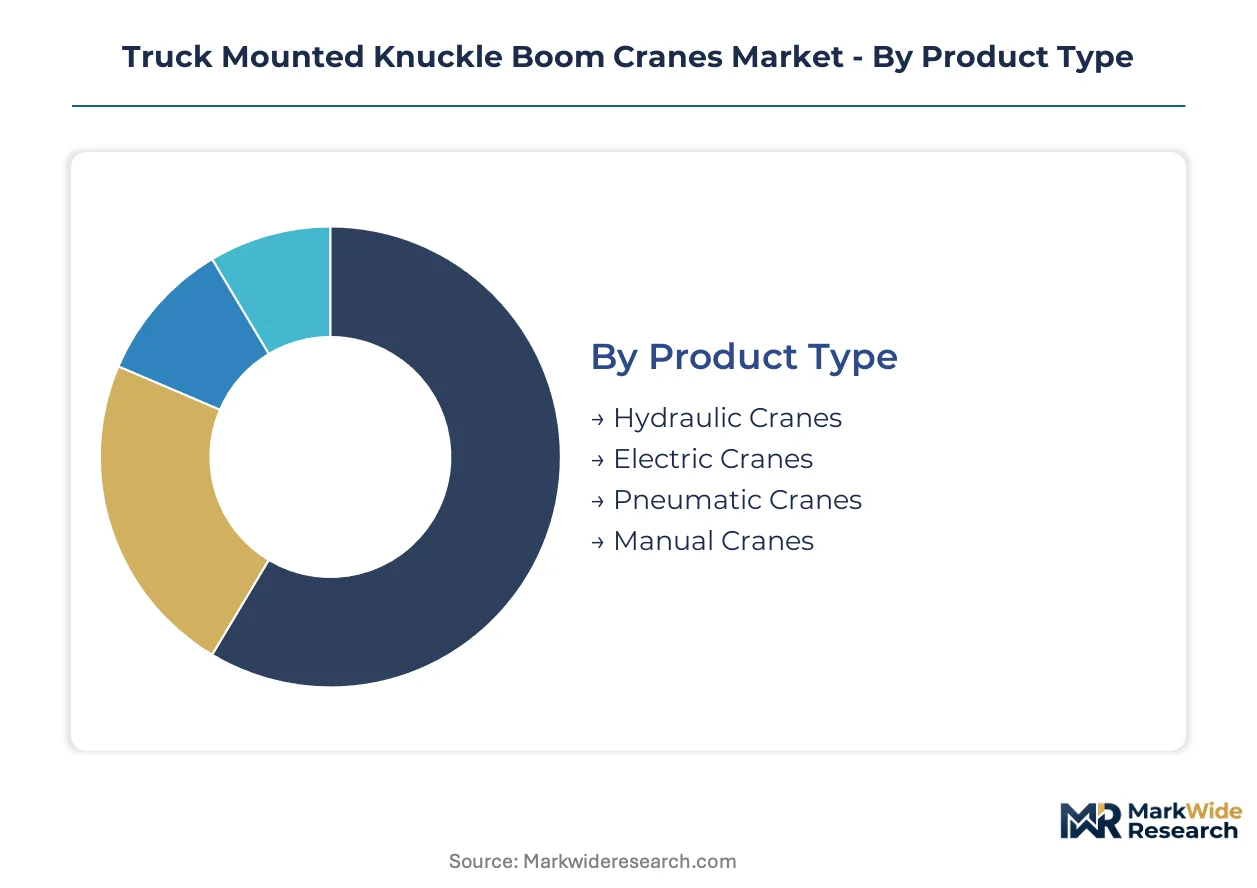
Segmentation in knuckle boom cranes determines aftermarket revenue intensity, with hydraulic systems commanding recurring service contracts and electric architectures shifting margin capture toward software-enabled diagnostics. Procurement patterns diverge sharply between municipal fleets prioritizing total cost of ownership and construction operators optimizing for lift capacity per chassis dollar.
Product Type:
After-sales service intensity varies dramatically across powertrain architectures, with hydraulic systems generating parts-heavy maintenance schedules and electric cranes enabling predictive intervention models.
- Hydraulic Cranes:These systems deploy high-pressure fluid circuits through articulated boom sections, delivering proven power density for loads exceeding fifty metric tons. Demand concentrates in German municipal utilities and North American construction rental fleets where established service infrastructure and technician certification pools reduce operational risk. Replacement part revenue and scheduled maintenance contracts sustain distributor profitability across decade-long equipment lifecycles.
- Electric Cranes:Battery-powered actuation eliminates hydraulic fluid maintenance while enabling zero-emission zone compliance in Scandinavian urban cores and Chinese port logistics hubs. Component sourcing concentrates on permanent magnet motor suppliers and power electronics vendors, reshaping traditional crane OEM supply relationships toward automotive-tier semiconductor procurement.
- Pneumatic Cranes:Compressed air systems serve explosion-sensitive environments in oil & gas extraction and chemical processing facilities where spark suppression mandates apply.
- Manual Cranes:Hand-cranked configurations address developing market budget constraints and specialized low-volume lifting in confined agricultural settings.
By volume, hydraulic cranes lead. By growth pace, electric configurations are expanding most quickly.
End User:
Customer procurement sophistication determines pricing realization, with telecommunications carriers accepting premium configurations for uptime-critical infrastructure deployment.
- Construction:General contractors and rental fleet operators specify load moment limiters and stability control systems to satisfy OSHA certification requirements and reduce insurance exposure. Demand clusters in United States urban corridor development and Chinese infrastructure renewal programs where chassis-mounted flexibility outperforms traditional tower crane economics.
- Telecommunications:5G cell tower densification drives compact-mount crane procurement for component lifting in congested urban rights-of-way across Germany, the United States, and China. Carriers prioritize rapid deployment capability and narrow corridor maneuverability over maximum lift capacity, accepting price premiums for sub-ten-meter outrigger span configurations.
- Forestry:Mechanized biomass harvesting operations in Nordic renewable energy supply chains deploy extended-reach configurations for log loading and chipper feeding.
- Oil & Gas:Remote extraction sites and pipeline maintenance crews require explosion-proof certifications and extreme temperature operational envelopes.
Construction commands the largest installed base. Telecommunications shows the steepest expansion trajectory.
Application:
Task-specific duty cycles influence component specification, with continuous loading operations demanding heavier boom construction than intermittent lifting.
- Lifting:Precision vertical displacement in confined spaces defines core knuckle boom functionality, with construction and utility segments specifying variable outreach control for overhead obstacle navigation.
- Loading:Repetitive material transfer operations in logistics and waste collection stress hydraulic system durability and drive fleet standardization around compatible quick-attach tooling.
- Unloading:Delivery truck applications prioritize rapid cycle times and single-operator control interfaces for urban distribution efficiency.
- Material Handling:General-purpose configurations balance reach, capacity, and weight for multi-task municipal fleet deployment.
Loading applications dominate fleet procurement volume. Lifting commands the highest specification premiums.
Distribution Channel:
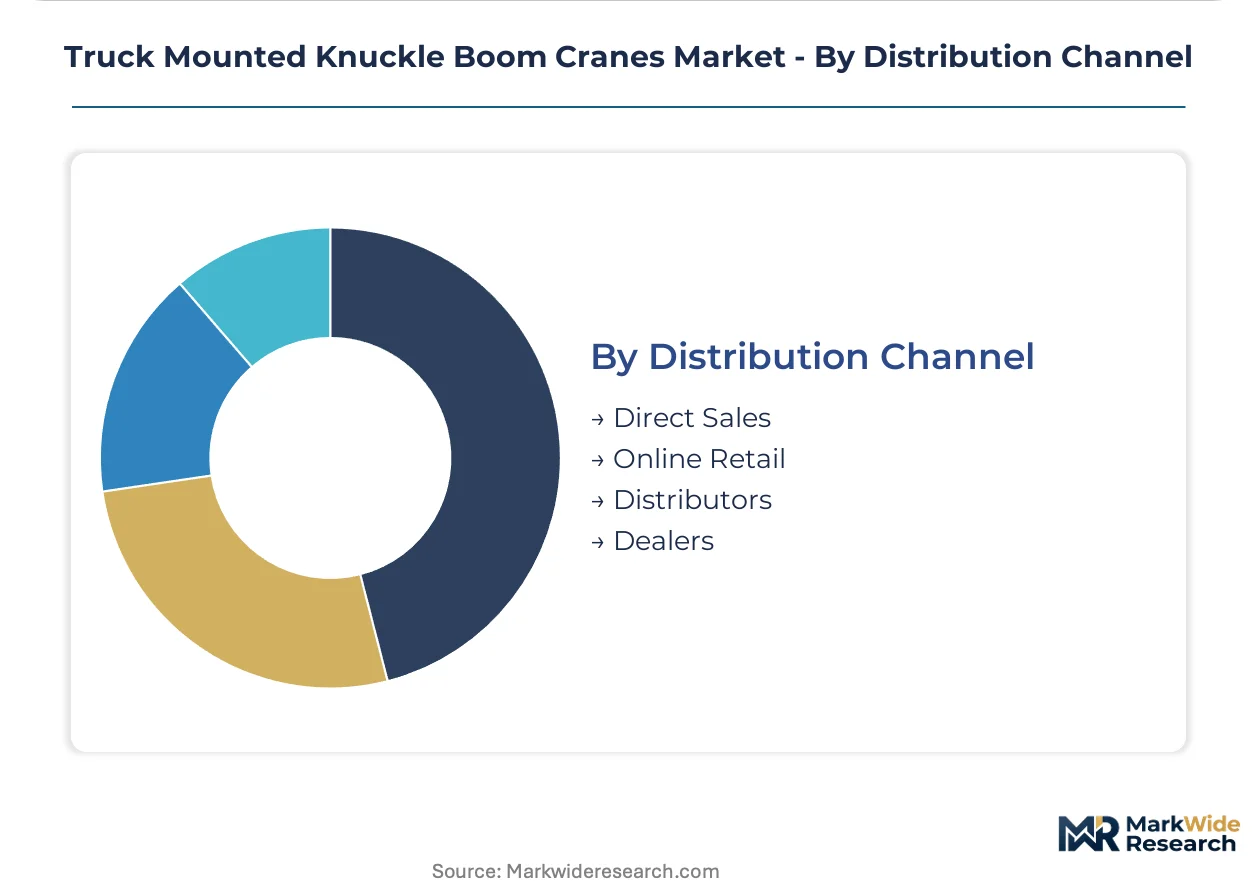
Channel selection determines margin capture and customer relationship depth, with direct sales enabling configuration customization and dealer networks delivering localized service response.
- Direct Sales:Large fleet operators and municipal procurement authorities negotiate factory-direct pricing for standardized multi-unit orders, capturing volume discounts while accepting longer delivery lead times.
- Distributors:Regional equipment houses stock common configurations and maintain technician certification for warranty service, bridging manufacturer capability and end-user accessibility.
- Dealers:Authorized networks provide chassis integration expertise and local regulatory compliance support, particularly critical in United States DOT permitting and European CE marking validation.
- Online Retail:Digital platforms serve replacement parts and accessory procurement for established fleet operators with in-house technical capability.
Dealers capture the highest transaction value per unit. Online channels are gaining share fastest in aftermarket parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in municipal procurement varies sharply across geographies. German buyers absorb premium pricing for CE-compliant stability systems. Indian first-time fleet operators prioritize acquisition cost over lifecycle service contracts.
United States
Telecommunications carriers drive compact-mount crane demand for 5G cell tower densification in urban corridors. OSHA mandates simulator-based operator certification and documented load chart competency. Fleet procurement concentrates in Texas utility markets and California vegetation management contracts addressing wildfire mitigation mandates.
Germany
Municipal utilities specify electro-hydraulic hybrid configurations for zero-emission zone compliance in Scandinavian-influenced procurement. The EU Machinery Directive and revised CE marking requirements accelerate replacement cycles among city fleet operators. Manufacturing clusters in Bavaria and North Rhine-Westphalia anchor European production capacity for hydraulic component integration.
China
Infrastructure renewal programs and logistics hub development sustain equipment replacement demand across coastal provinces. GB standards and SAMR enforcement establish technical benchmarks for domestic market participation. Yangtze River Delta port operators specify electric crane configurations for terminal electrification timelines.
India
National highway expansion and smart city initiatives create first-time fleet procurement for utility-mounted lifting equipment. Central Electricity Authority grid reliability standards expand vegetation management fleet requirements. Maharashtra and Gujarat municipal corporations issue tenders for compact-mount configurations suited to narrow urban corridors.
Brazil
Agricultural mechanization and forestry biomass harvesting expand crane applications in mechanized logging operations. Renewable energy subsidies for wood chip production drive equipment specification toward extended-reach configurations. São Paulo state fleet operators prioritize total cost of ownership calculations in municipal procurement.
Truck Mounted Knuckle Boom Cranes Market Competitive Landscape
Full-line manufacturers and specialized component suppliers split the market into distinct capability tiers. Consolidation pressure operates on hydraulic system integrators facing chassis electrification timelines. Three archetypes dominate: European precision-engineering houses with captive dealer networks, Chinese scale-driven fabricators with vertical steel supply control, and North American rental-focused specialists with rapid-configuration expertise. Competitive moves center on predictive maintenance platform deployment and electric actuator architecture validation partnerships with battery-electric chassis OEMs.
Among European-anchored precision manufacturers, Palfinger AG and Liebherr Group occupy positions emphasizing aftermarket service intensity and stability control engineering. XCMG Group exemplifies the scale-driven archetype through manufacturing footprint and structural component supply integration. Hyva represents municipal-specialist positioning with compact-mount configurations optimized for constrained urban deployment.
| Leading Market Players |
|---|
| Hyva |
| Cargotec Corporation |
| Palfinger AG |
| Liebherr Group |
| XCMG Group |
| Fassi S.r.l. |
| Terex Corporation |
| Manitex International |
| IMT |
| Others |
Value Network & Pricing Analysis
The Hamburg-Rotterdam freight corridor shapes cost dynamics across knuckle boom crane manufacturing, with chassis integration logistics feeding downstream price differentiation between premium electro-hydraulic configurations and standard hydraulic alternatives. Supply concentration in German and Italian precision component manufacturing amplifies pricing power for stability control systems, while municipal fleet procurement in Scandinavia absorbs premiums for zero-emission compatibility.
Pricing Analysis
Aftermarket service contracts anchor lifetime value capture, with predictive maintenance platforms generating recurring revenue streams that offset compressed margins on initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification grade and after-sales bundling intensity. Pricing pressure stems from high-strength steel input volatility, compressing fabrication margins for mid-tier manufacturers. Construction rental fleets exhibit highest price sensitivity, while telecommunications carriers accept premiums for rapid-deployment compact configurations.
Supply Chain Analysis
Export-control restrictions on precision hydraulic valves and permanent magnet motors limit technology flows from German and Italian suppliers to Chinese fabricators, reshaping procurement strategies. Manufacturing concentrates in Germany, China, and Italy, with structural steel sourcing anchored in domestic mills. Component dependencies rest on high-pressure pumps, alloy boom sections, and semiconductor-based control modules. Single-source vulnerability concentrates in precision valve sourcing. Distribution runs through authorized dealer networks with chassis integration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Knuckle boom crane demand sits in early-cycle expansion, with chassis electrification mandates creating first-mover advantages for electric actuator validation partnerships.
For Market Incumbents: Harden aftermarket service platforms against emerging predictive maintenance specialists by embedding IoT diagnostics as standard equipment. Deepen captive supply of structural steel components to offset alloy price volatility. Prioritize CE marking compliance investments as EU Machinery Directive updates accelerate replacement cycles among municipal fleets. For New Entrants and Emerging Players: Establish a beachhead in Indian municipal procurement for compact-mount configurations serving narrow urban corridors. Target telecommunications carrier segments in Germany and the United States where 5G densification programs prioritize maneuverability over lift capacity. Pursue simulator-based training partnerships to satisfy OSHA certification requirements and reduce buyer switching costs. For Investors and Strategic Acquirers: Battery-electric chassis compatibility standards reshape the acquisition landscape toward electric-hydraulic integration capabilities. Five-to-ten-year viability favors manufacturers with validated powertrain interfaces and software-defined control architectures. Monitor certification timeline acceleration as the signal indicating which powertrain configurations secure public-sector procurement lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Architecture Validation | Partnerships with battery-electric chassis OEMs secure zero-emission zone compliance for municipal procurement. |
| Predictive Maintenance Platform Deployment | IoT-enabled diagnostics shift margin capture from equipment sales to recurring service contracts. |
| CE Marking Acceleration Investment | Early compliance with revised EU Machinery Directive stability requirements captures replacement demand. |
| Compact-Mount Configuration Development | Sub-ten-meter outrigger span designs address 5G cell tower densification in congested urban rights-of-way. |
| Indian Market Localization Partnership | Joint ventures with domestic fabricators reduce landed cost for national highway expansion tenders. |
Research Methodology
A standing panel of fleet maintenance directors, municipal procurement officers, OEM chassis integration engineers, and aftermarket service heads provided ongoing calibration across primary fieldwork and secondary validation. Equipment manufacturer SEC filings, EU Machinery Directive compliance databases, customs trade records for hydraulic component flows, and municipal tender documentation supplied triangulation anchors. Bottom-up unit economics and top-down infrastructure spending forecasts were reconciled through iterative stakeholder review.
Scenario bracketing bounded projections across low, base, and high electrification adoption pathways over the projection horizon. Segmentation dimensions spanned powertrain architecture, end-use industry, application duty cycle, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and infrastructure program commitment tracking. Forecast inputs incorporated chassis electrification timelines and municipal fleet decarbonization mandates.
Sensitivities concentrate around battery-electric chassis payload penalty resolution and hydraulic component supply concentration disruptions. Forecasts reflect assumptions on regulatory enforcement consistency and alloy input price stabilization. Material shifts in EU zero-emission zone expansion schedules or OSHA certification requirement modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Powered Screed Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Log Splitters Rental Market