
 Coronary Guidewires Market | 2026-2036
Coronary Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Guidewires Market Intelligence
A procedural shift towards Ambulatory Surgical Centers is unwinding the historical dominance of large Specialty Cardiac Hospitals in case volume. Abbott Laboratories leverages its broad cardiovascular portfolio to serve both settings. Boston Scientific Corporation differentiates through its focus on guidewires for complex interventions. ASAHI INTECC sustains its premium position through specialized manufacturing of high-performance guidewires.
A coronary guidewire is a thin, flexible wire used to navigate coronary arteries during interventional procedures. These devices typically feature a 0.014-inch diameter with a core made of stainless steel or nitinol, designed to provide torque control and trackability. Nitinol-based guidewires command a significant share due to their flexibility and kink resistance. Within applications, guidewires designed for Chronic Total Occlusion procedures are a high-growth area, reflecting the trend toward treating more complex patient cases.
Market access requires stringent approvals from bodies like the U.S. FDA, and compliance with Europe's Medical Device Regulation (MDR). These frameworks, alongside Japan's PMDA requirements, mandate extensive clinical data on device safety and performance, influencing product design and testing protocols. Navigating the evolving reimbursement policies for procedures in outpatient settings is a critical factor for future profitability.
Market Dynamics
The increasing procedural complexity in interventional cardiology, particularly the focus on treating Chronic Total Occlusions, is the central force shaping the coronary guidewire market. This drives demand for highly specialized, high-performance devices, influencing material science, product design, and physician training.
Growth Catalysts
- Hybrid Guidewire Technology:Innovations combining nitinol and stainless steel cores enhance torque, flexibility, and trackability, enabling physicians to access and cross more complex and distal lesions than previously possible.
- Demand Concentration in Japan:The widespread practice of advanced interventional cardiology techniques and a favorable reimbursement environment in Japan create concentrated, high-value demand for premium, high-performance guidewires.
- Chronic Total Occlusion Procedures:The rising number of percutaneous coronary interventions for CTOs represents the fastest-growing application, requiring a specialized toolkit of guidewires with varying tip loads and stiffness profiles.
Market Restraints
- Stringent Regulatory Pathways:Market access requires extensive clinical data to satisfy bodies like the U.S. FDA, Europe's MDR, and Japan's PMDA, creating long development timelines and high compliance costs for new devices.
- Nitinol Supply Constraints:The reliance on medical-grade nitinol, a material with a concentrated supply base, exposes manufacturers to price volatility and potential sourcing disruptions that can impact production costs.
- Substitution by Imaging Catheters:In some diagnostic scenarios, advanced intravascular imaging catheters can reduce the need for multiple guidewire exchanges, representing a form of procedural substitution that can limit guidewire unit volume.
Strategic Opportunities
- Expansion in Latin America:As countries like Brazil and Mexico expand their cardiac care infrastructure, there is a significant opportunity to introduce advanced guidewire technologies into currently underpenetrated healthcare systems.
- Advanced Surface Coatings:Developing and patenting novel hydrophilic or hydrophobic coatings can create significant product differentiation by improving lubricity, reducing friction, and enhancing device trackability through tortuous anatomy.
- Guidewires for Robotic PCI:Designing guidewires optimized for use with robotic percutaneous coronary intervention systems presents a new market segment, catering to the unique torque and feedback requirements of automated platforms.
Industry Challenges
- Physician Training Gap:A shortage of interventional cardiologists with the specialized skills required to perform complex procedures like CTO limits the full adoption potential of the most advanced guidewire technologies.
- Reimbursement Navigation:Securing adequate and consistent reimbursement codes for new guidewire technologies and associated procedures in outpatient settings like Ambulatory Surgical Centers is a persistent operational hurdle.
- Manufacturing Sterility:Maintaining the integrity of the sterile manufacturing process and supply chain for Class III devices is a capital-intensive challenge, subject to rigorous and frequent regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Guidewires Market |
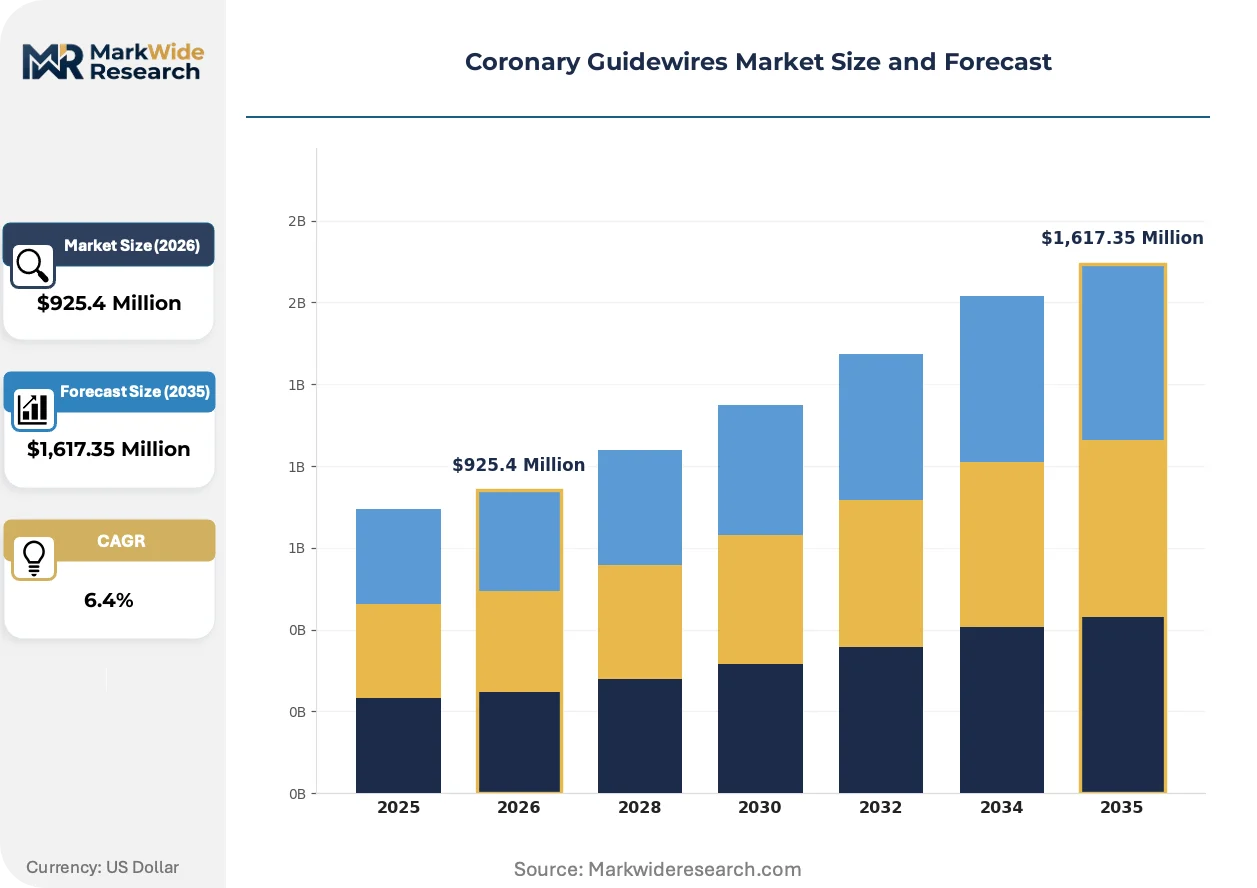
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,617.35 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Coated, Polymer Coated, Stainless Steel, Nitinol, Composite Application: Percutaneous Coronary Intervention, Chronic Total Occlusion, Bifurcation Lesions, Coronary Angioplasty End User: Specialty Cardiac Hospitals, Ambulatory Surgical Centers, Catheterization Laboratories, Diagnostic Imaging Centers Technology: Coil Core, Braided Core, Solid Core, Hybrid Core, Polymer Jacketed |
| Companies Covered | Terumo Medical Corporation, Cordis, Boston Scientific Corporation, B. Braun, Merit Medical Systems, Medtronic, ASAHI INTECC, Teleflex Incorporated, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Guidewires Market Strategic Shifts & Innovations
Material science innovation and procedural miniaturization are fundamentally altering coronary guidewire design. These advancements enable interventional cardiologists to address a wider spectrum of coronary artery disease, pushing the boundaries of what is considered treatable via percutaneous intervention.
Hybrid core technology combines a nitinol distal segment with a stainless steel proximal shaft. Interventional cardiologists in high-volume specialty cardiac hospitals are rapidly adopting these designs for complex cases. This composite construction is displacing single-material guidewires in CTO procedures by providing a unique combination of tip flexibility and proximal shaft support for superior pushability and torque response.
Europe's Medical Device Regulation (MDR) has intensified scrutiny on all medical devices, including coronary guidewires. This framework mandates more extensive clinical evidence and robust post-market surveillance throughout the device lifecycle. Guidewire manufacturers are most affected, as they must now allocate significant resources to generate continuous clinical data to maintain CE marking, especially for established products.
A procedural shift away from inpatient hospital settings toward Ambulatory Surgical Centers (ASCs) is changing purchasing dynamics. This trend disrupts the traditional, bulk-order procurement model of large hospitals, favoring suppliers who can offer flexible, just-in-time inventory management. This pattern is most pronounced in the United States, where payer policies increasingly incentivize outpatient cardiovascular procedures.
Coronary Guidewires Market Segmentation
Understanding the distinct segments within the coronary guidewires market is crucial for manufacturers to align product development with evolving clinical needs and procurement trends. Each segment reflects unique material science, application requirements, and end-user preferences, shaping investment priorities and market strategies.
Product Type:
Substitution pressure is a significant factor within the product type segmentation, particularly as newer material combinations challenge established designs.
- Nitinol:These guidewires feature a nickel-titanium alloy core, providing exceptional flexibility, kink resistance, and shape memory for intricate navigation. Demand concentrates in complex interventional procedures, where device reliability is paramount for patient safety.
- Composite:Combining materials like nitinol and stainless steel, these guidewires offer a unique blend of distal flexibility and proximal pushability for enhanced torque transmission. Interventional cardiologists increasingly adopt composite designs for challenging cases like Chronic Total Occlusion.
- Hydrophilic Coated:A polymer coating attracts water, creating a slippery surface that reduces friction and enhances trackability through tortuous anatomy.
- Polymer Coated:These guidewires feature a non-hydrophilic polymer jacket, providing smooth advancement and often tactile feedback during procedures.
- Stainless Steel:Traditional stainless steel guidewires offer high stiffness and excellent torque response, making them suitable for initial vessel access and support.
Nitinol guidewires retain volume leadership; Composite designs hold the steepest expansion curve.
Application:
The application segmentation reflects how procedural volume influences guidewire design and market demand.
- Chronic Total Occlusion:This demanding application involves specialized guidewires with varying tip loads and stiffness profiles to recanalize completely blocked coronary arteries. The rising number of complex patient cases drives demand for high-performance CTO-specific devices.
- Percutaneous Coronary Intervention:Guidewires are foundational tools for opening narrowed or blocked coronary arteries, facilitating balloon angioplasty and stent delivery. This broad application represents the largest volume segment, driven by global cardiovascular disease prevalence.
- Coronary Angioplasty:Guidewires provide access and support for balloon dilation to restore blood flow in stenosed coronary arteries.
- Bifurcation Lesions:Specialized guidewires assist in navigating and treating blockages at arterial branch points, requiring precise control and trackability.
Percutaneous Coronary Intervention remains the largest application segment; Chronic Total Occlusion procedures represent the fastest-growing trajectory.
End User:
The end-user segmentation highlights distinct customer procurement patterns and service delivery models.
- Specialty Cardiac Hospitals:These large facilities historically handle the highest volume of complex interventional cardiology cases, often driving demand for premium, high-performance guidewires. Their procurement models typically involve bulk purchasing and long-term contracts.
- Ambulatory Surgical Centers:A procedural shift towards outpatient settings is increasing the case volume in ASCs, requiring suppliers to adapt to flexible, just-in-time inventory management. These centers prioritize cost-effectiveness alongside device performance.
- Catheterization Laboratories:These dedicated units within hospitals perform diagnostic and interventional cardiac procedures, consistently consuming a steady volume of guidewires.
- Diagnostic Imaging Centers:While not primary users, some advanced imaging centers may utilize guidewires for specific diagnostic procedures requiring arterial access.
Specialty Cardiac Hospitals continue to drive the largest purchasing volumes; Ambulatory Surgical Centers are rapidly gaining share.
Technology:
Technological maturity and innovation cycles define the competitive landscape within the technology segmentation.
- Hybrid Core:These advanced guidewires combine different core materials, such as nitinol and stainless steel, to optimize flexibility, torque, and pushability. Hybrid core technology enables access to more challenging and distal lesions.
- Polymer Jacketed:A polymer coating encapsulates the guidewire core, providing enhanced lubricity and reducing friction during navigation through tortuous anatomy. This design improves trackability and reduces vessel trauma.
- Coil Core:Featuring a coiled wire construction, these guidewires offer good flexibility and tactile feedback, commonly used for initial access and diagnostic procedures.
- Braided Core:Braided wire construction enhances torque transmission and kink resistance, providing improved control and maneuverability.
- Solid Core:Solid core guidewires offer maximum stiffness and support, often employed for delivering larger devices or navigating calcified lesions.
Coil Core designs maintain foundational market presence; Hybrid Core technology is experiencing the most rapid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's advanced interventional cardiology techniques drive demand for specialized guidewires, often sourced from global manufacturers. This creates a significant trade corridor for high-performance devices. Regulatory frameworks across key markets influence product development and market access strategies.
Japan
Japan exhibits high-value demand for premium guidewires due to its widespread practice of advanced interventional cardiology. PMDA requirements mandate extensive clinical data for device approval, influencing product design. Tokyo's medical technology hub concentrates innovation and specialized manufacturing capabilities for high-performance devices.
United States
The United States market sees demand for complex intervention guidewires and a procedural shift towards Ambulatory Surgical Centers. U.S. FDA stringent approvals and evolving reimbursement policies shape market entry and profitability. Boston's MedTech corridor fosters innovation in cardiovascular devices, attracting significant investment.
Germany
Germany's specialty cardiac hospitals drive demand for high-performance guidewires, emphasizing quality and clinical efficacy. Compliance with Europe's Medical Device Regulation (MDR) requires continuous clinical evidence for market access. Munich's medical device industry cluster supports research and development in advanced interventional tools.
China
China's expanding cardiac care infrastructure and rising cardiovascular disease prevalence generate substantial demand for coronary guidewires. NMPA approval processes are critical for market entry, requiring localized clinical trials. Shanghai's medical device manufacturing base is rapidly developing domestic production capabilities.
Brazil
Brazil presents a significant opportunity as its cardiac care infrastructure expands into previously underpenetrated regions. ANVISA requirements govern medical device approvals, influencing import and local manufacturing. São Paulo's healthcare sector serves as a hub for advanced medical procedures and device distribution.
Coronary Guidewires Market Key Industry Players
Listed leaders compete with private specialists across material science innovation and application-specific performance. The market structure sees large, diversified cardiovascular players alongside highly specialized manufacturers. Strategic archetypes include broad portfolio providers, complex intervention innovators, and premium material specialists. Geographic expansion and strategic partnerships remain dominant competitive moves.
On the premium-tier vector, Abbott Laboratories represents a diversified cardiovascular portfolio provider, leveraging its extensive product range across various clinical settings, including both specialty hospitals and Ambulatory Surgical Centers. Boston Scientific Corporation exemplifies a focus on guidewires tailored for complex interventions, differentiating its offerings through advanced designs for challenging lesions. ASAHI INTECC, a Japan-based specialist, occupies a premium position through its highly specialized manufacturing capabilities for high-performance guidewires, sustaining its market standing with a reputation for precision.
| Leading Market Players |
|---|
| Terumo Medical Corporation |
| Cordis |
| Boston Scientific Corporation |
| B. Braun |
| Merit Medical Systems |
| Medtronic |
| ASAHI INTECC |
| Teleflex Incorporated |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing capacity for high-performance guidewires drives supply concentration, establishing higher price floors for advanced devices. This scale economy influences market access and material sourcing strategies, particularly for complex intervention tools.
Pricing Analysis
The pricing differential between hybrid core guidewires and traditional stainless steel designs reflects their distinct performance capabilities. Value-based pricing dominates for complex intervention devices, where clinical outcomes justify premium costs. Quality grade and FDA/MDR certification levels are primary price differentiation drivers. Pricing softness emerges in the standard segment due to increased competition, while specialty cardiac hospitals demonstrate lower price sensitivity for high-performance tools.
Supply Chain Analysis
Just-in-time inventory management is gaining traction among Ambulatory Surgical Centers, contrasting with the strategic stockpiling typical of large specialty hospitals. Geographic supply concentration for medical-grade nitinol primarily centers in Japan and the United States. Key raw material dependencies include specialized alloys and polymer coatings. Single-source vulnerability for rare earth elements presents a structural supply chain risk. Distribution runs through a blend of direct sales forces and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coronary guidewire market is experiencing a buyer-power shift, driven by the increasing procurement influence of Group Purchasing Organizations (GPOs) within hospital networks. This consolidation among buyers affects pricing negotiations.
For Market Incumbents:Secure long-term supply agreements for critical raw materials like nitinol to mitigate commodity price volatility. Invest in next-generation hybrid core technologies to counter competitive threats from specialized innovators. Expand manufacturing capabilities in regions like China to meet rising demand, leveraging vertical integration for cost control.
For New Entrants and Emerging Players:Lead with highly specialized guidewire designs for niche applications such as complex Chronic Total Occlusion procedures. Target underpenetrated healthcare systems in Latin America, focusing on Brazil, with cost-effective yet high-performance solutions. A go-to-market angle should emphasize superior trackability and torque response in challenging anatomies.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized manufacturers with strong patent portfolios in hybrid core and advanced coating technologies. Long-term viability over the next decade hinges on companies demonstrating robust clinical data for complex interventions. Acquisition targets should possess unique material science expertise or established market access. Watch for increasing regulatory approvals of robotic PCI systems as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Coating R&D | Develop novel hydrophilic coatings to enhance guidewire lubricity and trackability. |
| Robotic PCI Guidewire Optimization | Design guidewires specifically for robotic systems, capturing a nascent high-growth segment. |
| Clinical Data Generation for MDR | Allocate resources to continuous clinical evidence collection to maintain CE marking in Europe. |
| Expansion into Latin American Markets | Introduce advanced guidewire technologies into expanding cardiac care infrastructure in Brazil. |
| Nitinol Sourcing Diversification | Establish multiple supplier relationships for medical-grade nitinol to reduce supply chain risk. |
Research Approach
The analysis maps coronary guidewire product types and application segments, each validated through extensive primary interviews with interventional cardiologists, hospital procurement managers, and R&D directors. This primary data was triangulated with secondary sources including FDA filings, PMDA submissions, and medical device industry reports. A bottom-up approach estimated market size, cross-referenced with top-down validation from key player revenues.
Outputs were consistently validated against external benchmarks and historical market trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from projected procedural volumes and technological adoption curves. Industry-specific forecast inputs included cardiovascular disease prevalence rates and interventional cardiology procedure growth.
This study's analysis sits within stated boundaries; outcomes outside significant shifts in global healthcare policies or major technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding regulatory stability and material supply. Revision becomes warranted when new clinical evidence dramatically alters treatment paradigms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Electronics Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
General Surgery Devices Market
Medical Devices
US Nebulizer Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
Corneal Surgery Devices Market