
 Mexico Digital X-Ray Devices Market | 2026-2036
Mexico Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital X-Ray Devices Market Foresight
Radiologic technologist shortages across Mexican states is unwinding deployment timelines for advanced imaging networks. Siemens Healthineers leverages its installed base of analog systems to anchor retrofit conversion contracts in Jalisco and Nuevo León. GE Healthcare competes through localized service infrastructure that sustains uptime guarantees for public hospital tenders. Canon Medical Systems specializes in mobile X-ray configurations that navigate rural clinic access constraints.
Mexico digital X-ray devices are electronic imaging systems that replace photographic film with solid-state detectors, typically employing cesium iodide or amorphous selenium conversion layers to capture photon energy and render diagnostic images within seconds for clinical decision-making. Flat panel detectors dominate procurement budgets due to superior dose efficiency and immediate image availability, while mobile X-ray systems represent the fastest-expanding product category as hospital groups pursue point-of-care flexibility. Digital radiography technology leads installed capacity, though direct conversion architectures are gaining preference in orthopedic applications where spatial resolution requirements are most stringent.
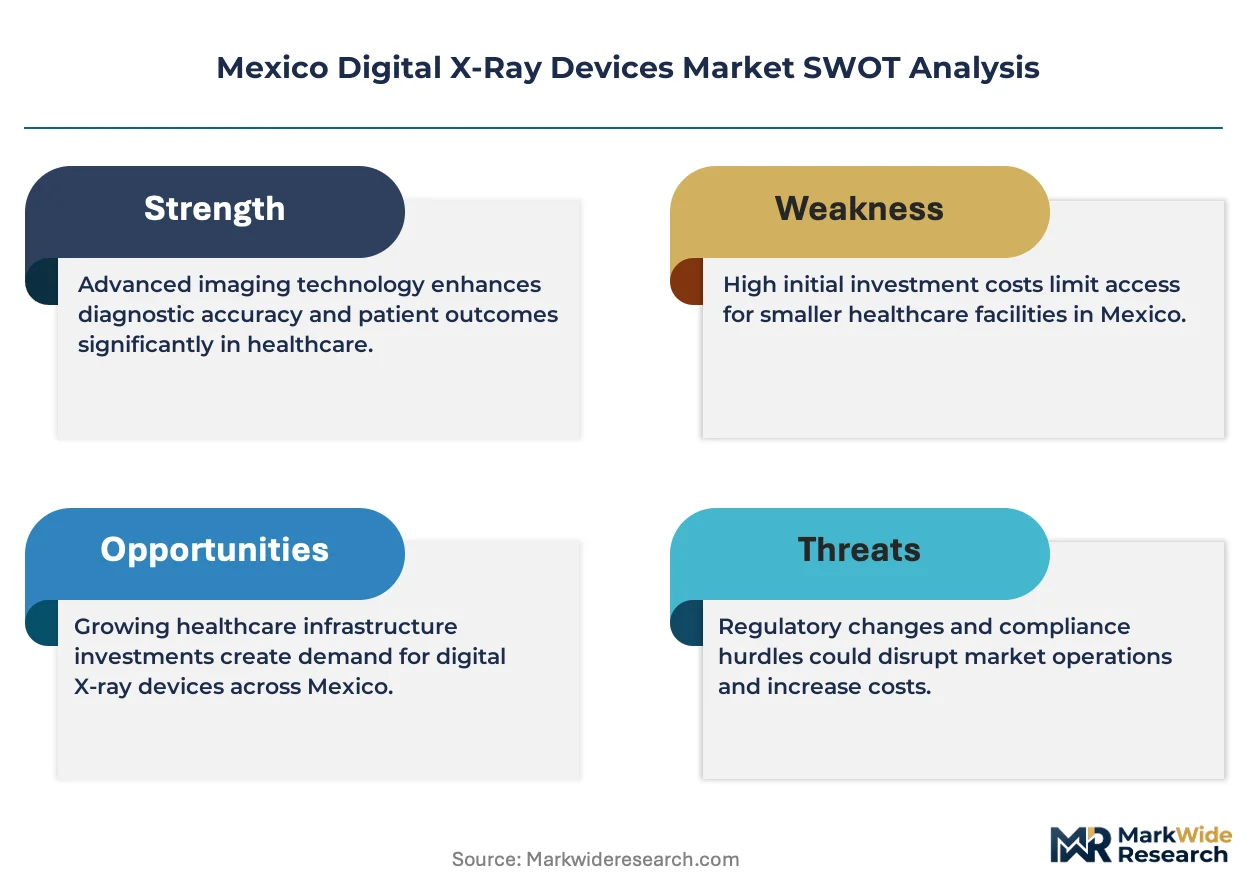
COFEPRIS, Mexico's national health regulator, enforces medical device registration and post-market surveillance protocols that shape product approval timelines and quality documentation burdens for importers. NOM standards for electromagnetic compatibility and electrical safety, administered by the national standardization body, determine technical compliance thresholds for equipment deployment in federal health facilities. Stakeholders must monitor pending updates to public procurement rules under INSABI restructuring, as these will determine whether domestic assembly requirements reshape supplier qualification criteria.
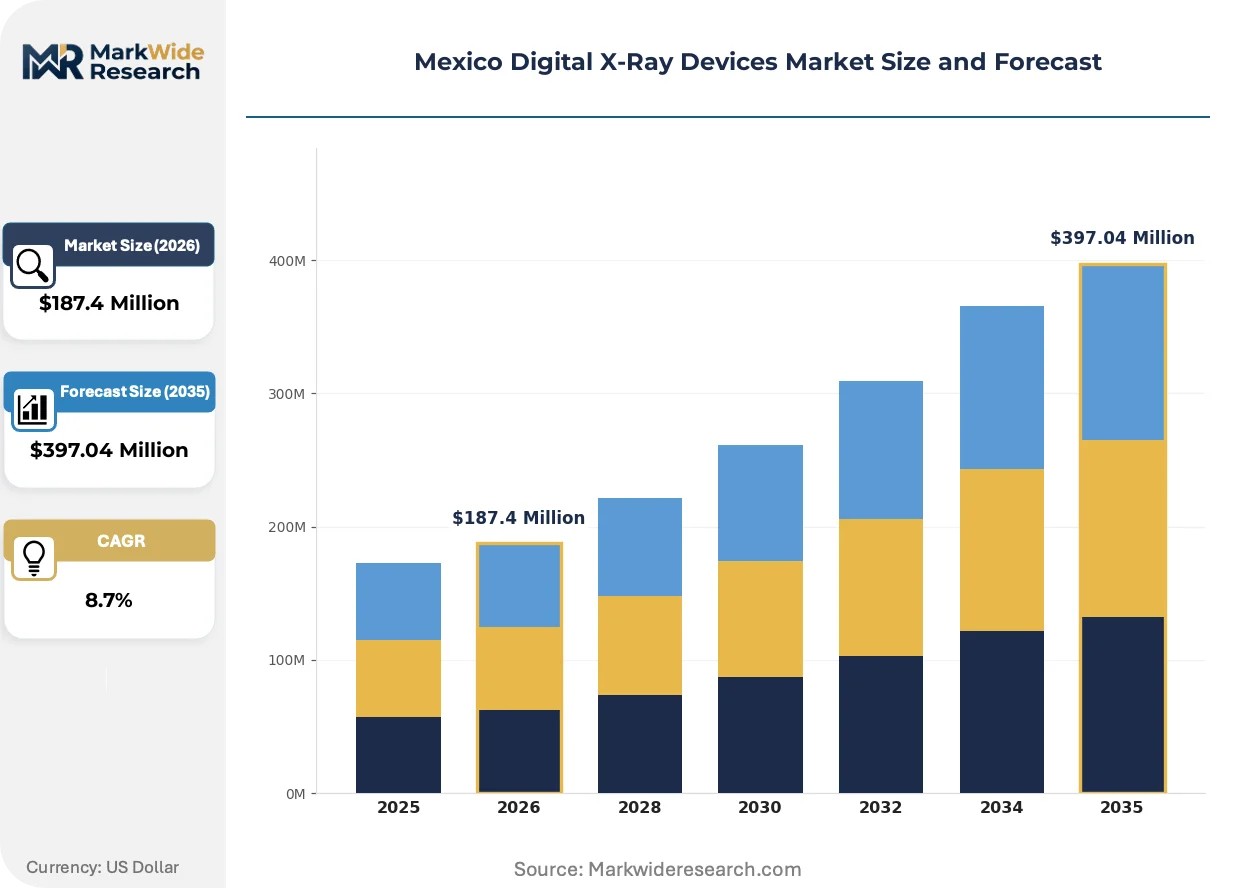
Market Dynamics
COFEPRIS enforcement of NOM electrical safety standards is compressing equipment approval timelines while INSABI restructuring redirects public procurement flows toward domestic assembly requirements.
Growth Catalysts
- INSABI Procurement Restructuring:Federal hospital consolidation is bundling radiography tenders into multi-year framework agreements that favor integrated service providers over equipment-only vendors.
- Amorphous Selenium Direct Conversion:Orthopedic centers in Mexico City are specifying direct-conversion flat panels for trauma imaging workflows requiring sub-millimeter spatial resolution.
- Jalisco Medical Cluster Expansion:Guadalajara's health technology manufacturing zone is attracting detector assembly operations that reduce import duty exposure for public sector buyers.
Market Restraints
- Cesium Iodide Supply Concentration:Scintillator substrate sourcing depends on three Asian chemical processors, exposing Mexican OEMs to raw material allocation disruptions.
- Radiologic Technologist Shortage:CONAET certification bottlenecks limit trained operator availability across 24 Mexican states, capping equipment utilization rates.
- Analog Retrofit Complexity:Legacy film-based rooms in rural clinics require structural modifications for detector integration that exceed available renovation budgets.
Strategic Opportunities
- Yucatán Peninsula Point-of-Care Networks:Mobile X-ray deployments to Merida and Cancun resort-corridor hospitals address tourist-season trauma surge capacity without fixed-room capex.
- Artificial Intelligence Workflow Integration:Automated chest X-ray screening algorithms are creating software attach revenue streams for hardware vendors serving IMSS tuberculosis programs.
- Tele-radiology Hub Architecture:Centralized image interpretation centers in Monterrey enable teleradiology service contracts that extend specialist reach to Chihuahua and Sonora border clinics.
Industry Challenges
- COFEPRIS Registration Timelines:Medical device approval queues extending 14-18 months delay product launches and compress revenue recognition windows.
- Legacy PACS Integration Friction:Hospital information system heterogeneity forces custom DICOM connectivity engineering for each major public health institution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital X-Ray Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography, Mobile X-Ray Systems, Retrofit Solutions End User: Hospitals, Diagnostic Centers, Dental Clinics, Research Laboratories Technology: Digital Radiography, Direct Conversion, Indirect Conversion, Hybrid Systems Application: Orthopedics, Cardiology, Oncology, Emergency Care |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems, Fujifilm Holdings Corporation, Carestream Health, Shimadzu Corporation, Mindray Medical International, Agfa Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital X-Ray Devices Market Shifts & Advancements
Detector architecture evolution and procurement model restructuring are redistributing competitive advantage away from hardware specifications toward integrated workflow solutions and localized service density.
Wireless flat panel detectors is fragmenting the traditional fixed-room radiography market by enabling corridor-based deployment models that eliminate dedicated shielded suite requirements. Community hospitals in Nuevo León are adopting battery-powered panels for emergency department overflow imaging. This mobility is compressing capital allocation per diagnostic site and expanding addressable clinic categories.
NOM-024-SCFI electromagnetic compatibility standards revision is mandating updated shielding documentation for all new digital radiography installations. Equipment importers must submit revised technical files to the national standardization body before federal facility deployment. Mobile system manufacturers are pre-certifying configurations to avoid tender disqualification under tightened compliance windows.
Service contract unbundling is separating preventive maintenance from equipment financing in public hospital tenders. State health secretariats in Puebla and Veracruz are negotiating standalone uptime guarantee agreements with independent service organizations. This disaggregation is most visible in IMSS regional divisions seeking operational flexibility outside manufacturer-captive service structures.
Mexico Digital X-Ray Devices Market Segmentation
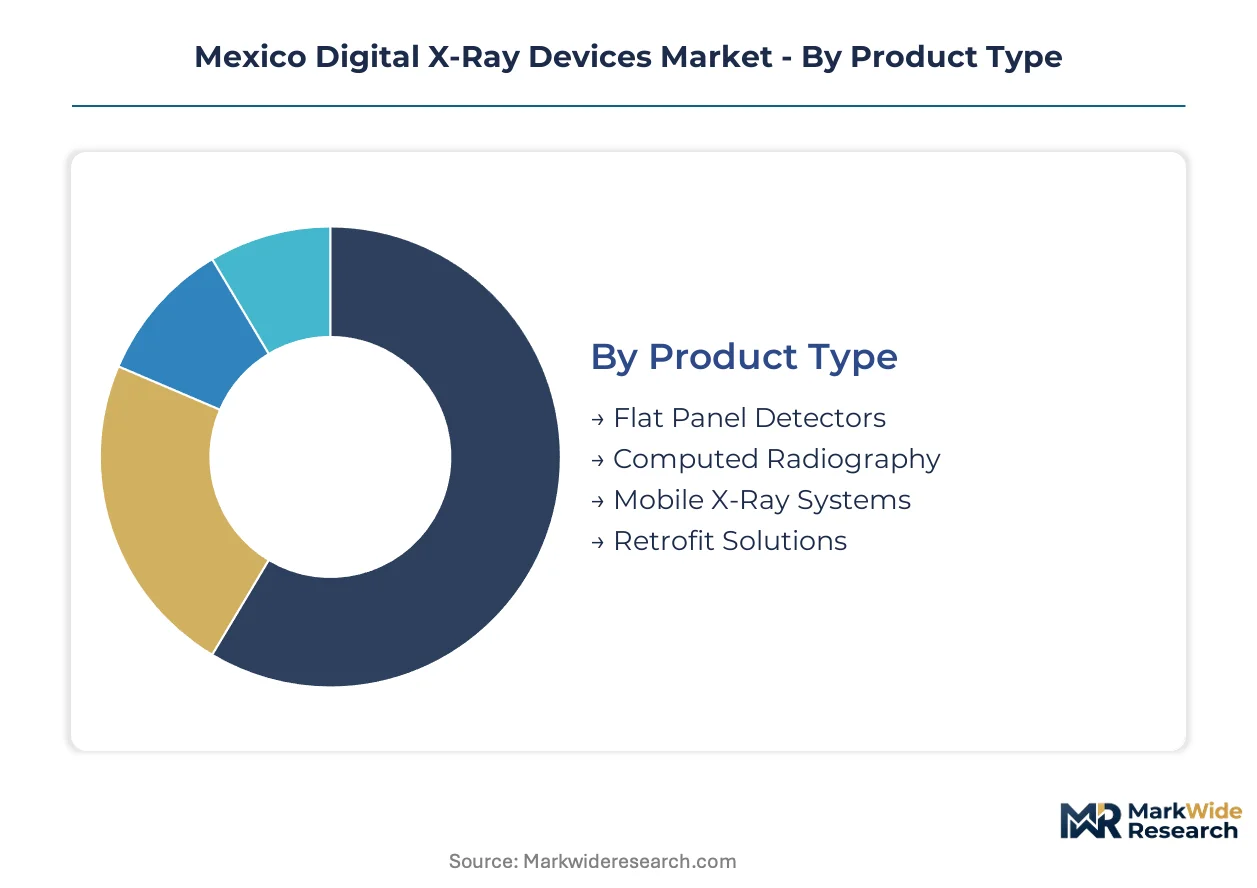
Digital X-ray segmentation in Mexico reveals divergent margin structures across hardware architectures and procurement channels. Hospital procurement consolidation and COFEPRIS regulatory tiers create distinct profitability zones that reshape vendor positioning strategies.
Product Type:
Margin pools concentrate in detector technologies where import duty exposure and service attach rates diverge most sharply.
- Flat Panel Detectors:Cesium iodide or amorphous selenium conversion layers deliver immediate image availability with superior dose efficiency. IMSS tertiary hospitals in Mexico City specify these for high-throughput trauma workflows where throughput justifies premium procurement budgets.
- Mobile X-Ray Systems:Battery-powered wireless configurations enable corridor-based deployment without dedicated shielded suites. Nuevo León community hospitals adopt these for emergency department overflow, compressing capital allocation per diagnostic site while expanding clinic categories.
- Computed Radiography:Photostimulable phosphor plate systems persist in budget-constrained state facilities where full digital conversion remains capital-prohibitive.
- Retrofit Solutions:Detector integration kits for legacy analog rooms address rural clinic upgrade paths without structural renovation.
The dominant share belongs to Flat Panel Detectors, while Mobile X-Ray Systems is closing the gap fastest.
End User:
Procurement scale and reimbursement structure determine equipment specification tiers across facility types.
- Hospitals:Federal health institutions including IMSS and ISSSTE facilities drive volume through multi-year framework agreements. INSABI restructuring bundles radiography tenders toward integrated service providers with uptime guarantee capabilities.
- Diagnostic Centers:Private imaging chains in Guadalajara and Monterrey prioritize throughput optimization and PACS connectivity for teleradiology hub participation.
- Dental Clinics:Intraoral and panoramic digital systems serve orthodontic and implant planning workflows with distinct sensor size requirements.
- Research Laboratories:Preclinical imaging configurations support pharmaceutical and academic research protocols with specialized resolution and dose calibration needs.
Hospitals command the largest procurement volumes, though Diagnostic Centers are expanding their share through private capital investment.
Technology:
Conversion architecture selection trades spatial resolution against manufacturing cost and supply chain reliability.
- Digital Radiography:Solid-state detector arrays with TFT backplanes constitute the installed base majority across Mexican public health infrastructure.
- Direct Conversion:Amorphous selenium layers eliminate intermediate scintillation steps for sub-millimeter spatial resolution. Mexico City orthopedic centers specify these for trauma imaging workflows requiring fine bone detail visualization.
- Indirect Conversion:Cesium iodide scintillator coupled to photodiode arrays balances cost and performance for general radiography applications.
- Hybrid Systems:Configurable platforms supporting both direct and indirect conversion modes address mixed specialty requirements in multi-service hospitals.
Digital Radiography maintains the broadest deployment, while Direct Conversion is gaining preference fastest in specialized orthopedic settings.
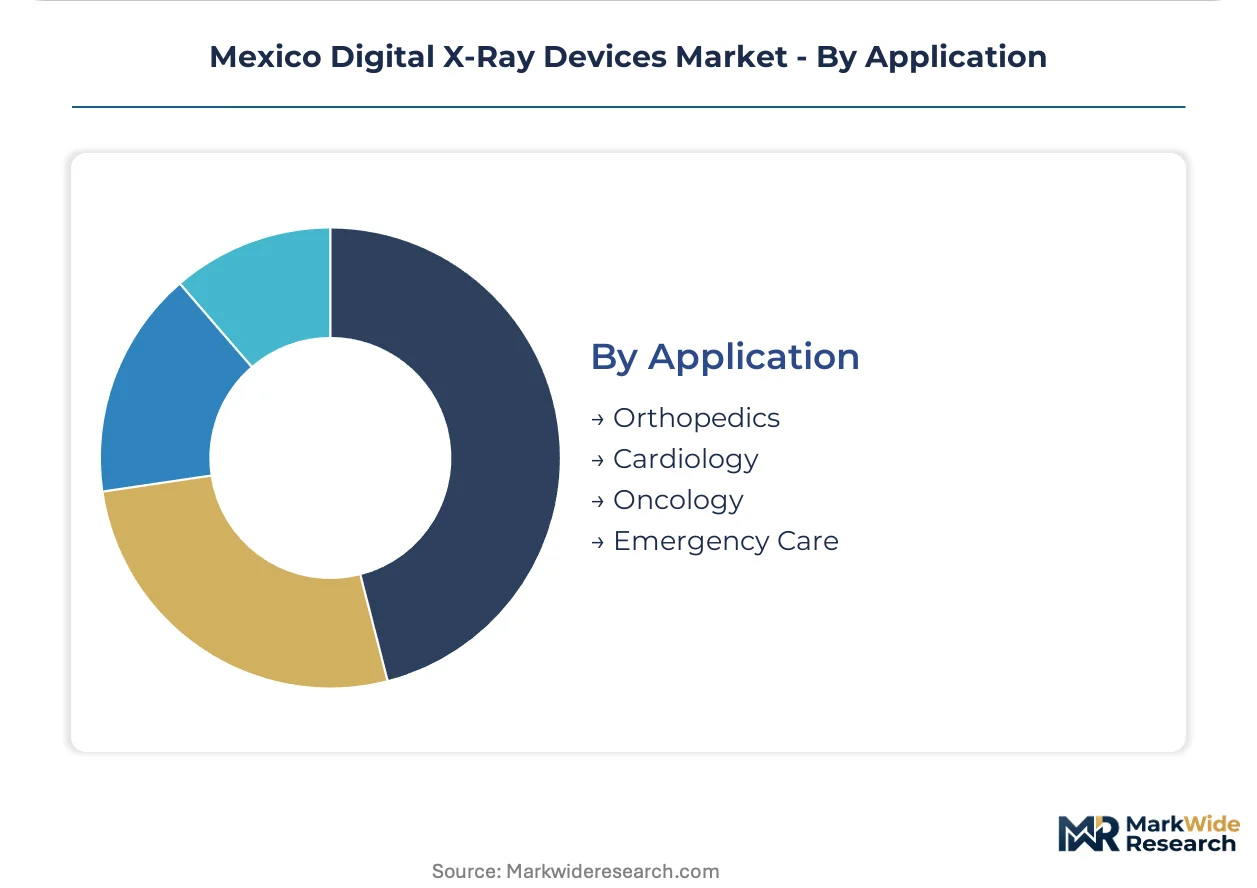
Application:
Clinical workflow demands shape detector specification priorities and software integration requirements.
- Orthopedics:Weight-bearing extremity imaging and trauma protocols demand high spatial resolution and rapid acquisition sequences. Direct conversion flat panels penetrate this segment most deeply.
- Cardiology:Cardiac catheterization and interventional procedures require real-time fluoroscopy integration with digital radiography platforms.
- Oncology:Radiation therapy simulation and treatment verification impose geometric accuracy and dose measurement precision standards.
- Emergency Care:Portable chest and trauma imaging in high-acuity settings drives mobile system adoption with wireless detector mobility.
Orthopedics leads equipment specification intensity, while Emergency Care is expanding fastest through mobile system deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's digital X-ray consumption concentrates in three metropolitan corridors that deploy equipment for fundamentally different clinical workflows than peripheral states. Mexico City prioritizes high-throughput trauma networks. Northern border states emphasize mobile point-of-care flexibility. Southern regions remain analog-dependent due to infrastructure constraints.
Mexico City Metro
IMSS tertiary hospitals and private orthopedic centers drive demand for direct-conversion flat panels with sub-millimeter resolution specifications. COFEPRIS enforces NOM-024-SCFI electromagnetic compatibility documentation for all federal facility deployments. The Polanco and Santa Fe medical corridors host concentration of diagnostic imaging chains pursuing teleradiology hub status.
Nuevo León
Monterrey's hospital groups specify mobile X-ray systems for emergency department overflow capacity and tourist-corridor trauma surge readiness. State health secretariats negotiate standalone uptime guarantee contracts with independent service organizations. The Apodaca manufacturing zone attracts detector assembly operations reducing import duty exposure for public buyers.
Jalisco
Guadalajara's medical technology cluster anchors retrofit conversion programs targeting legacy analog installations in surrounding rural municipalities. INSABI restructuring bundles radiography tenders toward integrated service providers with preventive maintenance capabilities. The El Salto health technology manufacturing zone supports localized detector production.
Northern Border States
Chihuahua and Sonora clinics deploy tele-radiology architectures linking border facilities to Monterrey interpretation centers. Baja California hospitals serving medical tourism flows specify rapid-acquisition digital radiography for orthopedic and dental workflows. Tijuana manufacturing maquiladoras generate occupational health screening demand.
Yucatán Peninsula
Mérida and Cancún resort-corridor hospitals prioritize mobile X-ray deployments addressing seasonal trauma volume spikes without fixed-room capital expenditure. CONAET certification bottlenecks limit trained technologist availability, capping equipment utilization rates. State health infrastructure remains dependent on computed radiography systems where full digital conversion exceeds renovation budgets.
Mexico Digital X-Ray Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on detector architecture and service density. Siemens Healthineers and GE Healthcare anchor the integrated tier through captive service infrastructure and multi-year framework agreements with federal health institutions. Canon Medical Systems and Fujifilm Holdings occupy specialist positions emphasizing mobile configurations and orthopedic workflow optimization. Competitive dynamics center on retrofit conversion contracts and artificial intelligence software attach rates rather than hardware specification alone.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify the integrated service-provider archetype that INSABI restructuring increasingly favors for bundled tender participation. Koninklijke Philips NV represents the premium-tier imaging vendor competing through workflow software integration. Canon Medical Systems anchors the mobile-specialist position addressing point-of-care flexibility requirements in Nuevo León and Yucatán Peninsula deployments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Mindray Medical International |
| Agfa Healthcare |
| Others |
Supply & Pricing Matrix
Detector manufacturing scale economies in Asian chemical processing centers establish cost floors that cascade through Mexican procurement tiers, concentrating pricing power among suppliers with captive cesium iodide conversion layer capacity while pressuring regional distributors to absorb tariff exposure through service bundling.
Pricing Analysis
Long-term framework agreements dominate public hospital procurement, with IMSS and ISSSTE bundling radiography tenders into multi-year service contracts that embed preventive maintenance and uptime guarantees. Price differentiation hinges on COFEPRIS registration tier and after-sales service density, with federal facilities paying premiums for NOM-024-SCFI pre-certified configurations. Cost compression in the mobile X-ray segment is intensifying as Nuevo León community hospitals prioritize capital efficiency over feature depth. State health secretariats in peripheral regions exhibit highest price sensitivity, while Mexico City orthopedic centers demonstrate lowest sensitivity due to resolution-critical trauma workflows.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Mexican distributors serving IMSS regional divisions, though detector assembly operations in Guadalajara's El Salto zone maintain strategic stockpiles of amorphous selenium substrates to buffer COFEPRIS approval delays. Manufacturing concentration rests on Japan, South Korea, and Germany for TFT backplane fabrication, while cesium iodide scintillator sourcing draws from Chinese and Taiwanese chemical processors. Single-source vulnerability in photodiode array supply creates exposure to allocation disruptions during semiconductor cycle upturns. Distribution runs through authorized medical device importers with COFEPRIS establishment licenses, who manage last-mile logistics to federal health facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive advantage as artificial intelligence workflow integration and teleradiology hub architectures transform hardware vendors into service-layer orchestrators, with interoperability standards determining ecosystem participation value.
For Market Incumbents: Fortify service infrastructure density in Jalisco and Nuevo León to defend against independent service organizations unbundling maintenance contracts from equipment financing. Deepen backward integration into detector assembly operations within Mexico's health technology manufacturing zones to offset import duty exposure under INSABI restructuring. Prioritize AI software attach development for IMSS tuberculosis screening programs where automated chest X-ray algorithms create switching costs. For New Entrants and Emerging Players: Rural clinic retrofit solutions represent the most penetrable white-space segment, where legacy analog room conversion complexity exceeds incumbent service bandwidth. Target Yucatán Peninsula point-of-care deployments with battery-powered wireless configurations that bypass dedicated shielded suite requirements. Pursue tele-radiology infrastructure partnerships with Monterrey interpretation centers as a channel to Chihuahua and Sonora border clinics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors detector architecture specialists with direct conversion capabilities and established COFEPRIS registration pathways over generalist imaging conglomerates. Acquisition targets should demonstrate installed base conversion potential in orthopedic and trauma workflows. Monitor INSABI procurement rule finalization as the inflection signal determining whether domestic assembly requirements reshape supplier qualification criteria and consolidation incentives.| Strategic Initiative | Industry Significance |
|---|---|
| AI Workflow Integration | Automated screening algorithms for IMSS tuberculosis programs create recurring software revenue streams. |
| Domestic Assembly Expansion | Guadalajara detector production reduces import duty exposure under pending INSABI restructuring rules. |
| Service Contract Unbundling | Standalone uptime guarantees with independent service organizations address Puebla and Veracruz operational flexibility demands. |
| Mobile System Certification | Pre-certified NOM-024-SCFI configurations prevent tender disqualification under tightened compliance windows. |
| Teleradiology Hub Architecture | Monterrey interpretation centers extend specialist reach to Chihuahua and Sonora border clinics. |
Research Methodology
Initial hypotheses were tested against primary input from hospital biomedical engineers, GPO contracts managers, radiologic technologists, and COFEPRIS regulatory consultants and refined through secondary validation against hospital procurement databases, GPO contract repositories, NOM standardization body filings, and customs import records. Bottom-up equipment deployment tracking across IMSS regional divisions was triangulated with top-down market sizing from federal health infrastructure budgets.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension: detector technology architecture, end-user facility type, conversion physics, and clinical application workflow. CAGRs were derived from equipment replacement cycle analysis and public procurement pipeline assessment. Forecast inputs incorporate CONAET certification capacity constraints and INSABI tender bundling trajectories.
Forecasts assume regulatory continuity in COFEPRIS medical device registration and NOM electromagnetic compliance regimes; material policy shifts would require re-modeling. Revision becomes warranted when radiologic technologist training bottlenecks or cesium iodide supply allocation disruptions cross thresholds that compress equipment utilization rates or extend procurement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market