
 Laparoscopic Devices Market | 2026-2036
Laparoscopic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Devices Market Intelligence
Single-use specification tiers are rotating demand away from reprocessed instruments across hospital procurement committees. Johnson & Johnson leverages its Ethicon franchise to dominate advanced energy device categories in North America. Medtronic anchors its portfolio through integrated visualization and powered stapling platforms that reduce operative variability. Karl Storz SE & Co. KG specializes in rigid endoscope optics and maintains manufacturing scale from its Tuttlingen, Germany headquarters.
Laparoscopic devices comprise trocar access systems, insufflation units, and specialized grasping or cutting instruments engineered for 5-12 mm port diameters and abdominal cavity pressures of 12-15 mmHg, enabling minimally invasive visualization and manipulation of internal organs. Electrosurgical technology leads current revenue contribution due to universal deployment across cholecystectomy and hernia repair protocols, while robotics is displacing hand-held instrumentation in high-complexity gynecological surgery as capital budgets shift toward systems with integrated haptic feedback. Visualization technology occupies concentrated margin pools because camera head and light source replacement cycles generate recurring consumable revenue.
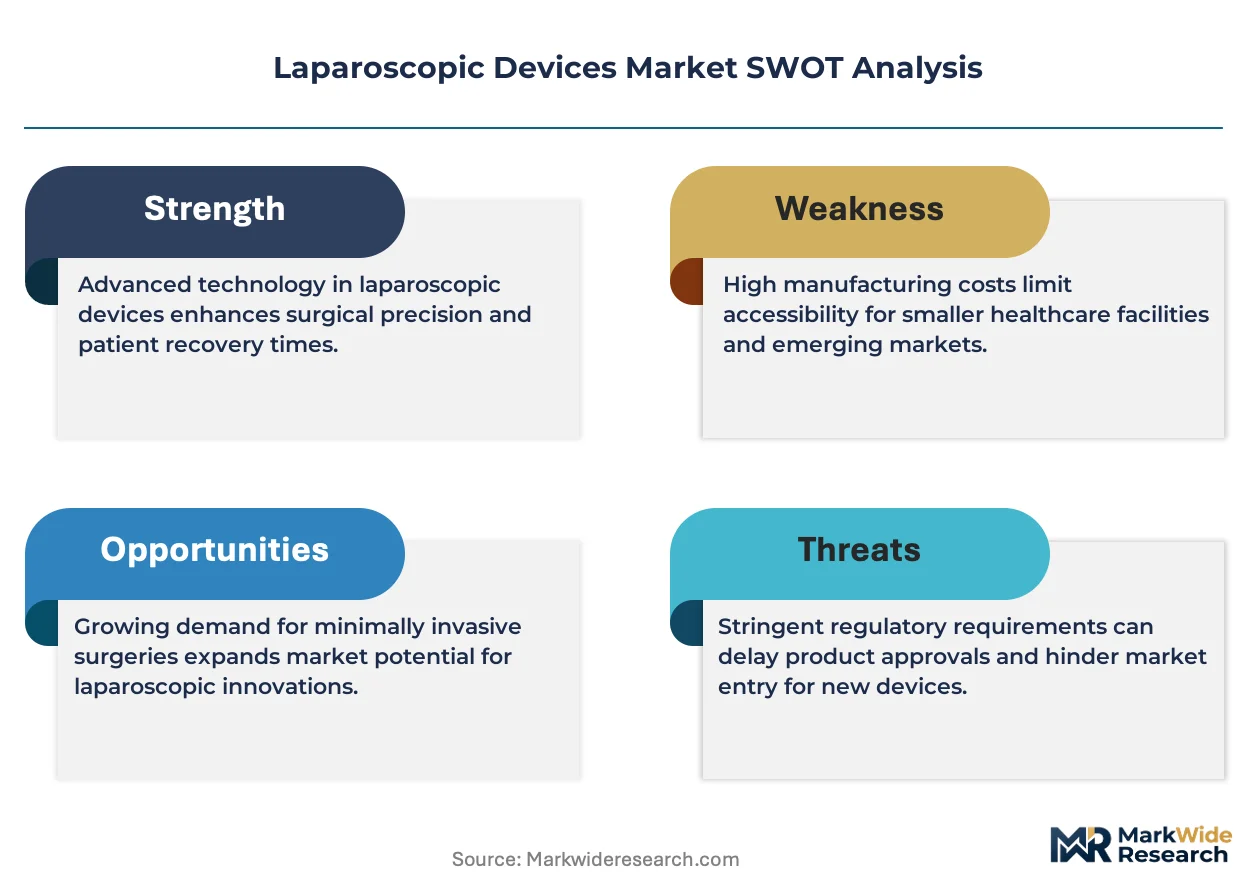
FDA 510(k) clearance and EU MDR technical documentation requirements are extending time-to-market for novel laparoscopic platforms and compressing margins for mid-tier manufacturers without dedicated regulatory affairs infrastructure. Japan's PMDA enforces stringent biocompatibility testing protocols that filter non-specialized entrants from its hospital supply chain. Stakeholders must monitor how CMS reimbursement coding for outpatient laparoscopic procedures interacts with ASC network expansion to determine capital allocation between robotic and conventional platform investments.
Market Dynamics
Robotic-assisted surgical platforms are compressing demand for conventional hand-held laparoscopic instruments as hospital capital committees prioritize systems with integrated haptic feedback and 3D visualization capabilities.
Growth Catalysts
- EU MDR recertification timelines:Compressed product launch cycles are accelerating innovation cadence among established manufacturers with dedicated regulatory infrastructure.
- Ambulatory surgical center networks:United States, Germany, and China are scaling outpatient facilities that favor minimally invasive procedure volumes and disposable instrument specifications.
- Advanced energy devices:Electrosurgical technology deployment across cholecystectomy and hernia repair protocols sustains universal adoption momentum in general surgery departments.
Market Restraints
- EU MDR technical documentation requirements:Extended time-to-market for novel platforms compresses margins for mid-tier manufacturers without regulatory affairs scale.
- German optics manufacturing concentration:Rigid endoscope production gravity in Tuttlingen creates supply vulnerability for specialized lens assemblies.
- Reprocessed instrument economics:Hospital procurement committees face tension between single-use specifications and cost-containment mandates for reusable alternatives.
Strategic Opportunities
- Japan PMDA pathway specialization:Stringent biocompatibility testing protocols filter non-specialized entrants, creating protected margin pools for compliant suppliers.
- Visualization technology convergence:Camera head and light source replacement cycles generate recurring consumable revenue streams independent of capital equipment sales.
- CMS reimbursement coding evolution:Outpatient laparoscopic procedure coverage expansion determines capital allocation between robotic and conventional platform investments.
Industry Challenges
- Integrated platform complexity:Powered stapling and visualization system interoperability demands specialized biomedical engineering talent scarce in regional health systems.
- FDA 510(k) clearance bottlenecks:Predicate device substantiation requirements extend development timelines for novel access systems and insufflation units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Devices Market |
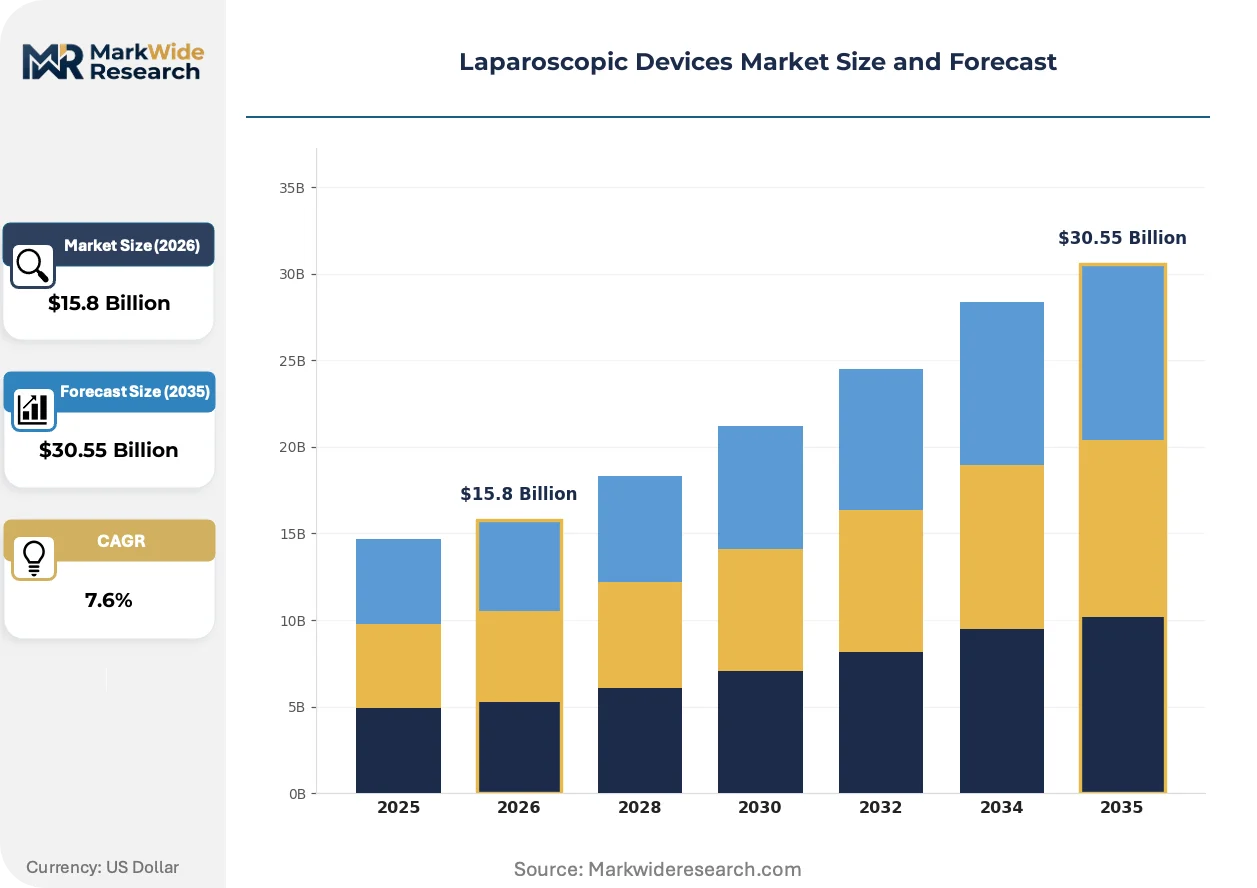
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $30.55 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insufflators, Trocar Systems, Scissors, Graspers End User: Hospitals, Surgical Centers, Clinics, Research Institutions Technology: Electrosurgical, Robotics, Visualization, Hand-held Application: Cholecystectomy, Appendectomy, Hernia Repair, Gynecological Surgery |
| Companies Covered | Johnson & Johnson, Medtronic, Olympus Corporation, Karl Storz SE & Co. KG, Stryker, Intuitive Surgical, CONMED Corporation, B. Braun Melsungen AG, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Devices Market Strategic Shifts & Innovations
Three intersecting forces are restructuring competitive positioning in laparoscopic devices: surgical robot penetration, regulatory documentation intensity, and procurement specification migration toward single-use consumables.
Single-use trocar access systems are supplanting reprocessed metal cannulas in tertiary hospital general surgery departments, with procurement committees mandating disposable specifications for infection control liability reduction. This shift compresses aftermarket servicing revenue for instrument reprocessors while expanding margin pools for manufacturers with sterilization-validated polymer supply chains.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for electrosurgical generators and insufflation units, forcing mid-tier manufacturers to outsource notified body interactions or exit the European market entirely. German and French hospital systems are responding by consolidating supplier lists toward vertically integrated platforms with dedicated regulatory affairs infrastructure.
Hospital supply chain committees are unbundling after-sales service contracts from capital equipment purchases, demanding à la carte maintenance pricing for camera heads and light sources. This behavioral shift is most visible in United States ambulatory surgical centers, where procurement autonomy from integrated delivery networks enables direct vendor negotiation and compressed switching cycles for visualization technology replacements.
Laparoscopic Devices Market Segmentation
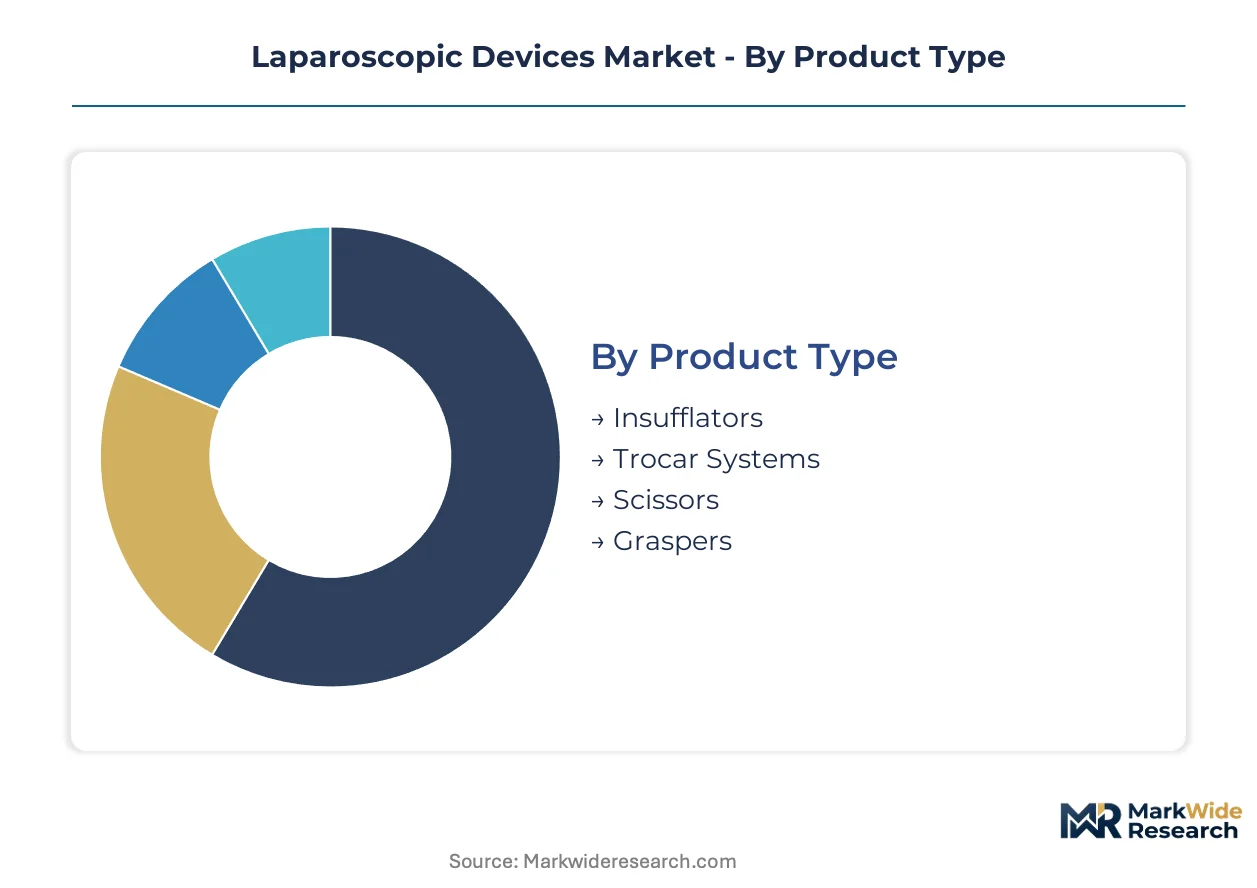
Laparoscopic device procurement channels diverge sharply by care setting and procedure complexity, with tertiary hospitals favoring integrated platform bundles while ambulatory surgical centers prioritize disposable instrument economics. Understanding segment-channel alignment enables manufacturers to calibrate pricing architecture and service attach rates across divergent customer workflows.
Product Type:
Channel distribution varies by product complexity: capital equipment flows through direct sales with service contracts, while consumables move via distribution partners with volume-based pricing tiers.
- Trocar Systems:Polymer-based disposable cannulas with integrated bladeless obturators and fixed or adjustable sleeve lengths. Demand concentrates in United States ambulatory surgical centers where infection control liability drives single-use specifications over reprocessed metal alternatives.
- Insufflators:Electronic gas delivery units regulating abdominal cavity pressure at 12-15 mmHg with integrated smoke evacuation. German hospital systems anchor procurement volume for advanced units with multi-pressure protocols and real-time flow sensing.
- Scissors:Monopolar and bipolar cutting instruments with ceramic or metal jaw configurations for tissue dissection.
- Graspers:Atraumatic and traumatic tip designs for organ manipulation across 5-12 mm port diameters.
By volume, Trocar Systems leads. By growth pace, Insufflators is climbing the fastest.
End User:
Customer type determines contract structure: integrated delivery networks negotiate enterprise pricing while independent facilities seek flexible procurement terms.
- Hospitals:Tertiary academic medical centers with dedicated minimally invasive surgery departments and capital equipment refresh cycles. United States general surgery departments are expanding robotic-assisted procedure volumes, compressing demand for conventional hand-held instrumentation.
- Surgical Centers:Outpatient facilities performing same-day laparoscopic procedures with constrained sterilization infrastructure. China's scaling ambulatory surgical center networks favor disposable instrument specifications and compressed vendor switching cycles.
- Clinics:Limited-procedure settings with basic diagnostic and minor interventional capabilities.
- Research Institutions:Preclinical and clinical trial sites evaluating novel access systems and energy platforms.
By installed base, Hospitals dominates. By expansion trajectory, Surgical Centers is gaining share fastest.
Technology:
Margin architecture separates capital-intensive platforms with recurring consumable revenue from commoditized hand-held alternatives.
- Electrosurgical:Monopolar and bipolar energy delivery systems with active electrode monitoring and tissue impedance feedback. Universal deployment across cholecystectomy and hernia repair protocols sustains revenue concentration in general surgery departments.
- Robotics:Computer-assisted platforms with articulated instrument arms and integrated haptic feedback. High-complexity gynecological surgery in United States health systems is displacing conventional laparoscopy as capital budgets shift toward integrated visualization systems.
- Visualization:Camera heads, light sources, and image processing units with HD or 4K resolution pathways.
- Hand-held:Conventional mechanical instruments without powered or energy-assisted functionality.
By revenue contribution, Electrosurgical leads. By capital commitment growth, Robotics is expanding most quickly.
Application:
Procedure volume and reimbursement coding determine platform investment priority across customer segments.
- Cholecystectomy:Gallbladder removal procedures representing the foundational laparoscopic technique with standardized instrument requirements. United States CMS reimbursement coding for outpatient settings drives volume concentration in ambulatory surgical centers.
- Hernia Repair:Inguinal and ventral defect closure with mesh placement using specialized trocar configurations. German hospital systems maintain high procedure volumes with preference for advanced energy devices reducing thermal spread risk.
- Appendectomy:Emergency and elective removal of the vermiform appendix.
- Gynecological Surgery:Hysterectomy, myomectomy, and endometriosis procedures with specialized instrumentation.
By procedure frequency, Cholecystectomy leads. By technology upgrade intensity, Hernia Repair is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optics manufacturing concentrates in southern Germany, while device assembly and regulatory approval pathways distribute across North American, European, and Asia-Pacific health systems. Hospital procurement committees in each geography apply divergent specifications for disposable versus reusable instrument portfolios.
United States
CMS reimbursement coding for outpatient laparoscopic procedures drives volume concentration in ambulatory surgical centers. FDA 510(k) clearance pathways favor predicate device substantiation for novel access systems. The Minneapolis medical device corridor anchors visualization technology development and powered stapling platform engineering.
Germany
Tertiary hospital general surgery departments maintain preference for advanced energy devices with multi-pressure insufflation protocols. EU MDR Article 10 technical documentation requirements filter mid-tier manufacturers from procurement lists. Tuttlingen in Baden-Württemberg hosts rigid endoscope optics manufacturing at scale for global supply.
China
Scaling ambulatory surgical center networks favor disposable instrument specifications and compressed vendor switching cycles. NMPA regulatory pathways for Class III medical devices extend registration timelines for imported platforms. The Yangtze River Delta cluster concentrates domestic device assembly and polymer supply chain integration.
Japan
PMDA biocompatibility testing protocols enforce stringent validation standards that protect compliant suppliers from price competition. METI industrial policy supports domestic manufacturing of surgical visualization components. The Kanto region around Tokyo concentrates hospital procurement decision-making for high-value capital equipment.
India
CDSCO medical device rules and quality management system certifications shape import dependency for advanced laparoscopic platforms. Government hospital procurement through centralized tendering favors cost-optimized instrument specifications. Maharashtra and Karnataka host emerging domestic assembly operations for disposable trocar systems.
Laparoscopic Devices Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated platform developers commanding premium pricing and specialized component fabricators competing on specification compliance. The vendor base separates into three strategic tiers: diversified health care conglomerates with full surgical portfolios, dedicated minimally invasive surgery specialists, and regional disposable instrument manufacturers. Dominant competitive moves include M&A to acquire regulatory approval infrastructure and strategic partnerships to secure polymer supply chains for single-use specifications.
Within the diversified health care tier, Johnson & Johnson and Medtronic exemplify platform-scale competitors with integrated visualization and energy device portfolios. Karl Storz SE & Co. KG occupies a specialist position anchored in German optics manufacturing heritage. These three entities represent divergent strategic postures: conglomerate breadth, integrated systems architecture, and component specialization.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker |
| Intuitive Surgical |
| CONMED Corporation |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with sterilization-validated polymer suppliers lock in supply access for disposable trocar manufacturers while anchoring price visibility against raw material volatility. These arrangements concentrate procurement power among vertically integrated platform developers with dedicated regulatory affairs infrastructure.
Pricing Analysis
EU MDR dictates the pricing tier structure across electrosurgical generators and insufflation units, separating premium-certified OEMs from mid-tier competitors facing conformity assessment delays. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification grade, and after-sales service bundling. Cost compression in the mid-tier is intensifying because outsourced notified body interactions erode margins. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while tertiary academic medical centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory buffers for specialized lens assemblies extend lead times beyond standard medical device procurement cycles, forcing hospital systems to pre-position replacement camera heads. Manufacturing gravity centers on Germany for rigid endoscope optics, China for polymer-based disposable instruments, and the United States for powered stapling platforms. Supply chains draw from optical glass, medical-grade polymers, and precision-machined metals as core inputs. Single-source vulnerability concentrates in Tuttlingen-based optics fabrication. Distribution runs through direct sales forces for capital equipment and distribution partners for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement committee consolidation across United States ambulatory surgical center networks is shifting buyer power toward volume aggregators capable of dictating disposable instrument specifications and compressed switching cycles.
For Market Incumbents: Shield margin pools in advanced energy devices by deepening backward integration into sterilization-validated polymer supply chains against emerging regional disposable manufacturers. Prioritize CE marking pathway investments to compress EU MDR recertification timelines before mid-tier competitors recover regulatory capacity. Channel control through direct hospital system partnerships remains the critical defensive lever. For New Entrants and Emerging Players: Anchor in China's scaling ambulatory surgical center networks where NMPA registration timelines for Class III devices filter established Western competitors and create protected white-space for domestic assembly operations. Target disposable trocar specifications with infection control liability positioning. A direct procurement model bypassing integrated delivery network intermediaries offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward specialist visualization component fabricators with captive optics manufacturing and recurring consumable revenue streams independent of capital equipment cycles. Long-term viability over the coming decade rests on regulatory approval infrastructure as a scarce, non-replicable asset. The signal to watch is CMS reimbursement coding evolution for outpatient robotic-assisted procedures, which will determine capital allocation velocity between platform types.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerates market access for manufacturers with dedicated regulatory affairs infrastructure against mid-tier competitors. |
| Hospital System Partnership | Locks in multi-year disposable instrument supply agreements with United States ambulatory surgical center networks. |
| Backward Integration into Polymer Supply | Captures margin pools in single-use trocar specifications while reducing infection control liability exposure. |
| Software Companion Development | Enables integrated visualization platforms with real-time flow sensing for multi-pressure insufflation protocols. |
| Reimbursement Strategy | Aligns robotic platform investments with CMS outpatient procedure coding expansion trajectories. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and minimally invasive surgery department heads and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up demand modeling across procedure volumes and top-down market sizing triangulated value estimates.
Variance decomposition across product type, end user, technology, application, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating ambulatory surgical center network expansion rates, robotic platform penetration curves, and single-use specification adoption patterns as industry-specific forecast inputs.
Material uncertainties — regulatory approval delays, reimbursement coding revisions, and supply chain disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about procedure volume growth and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Snoring Control Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Europe Otoscope Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Global Ureteral Stent Market