
 Healthcare Physician Staffing Market | 2026-2036
Healthcare Physician Staffing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Physician Staffing Market Foresight
Acute care hospitals is bifurcating from outpatient clinics as the dominant buyer archetype in physician staffing procurement. AMN Healthcare leverages its national locum tenens infrastructure to secure multi-year hospital contracts across state lines. CHG Healthcare anchors its competitive position through specialty-focused recruitment in anesthesiology and emergency medicine. Cross Country Healthcare competes on rapid-deployment capabilities, sustaining fill-rate advantages in rural and semi-urban markets.
Healthcare physician staffing encompasses the sourcing, credentialing, and placement of licensed medical doctors into clinical roles on temporary, permanent, or project-specific bases, with placement cycles typically ranging from 48 hours for emergency locum coverage to 180 days for executive search engagements. The primary commercial purpose is to bridge supply-demand gaps in clinical labor markets, ensuring continuous patient care during vacancies, seasonal surges, or permanent recruitment transitions. Locum tenens commands the fastest expansion within service type segmentation, driven by hospital cost-containment strategies that favor variable labor over fixed physician salaries. Permanent placement retains stronger margin profiles despite slower volume growth, as placement fees scale with specialist compensation tiers. Within specialty segmentation, psychiatry exhibits accelerating demand concentration as behavioral health integration mandates expand across hospital systems.
FDA oversight of physician credentialing standards intersects with CMS conditions of participation to shape staffing compliance requirements for Medicare-eligible facilities. The Joint Commission accreditation criteria further constrain vendor selection, privileging staffing agencies with documented quality assurance protocols and malpractice coverage verification systems. State medical boards impose varying licensure reciprocity rules that fragment market access and elevate compliance costs for multi-state operators. Stakeholders must monitor evolving scope-of-practice regulations and interstate licensure compacts to anticipate workforce mobility shifts and credentialing timeline compression.
Market Dynamics
The physician staffing market is experiencing acute pressure from CMS reimbursement rules that tie payment to documented staffing ratios, forcing facilities to abandon informal coverage arrangements in favor of credentialed vendor relationships.
Growth Catalysts
- Interstate Medical Licensure Compact:The compact is compressing credentialing timelines for multi-state operators, accelerating physician mobility across member jurisdictions.
- Behavioral health integration mandates:Hospital systems must embed psychiatric services into primary care workflows, generating specialty-specific demand that generalist recruiters cannot satisfy.
- Rural hospital closures:Service discontinuity in underserved counties is creating emergency locum dependencies that sustain vendor utilization rates.
Market Restraints
- Malpractice insurance concentration:Three national carriers dominate physician coverage, elevating premium costs that staffing agencies must absorb or pass through.
- State licensure fragmentation:Non-compact states maintain independent verification requirements that extend placement cycles and elevate compliance overhead.
- Permanent placement fee compression:Hospital cost-containment targets are capping contingency fees as a percentage of first-year compensation.
Strategic Opportunities
- Telemedicine credentialing infrastructure:Virtual care platforms require distinct licensing frameworks that specialized staffing vendors can operationalize faster than generalist competitors.
- APP-physician team staffing:Advanced practice provider integration creates bundled placement opportunities that capture higher contract values per engagement.
- Indian Health Service expansion:Federal facility growth in Arizona and New Mexico is concentrating demand for culturally competent placement services.
Industry Challenges
- Primary source verification bottlenecks:Medical school and training program response delays are extending credentialing timelines beyond client tolerance thresholds.
- EHR integration complexity:Staffing vendors must navigate hospital-specific electronic health record access protocols that vary by system vendor and deployment version.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Physician Staffing Market |
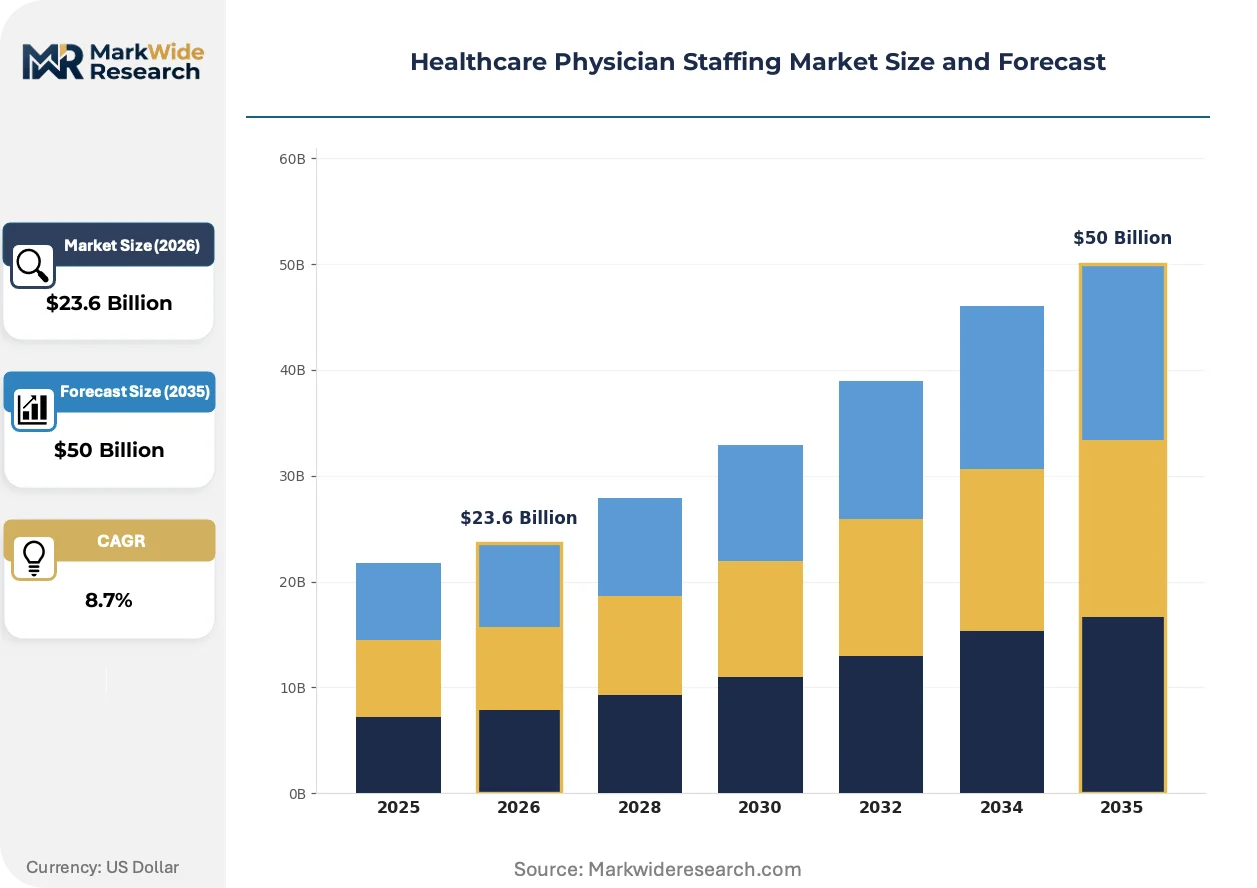
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $50 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temporary Staffing, Permanent Placement, Locum Tenens, Executive Search Specialty: Pediatrics, Cardiology, Surgery, Psychiatry End User: Hospitals, Clinics, Laboratories, Outpatient Facilities Recruitment Model: Direct Hire, Contingency Search, Retained Search, Niche Recruiting |
| Companies Covered | AMN Healthcare, CHG Healthcare, LocumTenens.com, Weatherby Healthcare, CompHealth, Cross Country Healthcare, Merritt Hawkins, Barton Associates, Medix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Physician Staffing Market Shifts & Advancements
Artificial intelligence is penetrating candidate matching and compliance monitoring functions, compressing placement cycles while elevating data security requirements for protected health information handling.
Credentialing automation platforms are bifurcating the vendor landscape between technology-enabled agencies and traditional recruitment shops. Large health systems are mandating API-enabled verification feeds that integrate directly with their privileging databases. The structural consequence is compressing margins for manual-process competitors while rewarding vendors with proprietary data infrastructure.
CMS conditions of participation are tightening supervision requirements for locum tenens physicians in critical access hospitals. The industrial consequence is elevating documentation burdens that only staffing firms with dedicated quality assurance staff can satisfy. Rural facilities in Texas and Arizona are responding by consolidating vendor relationships to reduce compliance fragmentation.
Subscription-based staffing contracts are displacing transactional locum arrangements in large hospital systems. Health systems in California and Florida are piloting annual retainer models that guarantee coverage pools. This pattern is most visible among multi-facility operators seeking budget predictability over per-diem flexibility.
Healthcare Physician Staffing Market Segmentation
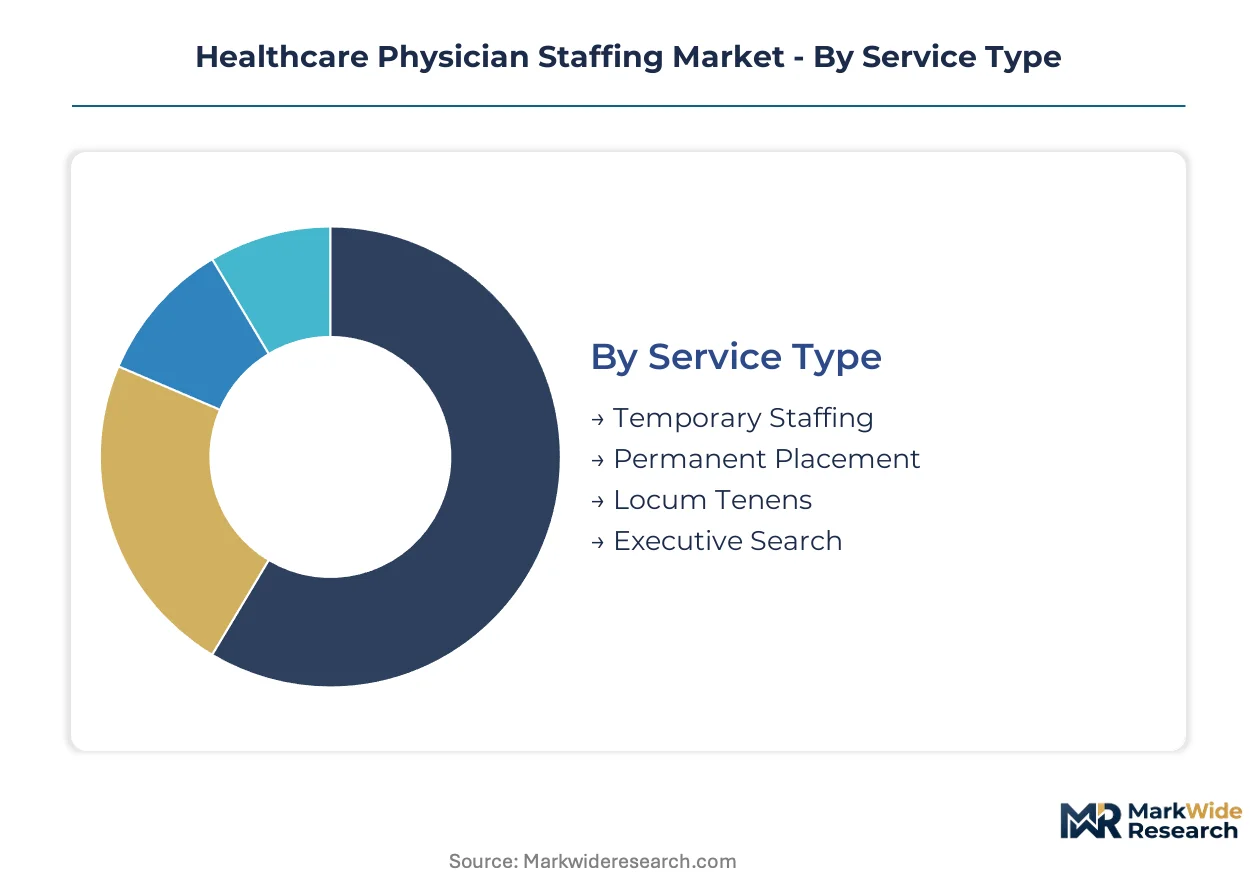
Segmentation in physician staffing reveals distinct margin profiles and compliance burdens across service delivery modes. Procurement patterns diverge sharply between acute care hospitals seeking rapid coverage and ambulatory networks optimizing permanent workforce ratios.
Service Type:
Locum tenens faces intensifying substitution pressure from telemedicine platforms and advanced practice provider expansion, while permanent placement resists displacement through specialist scarcity.
- Locum Tenens:Variable-cost physician coverage deployed for vacancy bridging, seasonal demand surges, and emergency backfill. Demand concentrates in rural Texas and Arizona hospitals where CMS conditions of participation mandate continuous specialty coverage. The Interstate Medical Licensure Compact compresses deployment timelines across member states.
- Permanent Placement:Contingency and retained search for full-time physician hiring with fees scaling to compensation tiers. Academic medical centers and integrated delivery networks in California and Florida anchor volume as they rebuild post-pandemic specialist rosters.
- Temporary Staffing:Project-based physician deployment for EMR implementation, clinical trial staffing, and service line launches.
- Executive Search:C-suite and departmental leadership recruitment with 120-180 day placement cycles.
Permanent placement anchors the volume base while locum tenens gains share at the steepest rate.
Specialty:
Psychiatry commands premium pricing due to behavioral health integration mandates, whereas general surgery faces fee compression from procedural volume shifts to outpatient settings.
- Psychiatry:Psychiatric physician sourcing for embedded primary care models, crisis intervention units, and telehealth platforms. Hospital systems in underserved states drive demand as CMS ties reimbursement to documented behavioral health capacity.
- Cardiology:Interventional and electrophysiology specialist placement for structural heart programs and catheterization laboratory expansion. Community hospitals in Arizona and New Mexico compete for limited interventional cardiologist supply.
- Surgery:General and subspecialty surgical staffing for OR block time coverage and trauma call panels.
- Pediatrics:Neonatal, pediatric critical care, and developmental specialist recruitment for children's hospitals and NICU networks.
Psychiatry expands most quickly as integration mandates proliferate, while surgery retains the largest absolute placement volume.
End User:
Cost tier stratification separates capital-rich hospital systems from margin-constrained outpatient operators with divergent procurement authority.
- Hospitals:Acute care, critical access, and specialty hospitals sourcing physicians across all service types. Multi-facility systems in Texas and California consolidate vendor relationships to reduce compliance fragmentation under Joint Commission criteria.
- Clinics:Community health centers and federally qualified health centers deploying locum coverage for continuity mandates. Rural clinic closures in Arizona counties generate emergency staffing dependencies.
- Outpatient Facilities:Ambulatory surgery centers and imaging centers seeking procedural specialists on limited schedules.
- Laboratories:Pathology and laboratory medicine staffing for diagnostic service expansion.
Hospitals dominate contract value while clinics drive transaction velocity through fragmented purchasing.
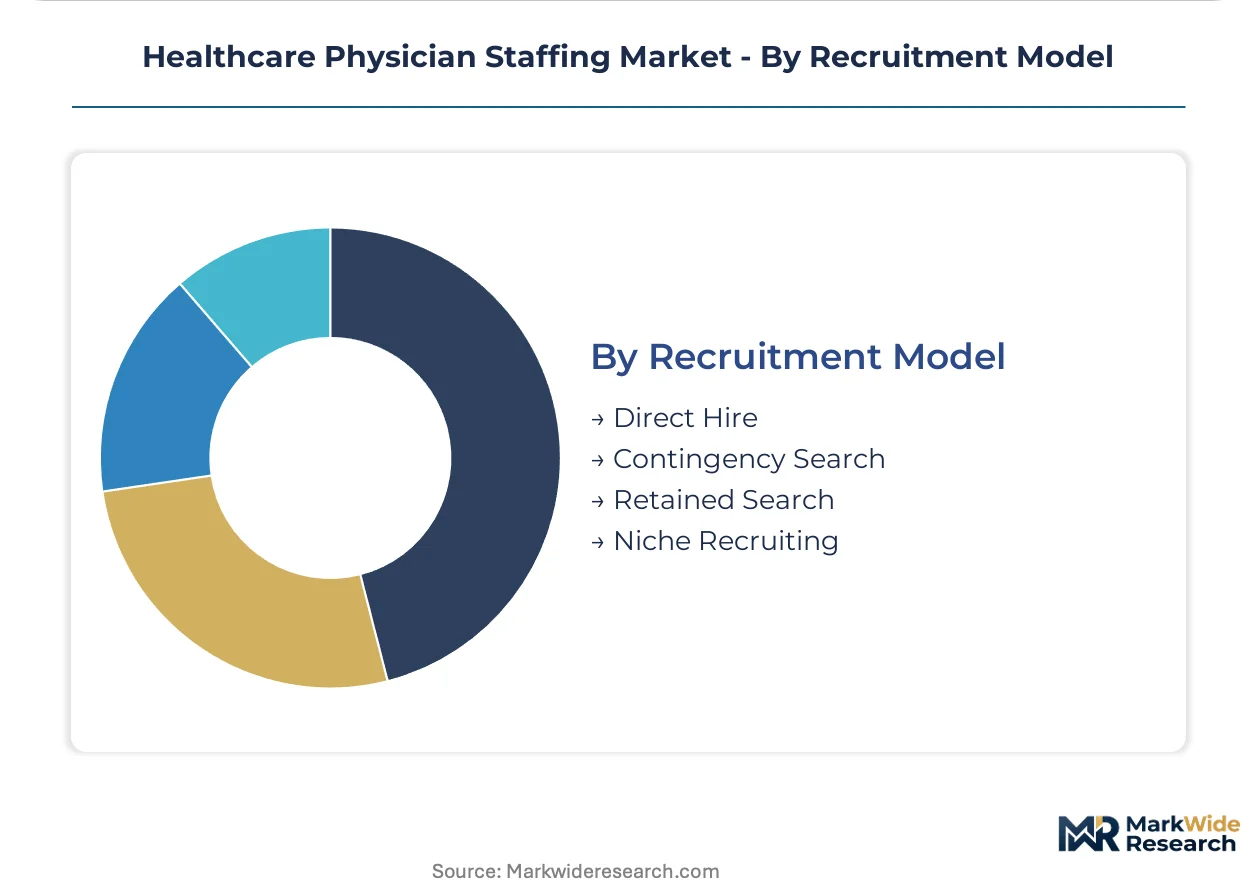
Recruitment Model:
Supply concentration among retained search boutiques creates pricing power in executive placement, contrasting with contingency fee compression in high-volume permanent search.
- Retained Search:Exclusive engagement with upfront fees for leadership and scarce specialty recruitment. Academic medical centers and large integrated systems prefer this model for departmental chair and division chief searches.
- Contingency Search:Success-fee placement for staff-level physicians with fees typically calculated as percentage of first-year compensation. Hospital cost-containment initiatives are capping these percentages.
- Direct Hire:In-house recruitment by health systems bypassing agency fees through employed physician recruiters.
- Niche Recruiting:Specialty-focused agencies concentrating on single disciplines like anesthesiology or emergency medicine with deep candidate networks.
Contingency search generates the highest transaction volume while retained search captures premium margin per engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute care hospitals concentrate procurement authority across the United States, Germany, and Japan, while ambulatory networks in Canada and Australia drive transaction velocity through fragmented purchasing patterns.
United States
Texas and Arizona hospitals deploy locum tenens at record rates to bridge physician shortages in underserved counties. CMS conditions of participation mandate continuous specialty coverage, forcing rural critical access hospitals toward credentialed vendor relationships. The Interstate Medical Licensure Compact compresses deployment timelines across member states, accelerating physician mobility into southwestern markets.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor permanent placement volume as they rebuild post-pandemic specialist rosters. The country's national healthcare regulator maintains strict credentialing reciprocity with EU member states, streamlining cross-border physician mobility. Berlin-Brandenburg health systems consolidate vendor relationships to reduce compliance fragmentation under Joint Commission-equivalent accreditation criteria.
Japan
Metropolitan Tokyo hospitals source emergency medicine and anesthesiology specialists through rapid-deployment staffing models. METI workforce policy encourages telemedicine credentialing infrastructure to address rural physician maldistribution. The Kansai region around Osaka exhibits accelerating demand concentration for psychiatric services as behavioral health integration mandates expand.
Canada
Ontario and Quebec community health centers expand reliance on temporary physician coverage to maintain service continuity amid rural hospital closures. Health Canada oversight intersects with provincial medical board licensure rules, fragmenting market access for multi-province operators. British Columbia health authorities pilot subscription-based staffing contracts to guarantee coverage pools.
Australia
New South Wales and Victoria ambulatory surgery centers seek procedural specialists on limited schedules, driving transaction velocity. The TGA maintains physician credentialing standards that shape staffing compliance requirements for Medicare-eligible facilities. Queensland rural clinics generate emergency staffing dependencies as service discontinuity in underserved regions sustains vendor utilization rates.
Healthcare Physician Staffing Market Competitive Landscape
Player mix skews toward national-scale locum tenens infrastructure operators and specialty-focused recruitment boutiques. The market structure concentrates around three tiers: large multi-service agencies with cross-state licensing capabilities, mid-size regional players with rapid-deployment advantages, and retained search boutiques serving academic medical centers. Consolidation through strategic acquisitions and technology licensing partnerships dominates competitive maneuvering as vendors seek credentialing automation capabilities.
Within the national infrastructure tier, AMN Healthcare and CHG Healthcare occupy positions exemplifying scale-driven service delivery. AMN Healthcare leverages cross-state locum tenens networks to secure multi-year hospital contracts, while CHG Healthcare anchors competitive positioning through specialty-focused recruitment in anesthesiology and emergency medicine. Cross Country Healthcare sits within the rapid-deployment segment, sustaining fill-rate advantages in rural and semi-urban markets through streamlined credentialing protocols.
| Leading Market Players |
|---|
| AMN Healthcare |
| CHG Healthcare |
| LocumTenens.com |
| Weatherby Healthcare |
| CompHealth |
| Cross Country Healthcare |
| Merritt Hawkins |
| Barton Associates |
| Medix |
| Others |
Supply & Pricing Matrix
Forty-five-day credentialing timelines for Interstate Medical Licensure Compact states concentrate placement velocity advantages with vendors holding automated verification infrastructure, compressing pricing premiums for rapid-deployment contracts while elevating cost burdens for manual-process competitors in non-compact jurisdictions.
Pricing Analysis
Technology-generation pricing gaps separate AI-enabled credentialing platforms from legacy manual processes and emerging blockchain-verification systems. Subscription-based annual retainers dominate large health system procurement, with price differentiation resting on automation depth and malpractice coverage bundling. Cost compression in contingency permanent placement intensifies as hospital cost-containment targets cap fees as percentages of first-year compensation. Community health centers exhibit highest price sensitivity; academic medical centers prioritize compliance assurance over rate minimization.
Supply Chain Analysis
The United States anchors physician labor supply through domestic medical education pipelines and visa-sponsored international graduates, while India and the Philippines feed registered nurse and advanced practice provider streams that enable APP-physician team staffing models. Raw material dependencies center on malpractice insurance capacity from three national carriers, credentialing software licenses, and primary source verification access to medical school registries. Single-source vulnerability concentrates in malpractice coverage where carrier consolidation elevates premium pass-through risks. Distribution runs through hospital procurement committees and GPO contracts that consolidate vendor relationships under Joint Commission-aligned quality protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthcare physician staffing market tracks a cyclical recovery pattern as rural hospital closures and CMS reimbursement tightening force facilities back toward credentialed vendor relationships after pandemic-era informal coverage experiments.
For Market Incumbents: Fortify credentialing automation infrastructure to defend against telemedicine platform substitution and pure-play technology entrants. Invest in Interstate Medical Licensure Compact licensing depth to compress deployment timelines below competitor reach. Prioritize malpractice coverage captive arrangements with the three dominant national carriers to insulate margin structures from premium volatility.
For New Entrants and Emerging Players: Differentiate on psychiatric specialty recruitment depth where behavioral health integration mandates outpace generalist recruiter capabilities. Target Indian Health Service expansion corridors in Arizona and New Mexico where federal facility growth concentrates demand for culturally competent placement services. Pursue API-enabled verification feed partnerships with large health system privileging databases as primary go-to-market channel.
For Investors and Strategic Acquirers: Carve-out targets emerge from hospital systems spinning off captive staffing units under margin pressure. Long-term viability favors vendors with proprietary credentialing data infrastructure over transaction-scale dependent competitors. Monitor Interstate Medical Licensure Compact expansion announcements as inflection signals for multi-state operator valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Credentialing Automation Platform Deployment | Compresses placement cycles below manual-process competitor tolerance thresholds under CMS timeline pressures. |
| Malpractice Coverage Captive Arrangement | Insulates margin structures from three-carrier market concentration elevating premium pass-through risks. |
| Interstate Medical Licensure Compact Expansion | Accelerates physician mobility into Texas and Arizona rural markets with documented staffing shortages. |
| Psychiatric Specialty Recruitment Deepening | Captures behavioral health integration mandate demand that generalist recruiters cannot satisfy. |
| Subscription-Based Staffing Contract Conversion | Replaces transactional locum arrangements with annual retainer models guaranteeing California and Florida coverage pools. |
Research Methodology
A spread of perspectives from hospital staffing directors, locum tenens physicians, GPO contracts managers, and medical licensing board administrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare data, hospital procurement databases, and Joint Commission accreditation records. Bottom-up placement volume estimates triangulated against top-down market sizing from national staffing agency disclosures and state medical board licensure statistics.
Segmentation dimensions modeled span service type, specialty concentration, end-user facility category, and recruitment model structure across the analysis window. CAGRs derived from historical placement volume trajectories adjusted for Interstate Medical Licensure Compact adoption curves and CMS condition of participation enforcement intensity. Forecast inputs incorporated rural hospital closure patterns, behavioral health integration mandate implementation timelines, and telemedicine credentialing framework evolution.
Material uncertainties — regulatory delays in interstate licensure reciprocity, malpractice carrier capacity constraints, and telemedicine platform substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about credentialing automation adoption rates and hospital vendor consolidation preferences. Recalibration cycles align with material shifts in CMS reimbursement rulemaking and Interstate Medical Licensure Compact membership expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
India Senior Living Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Acute Care Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Assisted Living Market